
 West Africa Biostimulants Market | 2026-2036
West Africa Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Biostimulants Market Intelligence
The capital-intensity divergence between microbial fermentation facilities and simple extraction operations is rotating competitive advantage toward players with in-house biological manufacturing. Koppert Biological Systems leverages its Dutch parent-company expertise in beneficial microorganisms to sustain premium positioning across Nigeria and Ghana. UPL Limited anchors its West Africa presence through extensive distributor networks that dominate smallholder access channels. FMC Corporation competes by extending its crop protection adjacency into biostimulant bundling with established agrochemical relationships.
West Africa biostimulants comprise organic and biological substances containing active compounds such as humic acids, seaweed polysaccharides, amino acid complexes, and viable microbial cultures that enhance nutrient uptake efficiency, abiotic stress tolerance, and crop quality parameters without direct fertilization. Their primary commercial purpose centers on restoring soil biological activity depleted by decades of intensive mineral fertilizer application across the region's smallholder-dominated farmland. Seaweed extracts currently occupy the largest product-type position due to established import channels from European processors, while microbial solutions represent the fastest-expanding category as local fermentation capabilities emerge. Liquid formulations lead the form dimension because of compatibility with existing sprayer infrastructure, though granules are gaining traction among cooperatives seeking storage stability in humid climates.
ECOWAS fertilizer regulation harmonization and Nigeria's national biosafety agency frameworks are reshaping product registration pathways and import documentation requirements for biological inputs. Ghana's national food and agriculture ministry standards for organic input certification create additional compliance layers that favor documented supply chains over informal traders. Stakeholders must monitor how rapidly national regulators adopt ECOWAS-wide maximum residue limits and microbial strain approval lists, as divergence between neighbor states would fragment market access and raise compliance costs for cross-border distributors.
Market Dynamics
ECOWAS fertilizer regulation harmonization is compressing registration timelines while simultaneously raising technical documentation barriers, forcing distributors to consolidate cross-border compliance functions or exit smaller national markets entirely.
Growth Catalysts
- ECOWAS Standards Harmonization:The regional bloc's unified fertilizer and input frameworks are eliminating redundant national registration processes, accelerating product entry for documented suppliers across Nigeria, Ghana, and Senegal.
- Seaweed Extract Formulations:Established import channels from European processors supply polysaccharide-based biostimulants to cocoa cooperatives in Nigeria's southwest and vegetable growers in Ghana's Central Region.
- Soil Biological Depletion:Decades of intensive mineral fertilizer application across smallholder-dominated farmland has created acute demand for microbial inoculants that restore rhizosphere activity and nutrient cycling capacity.
Market Restraints
- Import Dependency for Active Ingredients:Concentrated supply of refined seaweed extracts and characterized microbial strains originates from European fermentation facilities, exposing West African formulators to euro-denominated input cost volatility.
- Limited Cold Chain Infrastructure:Viable microbial cultures require temperature-controlled distribution from port to farm gate, a capability largely absent outside Nigeria's Lagos-Abuja corridor and Ghana's Accra-Kumasi axis.
- Substitution by Mineral Fertilizers:Subsidized urea and NPK blends distributed through government extension programs compete directly for smallholder wallet share despite inferior long-term soil health outcomes.
Strategic Opportunities
- Côte d'Ivoire Expansion:The world's largest cocoa producer maintains minimal biostimulant penetration relative to its West African neighbors, presenting first-mover positioning for suppliers establishing compliant distribution through Abidjan port facilities.
- Cooperative Procurement Consolidation:Farmer cooperatives in Ghana's vegetable-growing regions are aggregating demand into volume-based contracts, displacing fragmented individual purchases through agrodealer networks.
- Granular Formulation Development:Humid climate storage requirements favor stable solid formulations over liquids, rewarding technical investment in encapsulation and desiccation technologies compatible with existing cooperative warehousing.
Industry Challenges
- Microbial Strain Characterization:Ghana's national food and agriculture ministry organic input certification requires documented genomic identification and stability testing, capabilities scarce among local formulation facilities.
- Technical Extension Capacity:Effective microbial biostimulant deployment demands agronomic training on application timing, water quality compatibility, and tank-mix sequencing that exceeds current government extension service staffing levels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Biostimulants Market |
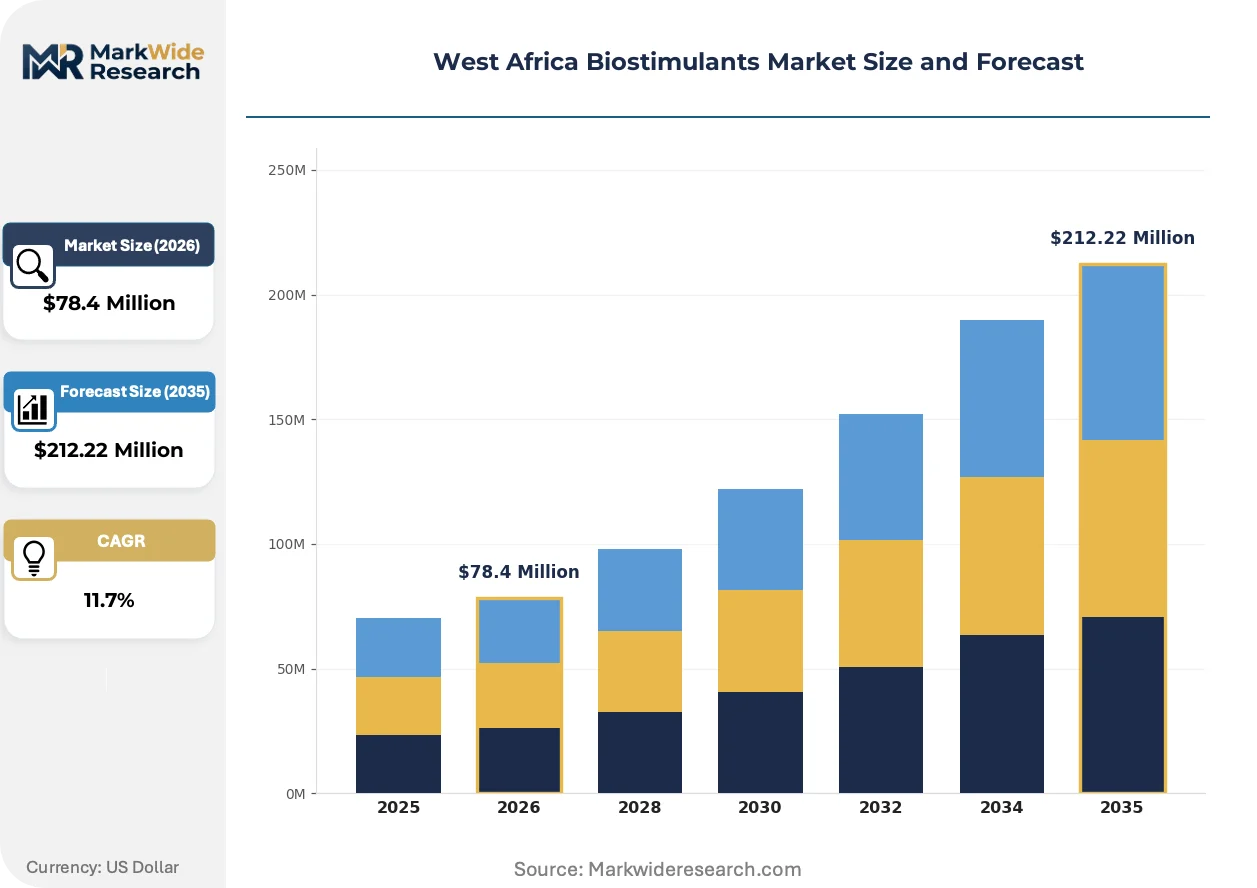
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $212.22 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Amino Acids, Microbial Solutions Application: Agricultural Crops, Horticultural Plants, Turf & Ornamentals, Soil Health Form: Granules, Liquids, Powders, Suspensions End User: Farmers, Distributors, Agricultural Cooperatives, Research Institutions |
| Companies Covered | Koppert Biological Systems, FMC Corporation, UPL Limited, Novozymes A/S, Agrinos AS, Syngenta AG, Italpollina S.p.A., Lallemand Inc., Valagro S.p.A., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Biostimulants Market Strategic Shifts & Innovations
Product development trajectories in West African biostimulants are diverging between premium microbial fermentation and cost-optimized extraction technologies, while regulatory alignment and cooperative purchasing reshape competitive access.
Microbial biostimulant technology is bifurcating the competitive landscape between capital-intensive fermentation specialists and extraction-based formulators. Specialty cocoa cooperatives in Nigeria's Ondo and Cross River states are adopting consortium inoculants containing Trichoderma and Bacillus species at accelerating rates. This technology compression is marginalizing simple humic acid blenders unable to demonstrate measurable rhizosphere colonization outcomes.
Nigeria's National Biosafety Management Agency frameworks are mandating contained-use permits for genetically modified microbial strains used in biostimulant formulations. Industrial consequence includes extended pre-market assessment timelines and mandatory environmental release monitoring protocols. Microbial solution providers targeting Nigeria's northern cereal belts face the most acute compliance burden, with several European suppliers redirecting registration investment toward Ghana's less stringent strain approval pathways.
Cooperative procurement consolidation is displacing individual smallholder purchases through fragmented agrodealer networks. Vegetable-growing cooperatives in Ghana's Ashanti Region now negotiate direct supply agreements with formulation companies, bypassing traditional distributor markups. This channel disintermediation is most visible in peri-urban tomato and pepper production clusters surrounding Kumasi, where documented supply chain requirements align with cooperative governance structures.
West Africa Biostimulants Market Segmentation
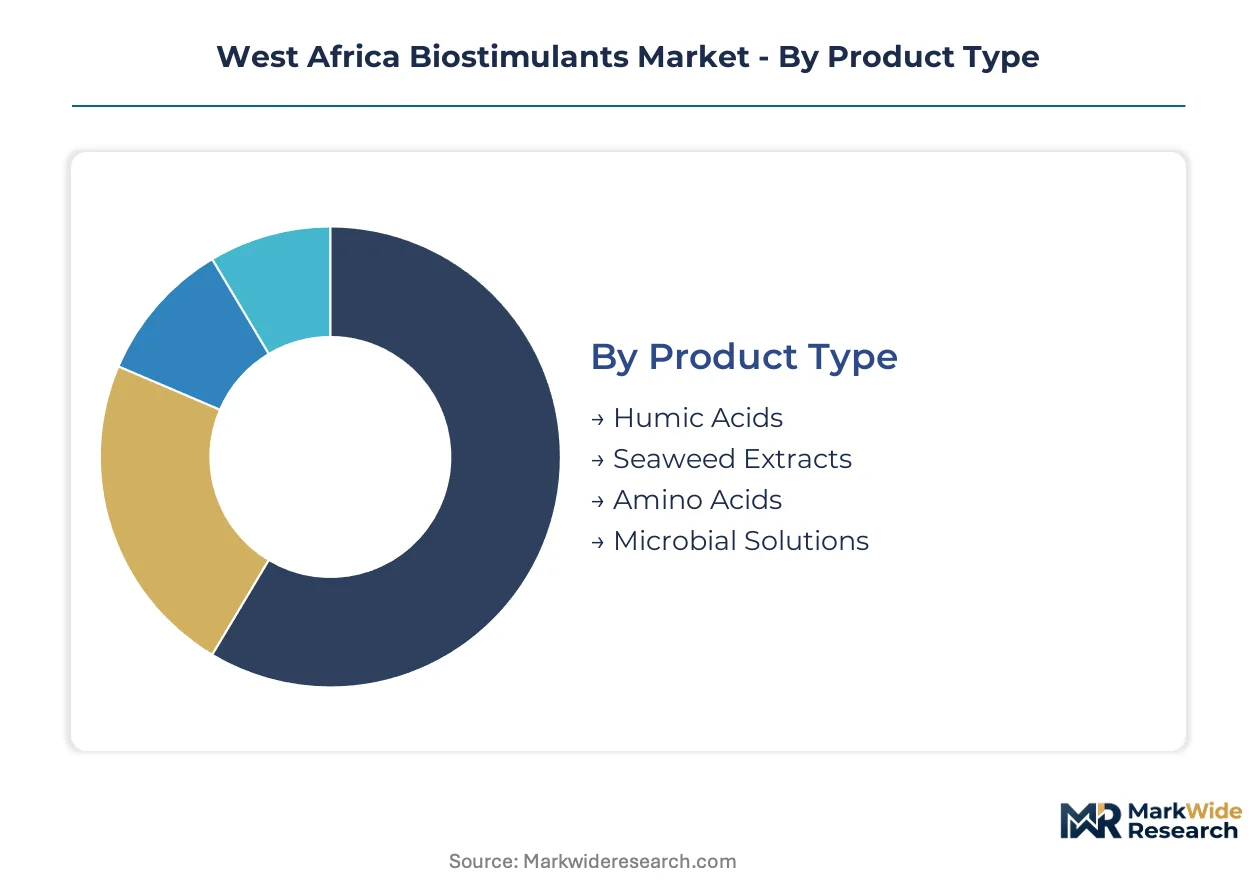
West African biostimulant purchasing decisions pivot on product stability under tropical storage conditions, crop-specific efficacy demonstrations, and alignment with cooperative procurement structures. Segmentation reveals where formulation investments translate into defendable market position versus commodity competition.
Product Type:
Humic acid blends face the most acute substitution pressure from subsidized mineral fertilizers, forcing differentiation through documented soil carbon restoration metrics.
- Seaweed Extracts:Polysaccharide-rich formulations derived from Ascophyllum nodosum and Laminaria species dominate cocoa cooperative procurement in Nigeria's Ondo State. European import channels supply refined extracts to processors in Lagos, though euro-denominated input costs create margin compression for local formulators.
- Microbial Solutions:Consortium inoculants containing Trichoderma harzianum and Bacillus subtilis strains command premium positioning through demonstrated rhizosphere colonization. Ghana's Ashanti Region vegetable cooperatives are accelerating uptake as domestic fermentation capabilities emerge around Kumasi industrial zones.
- Humic Acids:Leonardite-derived complexes compete primarily on price against NPK blends in Nigeria's northern cereal belts.
- Amino Acids:Hydrolyzed protein formulations from soy and fish processing waste serve niche stress-mitigation applications in peri-urban horticulture.
Seaweed extracts anchor the volume base while microbial solutions gain share at the steepest rate.
Application:
Application segmentation tracks directly to crop value intensity and extension service penetration depth across national agricultural systems.
- Agricultural Crops:Cocoa, maize, and rice production systems in Nigeria's southwest and Ghana's forest-savanna transition zones absorb the majority of biostimulant volume. ECOWAS fertilizer subsidy programs increasingly permit biostimulant co-procurement, redirecting smallholder expenditure from pure mineral dependency.
- Horticultural Plants:Tomato, pepper, and onion cultivation in Ghana's Central Region and Senegal's Niayes zone drives demand for precision-application liquid formulations. Export-oriented producers near Accra and Dakar pay compliance premiums for documented organic input chains.
- Soil Health:Degraded ferralsol restoration projects in Côte d'Ivoire's cocoa belt represent emerging demand from plantation rehabilitation programs.
- Turf & Ornamentals:Golf course maintenance and urban landscaping in Lagos and Abidjan constitute a thin premium segment served by specialized distributors.
Agricultural crops concentrate procurement scale while horticultural applications command the highest per-hectare expenditure rates.
Form:
Form selection reflects infrastructure constraints more than agronomic optimization, with storage stability overriding application precision in humid climates.
- Liquids:Ready-to-use formulations compatible with existing knapsack sprayer infrastructure dominate smallholder adoption in Nigeria. Compatibility with foliar feeding schedules and ease of tank-mixing with crop protection products sustain liquid preference despite shorter shelf life.
- Granules:Encapsulated microbial products and slow-release humic complexes are displacing liquids in Ghanaian cooperative warehouses where temperature control is absent. Solid form stability during monsoon storage conditions justifies formulation investment for suppliers targeting the cooperative channel.
- Powders:Soluble concentrates serve commercial farm operations with calibrated mixing equipment in Senegal's groundnut basin.
- Suspensions:High-concentration particulate formulations occupy a technical niche among precision agriculture adopters near Abuja.
Liquids retain the installed base advantage while granules expand most quickly through cooperative procurement consolidation.
End User:
End user segmentation captures the channel disintermediation underway as procurement authority shifts from fragmented agrodealer networks to consolidated buying entities.
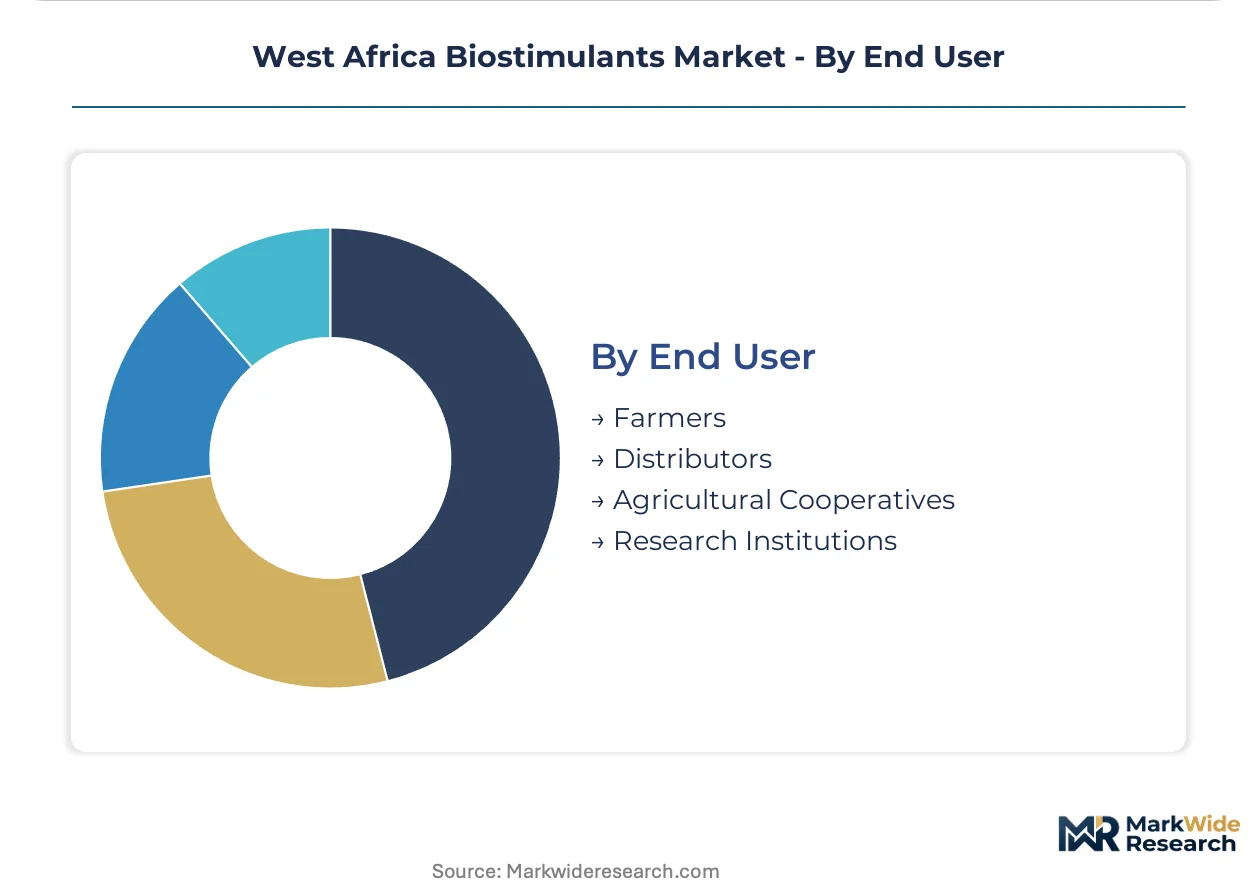
- Farmers:Individual smallholders under five hectares remain the numerically dominant purchasers, though their transaction scale limits supplier profitability. Nigerian cocoa farmers in Cross River State demonstrate highest willingness-to-pay for biostimulants when linked to certified premium cocoa offtake agreements.
- Agricultural Cooperatives:Aggregated procurement entities in Ghana's vegetable-growing regions now negotiate direct supply contracts, bypassing traditional distributor markups. Cooperative governance structures align with documented supply chain requirements that exclude informal traders.
- Distributors:Agrodealer networks retain relevance in remote areas beyond cooperative coverage, particularly in northern Nigeria and rural Senegal.
- Research Institutions:IITA and national agricultural research centers drive trial demand and strain validation protocols.
Farmers provide the volume foundation while agricultural cooperatives reshape pricing power through consolidated tender processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Ghana's cooperative procurement corridors while Nigerian smallholder fragmentation compresses margins. ECOWAS regulatory harmonization is redrawing competitive access maps across the region's five core agricultural economies.
Nigeria
Cocoa cooperatives in Ondo and Cross River states drive premium biostimulant uptake through certified offtake linkages. The National Biosafety Management Agency mandates contained-use permits for genetically modified microbial strains, extending registration timelines for northern cereal belt suppliers. Lagos-Abuja corridor distributors exploit the country's most developed cold chain infrastructure to deliver viable microbial cultures to peri-urban vegetable clusters.
Ghana
Vegetable-growing cooperatives in Ashanti and Central regions aggregate demand through volume-based tenders that displace agrodealer networks. The Ministry of Food and Agriculture's organic input certification requires documented genomic strain identification, favoring suppliers with European technical partnerships. Kumasi industrial zones host emerging domestic fermentation capabilities that reduce import dependency for Bacillus and Trichoderma formulations.
Côte d'Ivoire
Plantation rehabilitation programs in the cocoa belt generate nascent demand for soil biological restoration products. The national agricultural input regulator maintains minimal biostimulant-specific frameworks, creating first-mover advantages for compliant suppliers establishing Abidjan port distribution. Ferralsol degradation across western cocoa-growing districts exceeds the agronomic limits of mineral fertilizer-only regimes.
Senegal
Groundnut basin commercial operations adopt soluble powder concentrates compatible with calibrated mixing equipment. The national agricultural research institute validates microbial strain efficacy under Sahelian storage conditions, informing regional adaptation protocols. Niayes zone peri-urban horticulture near Dakar commands compliance premiums for documented organic input chains serving export markets.
Benin and Togo
Cotton cooperative procurement in northern growing districts absorbs basic humic acid formulations competing against subsidized NPK blends. National regulators align fertilizer documentation requirements with ECOWAS harmonization schedules, reducing cross-border compliance friction with Nigerian suppliers. Cotonou and Lomé port facilities serve as secondary import channels for European seaweed extract processors seeking market diversification.
West Africa Biostimulants Market Key Industry Players
Concentration sits with European biological specialists and Indian agrochemical conglomerates that control strain access and distribution reach. The market structure fragments between capital-intensive fermentation players and extraction-based formulators lacking microbial characterization capabilities. Two strategic archetypes dominate: integrated biological manufacturers with captive strain libraries, and crop protection bundlers leveraging existing agrochemical relationships. Competitive moves center on cooperative direct contracting and granular formulation investments for humid-climate storage stability.
Within the European specialist tier, Koppert Biological Systems and Valagro occupy positions anchored by technical strain expertise and established import channel relationships. UPL Limited exemplifies the distribution-scale archetype, while FMC Corporation represents crop protection adjacency strategies. Novozymes A/S and Lallemand Inc. sit within the microbial fermentation specialist category, their positioning tied to genomic identification capabilities required by Ghana's certification frameworks. These company groupings illustrate how regulatory technical barriers stratify competitive access across national markets.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| FMC Corporation |
| UPL Limited |
| Novozymes A/S |
| Agrinos AS |
| Syngenta AG |
| Italpollina S.p.A. |
| Lallemand Inc. |
| Valagro S.p.A. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day lead times for European-sourced seaweed extracts and characterized microbial strains concentrate pricing power with importers holding bonded warehouse inventory in Lagos and Accra. This inventory positioning allows distributors to buffer euro-denominated input volatility while cooperative buyers in Ghana's Ashanti Region negotiate volume-based contracts that compress margins for smaller agrodealer networks.
Pricing Analysis
Configured-to-order consortium inoculants command a 40-60% premium over standard humic acid blends across Nigeria's cocoa belt. Three-tier pricing structure across premium microbial, standard seaweed, and economy humic tiers reflects certification grade and genomic documentation requirements under Ghana's Ministry of Food and Agriculture organic input standards. Cost compression in the standard tier is intensifying as subsidized NPK blends compete for smallholder wallet share. Individual smallholders under five hectares exhibit highest price sensitivity, while export-oriented vegetable cooperatives near Accra pay compliance premiums for documented supply chains.
Supply Chain Analysis
Netherlands and Italy anchor refined seaweed extract supply through established fermentation and processing facilities serving West African formulators. Active ingredient supply draws from European strain libraries for Trichoderma and Bacillus species, while local encapsulation capabilities emerge around Kumasi industrial zones. Single-source vulnerability concentrates in euro-denominated microbial strain imports, exposing formulators to currency fluctuation. Distribution runs through cooperative procurement consolidation in Ghana and fragmented agrodealer networks in northern Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through Ghana's genomic identification requirements and Nigeria's biosafety permitting creates sustainable competitive advantage for documented suppliers.
For Market Incumbents: Secure strain library exclusivity through partnerships with European fermentation specialists before Ghana's certification requirements harden. Deepen cooperative direct contracting in Nigeria's Ondo State cocoa belt to displace distributor markups. Vertical integration into domestic encapsulation capabilities around Kumasi industrial zones defends margin position against import-dependent competitors facing euro volatility. For New Entrants and Emerging Players: Ghana's Ministry of Food and Agriculture organic input certification fast-track offers entry pathway for suppliers with documented European technical partnerships. Côte d'Ivoire's plantation rehabilitation programs present the most penetrable geography given minimal biostimulant-specific regulatory frameworks. Target Abidjan port distribution establishment with soil biological restoration products for degraded ferralsol zones before incumbent networks consolidate. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because national biosafety frameworks and organic certification requirements favor technical specialists over commodity blenders. Acquisition target archetype: European microbial fermentation specialists with Ghana-compliant genomic identification capabilities and existing Lagos distributor relationships. Watch ECOWAS-wide maximum residue limit adoption velocity as inflection indicator for cross-border market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Buildout | Kumasi industrial zones reduce import dependency for Bacillus and Trichoderma formulations. |
| Cooperative Direct Supply Agreements | Ashanti Region vegetable cooperatives displace traditional agrodealer markups through volume tenders. |
| Granular Formulation Development | Encapsulation technologies address humid climate storage requirements in cooperative warehouses. |
| ECOWAS Regulatory Compliance Investment | Harmonized fertilizer frameworks accelerate product entry across Nigeria, Ghana, and Senegal. |
| Côte d'Ivoire First-Mover Positioning | Abidjan port distribution captures plantation rehabilitation demand in underpenetrated cocoa belt. |
Research Approach
Operator-level perspectives from formulation plant managers, cooperative procurement officers, agrodealer network owners, and national agricultural extension directors anchored the qualitative base. Primary interviews combined with secondary validation from ECOWAS fertilizer harmonization documentation, Ghana's Ministry of Food and Agriculture certification standards, Nigeria's National Biosafety Management Agency permit records, and customs import data for seaweed extracts and microbial inoculants. Bottom-up cooperative procurement volume estimates triangulated against top-down regional agricultural input expenditure benchmarks.
Sensitivity analysis across product type, application crop, formulation form, and end-user channel dimensions informed the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectory modeling incorporating cooperative consolidation rates, regulatory adoption timelines, and strain import dependency ratios. Industry-specific inputs included cocoa certified offtake linkage penetration, peri-urban horticulture expansion patterns, and cold chain infrastructure development corridors.
Decision-makers should treat outputs as directional under assumptions of continued ECOWAS regulatory harmonization and cooperative procurement consolidation; material deviation in national biosafety permitting divergence or mineral fertilizer subsidy expansion would warrant model refresh. Recalibration cycles align with material shifts in strain approval pathways and cross-border distributor compliance costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Red Algae Market