
 Red Algae Market | 2026-2036
Red Algae Market Size, Share, and Industry Trends Forecast 2026-2036
Red Algae Market Analysis
Ingredient refining revenue is tilting toward high-purity phycoerythrin and specialized hydrocolloid fractions. Cargill Incorporated leverages its global procurement infrastructure to secure multi-origin red algae biomass. Algatechnologies Ltd. anchors its position through closed-culture astaxanthin production from Haematococcus strains. Cyanotech Corporation differentiates via Hawaiian open-pond cultivation systems that command premium positioning in nutraceutical channels.
Red algae comprise marine macroalgae of the phylum Rhodophyta, containing phycobiliprotein pigments and sulfated galactan polysaccharides such as carrageenan and agar with gel-forming functionality. These organisms serve as essential raw inputs for food stabilization, pharmaceutical encapsulation, and cosmetic active delivery systems. Carrageenan dominates volume flows into dairy alternative and processed meat applications where texture replication commands formulation priority. Nutraceuticals represents the fastest-expanding end-use channel as astaxanthin and porphyran extracts gain clinical traction for oxidative stress modulation. Powdered form factors lead industrial procurement due to shelf stability and dosing precision in batch manufacturing.
The FDA GRAS notification pathway governs carrageenan inclusion in US food matrices while EFSA evaluates novel algae protein safety under the EU Novel Food Regulation. China's SAMR enforces GB standards for edible seaweed contaminants that directly shape import acceptance thresholds for dried raw material. Stakeholders must monitor evolving marine harvest quotas and aquaculture certification schemes that will determine sustainable supply scalability without geographic expansion.
Market Dynamics
Carrageenan extraction capacity is consolidating around coastal aquaculture zones as food processors demand traceable supply chains for plant-based meat formulations. This geographic clustering is reshaping competitive positioning among ingredient refiners.
Growth Catalysts
- EU Novel Food Regulation:Streamlined approval pathways for algae-derived proteins are accelerating commercialization timelines for novel hydrocolloid fractions in European food matrices.
- Plant-based meat processors:Texture replication requirements in dairy alternatives and processed meat applications are pulling high-purity carrageenan volumes into formulation pipelines.
- China's coastal aquaculture expansion:Raw material supply security is improving through state-backed biomass cultivation programs in Fujian and Shandong provinces.
Market Restraints
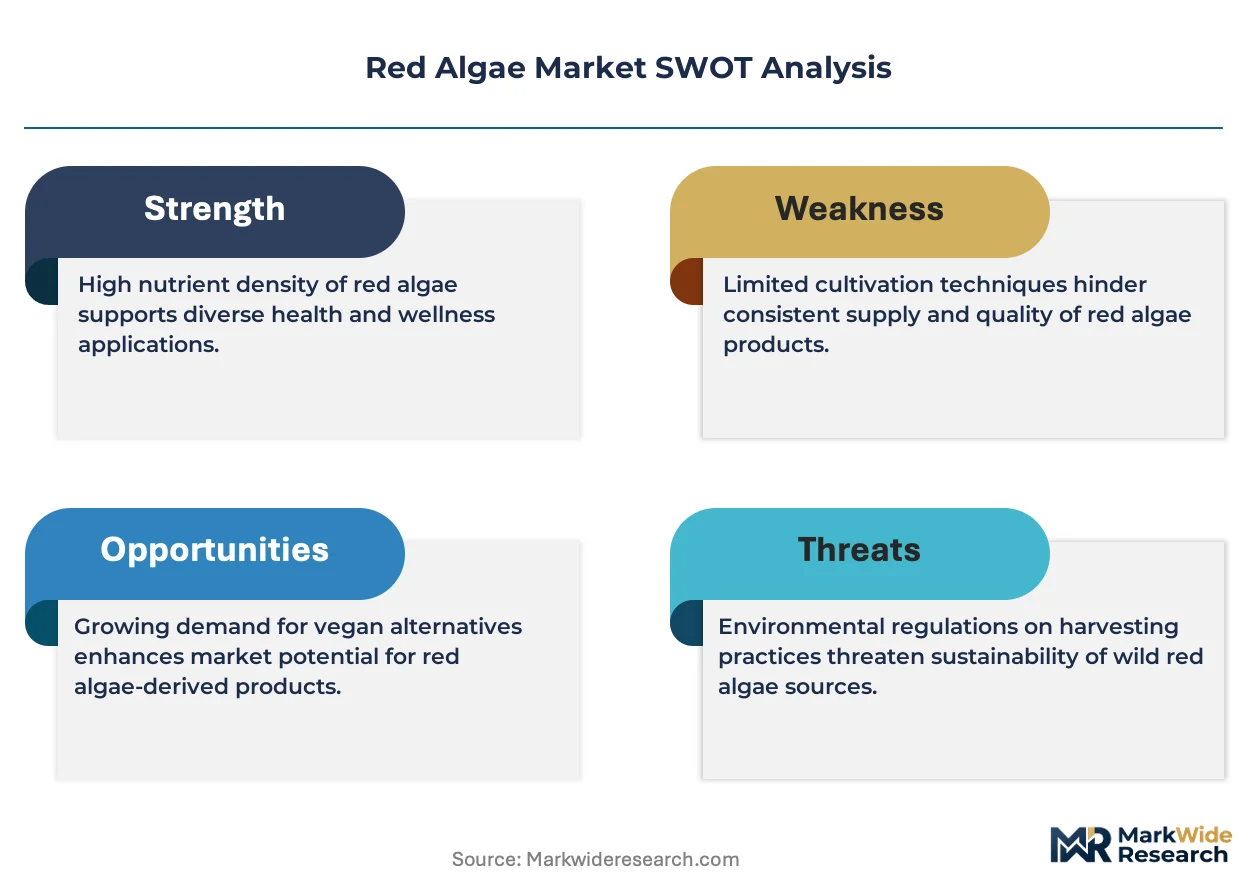
- Harvest quota volatility:Chilean and Indonesian wild seaweed harvest limits are constraining feedstock availability for non-cultivated carrageenan production.
- Cellulose gum substitution:Cost-sensitive food manufacturers in emerging markets are displacing carrageenan with cheaper stabilizers in low-margin applications.
- EFSA re-evaluation cycles:Periodic safety reviews of sulfated polysaccharides are creating regulatory uncertainty for long-term formulation commitments.
Strategic Opportunities
- Pharmaceutical encapsulation demand:Controlled-release drug delivery applications for porphyran extracts remain underdeveloped in North American and European markets.
- Closed-culture astaxanthin:Photobioreactor systems are enabling pharmaceutical-grade pigment production independent of seasonal harvest constraints.
- US FDA GRAS self-affirmation:Streamlined notification pathways for novel red algae extracts are lowering barriers to entry for specialized nutraceutical ingredients.
Industry Challenges
- Phycobiliprotein extraction expertise:Technical talent scarcity in high-purity chromatography separation is limiting scale-up for cosmetic-grade phycoerythrin production.
- Multi-jurisdiction certification:Divergent contaminant thresholds between China's SAMR GB standards and EU EFSA requirements are complicating unified quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Algae Market |
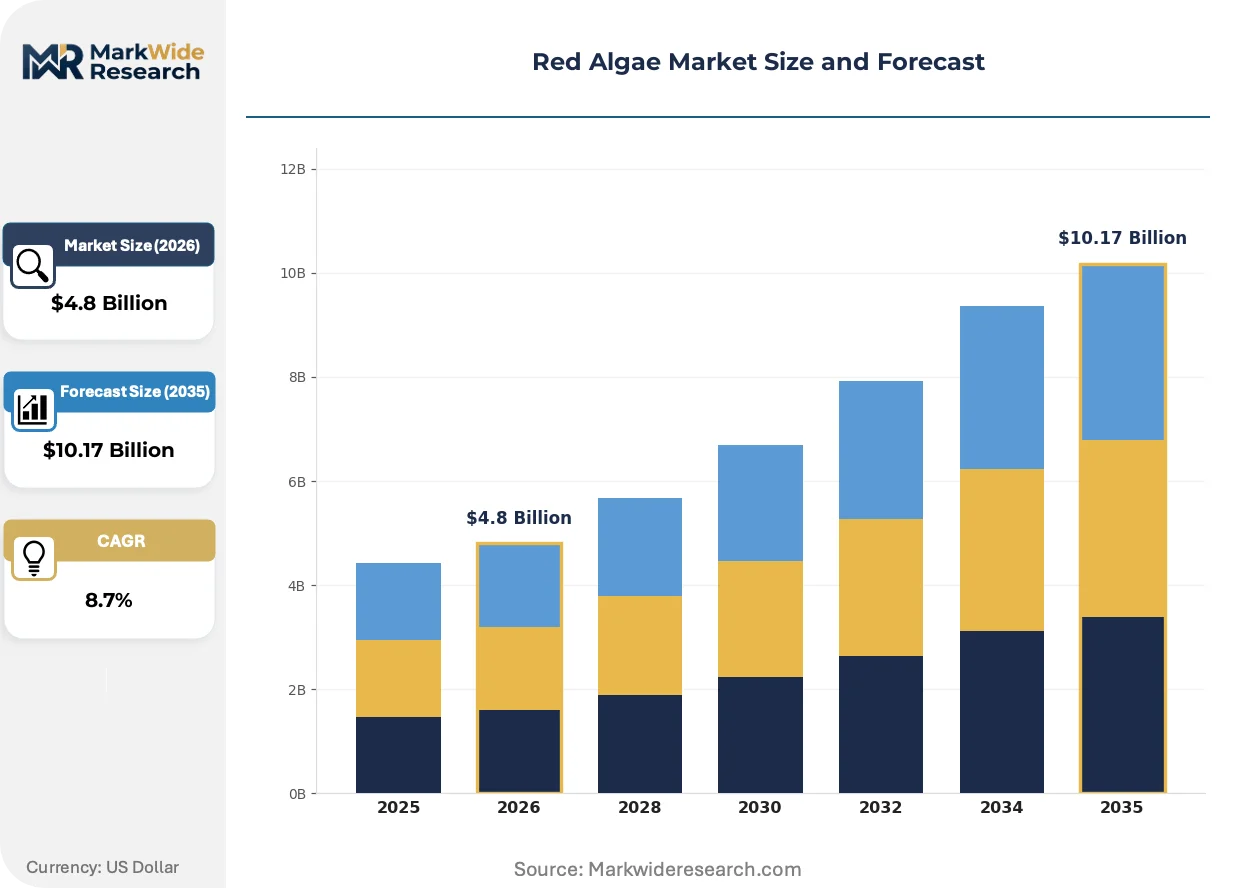
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrageenan, Agar, Nori, Dulse End Use: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Dried, Powdered, Liquid, Flakes Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Cargill Incorporated, Cyanotech Corporation, Alga Technologies, Algatechnologies Ltd., Bontac Bioengineering, ATCHA LLC., Algea, AlgaeCan Biotech Ltd., Algix, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Algae Market Emerging Trajectories
Bioprocess engineering advances are compressing extraction yields while sensor networks are enabling real-time cultivation monitoring. These technical currents are restructuring how value accumulates across the red algae value chain.
Photobioreactor automation is digitizing cultivation control systems for Haematococcus and Porphyra strains. Commercial algae operators in Israel and Iceland are deploying IoT-enabled monitoring at commercial scale. This infrastructure is digitizing batch consistency records for pharmaceutical-grade astaxanthin certification.
China's SAMR is tightening GB 19643 edible seaweed contaminant limits for heavy metals and iodine content. Import clearance delays are lengthening for Indonesian and Philippine dried biomass shipments. European ingredient importers are responding by qualifying alternative cultivation sources in Morocco and Portugal.
Long-term offtake contracting is displacing spot purchasing among major hydrocolloid buyers. Food manufacturers in Germany and the Netherlands are locking three-year supply agreements directly with aquaculture cooperatives. This pattern is most visible in carrageenan procurement for dairy alternative production.
Red Algae Market Segmentation
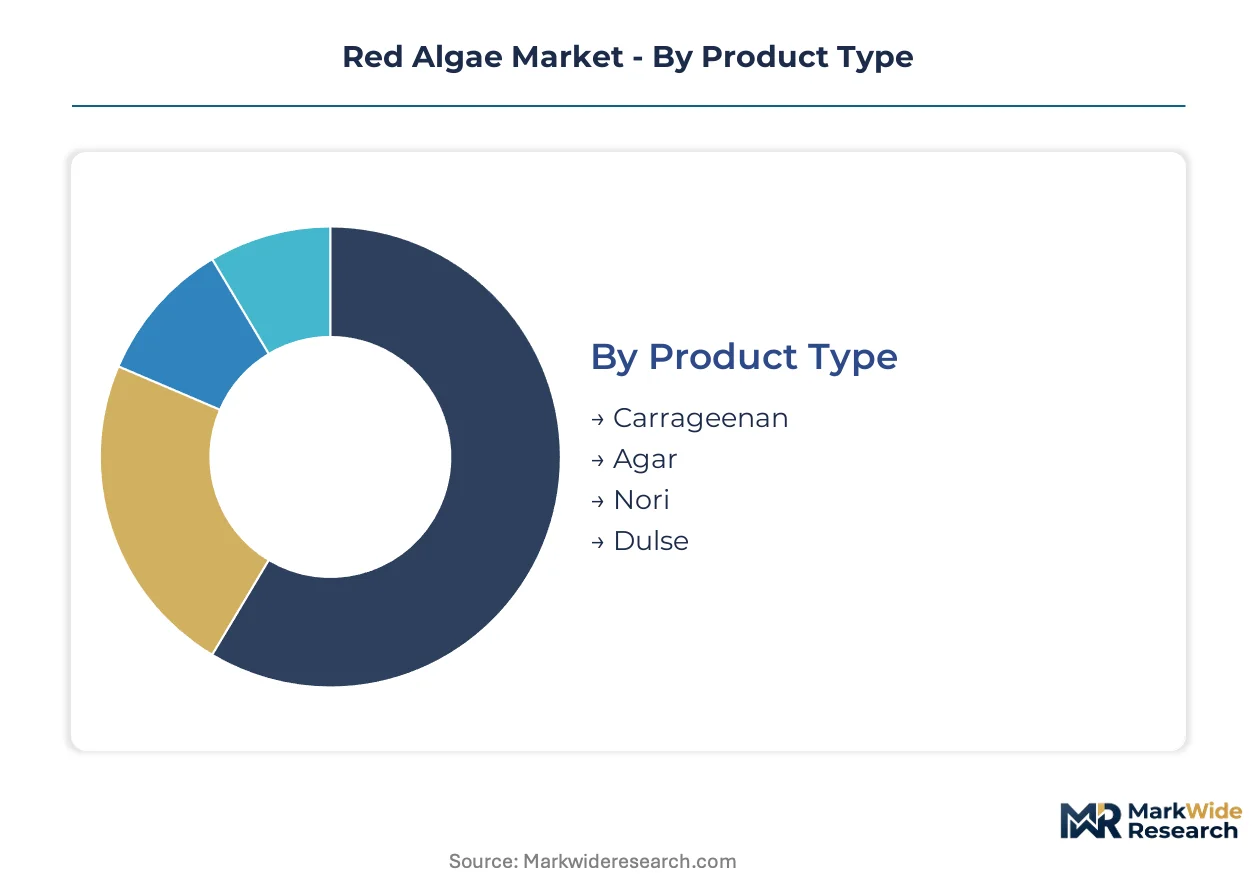
Segmentation in the red algae market reveals how functional properties dictate procurement patterns across divergent end-use specifications. Carrageenan gel strength requirements for plant-based meat formulations differ fundamentally from pharmaceutical-grade astaxanthin purity thresholds. Understanding these segment boundaries enables suppliers to align extraction investments with margin concentration points.
Product Type:
Each product type commands distinct formulation roles spanning food stabilization, pharmaceutical encapsulation, and cosmetic active delivery systems.
- Carrageenan:Sulfated galactan polysaccharides extracted primarily from Kappaphycus and Eucheuma species deliver thermoreversible gelation critical for dairy alternative texture replication. Food processors in Germany and the Netherlands are locking three-year supply agreements directly with aquaculture cooperatives to secure traceable volumes for plant-based meat pipelines.
- Agar:Complex polysaccharide blend of agarose and agaropectin provides superior clarity and lower gelling temperatures than carrageenan, making it indispensable for microbiological culture media and confectionery applications. Laboratory supply distributors in Japan and South Korea are expanding cold-chain logistics capacity to preserve agar gel strength during transit.
- Nori:Dried Porphyra sheets dominate sushi-grade consumption with protein content exceeding 30% dry weight, though harvest quota volatility in Japanese coastal waters is forcing processors toward Chinese cultivation sources.
- Dulse:Palmaria palmata flakes command premium positioning in Atlantic Canadian and Irish specialty food channels where umami intensity drives chef procurement decisions.
The dominant share belongs to Carrageenan, while Nutraceuticals-grade astaxanthin extraction from Haematococcus is closing the gap fastest.
End Use:
Application-specific purity requirements create tiered pricing structures that separate commodity food-grade from pharmaceutical-grade specifications.
- Food & Beverage:Hydrocolloid functionality for stabilization, thickening, and water-binding dominates volume flows, with EFSA Novel Food Regulation pathways accelerating algae protein approval timelines in European formulation pipelines.
- Pharmaceuticals:Controlled-release encapsulation applications for porphyran extracts remain underdeveloped in North American markets despite demonstrated bioadhesive properties for targeted drug delivery systems.
- Cosmetics:Phycoerythrin pigments and sulfated polysaccharide fractions serve active delivery functions in premium skincare, though technical talent scarcity in high-purity chromatography separation constrains cosmetic-grade production scale-up.
- Nutraceuticals:Astaxanthin and porphyran extracts gain clinical traction for oxidative stress modulation, with closed-culture photobioreactor systems enabling pharmaceutical-grade pigment production independent of seasonal harvest constraints.
Food & Beverage maintains volume leadership, yet Nutraceuticals exhibits the steepest expansion trajectory as clinical validation accumulates for algae-derived bioactives.
Form:
Physical state selection balances shelf stability against reconstitution speed and dosing precision in downstream manufacturing workflows.
- Powdered:Dominates industrial procurement due to extended shelf life, precise batch dosing, and reduced transportation costs relative to hydrated alternatives.
- Dried:Whole thallus preservation maintains structural integrity for rehydration applications in traditional Asian cuisine preparation.
- Liquid:Pre-hydrated extracts accelerate formulation speed for beverage manufacturers requiring immediate hydrocolloid dispersion without hydration lag time.
- Flakes:Visual texture appeal drives specialty food positioning, particularly in Atlantic European markets where dulse flakes garnish premium seafood products.
Powdered form factors command the largest procurement volumes, though Liquid extracts are gaining share fastest among beverage manufacturers optimizing production line efficiency.
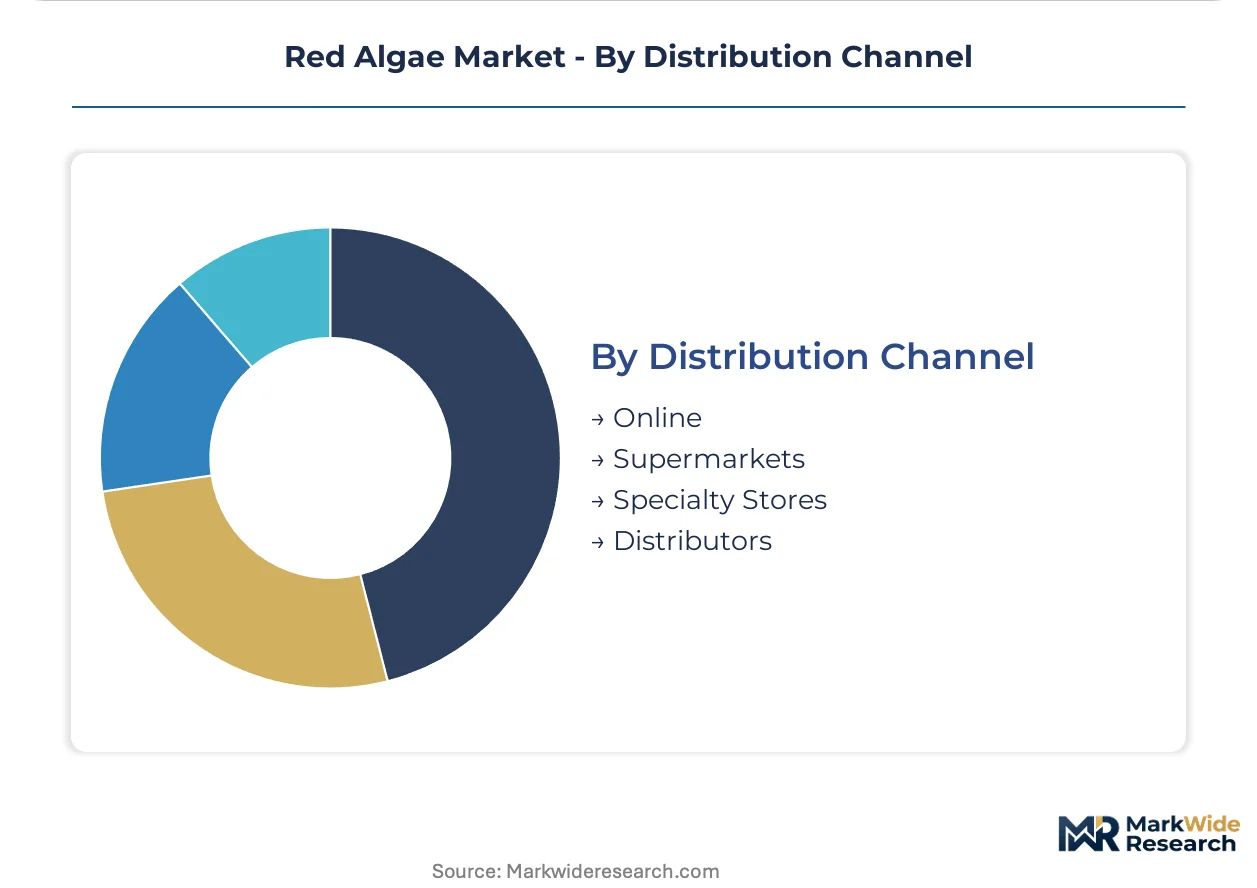
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and certification documentation needs across buyer segments.
- Distributors:Ingredient refiners leverage established relationships with food manufacturers to provide technical formulation support and regulatory documentation packages required for EFSA and FDA compliance.
- Specialty Stores:Premium positioning for culinary-grade nori and dulse serves consumer segments prioritizing provenance transparency and organic certification.
- Supermarkets:Mass-market packaged seaweed snacks and carrageenan-containing dairy alternatives reach volume consumers through retail shelf placement.
- Online:Direct-to-consumer channels expand access for small-batch nutraceutical buyers and specialty cosmetic formulators seeking specific phycobiliprotein specifications.
Distributors retain the dominant procurement channel position, while Online platforms are expanding most quickly among nutraceutical and cosmetic ingredient buyers requiring specialized specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement zones. German and Dutch food manufacturers absorb premium carrageenan costs for traceable supply chains, while Southeast Asian processors prioritize volume discounts over certification documentation.
China
Coastal aquaculture expansion in Fujian and Shandong provinces secures raw material flows for hydrocolloid refiners. SAMR's tightened GB 19643 contaminant standards for heavy metals and iodine are extending import clearance timelines for Indonesian biomass. Qingdao clustering supports integrated carrageenan extraction facilities serving domestic dairy alternative manufacturers.
Germany
Plant-based meat formulators in Hamburg and Bremen drive demand for high-purity carrageenan with documented supply chain provenance. EFSA's Novel Food Regulation pathways accelerate approval timelines for algae-derived proteins in European food matrices. The northern industrial corridor anchors long-term offtake contracting directly with aquaculture cooperatives.
United States
Nutraceutical channels in California and Oregon command pharmaceutical-grade astaxanthin specifications with batch consistency documentation. FDA GRAS self-affirmation pathways lower entry barriers for novel red algae extracts in functional ingredient applications. Hawaiian open-pond cultivation systems serve premium positioning in antioxidant supplement distribution.
Indonesia
Wild seaweed harvest quotas in Sulawesi and Kalimantan constrain feedstock availability for non-cultivated carrageenan production. Export clearance delays to China are lengthening under stricter SAMR import inspections. Makassar processing hubs face margin compression from cellulose gum substitution in cost-sensitive Asian food manufacturing.
Israel
Photobioreactor automation for Haematococcus strains enables pharmaceutical-grade astaxanthin production independent of seasonal constraints. Closed-culture systems in the Negev region digitize batch consistency records for certification requirements. Tel Aviv-area bioprocess engineering firms compress extraction yields through chromatography advances.
Red Algae Market Vendor Landscape
Capability concentration sits with specialized biotech operators; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: multinational hydrocolloid traders with global procurement infrastructure, regional aquaculture-integrated refiners, and closed-culture biotechnology specialists. Consolidation pressures favor long-term supply contracting over spot purchasing. Capacity expansion clusters in coastal cultivation zones while technology licensing accelerates photobioreactor deployment.
Within the multinational trading tier, Cargill Incorporated anchors global biomass sourcing networks across multiple origin points. Cyanotech Corporation exemplifies the geography-specific cultivation archetype through Hawaiian open-pond systems. Algatechnologies Ltd. represents the closed-culture biotechnology specialist segment with photobioreactor-controlled astaxanthin production.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Cyanotech Corporation |
| Alga Technologies |
| Algatechnologies Ltd. |
| Bontac Bioengineering |
| ATCHA LLC. |
| Algea |
| AlgaeCan Biotech Ltd. |
| Algix, LLC. |
| Others |
Supply Flow & Price Mechanics
Coastal aquaculture concentration in Fujian and Shandong provinces anchors upstream biomass availability, concentrating margin capture with hydrocolloid refiners who lock three-year offtake agreements directly with cultivation cooperatives. This geographic clustering transfers pricing power downstream to processors commanding traceable supply chains for plant-based meat formulations.
Pricing Analysis
Long-term offtake contracting drives lifetime value for ingredient refiners serving German and Dutch dairy alternative manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications separates premium astaxanthin extracts from commodity carrageenan volumes. Cost compression in standard-grade hydrocolloids intensifies as Indonesian processors displace carrageenan with cellulose gum in cost-sensitive Asian markets. Multinational food manufacturers exhibit lowest price sensitivity, prioritizing certification documentation over volume discounts.
Supply Chain Analysis
Extended payment terms from Chinese hydrocolloid refiners to Fujian aquaculture cooperatives stabilize working capital across seasonal cultivation cycles. Raw material flows draw from China, Indonesia, and the Philippines, with dried Kappaphycus and Eucheuma biomass feeding extraction facilities in Qingdao and Makassar. Single-source vulnerability concentrates in Indonesian wild harvest quotas, where SAMR import inspections now extend clearance timelines. Distribution runs through ingredient distributors providing technical formulation support and EFSA compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photobioreactor automation for Haematococcus strains represents a technological inflection compressing extraction yields while digitizing batch certification, positioning closed-culture operators to capture pharmaceutical-grade margin pools.
For Market Incumbents: Entrench supply security through backward integration into coastal aquaculture zones in Morocco and Portugal, diversifying beyond Indonesian wild harvest exposure. Lock multi-year offtake agreements with European plant-based meat processors before EFSA re-evaluation cycles create formulation uncertainty. Prioritize certification investment for GB 19643 compliance to preempt SAMR import clearance delays. For New Entrants and Emerging Players: Pharmaceutical encapsulation applications for porphyran extracts in North American markets represent the most penetrable entry point, with controlled-release drug delivery specifications underserved by incumbent hydrocolloid refiners. Closed-culture astaxanthin production using Israeli photobioreactor engineering offers a second white-space target. Pursue FDA GRAS self-affirmation pathways to lower regulatory barriers for novel extract commercialization. For Investors and Strategic Acquirers: Capital is best deployed toward closed-culture biotechnology specialists with photobioreactor-controlled production systems, as these assets decouple from seasonal harvest constraints and command premium positioning in nutraceutical channels. Monitor EFSA safety review outcomes for sulfated polysaccharides as the critical inflection signal for long-term formulation commitment durability. Macroeconomic, regulatory, or technological deviation would prompt revision.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Aquaculture | Qingdao and Negev operators secure biomass supply independent of Indonesian wild harvest quota volatility. |
| Photobioreactor Automation Deployment | Israeli engineering firms digitize batch consistency records for FDA pharmaceutical-grade astaxanthin certification. |
| Long-term Supply Agreement Lock-in | German and Dutch food manufacturers secure traceable carrageenan volumes for plant-based meat pipelines. |
| Regulatory Certification Investment | EFSA Novel Food Regulation compliance accelerates algae protein approval timelines in European formulation matrices. |
| Geographic Sourcing Diversification | Morocco and Portugal cultivation sources reduce SAMR import clearance exposure from Indonesian biomass. |
Methodological Framework
Initial hypotheses were tested against primary input from hydrocolloid refinery operations managers, aquaculture cooperative directors, food formulation technologists at plant-based meat processors, and pharmaceutical encapsulation specialists, then refined against secondary validation from FDA GRAS notification filings, EFSA Novel Food Regulation submission databases, SAMR GB standard revisions, and customs trade flow records for dried seaweed biomass. Bottom-up procurement volume estimates and top-down consumption pattern analysis were triangulated to anchor market sizing.
Demand-supply-balance framing structured the analytical framework across the projection horizon, modeling segmentation dimensions spanning product type, end-use application, physical form factor, and distribution channel alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and forward-looking capacity expansion announcements. Forecast inputs incorporated photobioreactor yield compression rates and EFSA re-evaluation cycle timing assumptions.
Practitioners should monitor harvest quota adjustments in Indonesian coastal waters, SAMR contaminant threshold revisions, and cellulose gum substitution rates in Asian food manufacturing for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
India Agricultural Biologicals Market