
 Biofibre Market | 2026-2036
Biofibre Market Size, Share, and Industry Trends Forecast 2026-2036
Biofibre Market Analytics
Modular fibre bundling is decoupling raw material supply from finished textile contracts, letting buyers swap fibre grades without requalifying entire supply chains. Lenzing AG anchors European viscose and lyocell output through integrated pulp-to-fibre mills in Austria and Czechia. BASF competes in biopolymer intermediates, leveraging its Ludwigshafen complex to sustain captive adipic acid routes for polyamide 6.10 fibres. DuPont differentiates in high-performance bio-based aramids, occupying a narrow segment where thermal resistance commands premium positioning.
Biofibre denotes fibres derived wholly or partly from renewable biological sources, including cellulose regenerated from wood pulp, polylactic acid synthesized from corn starch, and protein-based fibres with tenacities ranging from 15 to 65 cN/tex depending on draw ratio and moisture content. These materials serve industrial applications requiring controlled biodegradability, reduced fossil dependency, or specific surface chemistry for composite adhesion. Natural fibres lead product type volume due to established cotton and jute cultivation infrastructure, while biodegradable fibres capture the fastest expansion as packaging and agricultural film regulations tighten across multiple jurisdictions. In application terms, automotive composites concentrate margin pools because OEMs pay certification premiums for crash-tested biocomposite door panels and seat structures.
The EU ECHA enforces REACH registration for novel bio-based monomers, creating a compliance moat that favours incumbents with dedicated regulatory affairs teams. The USDA BioPreferred programme and associated federal procurement mandates shape North American demand by specifying minimum biobased content thresholds for textile and composite products sold to government buyers. Japan's METI promotes bioplastic and biofibre commercialization through its Green Innovation Fund, directing capital toward domestic spinning technology upgrades. Stakeholders must monitor how divergent biodegradability certification standards between jurisdictions fragment export eligibility and force parallel product line investments.
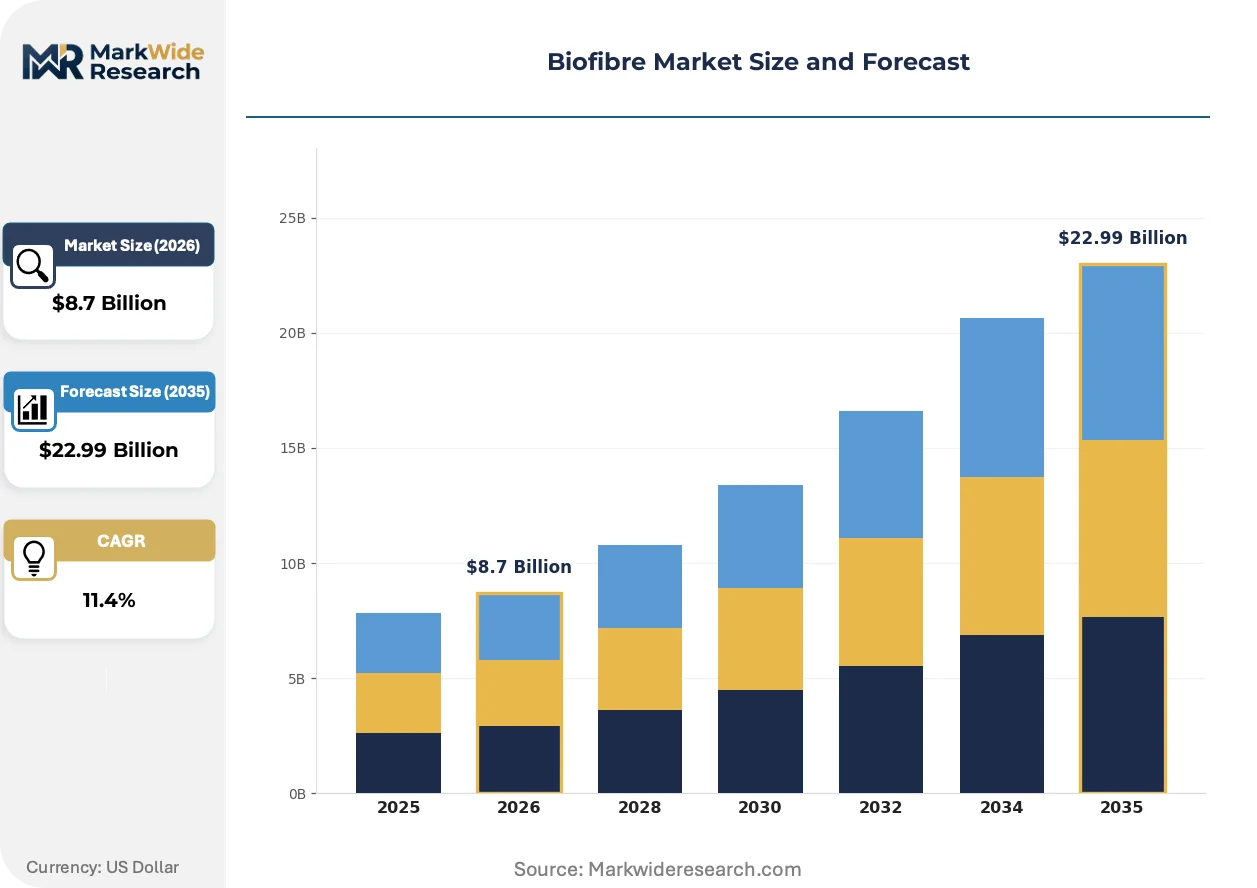
Market Dynamics
The EU Green Deal and CSRD reporting obligations are forcing automotive OEMs to requalify their entire material base, creating immediate procurement pressure for certified biofibre supply chains that can demonstrate lifecycle carbon reductions.
Growth Catalysts
- EU CSRD Mandates:Corporate Sustainability Reporting Directive disclosure rules require European manufacturers to document Scope 3 emissions from raw material sourcing, accelerating biofibre substitution for petroleum-based textiles in interior automotive applications.
- Automotive Lightweighting:Crash-tested biofibre composites for door panels and seat structures enable OEMs to meet fleet CO2 reduction targets while maintaining safety certification standards.
- Modular Fibre Bundling:Standardized raw material contracts allow buyers to swap between viscose, lyocell, and polylactic acid grades without triggering full supply chain requalification, reducing switching friction.
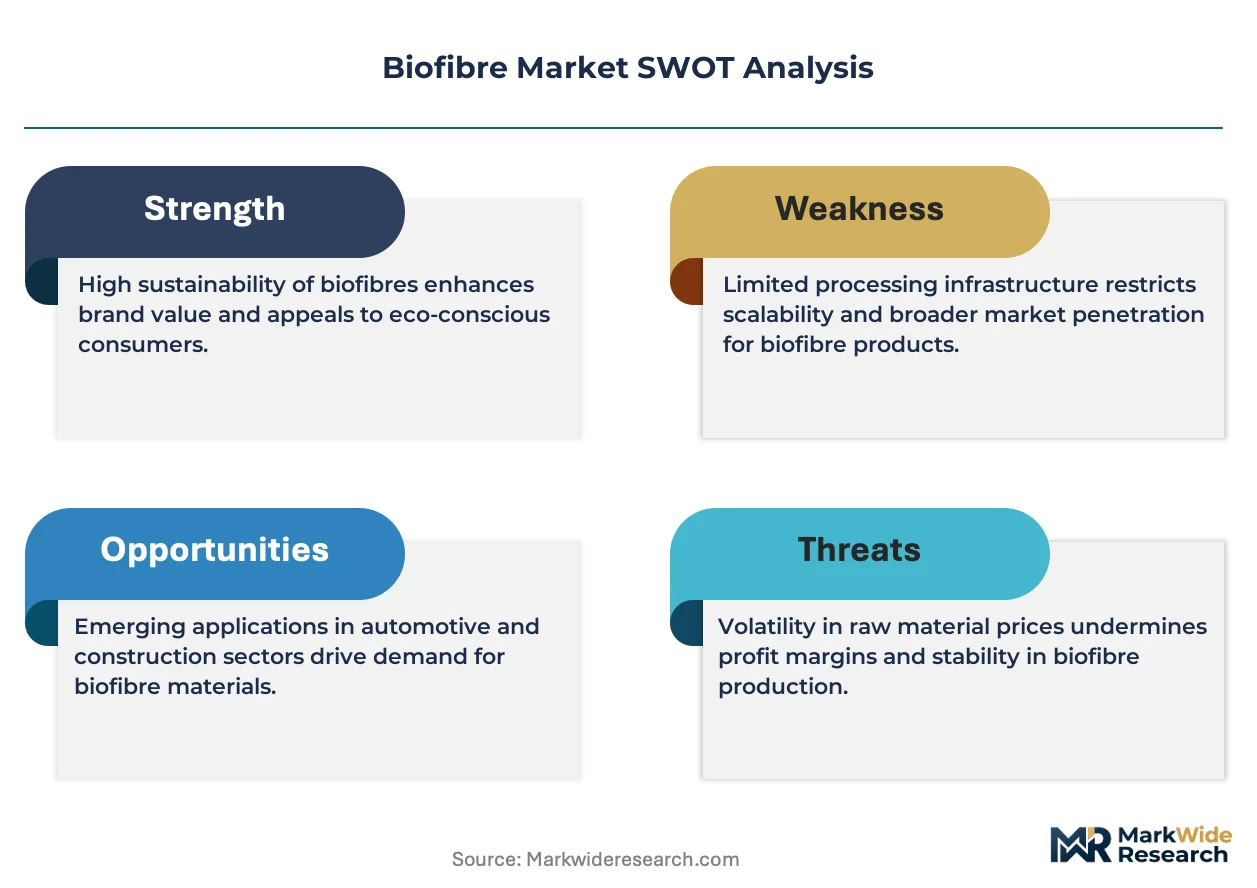
Market Restraints
- Input Cost Volatility:Wood pulp prices fluctuate with Nordic forestry harvest cycles and energy costs at Austrian and Czech integrated mills, compressing margin predictability for regenerated cellulose producers.
- REACH Registration Barriers:EU ECHA requirements for novel bio-based monomers create multi-year compliance timelines that favor incumbents with dedicated regulatory affairs teams and captive toxicology data.
- Performance Substitution:Glass fibre and carbon fibre retain dominance in structural automotive applications where thermal resistance above 200°C or specific tensile modulus thresholds are mandatory.
Strategic Opportunities
- Underpenetrated Agricultural Films:Biodegradable mulching and greenhouse films face tightening disposal regulations in Italy and Spain, creating pull for polylactic acid and starch-based fibres that decompose in soil microbiomes.
- USDA BioPreferred Tailwinds:Federal procurement mandates specifying minimum biobased content thresholds for textile and composite products open dedicated demand channels for suppliers achieving third-party certification.
- Lyocell-Polyamide Hybrid Convergence:Blending closed-loop solvent-spun cellulose with bio-based polyamide 6.10 intermediates enables moisture management and durability in performance apparel previously served by petroleum synthetics.
Industry Challenges
- Biodegradability Certification Fragmentation:Divergent industrial composting standards between EU EN 13432, US ASTM D6400, and Japanese GreenPla force parallel product line investments and limit cross-border SKU consolidation.
- Spinning Technology Retrofit Capex:Converting legacy viscose lines to lyocell N-Methylmorpholine N-oxide solvent recovery systems requires capital deployment at integrated pulp-to-fibre facilities with multi-year payback horizons.
- Composite Interface Chemistry Expertise:Automotive tier suppliers face acute shortages of polymer scientists capable of engineering fibre-matrix adhesion for biofibre-reinforced polypropylene and epoxy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofibre Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fibres, Synthetic Fibres, Biodegradable Fibres, Composite Fibres Application: Textiles, Composites, Automotive, Medical Devices End User: Aerospace, Automotive Manufacturers, Healthcare Providers, Textile Industry Technology: Fiber Extraction, Spinning Technology, Biopolymer Processing, Biocomposites |
| Companies Covered | NatureWorks LLC, DuPont, BASF, Lenzing AG, Novamont, Cargill, Braskem, ADM, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofibre Market Evolving Landscape
Modular production architectures and regulatory disclosure mandates are rewiring how biofibre supply chains contract, qualify, and deliver material performance guarantees to industrial buyers.
Closed-loop lyocell solvent recovery is decentralizing geographic production constraints that previously concentrated regenerated cellulose output around Austrian and Czech integrated mills. Automotive seating suppliers in Germany and tier suppliers in Japan are adopting distributed lyocell spinning modules that recycle N-Methylmorpholine N-oxide on-site. This architecture is decentralizing the historical monopoly of pulp-to-fibre integrated complexes and enabling regional biofibre supply within 500-kilometer radii of OEM assembly plants.
EU CSRD Scope 3 disclosure requirements are mandating granular carbon accounting across tiered supply chains. The regulation forces first-tier automotive suppliers to audit and document biogenic carbon content from wood pulp cultivation through finished textile conversion. Biofibre producers with ISO 14067-compliant product carbon footprints and blockchain-tracked chain-of-custody certification are capturing preferred supplier status in German OEM procurement frameworks.
Automotive procurement departments are consolidating qualified biofibre suppliers into multi-year framework agreements with volume commitments and price collars. This replaces spot-market purchasing for commodity viscose and establishes direct contractual relationships between BMW, Mercedes-Benz, and dedicated fibre spinners. The shift is most visible in Bavaria and Baden-Württemberg, where OEM sustainability targets and CSRD compliance deadlines have compressed traditional three-tier supply chain intermediation.
Biofibre Market Segmentation
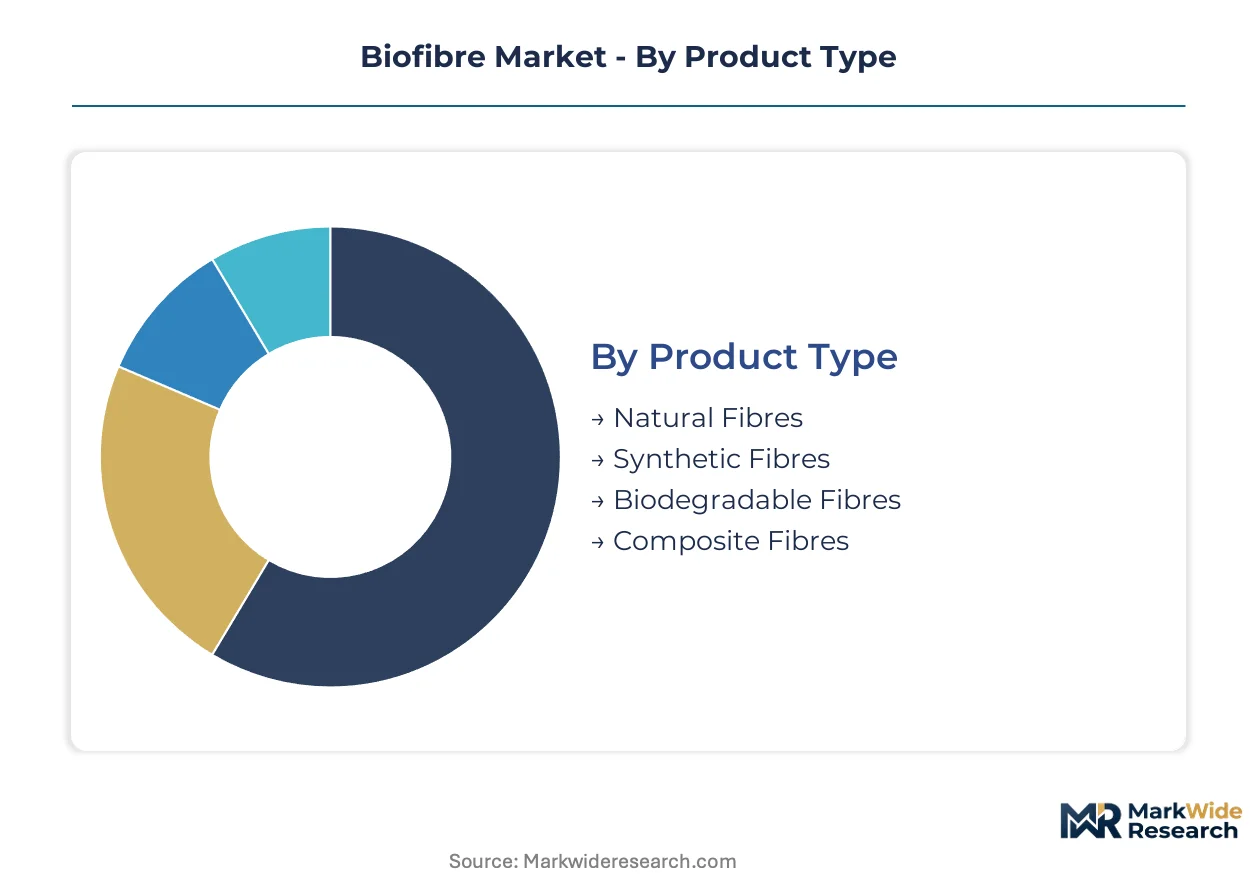
Biofibre procurement decisions diverge sharply between standalone material sourcing and embedded composite systems. Understanding where each segment sits on this integration spectrum reveals which supply chains demand full qualification cycles versus modular substitution.
Product Type:
Natural fibres operate as standalone inputs with minimal downstream processing, while composite fibres demand tight integration with matrix chemistry and curing protocols.
- Natural Fibres:Cotton, jute, and hemp cellulose structures require only mechanical cleaning and length grading before textile spinning. German automotive seating suppliers source long-fibre hemp directly from Bavarian cultivation cooperatives to bypass viscose reconstitution entirely.
- Synthetic Fibres:Petroleum-derived polyester and polyamide filaments dominate technical textile durability benchmarks. Their fossil feedstock dependency exposes buyers to EU ETS carbon cost pass-throughs that bio-based alternatives increasingly circumvent.
- Biodegradable Fibres:Polylactic acid from corn starch and polyhydroxyalkanoates from bacterial fermentation decompose in industrial composting environments. Italian agricultural film regulations mandate soil-degradable mulching materials that these grades satisfy.
- Composite Fibres:Biofibre reinforcements engineered for specific thermoset or thermoplastic matrices require surface functionalization and length optimization. Crash-tested door panel applications from BMW and Mercedes-Benz procurement frameworks specify these grades exclusively.
Volume placements concentrate in Natural Fibres; the faster expansion belongs to Composite Fibres.
Application:
Cost tier stratification separates commodity textile contracts from premium automotive qualification programs with multi-year development horizons.
- Textiles:Apparel and home furnishing applications consume regenerated cellulose at scale. Lenzing AG's Austrian and Czech integrated mills anchor European viscose and lyocell output for fashion industry buyers seeking closed-loop solvent recovery credentials.
- Composites:Structural reinforcement applications demand fibre-matrix interface engineering. Tier suppliers in Baden-Württemberg face acute shortages of polymer scientists capable of engineering adhesion for biofibre-reinforced polypropylene systems.
- Automotive:Interior panels and seat structures require crash certification and lifecycle carbon documentation. EU CSRD Scope 3 disclosure mandates force first-tier suppliers to audit biogenic content from pulp cultivation through finished conversion.
- Medical Devices:Sutures, scaffolds, and drug delivery matrices require absorbability control and biocompliance testing. Regulatory timelines from FDA and EMA extend commercialization pathways beyond typical textile development cycles.
Automotive commands margin premiums; Medical Devices present the steepest expansion trajectory amid absorbable implant demand.
End User:
Customer type determines contracting structure, with government procurement mandates creating dedicated demand channels distinct from private industrial purchasing.
- Aerospace:Cabin interior panels and seating fabrics face stringent flammability and smoke toxicity standards. Biofibre adoption remains constrained until thermal resistance above 200°C becomes economically achievable.
- Automotive Manufacturers:BMW and Mercedes-Benz have established direct framework agreements with dedicated fibre spinners, compressing traditional three-tier supply chain intermediation in Bavaria and Baden-Württemberg.
- Healthcare Providers:Hospital procurement of surgical textiles and wound care materials prioritizes single-use biodegradability. Sterilization compatibility requirements limit material flexibility compared to consumer textile applications.
- Textile Industry:Spinners and weavers operate as intermediaries between raw fibre producers and finished goods manufacturers. Modular fibre bundling contracts now allow grade swapping without full supply chain requalification.
Automotive Manufacturers concentrate qualified supplier relationships; Healthcare Providers are gaining share fastest on single-use regulatory tailwinds.
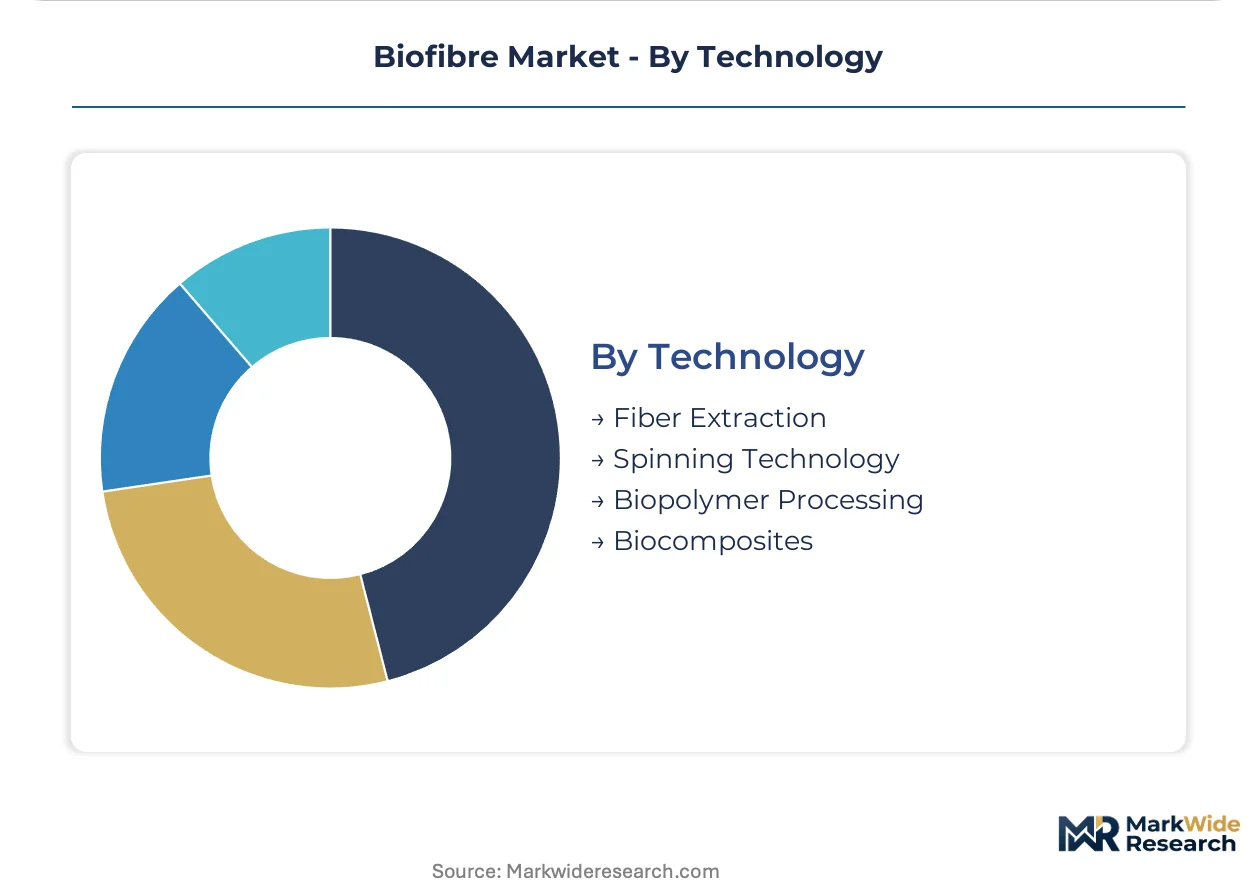
Technology:
Supply concentration in integrated pulp-to-fibre complexes shapes competitive moats around solvent recovery and biopolymer intermediate production.
- Fiber Extraction:Mechanical decortication and chemical retting separate bast fibres from hemp and flax stalks. Czech and Austrian facilities cluster near cultivation regions to minimize moisture-degraded feedstock transport.
- Spinning Technology:Viscose, lyocell, and polylactic acid extrusion systems require distinct solvent recovery infrastructure. Converting legacy viscose lines to lyocell N-Methylmorpholine N-oxide recovery demands capital deployment with multi-year payback horizons.
- Biopolymer Processing:Fermentation and purification of polylactic acid and polyhydroxyalkanoates from agricultural feedstocks. BASF leverages its Ludwigshafen complex for captive adipic acid routes feeding polyamide 6.10 fibre production.
- Biocomposites:Compounding biofibre reinforcements with thermoplastic or thermoset matrices for structural applications. Distributed lyocell spinning modules in Japan enable regional supply within 500-kilometer radii of OEM assembly plants.
Spinning Technology anchors volume capacity; Biocomposites are climbing the fastest on automotive lightweighting procurement pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European integrated mills dominate upstream cellulose fibre output while East Asian automotive clusters drive downstream composite demand. North American federal procurement mandates create a distinct demand channel separate from private industrial purchasing. Latin American agricultural feedstock reserves position the region for biopolymer fermentation scale-up.
Germany
BMW and Mercedes-Benz procurement frameworks mandate certified biofibre supply chains for interior panels and seat structures. The EU Green Deal and CSRD reporting obligations force first-tier suppliers to document Scope 3 emissions from pulp cultivation through finished conversion. Bavarian hemp cultivation cooperatives supply long-fibre feedstock directly to Baden-Württemberg seating manufacturers, bypassing viscose reconstitution entirely.
United States
Federal procurement through the USDA BioPreferred programme specifies minimum biobased content thresholds for textile and composite products. EPA regulations on agricultural film disposal in California and Florida tighten soil-degradability requirements. Midwest corn belt states anchor polylactic acid fermentation capacity, while Southeast automotive assembly plants in South Carolina and Alabama source biofibre composites for lightweighting programmes.
China
Dual carbon goals and MIIT industrial policy direct capital toward closed-loop lyocell solvent recovery systems. Yangtze River Delta textile clusters retrofit legacy viscose lines to N-Methylmorpholine N-oxide recovery, requiring multi-year capital deployment. Shandong Peninsula pulp-to-fibre complexes integrate with regional automotive supplier parks serving domestic EV manufacturers.
Japan
METI Green Innovation Fund directs subsidies toward domestic spinning technology upgrades and bioplastic commercialization. Kanto region automotive seating suppliers adopt distributed lyocell spinning modules that recycle solvent on-site. Nagoya-area OEM assembly plants source biofibre composites within 500-kilometer radii, decentralizing historical Austrian and Czech supply monopolies.
Brazil
Sugarcane bagasse and corn starch feedstocks support polylactic acid and polyhydroxyalkanoate fermentation at scale. ANVISA biocompatibility standards for medical device applications extend regulatory timelines beyond typical textile development cycles. São Paulo state chemical complexes leverage captive agricultural supply for biopolymer intermediate production serving South American packaging and agricultural film markets.
Biofibre Market Competitive Landscape
The competitive structure tilts toward integrated pulp-to-fibre complexes with captive solvent recovery infrastructure. Incumbents with dedicated regulatory affairs teams capture preferred supplier status under EU REACH registration requirements. Three archetypes dominate: Austrian and Czech integrated cellulose producers, German chemical conglomerates with biopolymer intermediate routes, and specialty fibre spinners serving automotive qualification programmes. Competitive moves concentrate on multi-year framework agreements with volume commitments and geographic expansion through distributed spinning modules.
Among integrated cellulose specialists, Lenzing AG anchors European viscose and lyocell output through Austrian and Czech mill complexes. BASF occupies a position within the chemical intermediate tier, leveraging its Ludwigshafen complex for captive adipic acid routes. DuPont represents the high-performance specialty segment where thermal resistance commands premium positioning in narrow application sets.
| Leading Market Players |
|---|
| NatureWorks LLC |
| DuPont |
| BASF |
| Lenzing AG |
| Novamont |
| Cargill |
| Braskem |
| ADM |
| Arkema |
| Others |
Value Network & Pricing Analysis
German automotive OEM procurement departments concentrate qualified supplier relationships into multi-year framework agreements with volume commitments and price collars, establishing contract-based long-term offtake as the dominant pricing model. This buyer concentration compresses traditional three-tier supply chain intermediation and transfers pricing power upstream to integrated pulp-to-fibre complexes with captive solvent recovery infrastructure.
Pricing Analysis
Cost-down pressure on regenerated cellulose grades accelerates because wood pulp prices fluctuate with Nordic forestry harvest cycles and energy costs at Austrian and Czech integrated mills. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14067-compliant product carbon footprints with blockchain-tracked chain-of-custody certification from commodity viscose lacking documentation. Certification premiums command least price sensitivity among BMW and Mercedes-Benz procurement frameworks, while textile industry spinners and weavers operating as intermediaries exhibit highest sensitivity to input cost volatility.
Supply Chain Analysis
Polymer scientists capable of engineering fibre-matrix adhesion for biofibre-reinforced polypropylene systems face acute shortages in Baden-Württemberg and Bavaria manufacturing clusters. Supply concentrates in Austria and Czechia for integrated pulp-to-fibre mills, with secondary nodes emerging in Japan's Kanto region through distributed lyocell spinning modules. Raw material dependencies draw from Nordic wood pulp, corn starch from the US Midwest corn belt, and sugarcane bagasse from São Paulo state chemical complexes. Single-source vulnerability around Austrian and Czech solvent recovery infrastructure poses structural risk. Distribution runs through direct contractual relationships between OEMs and dedicated fibre spinners, displacing spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofibre market functions as a cost-of-compliance story where EU ECHA REACH registration requirements for novel bio-based monomers create multi-year compliance timelines that favor incumbents with dedicated regulatory affairs teams and captive toxicology data, erecting a formidable barrier-to-entry moat.
For Market Incumbents: Lock in preferred supplier status under German OEM procurement frameworks by securing ISO 14067-compliant product carbon footprints and blockchain-tracked chain-of-custody certification before CSRD disclosure deadlines tighten. Deepen upstream control over Nordic wood pulp supply through long-term offtake agreements with Bavarian hemp cultivation cooperatives, defending against emerging distributed lyocell spinning modules that decentralize historical production monopolies. For New Entrants and Emerging Players: Distributed lyocell spinning modules with on-site N-Methylmorpholine N-oxide solvent recovery offer a technology-first wedge into underpenetrated agricultural films facing tightening disposal regulations in Italy and Spain. Target biodegradable mulching and greenhouse film applications where soil-degradability mandates create pull for polylactic acid and starch-based fibres, partnering with regional OEM assembly plants within 500-kilometer supply radii to bypass established Austrian and Czech supply chains. For Investors and Strategic Acquirers: The window for entry favors integrated cellulose specialists with captive solvent recovery infrastructure and established regulatory affairs capabilities over pure-play biopolymer fermentation startups lacking downstream spinning assets. Acquisition candidates should demonstrate qualified supplier relationships within BMW and Mercedes-Benz procurement frameworks. Watch for inflection signals in federal procurement mandate expansion beyond current USDA BioPreferred thresholds into defence and infrastructure applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood Pulp Supply | Long-term offtake agreements with Bavarian hemp cooperatives secure feedstock cost predictability against Nordic harvest volatility. |
| Lyocell Spinning Module Deployment | Distributed N-Methylmorpholine N-oxide recovery systems in Japan's Kanto region enable 500-kilometer OEM supply radii. |
| Carbon Footprint Certification Investment | ISO 14067 compliance and blockchain-tracked chain-of-custody documentation capture preferred supplier status under CSRD mandates. |
| Composite Interface Chemistry R&D | Fibre-matrix adhesion engineering for biofibre-reinforced polypropylene addresses acute polymer scientist shortages in Baden-Württemberg. |
| Biodegradable Film Formulation Partnership | Polylactic acid and starch-based fibre development for Italian and Spanish agricultural film regulations opens dedicated demand channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with fibre spinning plant managers, automotive Tier 1 procurement leads, chemical distribution channel partners, and technical R&D directors with bottom-up and top-down triangulation. Secondary validation drew from EU ECHA REACH registration databases, USDA BioPreferred programme specifications, SEC 10-K filings of listed chemical conglomerates, and automotive production databases tracking biofibre composite adoption.
Reconciliation of supply-side capacity announcements, demand-pull indicators from OEM sustainability target disclosures, and trade flow data informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application vertical, end-user category, and technology route. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Industry-specific forecast inputs incorporated CSRD compliance deadline clustering and federal procurement mandate threshold trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under divergent biodegradability certification standard harmonization scenarios or sudden Nordic wood pulp supply disruptions. Material deviation in EU ETS carbon cost pass-through rates or REACH registration timeline extensions for novel bio-based monomers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Global Citrus Bioflavonoids Market