
 Bio-Based Succinic Acid Market | 2026-2036
Bio-Based Succinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Succinic Acid Market Analysis
Food industry offtake is shifting toward bio-based acidulants and preservatives as clean-label formulations gain shelf space in North American and European retail channels. BASF SE leverages its integrated biotechnology platform to supply pharmaceutical-grade succinic acid with documented purity certificates. Roquette Frères anchors its position through fermentation expertise rooted in starch-derived feedstock processing. DSM competes on enzymatic synthesis pathways that reduce energy intensity compared to conventional petrochemical routes.
Bio-based succinic acid is a C4 dicarboxylic acid produced through microbial fermentation of renewable carbohydrates such as corn starch, sugarcane, or lignocellulosic biomass, typically achieving purity levels above 99.5% for polymer-grade applications. It functions primarily as a platform chemical for synthesizing polybutylene succinate (PBS), polyurethane precursors, and pharmaceutical intermediates, displacing maleic anhydride in multiple industrial pathways. Solid succinic acid dominates current volume flows due to stability in storage and compatibility with downstream chemical processing equipment. Fermentation technology leads investment activity as producers scale anaerobic bioreactor capacity, while bioplastics applications capture widening margin pools as brand-owner sustainability commitments harden into procurement specifications.
EPA bio-preferred program standards and EU REACH registration requirements shape product certification pathways for North American and European market access, creating compliance moats for established producers. FDA food additive regulations and EFSA safety evaluations govern pharmaceutical and food-grade succinic acid purity thresholds, directly influencing manufacturing investment decisions. Stakeholders must monitor feedstock cost volatility and evolving biopolymer blending ratios to calibrate capacity commitments against offtake contract structures.
Market Dynamics
Fermentation technology scale-up and EU Green Deal compliance deadlines are compressing the competitive window for petroleum-derived succinic acid, forcing capital deployment into anaerobic bioreactor capacity before 2030 certification cliffs.
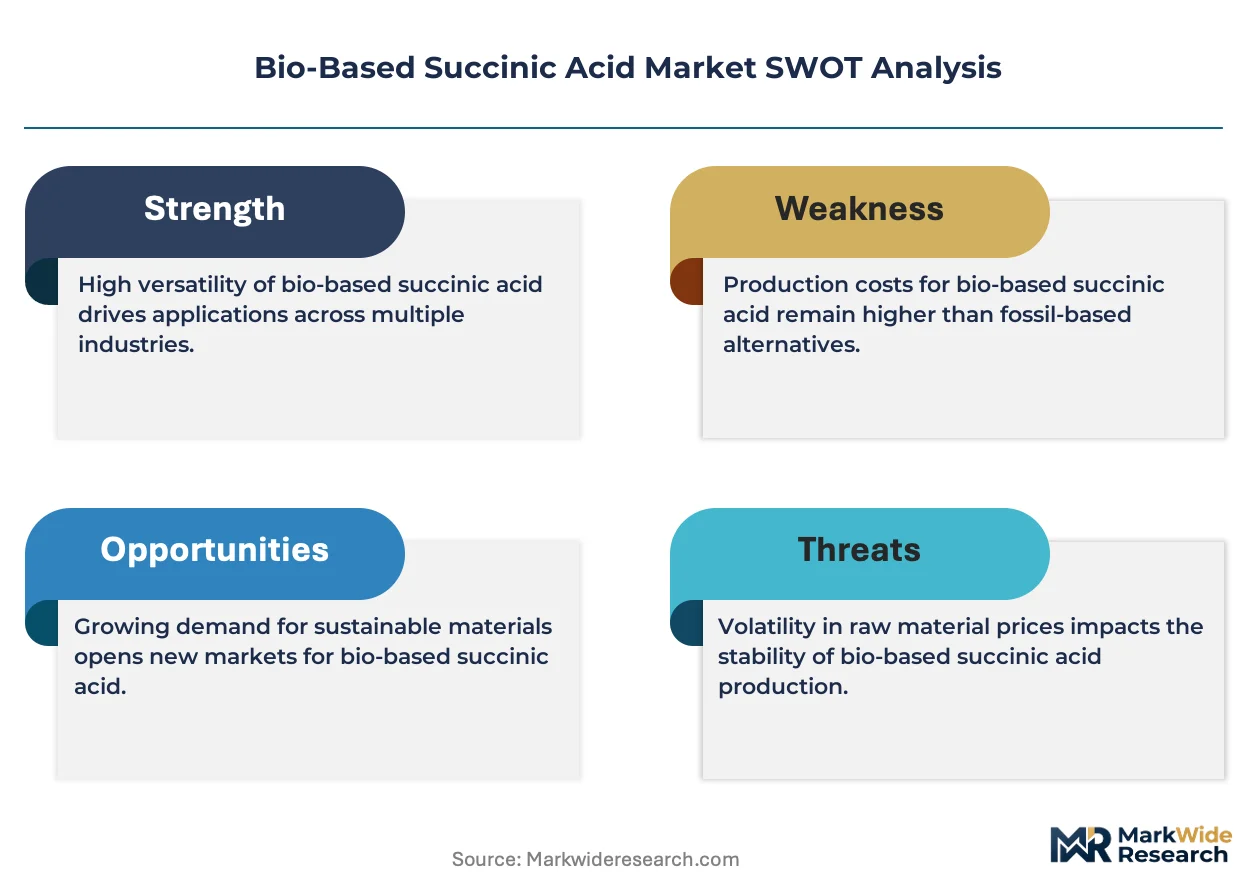
Growth Catalysts
- REACH substitution mandates:ECHA registration requirements for petrochemical alternatives accelerate biobased procurement across European polyurethane and polyester value chains.
- Automotive OEM specifications:German manufacturers embed bio-based PBS content targets into tier-1 supplier contracts, pulling fermentation-derived feedstock demand.
- Lignocellulosic feedstock processing:Second-generation biomass conversion routes reduce raw material cost exposure to corn and sugarcane price cycles.
Market Restraints
- Feedstock cost volatility:Corn starch and sugarcane prices fluctuate with agricultural commodity markets, compressing margin predictability for fermentation operators.
- Purification energy intensity:Crystallization and downstream processing consume substantial thermal energy, creating carbon footprint tensions with green marketing claims.
- Petrochemical maleic anhydride:Established petroleum routes maintain cost advantages at scale, limiting bio-based penetration in price-sensitive industrial applications.
Strategic Opportunities
- Pharmaceutical-grade certification:FDA and EMA purity documentation opens margin-rich segments for documented 99.5%+ purity fermentation output.
- India bioplastics procurement:BIS standards development and state-level plastic bans create early-mover positioning for fermentation-based platform chemicals.
- Enzymatic synthesis convergence:Cell-free biocatalysis paired with continuous processing reduces reactor residence times and capital intensity.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiology and metabolic pathway optimization expertise concentrates in Germany and Netherlands, constraining global facility staffing.
- Multi-jurisdiction certification timelines:Parallel FDA food additive, EPA bio-preferred, and REACH registration pathways extend market entry cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Succinic Acid Market |
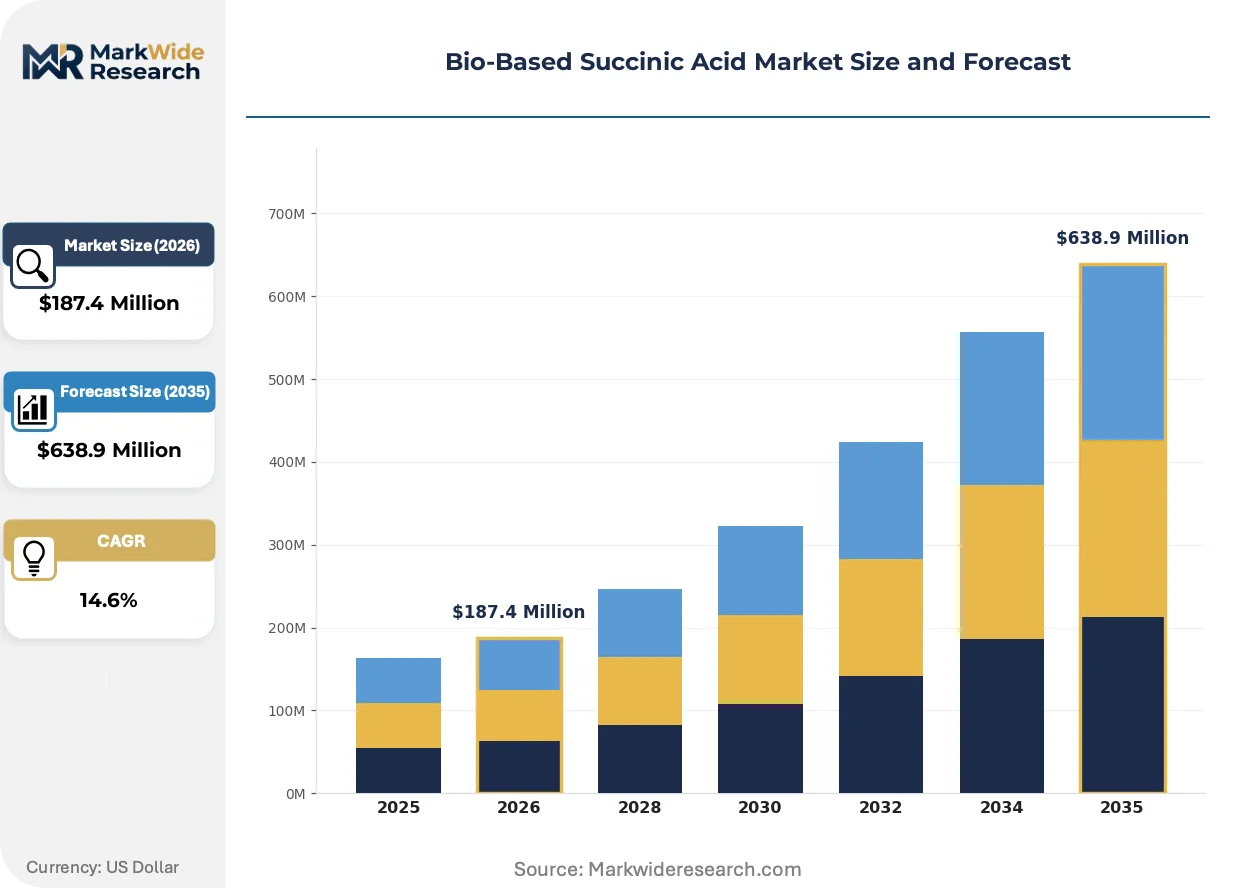
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Succinic Acid, Solid Succinic Acid, Succinic Acid Derivatives, Bio-Based Solvents Application: Pharmaceuticals, Food Additives, Bioplastics, Cosmetics End User: Food Industry, Pharmaceutical Sector, Chemical Manufacturers, Personal Care Production Technology: Fermentation, Catalytic Process, Bioprocessing, Enzymatic Synthesis |
| Companies Covered | BASF SE, Roquette Frères, Mitsubishi Chemical Group Corporation, DSM, Corbion N.V., BioAmber Inc., PTT Global Chemical Public Company Limited, Mitsui & Co., Ltd., Myriant Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Succinic Acid Market Emerging Trajectories
Anaerobic fermentation pathway optimization and regulatory compliance automation are compressing production economics and accelerating certification throughput for bio-based platform chemicals.
Continuous fermentation systems with real-time metabolite monitoring are rewriting the capital efficiency calculus for commercial-scale succinic acid manufacturing. Bioplastics compounders in Germany and the Netherlands adopt these integrated bioreactor configurations to secure supply under automotive OEM sustainability mandates. The technology is rewriting minimum viable scale thresholds, enabling mid-cap producers to achieve unit economics previously reserved for integrated petrochemical complexes.
EU Green Deal carbon border adjustment mechanisms and delegated acts under the Packaging and Packaging Waste Regulation tighten embodied carbon thresholds for imported chemical intermediates. Industrial users face compliance verification requirements that favor EU-registered fermentation production with documented lifecycle assessments. Polybutylene succinate manufacturers with European supply chains adjust procurement specifications to preempt 2026-2027 adjustment phase entry.
Brand-owner sustainability commitments harden into binding procurement clauses with penalty structures for non-compliance. Food and personal care multinationals in North America and Europe now require bio-based acidulant documentation with mass-balance chain-of-custody certification. Tier-2 and tier-3 suppliers absorb compliance costs or face contract termination, compressing the supplier base toward integrated fermentation operators with established certification infrastructure.
Bio-Based Succinic Acid Market Segmentation
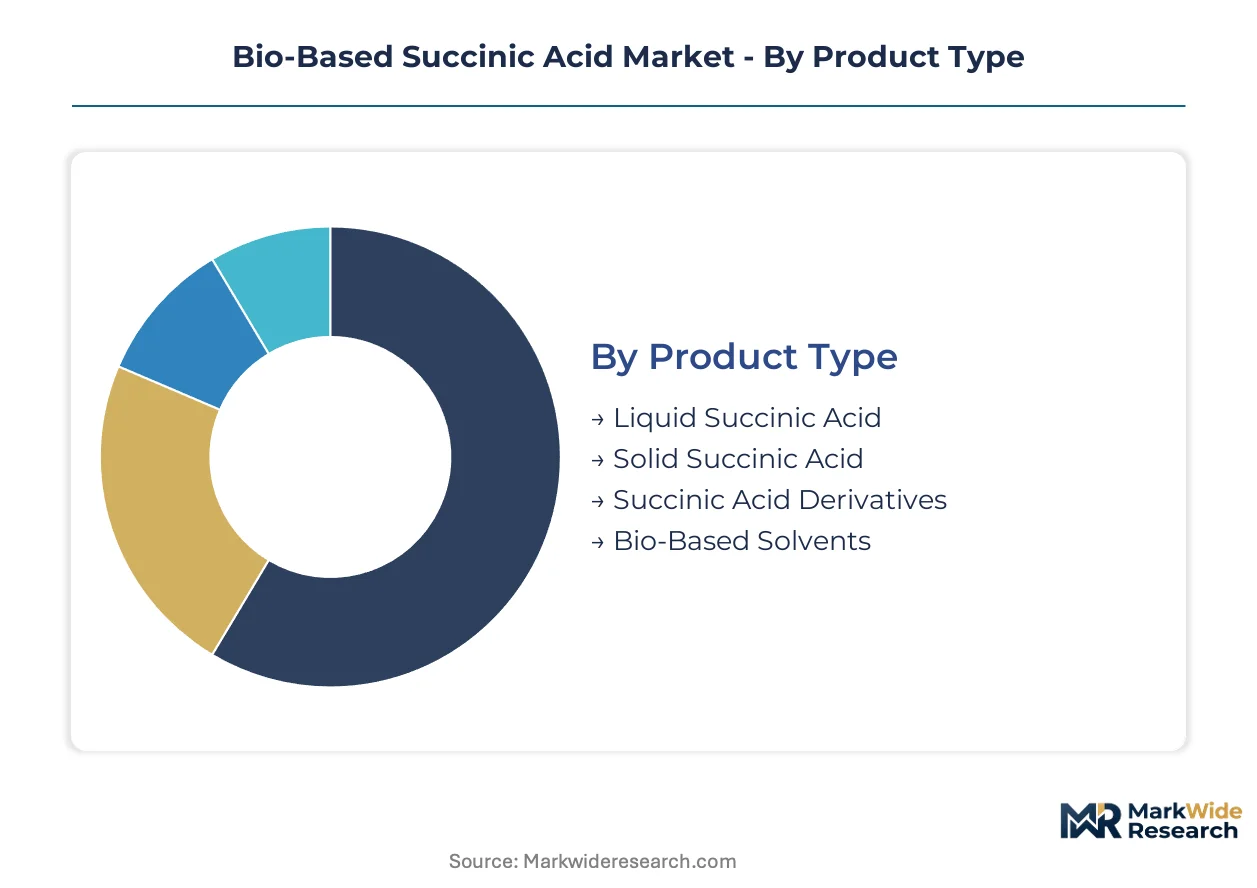
Segmentation in bio-based succinic acid markets reveals how purification requirements, regulatory pathways, and downstream processing economics fragment procurement specifications across polymer-grade, food-grade, and pharmaceutical-grade tiers. Manufacturers calibrate fermentation scale and downstream investment to match these divergent margin structures.
Product Type:
Upgrade cycles from liquid to solid forms are accelerating as automotive OEMs and bioplastics compounders impose stability and handling specifications that liquid variants cannot meet.
- Solid Succinic Acid:Crystalline powder above 99.5% purity dominates polymer-grade supply chains due to thermal stability and compatibility with PBS extrusion equipment. German automotive tier-1 suppliers mandate solid form documentation under EU Green Deal procurement clauses, concentrating demand in industrial biotech clusters around Frankfurt and Ludwigshafen.
- Liquid Succinic Acid:Aqueous solutions suit food acidulant and pharmaceutical buffer applications where dissolution speed outweighs shelf-life concerns. North American clean-label food manufacturers are expanding offtake as FDA food additive documentation requirements harden for petroleum-derived alternatives.
- Succinic Acid Derivatives:Functionalized esters and anhydrides serve as polyurethane precursors and polyester intermediates with modified reactivity profiles.
- Bio-Based Solvents:Succinate ester solvents displace petroleum-derived options in coatings and cleaning formulations under EPA bio-preferred standards.
Volume placements concentrate in Solid Succinic Acid; the faster expansion belongs to Liquid Succinic Acid.
Application:
Cost tier stratification separates pharmaceutical-grade certification investments from commodity bioplastics volume plays.
- Bioplastics:Polybutylene succinate synthesis consumes the largest fermentation output volumes as European packaging mandates tighten. PBS compounders in the Netherlands and Germany pay premium pricing for REACH-registered supply with documented lifecycle assessments, creating margin pools unavailable to industrial acidulant buyers.
- Pharmaceuticals:Excipient and active pharmaceutical intermediate applications demand EMA and FDA purity documentation that extends production cycles and multiplies quality overhead. DSM and BASF SE anchor this segment through integrated biotechnology platforms with established regulatory dossiers.
- Food Additives:Acidulant and preservative functions in clean-label formulations drive North American and European retail channel offtake.
- Cosmetics:pH adjustment and buffering applications in personal care formulations require cosmetic-grade certification under EU Cosmetics Regulation.
Margin concentration sits with Pharmaceuticals; volume leadership rests with Bioplastics.
End User:
Customer-type fragmentation separates specification-heavy pharmaceutical procurement from price-sensitive chemical manufacturing.
- Chemical Manufacturers:Polyurethane and polyester producers represent the largest volume sink, with procurement teams negotiating long-term fermentation supply contracts to hedge maleic anhydride price volatility. German chemical parks with integrated bioreactor infrastructure capture preferential supply allocations.
- Pharmaceutical Sector:QA/QC documentation requirements and audit protocols create switching costs that favor incumbent suppliers with multi-jurisdiction regulatory files. EMA inspections and FDA facility registrations extend sales cycles but protect margin structures.
- Food Industry:Clean-label formulation trends in North American and European retail are pulling fermentation-derived acidulant demand.
- Personal Care:Cosmetic brand-owner sustainability commitments are hardening into mass-balance certification requirements for surfactant and emollient precursors.
Contract tenure runs longest with Pharmaceutical Sector; spot market liquidity clusters around Chemical Manufacturers.
Production Technology:
Technology maturity curves separate scaled fermentation infrastructure from experimental enzymatic routes.
- Fermentation:Anaerobic bioreactor systems using engineered yeast or bacterial strains dominate commercial capacity, with Roquette Frères and similar operators leveraging starch-derived feedstock processing expertise. German industrial biotech clusters concentrate operational know-how and metabolic pathway optimization talent.
- Enzymatic Synthesis:Cell-free biocatalysis reduces energy intensity and reactor residence times, though scale-up economics remain unproven at commercial volumes. DSM competes on this pathway for pharmaceutical-grade output where purity premiums offset higher capital costs.
- Catalytic Process:Chemical conversion of bio-derived intermediates bridges fermentation and petrochemical processing equipment.
- Bioprocessing:Integrated upstream and downstream configurations optimize yield across lignocellulosic feedstock variations.
Installed capacity concentrates in Fermentation; steepest expansion trajectory belongs to Enzymatic Synthesis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial biotech clusters in the German Rhine-Main and Rhine-Neckar regions concentrate fermentation capacity serving automotive OEM sustainability mandates. Tax incentives under the EU Green Deal industrial policy accelerate capital deployment into anaerobic bioreactor infrastructure across multiple jurisdictions.
Germany
Automotive tier-1 suppliers in Frankfurt and Ludwigshafen embed bio-based PBS content targets into procurement contracts. EU REACH substitution mandates under ECHA registration requirements pull fermentation-derived feedstock demand from petrochemical alternatives. The Rhine-Main industrial biotech cluster anchors operational know-how for metabolic pathway optimization.
United States
Clean-label food manufacturers expand offtake of fermentation-derived acidulants as FDA food additive documentation requirements harden. EPA bio-preferred program standards shape product certification pathways for North American market access. Midwest agricultural processing corridors supply corn starch feedstock to fermentation operators scaling commercial capacity.
Netherlands
PBS compounders pay premium pricing for REACH-registered supply with documented lifecycle assessments under EU Packaging and Packaging Waste Regulation delegated acts. The Rotterdam-Antwerp chemical corridor integrates bioreactor configurations to secure supply under automotive OEM sustainability clauses. ECHA compliance verification requirements favor domestic fermentation production.
China
Dual carbon goals and MIIT industrial biotechnology development plans accelerate substitution mandates across polyurethane and polyester value chains. Yangtze River Delta chemical parks evaluate lignocellulosic feedstock processing to reduce raw material cost exposure. SAMR standards development creates certification infrastructure for bio-based platform chemicals.
India
State-level plastic bans and BIS standards development create early-mover positioning for fermentation-based platform chemicals. Maharashtra and Gujarat industrial corridors attract capacity investment as brand-owner sustainability commitments harden into procurement specifications. CDSCO pharmaceutical-grade documentation requirements open margin-rich segments for documented purity fermentation output.
Bio-Based Succinic Acid Market Vendor Landscape
Top-tier vendors anchor integrated biotechnology platforms with established multi-jurisdiction regulatory dossiers, while mid-cap fermentation specialists compete on feedstock flexibility and regional certification speed. The vendor base stratifies across three tiers: integrated chemical conglomerates with pharmaceutical-grade infrastructure, starch-processing conglomerates leveraging agricultural supply chains, and pure-play biotech operators scaling novel enzymatic pathways. Strategic archetypes include fermentation-scale maximizers, enzymatic-synthesis innovators, and backward-integrated feedstock controllers. Dominant competitive moves encompass capacity expansion in German industrial biotech clusters and technology licensing partnerships to circumvent bioprocess engineering talent scarcity.
Among European-based integrated operators, BASF SE and DSM occupy positions exemplifying the pharmaceutical-grade certification tier, while Roquette Frères anchors the agricultural-feedstock-integrated archetype. These three entities represent distinct competitive vectors: BASF SE through documented purity certificates, DSM via enzymatic synthesis pathways, and Roquette Frères through starch-derived feedstock processing expertise.
| Leading Market Players |
|---|
| BASF SE |
| Roquette Frères |
| Mitsubishi Chemical Group Corporation |
| DSM |
| Corbion N.V. |
| BioAmber Inc. |
| PTT Global Chemical Public Company Limited |
| Mitsui & Co., Ltd. |
| Myriant Corporation |
| Others |
Supply Flow & Price Mechanics
Industrial microbiology talent scarcity in the Rhine-Main and Rhine-Neckar clusters widens labor-cost differentials between German fermentation operators and emerging Asian capacity, directly translating into premium-mid-economy pricing stratification across pharmaceutical-grade and commodity bioplastics tiers.
Pricing Analysis
Short lead-time premiums concentrate in German automotive tier-1 supply chains where EU Green Deal compliance deadlines compress procurement windows. Contract-based long-term offtake dominates volume transactions, with price differentiation driven by REACH registration status and documented lifecycle assessment completeness. Cost compression in standard-grade bioplastics intensifies as lignocellulosic feedstock processing scales in China and India. Chemical manufacturers exhibit highest price sensitivity due to maleic anhydride substitution economics, while pharmaceutical sector buyers absorb premiums for FDA and EMA purity documentation.
Supply Chain Analysis
EU Green Deal domestic-content mandates and carbon border adjustment mechanisms are reshaping sourcing toward ECHA-registered European fermentation capacity. Supply concentrates in Germany, the Netherlands, and the United States, with raw material dependencies on corn starch from Midwest agricultural corridors and sugarcane from Brazilian processing networks. Single-source vulnerability runs through engineered yeast strain suppliers concentrated in German industrial biotech clusters. Distribution runs through integrated chemical parks in Ludwigshafen and Rotterdam-Antwerp corridors serving automotive OEM sustainability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity expansion timelines lag demand acceleration from automotive OEM bio-based PBS targets, sustaining pricing power for incumbent operators with certified European supply chains.
For Market Incumbents: Extend certification infrastructure into Indian and Chinese regulatory frameworks before BIS and SAMR standards harden into procurement barriers. Deepen backward integration into lignocellulosic feedstock processing to isolate margin structures from corn price volatility. Prioritize continuous fermentation technology licensing partnerships to circumvent bioprocess engineering talent scarcity constraining global facility staffing.
For New Entrants and Emerging Players: Indian state-level plastic bans and CDSCO pharmaceutical-grade documentation requirements offer penetrable entry points with lower incumbent saturation. Target Maharashtra and Gujarat industrial corridors where brand-owner sustainability commitments outpace certified supply availability. Pursue enzymatic synthesis differentiation to reduce capital intensity versus anaerobic bioreactor scale-up requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-scale maximizers possessing established REACH dossiers given EU Packaging and Packaging Waste Regulation delegated acts tightening embodied carbon thresholds. Five-to-ten year viability favors operators with integrated starch-processing supply chains and automotive OEM contract visibility. Monitor ECHA substitution mandate enforcement intensity as inflection indicator for bio-based platform chemical demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Anaerobic bioreactor deployment in German industrial biotech clusters secures automotive OEM contract allocations under EU Green Deal timelines. |
| Backward Integration | Lignocellulosic feedstock processing investment reduces raw material cost exposure to agricultural commodity price cycles. |
| Green Manufacturing Transition | Continuous fermentation systems with real-time metabolite monitoring compress carbon footprint for ECHA compliance verification. |
| Long-term Supply Agreement | Multi-year offtake contracts with PBS compounders hedge against maleic anhydride price volatility in polyurethane value chains. |
| Joint Venture | Technology licensing partnerships with Indian and Chinese operators circumvent bioprocess engineering talent scarcity in facility staffing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fermentation plant managers, procurement leads at automotive tier-1 suppliers, bioplastics compounders, and ECHA regulatory affairs specialists combined with secondary validation from Cefic industry reports, SEC 10-K disclosures, and EU customs databases. Bottom-up capacity installation tracking and top-down demand segmentation triangulated volume estimates across polymer-grade, food-grade, and pharmaceutical-grade tiers.
Data-stream reconciliation across production capacity databases, feedstock cost indices, and downstream offtake contract registries informed the analytical framework over the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry application, production technology pathway, and regional regulatory cluster. CAGRs derived from weighted average of capacity expansion schedules and substitution elasticity estimates against petrochemical maleic anhydride. Industry-specific inputs encompassed automotive OEM sustainability target disclosure tracking and ECHA registration timeline monitoring.
Revisions become necessary when feedstock cost volatility exceeds modeled ranges, bioprocess engineering talent scarcity intensifies facility commissioning delays, or EU carbon border adjustment mechanism implementation accelerates beyond baseline assumptions. Forecasts reflect documented capacity commitments and regulatory enforcement intensity assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market