
 Bioherbicides Market | 2026-2036
Bioherbicides Market Size, Share, and Industry Trends Forecast 2026-2036
Bioherbicides Market Intelligence
Modular tank-mix configurations is shifting how growers assemble weed management programs from single-product reliance to layered biological-chemical protocols. Certis USA leverages its fermentation infrastructure to supply consistent microbial inoculum at scale. Seipasa anchors Southern European specialty crop penetration with botanical extract formulations. FMC Corporation competes through backward integration into active ingredient discovery, reducing reliance on external research partnerships.
Bioherbicides comprise living microorganisms, plant-derived allelochemicals, and biochemical compounds formulated to suppress or eliminate weed species through species-specific modes of action such as host-pathogen specificity or enzymatic inhibition. These agents function primarily to manage herbicide-resistant weed populations while preserving soil microbiome integrity and reducing synthetic chemical residues in food systems. Microbial bioherbicides occupy the dominant value position due to longer residual patent protection and reproducible manufacturing via submerged fermentation. Botanical bioherbicides command premium positioning in organic-certified supply chains where residue limits are most stringent. Application through crop management channels generates the largest revenue pool, though non-crop areas including municipal rights-of-way represent the fastest-expanding adoption segment.
EPA biopesticide registration under FIFRA Section 3(c)(5) creates accelerated review timelines that compress market entry cycles for novel microbial strains. EU REACH and the Sustainable Use Directive impose residue thresholds that favor bioherbicide substitution in export-oriented production systems. Stakeholders must monitor regulatory harmonization between EPA and EMA frameworks, as divergent data requirements for microbial safety testing determine which innovators can pursue parallel market filings without duplicative toxicology investment.
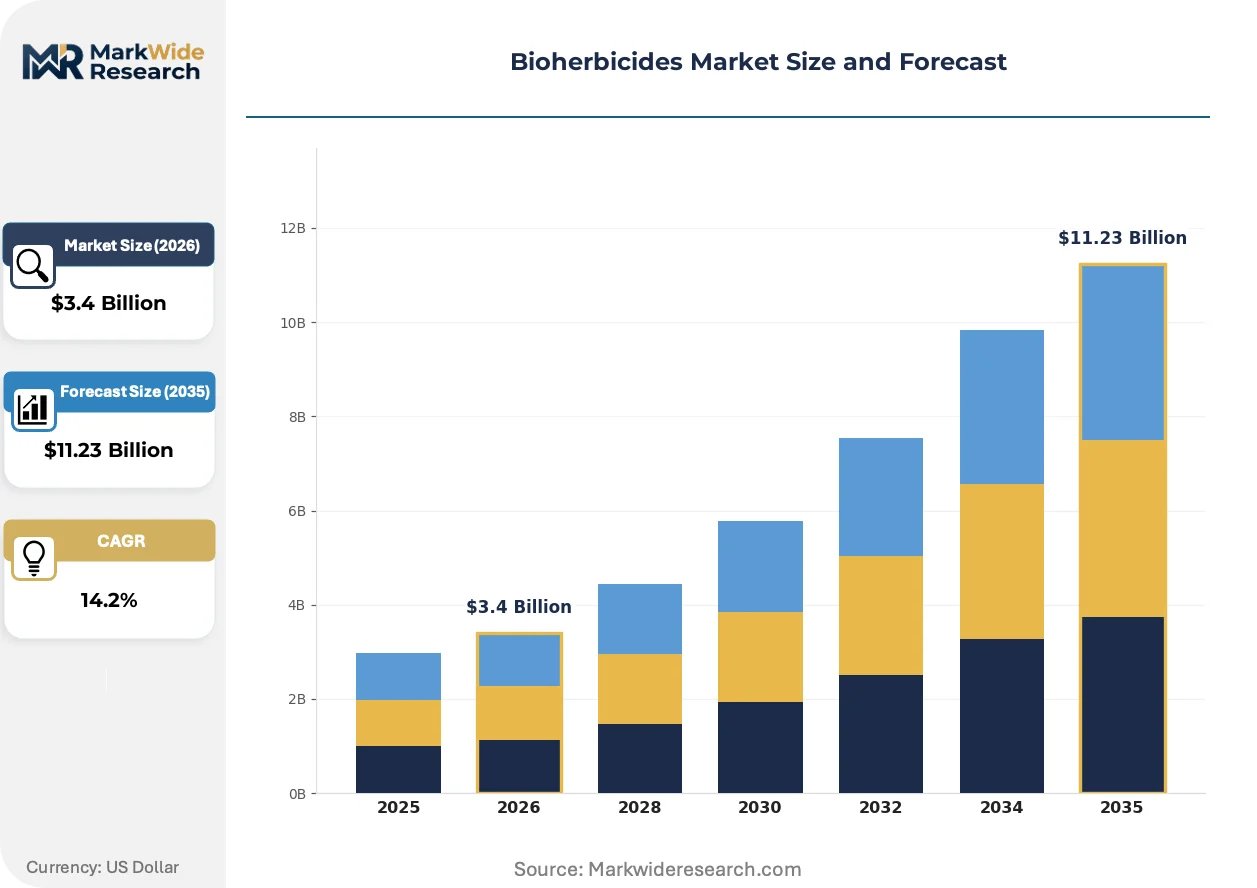
Market Dynamics
Glyphosate resistance management is compressing grower switching cycles across major row-crop regions, forcing biological-chemical protocol layering into standard agronomic practice.
Growth Catalysts
- EPA FIFRA Section 3(c)(5):Accelerated biopesticide review timelines compress market entry cycles for novel microbial strains, reducing regulatory capital requirements relative to synthetic chemistry pathways.
- Organic supply chain procurement:Certification-driven residue limits in export-oriented production systems create specification pull for botanical formulations in premium food channels.
- Submerged fermentation infrastructure:Reproducible manufacturing platforms enable consistent microbial inoculum supply at commercial scale, reducing batch-to-batch efficacy variation.
Market Restraints
- Host-range specificity:Narrow weed-targeting limits addressable market size per formulation, requiring portfolio breadth investments that strain R&D budgets.
- Formulation stability:Live microbial viability degrades under temperature excursions in distribution networks lacking cold-chain infrastructure across Brazil's Cerrado and US Plains states.
- Synthetic herbicide price floors:Commodity glyphosate pricing creates substitution pressure in cost-sensitive conventional cropping systems.
Strategic Opportunities
- Municipal rights-of-way expansion:Non-crop vegetation management contracts represent the fastest-adoption segment as public agencies face synthetic chemical application restrictions near waterways.
- EU Green Deal residue thresholds:Export-oriented producers in Southern Europe anchor demand for botanical formulations meeting EFSA import tolerance requirements.
- RNA interference convergence:Bioherbicide-RNAi stack development enables species-specific mode-of-action layering against resistant weed populations.
Industry Challenges
- Field trial standardization:Variable environmental conditions across trial sites complicate efficacy data packages required for EPA and EMA parallel submissions.
- Strain banking protocols:Long-term microbial culture preservation demands specialized cryogenic infrastructure that mid-scale innovators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioherbicides Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Bioherbicides, Botanical Bioherbicides, Biochemical Bioherbicides, Bioactive Agents Formulation: Granular, Liquid, Powder, Emulsifiable Concentrate Application: Crop Management, Pastureland, Non-Crop Areas, Forestry End User: Growers, Agricultural Cooperatives, Crop Consultants, Research Institutions |
| Companies Covered | Certis USA, Seipasa, FMC Corporation, Harpe BioHerbicide Solutions, BioWest Ag Solutions, Marrone Bio Innovations, Corteva, Hindustan Bio Tech, Emery Oleochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioherbicides Market Strategic Shifts & Innovations
Modular tank-mix architectures are displacing single-product weed management programs, enabling growers to assemble layered protocols from discrete biological and chemical components.
RNA interference technology is expanding into bioherbicide development pipelines, enabling sequence-specific gene silencing in target weed species without off-target crop damage. Large-scale row-crop operators in the US Corn Belt and Brazilian soybean regions are piloting RNAi-microbial combination treatments during the 2024-2025 growing seasons. This convergence is expanding into patent-protected product categories previously dominated by synthetic chemistry, creating defensible intellectual property positions for biological innovators.
EU REACH registration amendments are tightening residue thresholds for synthetic herbicides in imported agricultural commodities, creating regulatory displacement pressure favoring bioherbicide substitution. Export-oriented specialty crop producers in Spain, Italy, and Portugal now face EFSA monitoring programs that detect glyphosate metabolites at parts-per-billion levels. Botanical formulation suppliers are capturing this displacement through organic-certified supply chain integration.
Buyer concentration among integrated grain processors is compressing supplier qualification timelines, favoring bioherbicide vendors with documented fermentation capacity and multi-year efficacy databases. Procurement teams at major oilseed and cereal processors now require microbial strain identification and mode-of-action documentation prior to contract inclusion. This compression is most visible in North American Plains states where glyphosate resistance management has become a procurement specification rather than a grower preference.
Bioherbicides Market Segmentation
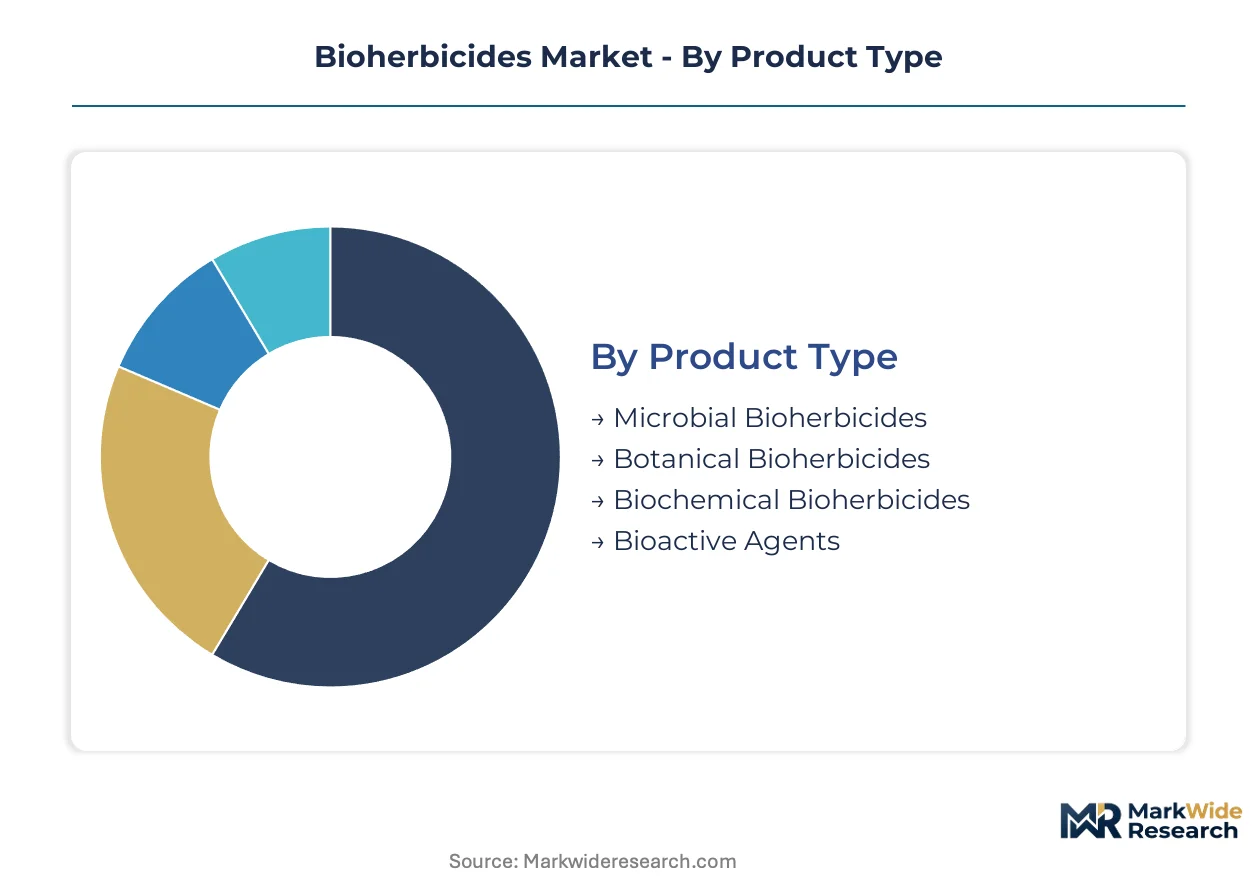
Bioherbicide segmentation reflects divergent regulatory pathways and manufacturing requirements across product categories. EPA FIFRA Section 3(c)(5) accelerates microbial approvals while botanical formulations face EFSA residue scrutiny. Understanding these certification burdens enables suppliers to prioritize R&D investment and geographic market entry sequencing.
Product Type:
EPA biopesticide registration compresses timelines for microbial strains while EU REACH residue thresholds favor botanical substitution in export channels.
- Microbial Bioherbicides:Living fungal or bacterial formulations manufactured via submerged fermentation deliver reproducible inoculum at commercial scale. Demand concentrates in North American Plains states where glyphosate resistance management drives grower switching toward species-specific host-pathogen solutions.
- Botanical Bioherbicides:Plant-derived allelochemicals formulated from extracts meet organic-certified supply chain residue limits most stringent in premium food channels. Southern European specialty crop producers in Spain, Italy, and Portugal anchor penetration as EFSA monitoring programs detect synthetic metabolites at parts-per-billion levels.
- Biochemical Bioherbicides:Naturally occurring compounds with non-toxic modes of action occupy intermediate regulatory positioning between microbial and synthetic chemistries.
- Bioactive Agents:Purified protein or peptide formulations derived from microbial fermentation occupy emerging patent-protected categories.
Microbial Bioherbicides sits at the top of the volume ranking, with Botanical Bioherbicides climbing the fastest.
Formulation:
Distribution infrastructure constraints and application equipment compatibility determine formulation selection across cost-sensitive versus premium market tiers.
- Liquid:Tank-mix compatible concentrates enable modular protocol assembly from discrete biological and chemical components. Brazilian soybean operators and US Corn Belt growers pilot liquid microbial-RNAi combinations during growing seasons.
- Granular:Soil-incorporated delivery systems protect live microbial viability from temperature excursions in distribution networks lacking cold-chain infrastructure across Brazil's Cerrado.
- Powder:Lightweight shipping profiles reduce freight costs for export-oriented producers meeting EU import tolerance requirements.
- Emulsifiable Concentrate:Oil-based carriers improve leaf-surface retention for contact-acting botanical extracts in specialty crop applications.
Liquid formulations dominate procurement specifications, with Granular gaining share fastest in regions with inadequate cold-chain coverage.
Application:
End-use concentration varies sharply between crop management revenue pools and non-crop adoption velocity driven by public agency restrictions.
- Crop Management:Integrated grain processor procurement teams require microbial strain identification and multi-year efficacy databases prior to contract inclusion. Buyer concentration compresses supplier qualification timelines most visibly in oilseed and cereal production systems.
- Non-Crop Areas:Municipal rights-of-way vegetation management contracts face synthetic chemical application restrictions near waterways. Public agencies represent the steepest expansion trajectory as regulatory displacement accelerates.
- Pastureland:Forage quality preservation drives adoption among livestock operators managing invasive weed species without grazing restrictions.
- Forestry:Long-rotation timber stands require multi-year weed suppression compatible with reforestation certification standards.
Crop Management generates the largest revenue pool, with Non-Crop Areas expanding most quickly.
End User:
Procurement authority concentration and technical advisory relationships shape channel strategy across direct grower sales versus institutional research partnerships.
- Growers:Large-scale row-crop operators in US Corn Belt and Brazilian soybean regions specify microbial formulations in procurement contracts. Direct purchasing decisions increasingly incorporate resistance management as mandatory specification rather than preference.
- Agricultural Cooperatives:Consolidated buying power enables volume-based pricing negotiations and shared application equipment infrastructure.
- Crop Consultants:Technical advisory relationships influence protocol layering recommendations between biological and chemical components.
- Research Institutions:Field trial partnerships generate efficacy data packages required for EPA and EMA parallel submissions without duplicative toxicology investment.
Growers command the highest procurement volume, with Agricultural Cooperatives gaining influence fastest through consolidated purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioherbicide commercialization traces its industrial roots to submerged fermentation facilities established in the United States during the 1980s, with Brazilian soybean expansion and European organic certification demands subsequently diversifying geographic production centers.
United States
Glyphosate resistance management protocols and EPA FIFRA Section 3(c)(5) accelerated review timelines compress supplier qualification cycles for microbial formulations. Integrated grain processors in Iowa, Illinois, and Nebraska now mandate strain identification documentation prior to contract inclusion.
Brazil
Organic soybean procurement specifications and cold-chain infrastructure gaps across the Cerrado drive demand for granular soil-incorporated delivery systems. ANVISA regulatory harmonization with EPA microbial safety standards enables parallel filing strategies for fermentation-based suppliers.
Germany
EU REACH residue threshold tightening and EFSA glyphosate metabolite detection programs displace synthetic chemistry in export-oriented supply chains. Bavarian and Baden-Württemberg specialty crop producers anchor botanical formulation penetration through organic-certified distribution channels.
Spain
EFSA import tolerance enforcement and EU Green Deal agricultural transition funding accelerate botanical substitution in Mediterranean fruit and vegetable exports. Andalusian and Valencian cooperative procurement teams specify allelochemical formulations meeting parts-per-billion residue limits.
India
Smallholder resistance management needs and FSSAI organic certification growth create specification pull for microbial inoculum in Punjab and Haryana wheat-rice systems. CDSCO biopesticide registration pathways remain under development, constraining parallel EPA-EMA filing strategies.
Bioherbicides Market Key Industry Players
Premium-margin players sit above commodity-margin players across fermentation capacity and multi-year efficacy database depth. The vendor base stratifies into three tiers: integrated agrochemical conglomerates with captive biological discovery units, mid-scale fermentation specialists supplying consistent inoculum, and botanical extract formulators serving organic-certified channels. Dominant competitive moves include backward integration into active ingredient discovery and municipal rights-of-way contract capture.
Within the fermentation-specialist tier, Certis USA exemplifies infrastructure-heavy positioning through submerged manufacturing scale. Seipasa occupies the botanical-formulation archetype with Southern European supply chain integration. FMC Corporation represents conglomerate-tier competition through in-house discovery capabilities rather than external research dependence.
| Leading Market Players |
|---|
| Certis USA |
| Seipasa |
| FMC Corporation |
| Harpe BioHerbicide Solutions |
| BioWest Ag Solutions |
| Marrone Bio Innovations |
| Corteva |
| Hindustan Bio Tech |
| Emery Oleochemicals |
| Others |
Cost & Logistics Intelligence
Fermentation substrate costs for microbial inoculum production cascade through three distinct pricing tiers downstream, with submerged manufacturing scale separating premium microbial suppliers from standard botanical extractors and economy-tier biochemical blenders across Brazil's Cerrado and the US Plains states.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by EPA registration status and cold-chain infrastructure access. Premium microbial formulations command certification-grade margins where strain identification documentation satisfies integrated grain processor procurement mandates. Price erosion runs through economy-tier biochemical segments as commodity glyphosate pricing compresses substitution economics. Agricultural cooperatives exhibit highest price sensitivity, while municipal rights-of-way contracts show lowest elasticity due to regulatory displacement mandates.
Supply Chain Analysis
EPA FIFRA Section 3(c)(5) registration documentation and EFSA residue compliance certificates gate supplier qualification timelines, compressing vendor pools before commercial negotiations commence. Manufacturing concentrates in the United States, Brazil, and Germany, with submerged fermentation infrastructure anchoring microbial supply and Southern European extraction facilities feeding botanical channels. Raw material dependencies include agricultural substrates, specialized cryogenic preservation media, and allelochemical feedstock from Mediterranean cultivars. Single-source vulnerability concentrates in cryogenic strain banking capacity. Distribution runs through agricultural cooperatives and direct processor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioherbicides function as a stable compounder where regulatory displacement of synthetic chemistries generates persistent specification pull across export-oriented supply chains.
For Market Incumbents: Extend fermentation capacity into Brazil's Cerrado to capture ANVISA-harmonized registration advantages before cold-chain infrastructure matures. Consolidate backward integration into active ingredient discovery to reduce external research partnership dependence. Defensive positioning requires multi-year efficacy databases that satisfy compressed qualification timelines at integrated grain processors. For New Entrants and Emerging Players: EPA FIFRA Section 3(c)(5) in the United States opens a window for microbial strain developers to bypass synthetic chemistry registration timelines. Municipal rights-of-way contracts represent the most penetrable white-space segment given public agency synthetic application restrictions near waterways. Go-to-market execution should anchor in direct technical advisory relationships with crop consultants who influence protocol layering decisions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale innovators lack cryogenic strain banking infrastructure required for long-term culture preservation. Five-to-ten year viability frames favor fermentation specialists with documented manufacturing scale over botanical extractors facing EFSA metabolite detection variability. Acquisition targets should demonstrate parallel EPA-EMA filing capabilities. The signal to watch is ANVISA regulatory harmonization progress that enables Brazilian market entry without duplicative toxicology investment.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Submerged manufacturing scale reduces batch-to-batch efficacy variation for microbial inoculum supply. |
| Parallel Regulatory Filing | EPA-EMA submission alignment minimizes duplicative toxicology investment for strain developers. |
| Municipal Rights-of-Way Capture | Non-crop contracts accelerate adoption velocity where synthetic restrictions apply near waterways. |
| RNAi-Bioherbicide Stack Development | Sequence-specific gene silencing creates defensible intellectual property positions against resistant weeds. |
| Botanical Supply Chain Integration | Southern European organic-certified channels anchor premium positioning under EFSA monitoring programs. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility managers, regulatory affairs specialists at biological pesticide developers, procurement leads at integrated grain processors, and crop consultant advisors with secondary validation against EPA registration databases, ANVISA filing records, EFSA residue monitoring reports, and customs trade data for microbial inoculum shipments. Bottom-up strain-level production estimates triangulated against top-down market sizing from agricultural input expenditure surveys.
Comparable-period anchoring linked historical biopesticide adoption curves to forward projection assumptions across the analysis window. Segmentation dimensions modeled included product type tier, formulation compatibility, application end-use concentration, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves calibrated to resistance management switching velocity. Industry-specific inputs incorporated glyphosate resistance allele frequency data and organic certification growth trajectories.
Revisions become necessary when EPA-EMA regulatory harmonization diverges, ANVISA implementation timelines shift, or RNAi regulatory classification changes materialize. Forecasts reflect documented assumptions about strain banking infrastructure availability and cold-chain distribution maturity. A model refresh is warranted upon material change in EFSA residue threshold enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market