
 Asia-Pacific Bio-Ethanol Market | 2026-2036
Asia-Pacific Bio-Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bio-Ethanol Market Outlook
Market Context
Chinese state-owned ethanol producers is consolidating capacity around corn and cassava processing hubs in Jilin and Henan provinces. Jilin Fuel Ethanol leverages its CNPC parent network to control fuel distribution channels across Northeast China. Henan Tianguan Group sustains feedstock flexibility through integrated wheat and corn sourcing from the North China Plain. Wilmar International dominates Southeast Asian supply through palm oil mill effluent and molasses-based ethanol operations in Indonesia and Malaysia.
Technical Definition and Segments
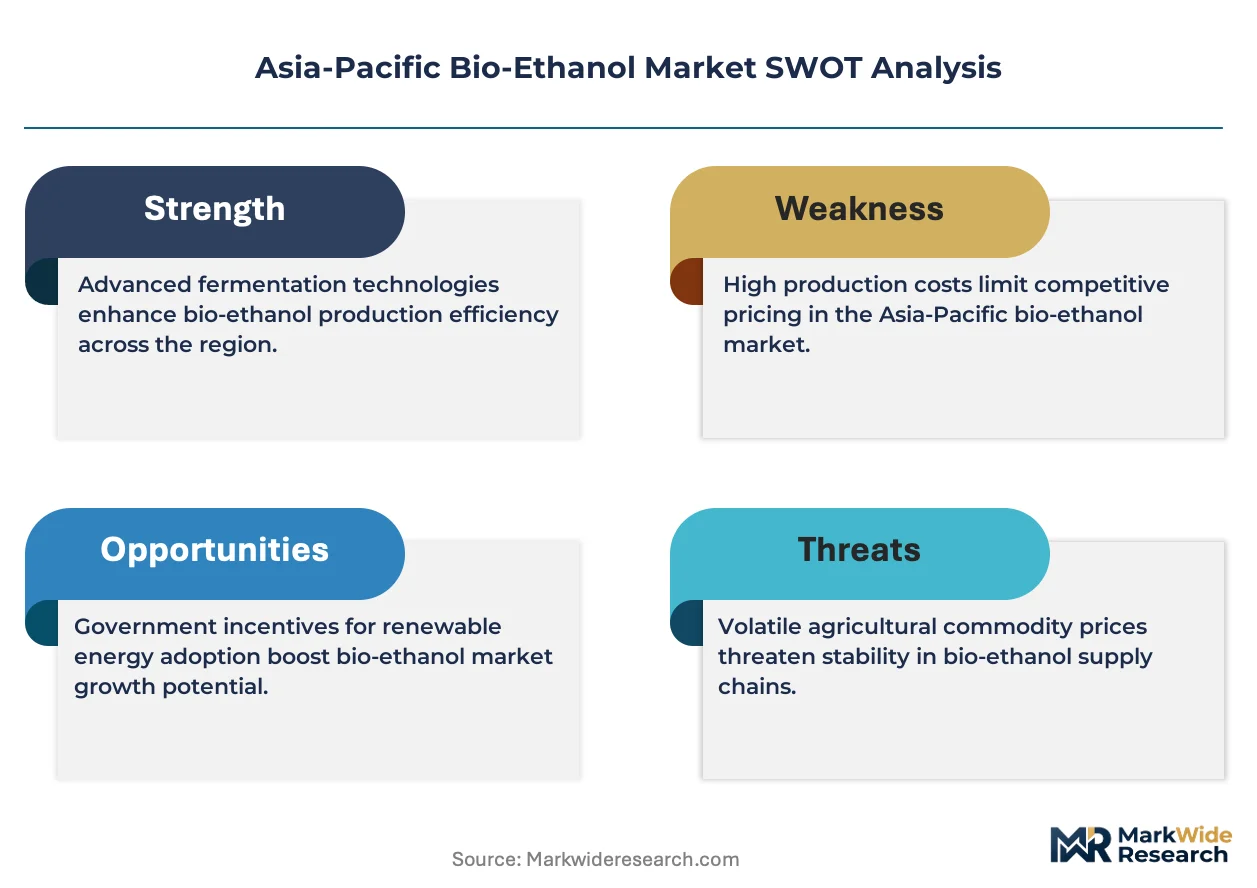
Asia-Pacific bio-ethanol denotes hydrous or anhydrous ethanol derived from biomass fermentation, typically containing 99.5 percent purity for fuel applications and meeting octane enhancement specifications for gasoline blending ratios from E10 to E85. The substance functions primarily as a transportation fuel oxygenate, industrial solvent precursor, and chemical feedstock for ethylene production. Fuel ethanol occupies the largest value pool given mandatory blending policies across India, China, and Southeast Asian markets, while industrial ethanol from cassava feedstock registers the fastest structural expansion due to processing cost advantages in Thailand and Vietnam. Enzymatic hydrolysis technology is gaining share against conventional fermentation as second-generation cellulosic pathways mature, though solid-state fermentation retains margin advantages for small-scale molasses operators.
Regulatory Frame and Outlook
India's Ministry of Petroleum and Natural Gas enforces ethanol blending mandates through the Oil Marketing Companies procurement framework, while China's National Energy Administration coordinates grain-to-ethanol quotas under food security constraints. Thailand's Department of Alternative Energy Development and Efficiency certifies molasses and cassava-derived ethanol for E20 and E85 programs, with BIS standards in India governing fuel quality specifications. Stakeholders must monitor feedstock competition with food security policies, blending mandate enforcement consistency, and carbon intensity accounting methodologies that will determine facility-level competitiveness across the region.
Market Dynamics
The Asia-Pacific bio-ethanol sector is restructuring around feedstock security mandates and fuel blending enforcement, with government procurement quotas now overriding price signals in India and Thailand.
Growth Catalysts
- India's Ethanol Blending Program:The Oil Marketing Companies procurement framework mandates progressive ethanol-gasoline ratios, creating guaranteed offtake for domestic distilleries regardless of international price volatility.
- Cassava Processing Advances:Enzymatic hydrolysis improvements in Thailand and Vietnam are compressing unit conversion costs for root-to-ethanol pathways, expanding viable supply geography.
- Transportation Fuel Oxygenates:Automotive sector demand for octane enhancement specifications is accelerating as regional refining capacity shifts toward lighter crude slates requiring ethanol supplementation.
Market Restraints
- Grain Quota Restrictions:China's National Energy Administration imposes food-security ceilings on corn-to-ethanol capacity, capping expansion in Jilin and Henan processing hubs regardless of fuel demand.
- Molasses Supply Concentration:Southeast Asian ethanol output depends on sugar mill byproduct flows concentrated in Thai and Indonesian plantation belts, exposing processors to cyclical cane harvests.
- Second-Generation Scale Limits:Cellulosic ethanol from agricultural residues remains trapped at pilot scale due to lignin separation energy penalties and enzyme cost structures.
Strategic Opportunities
- Vietnam Feedstock Expansion:Cassava cultivation in the Central Highlands and Mekong Delta offers untapped processing capacity for hydrous ethanol targeting domestic E5 blending and export markets.
- Carbon Intensity Accounting:Emerging lifecycle assessment methodologies for transport fuels create differentiation premiums for low-carbon ethanol pathways certified under evolving national frameworks.
- Palm Oil Mill Effluent Valorization:Malaysian and Indonesian plantation clusters can expand anaerobic digestion-to-ethanol conversion, converting waste streams into fuel-grade output with minimal incremental land use.
Industry Challenges
- Blending Infrastructure Retrofit:Fuel distribution networks across India and Southeast Asia require corrosion-resistant storage and dispensing upgrades to handle hydrous ethanol concentrations above E10.
- Enzyme Supply Security:Cellulase and amylase procurement for advanced processing depends on concentrated global biotechnology suppliers, creating input vulnerability for second-generation project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bio-Ethanol Market |
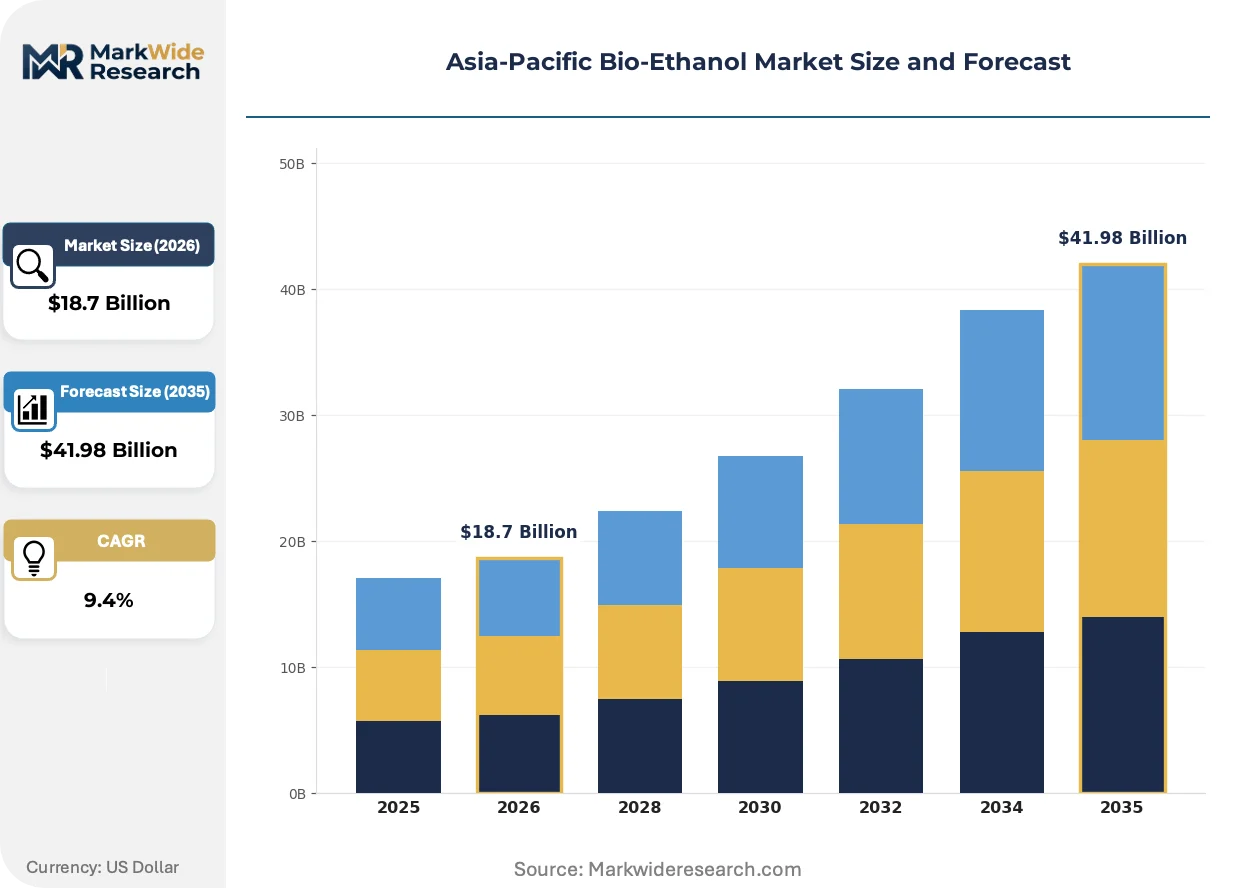
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Ethanol, Industrial Ethanol, Beverage Ethanol, Bioethanol Blends Feedstock: Sugarcane, Corn, Wheat, Cassava End Use: Transportation, Industrial, Food & Beverage, Pharmaceuticals Technology: Fermentation, Gasification, Solid-State Fermentation, Enzymatic Hydrolysis |
| Companies Covered | Jilin Fuel Ethanol Co. Ltd (CNPC), Henan Tianguan Group Co. Ltd, Wilmar International, POET, LLC., Valero, ADM, Green Plains Inc., Neste Corporation, Bharat Petroleum, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bio-Ethanol Market Strategic Shifts
Processing technology and regulatory accounting standards are converging to reward feedstock-flexible operations while penalizing carbon-intensive legacy pathways across the Asia-Pacific fuel ethanol complex.
Cellulosic pretreatment systems using steam explosion and dilute acid hydrolysis are rewriting the cost structure for agricultural residue conversion. Thai and Chinese project developers are piloting integrated biorefinery configurations that co-produce ethanol, lignin pellets, and C5 sugar streams. This technology is compressing the capital intensity gap between first and second-generation pathways.
India's Bureau of Indian Standards has tightened fuel ethanol quality specifications for water content and acidity, forcing distilleries to upgrade dehydration and purification trains. The BIS amendments affect molasses and grain-based suppliers differently, with cassava operators in the Northeast and Deccan regions facing steeper compliance investments than established sugar-integrated producers.
Fleet operators and fuel retailers are consolidating procurement around certified low-carbon ethanol with verifiable feedstock provenance. Indian state transport corporations and Thai logistics fleets now specify documented chain-of-custody from cultivation to blending terminal. This preference shift concentrates contract volumes with integrated agricultural processors in Maharashtra, Uttar Pradesh, and Nakhon Ratchasima provinces.
Asia-Pacific Bio-Ethanol Market Segmentation
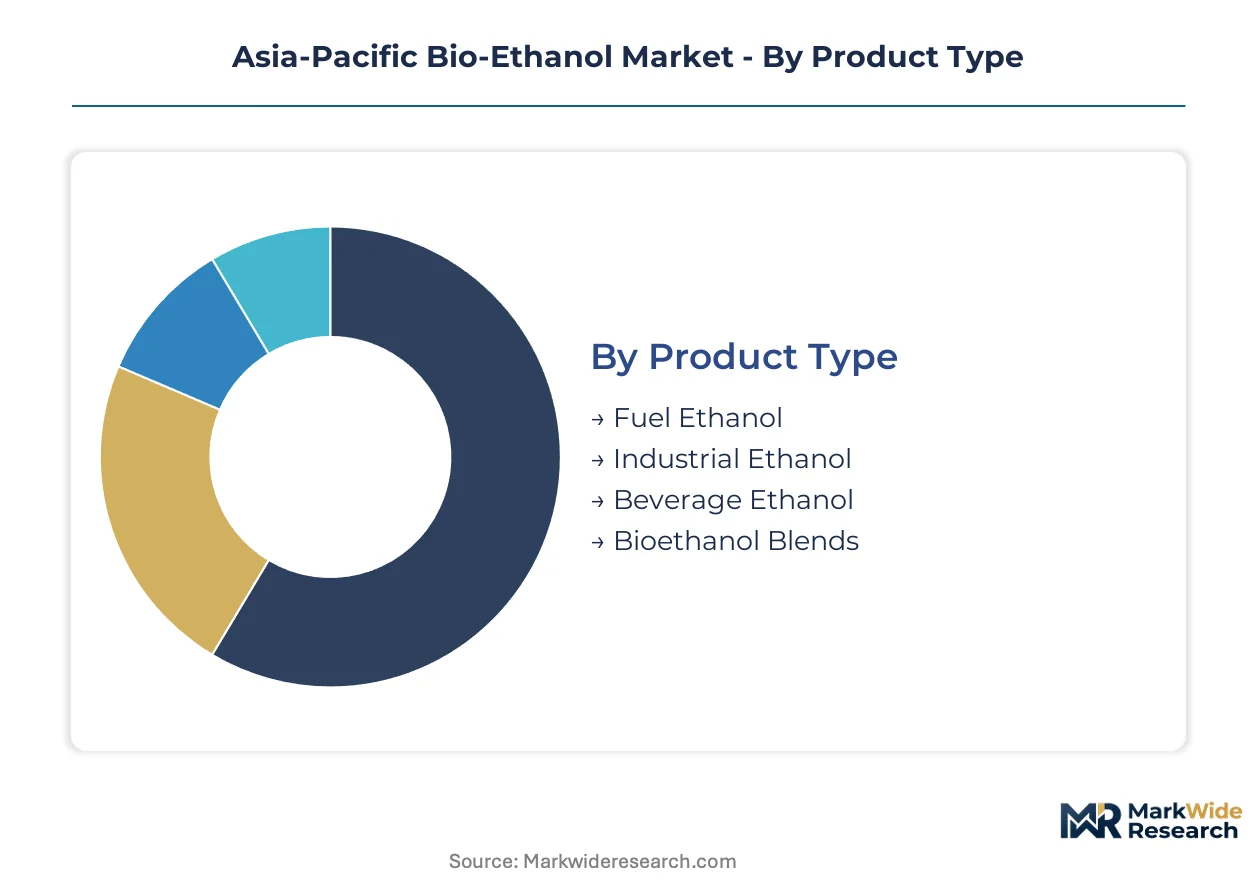
Segmentation in the Asia-Pacific bio-ethanol market reveals how regulatory frameworks and feedstock economics allocate value across distinct production pathways. Each category carries specific certification burdens and supply chain configurations that determine facility-level competitiveness.
Product Type:
Fuel ethanol carries the heaviest certification load under India's BIS specifications and Thailand's Department of Alternative Energy Development and Efficiency protocols, while industrial ethanol faces lighter purity requirements but stricter solvent-grade documentation.
- Fuel Ethanol:Anhydrous ethanol meeting 99.5 percent purity specifications for gasoline blending ratios from E10 to E85. Demand concentrates in India's Oil Marketing Companies procurement framework and Thailand's E20/E85 programs, driven by mandatory blending enforcement regardless of international price volatility.
- Industrial Ethanol:Hydrous ethanol serving as chemical feedstock for ethylene production and solvent applications. Maharashtra and Uttar Pradesh distilleries supply India's pharmaceutical and coatings sectors, constrained by BIS water content and acidity amendments requiring dehydration train upgrades.
- Beverage Ethanol:Extra-neutral alcohol meeting food-grade fermentation standards. Thai and Indian sugar-integrated producers dominate supply through molasses-based pathways.
- Bioethanol Blends:Pre-mixed formulations for direct retail dispensing. Malaysian and Indonesian palm oil mill effluent operations supply niche industrial heating markets.
Fuel ethanol sits at the top of the volume ranking, with industrial ethanol climbing the fastest on cassava processing cost advantages in Vietnam and Thailand.
Feedstock:
Feedstock selection determines margin structure through regional agricultural economics and food security policy boundaries.
- Sugarcane:Molasses-derived ethanol from Thai and Indonesian plantation belts supplies established sugar-integrated distilleries. Cyclical cane harvests expose processors to supply interruptions.
- Corn:Grain-to-ethanol capacity concentrates in Jilin and Henan provinces under China's National Energy Administration quotas. Food security ceilings cap expansion regardless of fuel demand signals.
- Wheat:North China Plain sourcing sustains Henan Tianguan Group's feedstock flexibility through integrated procurement networks.
- Cassava:Root-to-ethanol pathways in Thailand and Vietnam benefit from enzymatic hydrolysis improvements compressing unit conversion costs. Central Highlands and Mekong Delta cultivation offers untapped processing capacity.
Cassava is gaining share fastest on processing technology advances, while sugarcane maintains the largest existing supply base.
End Use:
End-use segmentation tracks how oxygenate demand splits between mandatory transportation blending and discretionary industrial consumption.
- Transportation:Automotive sector oxygenate demand accelerates as regional refining shifts toward lighter crude slates requiring ethanol supplementation. Indian state transport corporations and Thai logistics fleets now specify documented chain-of-custody certification.
- Industrial:Chemical feedstock and solvent precursor applications concentrate in Maharashtra pharmaceutical clusters and coatings manufacturing.
- Food & Beverage:Extra-neutral alcohol for spirits production flows through Thai sugar-integrated channels and Indian molasses distilleries.
- Pharmaceuticals:High-purity ethanol for drug formulation faces stringent CDSCO and Thai FDA documentation requirements.
Transportation dominates volume, with industrial applications expanding most quickly on ethylene production demand.
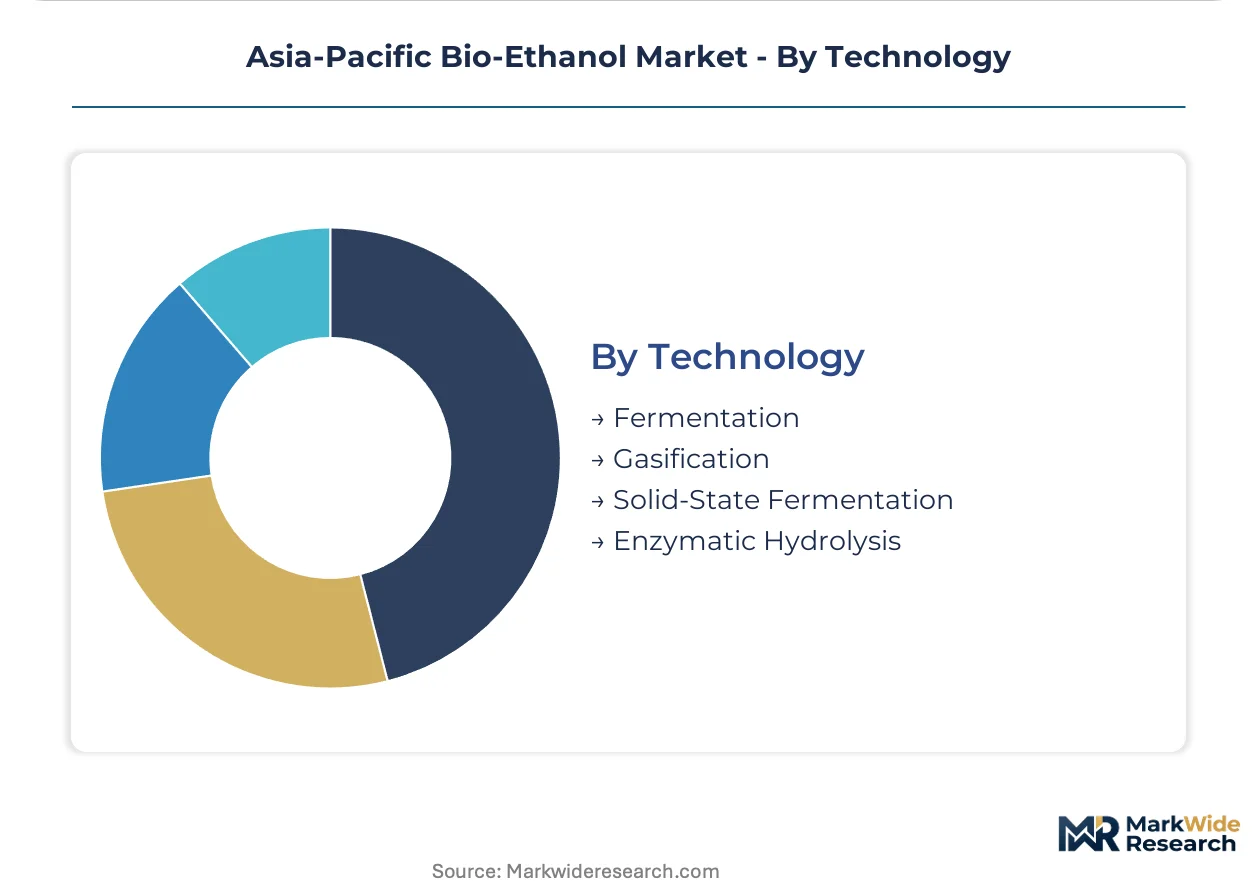
Technology:
Technology pathways differentiate through capital intensity and enzyme supply security vulnerabilities.
- Fermentation:Conventional yeast-based conversion of simple sugars dominates molasses and grain processing. Established operations in Jilin and Uttar Pradesh benefit from depreciated capital bases.
- Gasification:Thermochemical conversion of lignocellulosic biomass remains at pilot scale due to syngas cleanup cost structures.
- Solid-State Fermentation:Low-moisture processing retains margin advantages for small-scale molasses operators in Thai plantation belts.
- Enzymatic Hydrolysis:Cellulase and amylase-based conversion of starch and cellulosic feedstocks. Thai and Chinese developers pilot integrated biorefinery configurations co-producing ethanol, lignin pellets, and C5 sugar streams.
Fermentation holds the largest installed base, while enzymatic hydrolysis shows the steepest expansion trajectory on second-generation pathway maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with lower compliance burdens and guaranteed offtake frameworks, concentrating capacity in India and Thailand where blending mandates override price volatility. Regulatory arbitrage favors cassava-processing zones over grain-restricted hubs.
India
Oil Marketing Companies procurement guarantees anchor demand for domestic distilleries across Maharashtra and Uttar Pradesh. The Ministry of Petroleum and Natural Gas enforces progressive ethanol-gasoline blending ratios regardless of international price signals. State transport corporations in Maharashtra now specify documented chain-of-custody certification for fleet fuel procurement.
China
Food-security ceilings cap corn-to-ethanol expansion in Jilin and Henan provinces despite fuel demand signals. The National Energy Administration coordinates grain-to-ethanol quotas under dual carbon goals and agricultural policy constraints. Jilin Fuel Ethanol leverages CNPC parent network distribution across Northeast China processing clusters.
Thailand
E20 and E85 program mandates sustain molasses and cassava-derived ethanol demand through the Department of Alternative Energy Development and Efficiency certification framework. Enzymatic hydrolysis improvements compress unit conversion costs for root-to-ethanol pathways. Nakhon Ratchasima province hosts integrated agricultural processors serving certified low-carbon procurement specifications.
Vietnam
Untapped cassava cultivation in the Central Highlands and Mekong Delta offers expansion capacity for hydrous ethanol targeting domestic E5 blending. Feedstock cost advantages attract processing investment absent mature regulatory frameworks. Developers pilot integrated biorefinery configurations co-producing ethanol and lignin pellets.
Indonesia
Palm oil mill effluent valorization converts plantation waste streams into fuel-grade output with minimal incremental land use. Malaysian and Indonesian clusters expand anaerobic digestion-to-ethanol conversion under emerging lifecycle assessment methodologies. Wilmar International operations anchor Southeast Asian supply through molasses-based channels.
Asia-Pacific Bio-Ethanol Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue feedstock-flexible configurations and carbon intensity certification. State-owned and agribusiness-integrated players dominate procurement relationships with mandatory blending programs. Two archetypes prevail: grain-quota-constrained national champions and plantation-integrated Southeast Asian operators. Competitive moves concentrate on capacity expansion in Vietnam and cassava technology licensing partnerships.
Among China-based state-owned enterprises, Jilin Fuel Ethanol Co. Ltd (CNPC) and Henan Tianguan Group Co. Ltd exemplify the grain-quota-constrained national champion archetype. Wilmar International occupies a position within the plantation-integrated Southeast Asian operator tier. These three entities anchor the competitive structure across the region's dominant production geographies.
| Leading Market Players |
|---|
| Jilin Fuel Ethanol Co. Ltd (CNPC) |
| Henan Tianguan Group Co. Ltd |
| Wilmar International |
| POET, LLC. |
| Valero |
| ADM |
| Green Plains Inc. |
| Neste Corporation |
| Bharat Petroleum |
| Others |
Value Chain & Pricing Dynamics
Oil Marketing Companies procurement concentration in India anchors contract-based long-term offtake pricing across the Asia-Pacific fuel ethanol complex. Blending mandate enforcement overrides spot market volatility, compressing margin negotiation space for distilleries serving mandatory programs.
Pricing Analysis
Distributor margins for fuel-grade ethanol compress under India's Oil Marketing Companies procurement framework, which enforces standardized offtake terms regardless of feedstock cost fluctuations. Three-tier pricing structure across certified low-carbon, standard BIS-compliant, and unverified economy grades differentiates ethanol streams, with carbon intensity accounting driving premium tier separation. Cost compression in cassava-based supply is intensifying because enzymatic hydrolysis improvements in Thailand and Vietnam expand viable production geography. State transport corporations exhibit lowest price sensitivity due to documented chain-of-custody mandates, while independent industrial solvent buyers remain most responsive to hydrous ethanol spot differentials.
Supply Chain Analysis
Regional distribution centers in Maharashtra and Uttar Pradesh anchor hub-and-spoke patterns for Indian fuel ethanol, with rail-fed terminals extending procurement reach into Northeast processing clusters. Geographic supply concentrates in India, Thailand, and Vietnam, with Jilin and Henan provinces operating under China's National Energy Administration grain quotas. Raw material flows draw from molasses byproduct streams, cassava root harvests, and corn procurement networks. Single-source vulnerability in cellulase and amylase supply creates input security risks for enzymatic hydrolysis operators. Distribution runs through state-owned petroleum marketing company terminals, with corrosion-resistant storage retrofits required for hydrous concentrations above E10.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific bio-ethanol market represents a late-cycle quality story as fleet operators and fuel retailers consolidate procurement around certified low-carbon ethanol with verifiable feedstock provenance.
For Market Incumbents: Acquire cassava processing technology licenses to secure feedstock-flexible capacity expansion in Vietnam's Central Highlands and Mekong Delta. Integrate backward into plantation operations across Nakhon Ratchasima province to guarantee documented chain-of-custody certification for state transport corporation contracts. Carbon intensity accounting methodologies threaten margin position for legacy molasses operators lacking verified low-carbon pathways. For New Entrants and Emerging Players: Enter via Vietnam's E5 blending program, where regulatory frameworks remain immature and feedstock cost advantages attract processing investment absent entrenched incumbent relationships. Target industrial ethanol supply to Maharashtra pharmaceutical clusters, where BIS water content amendments force dehydration train upgrades among established distilleries. Partner with Thai enzymatic hydrolysis technology developers for integrated biorefinery licensing. For Investors and Strategic Acquirers: Plantation-integrated Southeast Asian operators are the most active acquirer in this space, consolidating molasses and palm oil mill effluent processing capacity under Wilmar International's supply architecture. Long-term viability over the five-to-ten year window hinges on carbon intensity certification premiums and feedstock security beyond grain-restricted Chinese hubs. Watch for enforcement consistency in India's progressive blending mandates as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cassava Processing Technology Licensing | Thai and Vietnamese developers compress unit conversion costs for root-to-ethanol pathways. |
| Integrated Biorefinery Configuration | Co-production of ethanol, lignin pellets, and C5 sugar streams rewrites capital intensity economics. |
| Carbon Intensity Certification Investment | BIS and Department of Alternative Energy Development and Efficiency protocols reward verified low-carbon pathways. |
| Backward Integration into Plantation Operations | Nakhon Ratchasima and Central Highlands cultivation secures documented chain-of-custody for fleet procurement. |
| Corrosion-Resistant Storage Infrastructure Retrofit | Fuel distribution networks require upgraded terminals to handle hydrous ethanol concentrations above E10. |
Study Parameters
Multiple input streams — regulatory filings with India's Ministry of Petroleum and Natural Gas and Thailand's Department of Alternative Energy Development and Efficiency, trade customs data for molasses and cassava feedstock flows, and capacity announcements from Jilin and Henan processing hubs — were reconciled through bottom-up and top-down triangulation. Primary interviews with distillery operations managers, Oil Marketing Companies procurement officers, enzymatic hydrolysis technology providers, and plantation-integrated agribusiness executives were validated against secondary sources including BIS standard amendments, National Energy Administration grain quota circulars, and integrated biorefinery project disclosures.
Historical capacity utilization and blending mandate enforcement patterns were cross-referenced against expert panel inputs from fuel distribution infrastructure specialists and carbon accounting methodology developers. The analytical framework models segmentation across fuel versus industrial ethanol grades, cassava versus molasses versus corn feedstock pathways, and enzymatic hydrolysis versus conventional fermentation technology tiers. CAGRs were derived from facility-level cost structures and procurement quota trajectories, incorporating enzyme supply security premiums and dehydration train upgrade capital requirements as industry-specific forecast inputs across the projection horizon.
The model holds under consistent blending mandate enforcement and stable feedstock harvest conditions; deviation in cellulase supply disruptions or food security policy tightening would shift capacity expansion trajectories. Forecasts reflect documented assumption sets around regulatory continuity and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Africa Biostimulants Market