
 India Biofertilizer Market | 2026-2036
India Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
India Biofertilizer Market Insights
Project finance tied to farmer producer organization (FPO) procurement contracts is tilting competitive access toward entities with balance-sheet scale. National Fertilizers Limited leverages its pan-India dealership network to sustain last-mile distribution in Bihar and Uttar Pradesh. Gujarat State Fertilizers & Chemicals Ltd anchors production capacity through in-house fermentation infrastructure at its Vadodara complex. IPL Biologicals Limited specializes in consortia-based formulations that differentiate on colony-forming unit stability.
Biofertilizers comprise living microbial preparations containing bacteria, fungi, or algae that colonize the rhizosphere or plant interior to fix atmospheric nitrogen, solubilize mineral phosphates, or mobilize potassium through organic acid secretion, with standard specifications requiring minimum viable counts of 10^8 CFU per gram at manufacture. Their primary industrial purpose is to reduce synthetic nitrogenous fertilizer dependency in intensive cereal-legume rotations while maintaining soil microbial biomass carbon. Nitrogen-fixing rhizobium and azotobacter strains dominate volume offtake across the Indo-Gangetic wheat belt, though mycorrhizal formulations command premium positioning in horticulture export zones where phosphorus use efficiency directly determines compliance with residue thresholds. Seed treatment and soil application modes together absorb the majority of product flows, with drip-compatible liquid formulations representing the fastest-adjusting channel as micro-irrigation expands under the Pradhan Mantri Krishi Sinchayee Yojana.
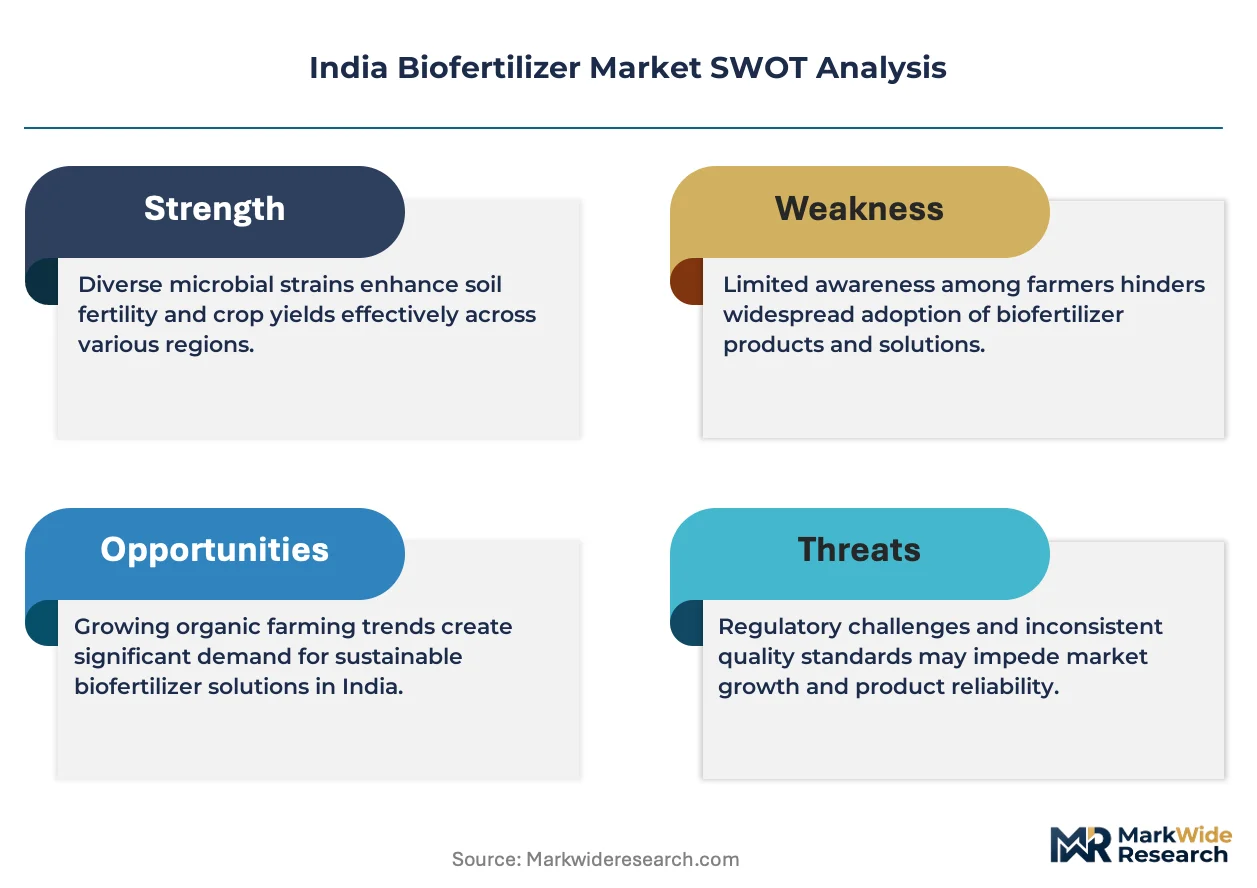
The Fertiliser Control Order under the Ministry of Agriculture mandates BIS certification and quality control protocols for all marketed microbial inoculants, while the Food Safety and Standards Authority of India enforces residue limits that indirectly channel growers toward certified organic inputs. State agricultural departments in Gujarat, Maharashtra, and Tamil Nadu operate parallel subsidy structures that condition reimbursement on FCO-compliant product procurement. Stakeholders must monitor how the proposed National Mission on Natural Farming recalibrates procurement priorities between single-strain and multi-microbial consortia.
Market Dynamics
Paramparagat Krishi Vikas Yojana subsidy disbursement is concentrating procurement authority within farmer producer organizations, forcing manufacturers to restructure distribution from state depots to FPO-anchored consignment models. This shift rewards entities with working capital depth and penalizes small-batch fermenters lacking invoice discounting relationships.
Growth Catalysts
- FCO Standard Revision:The Ministry of Agriculture's tightened BIS certification protocols are filtering out substandard inoculants, creating shelf space for quality-compliant consortia formulations in state tender pipelines.
- Pulse Belt Expansion:Madhya Pradesh and Maharashtra are absorbing rising rhizobium volumes as soybean and pigeon-pea acreage displaces water-intensive cereals under micro-irrigation mandates.
- Micro-irrigation Convergence:Pradhan Mantri Krishi Sinchayee Yojana drip infrastructure is accelerating liquid biofertilizer adoption through fertigation compatibility, bypassing traditional seed-treatment logistics.
Market Restraints
- Molasses Price Volatility:Fermentation feedstock costs swing with sugarcane crush cycles, compressing gross margins for standalone biological units lacking distillery backward integration.
- Cold Chain Deficits:Viability loss during last-mile transport in Bihar and eastern Uttar Pradesh limits shelf-life guarantees, constraining market development beyond state capital hubs.
- Synthetic Nitrogen Substitution Economics:Urea remains price-controlled under the New Urea Policy, perpetuating a 4-6x cost gap per unit nitrogen that biofertilizers cannot bridge without subsidy stacking.
Strategic Opportunities
- North-East Penetration:Assam and Meghalaya organic mission schemes remain undersupplied, offering first-mover positioning for consortia producers willing to establish Guwahati warehousing.
- Horticulture Export Zones:Maharashtra grape and Karnataka pomegranate belts require mycorrhizal phosphorus solubilizers to meet FSSAI residue thresholds for EU-bound shipments.
- Direct-to-FPO Digital Channels:State agricultural department e-procurement portals are disintermediating traditional dealer networks, rewarding manufacturers with API-integrated inventory management systems.
Industry Challenges
- Microbiologist Talent Scarcity:Strain characterization and quality control functions require PhD-level expertise that rural fermentation facilities struggle to attract against pharmaceutical sector compensation.
- Consortia Stability Validation:Multi-strain formulation shelf-life testing under varying temperature regimes extends CDSCO-style bio-efficacy timelines, delaying product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biofertilizer Market |
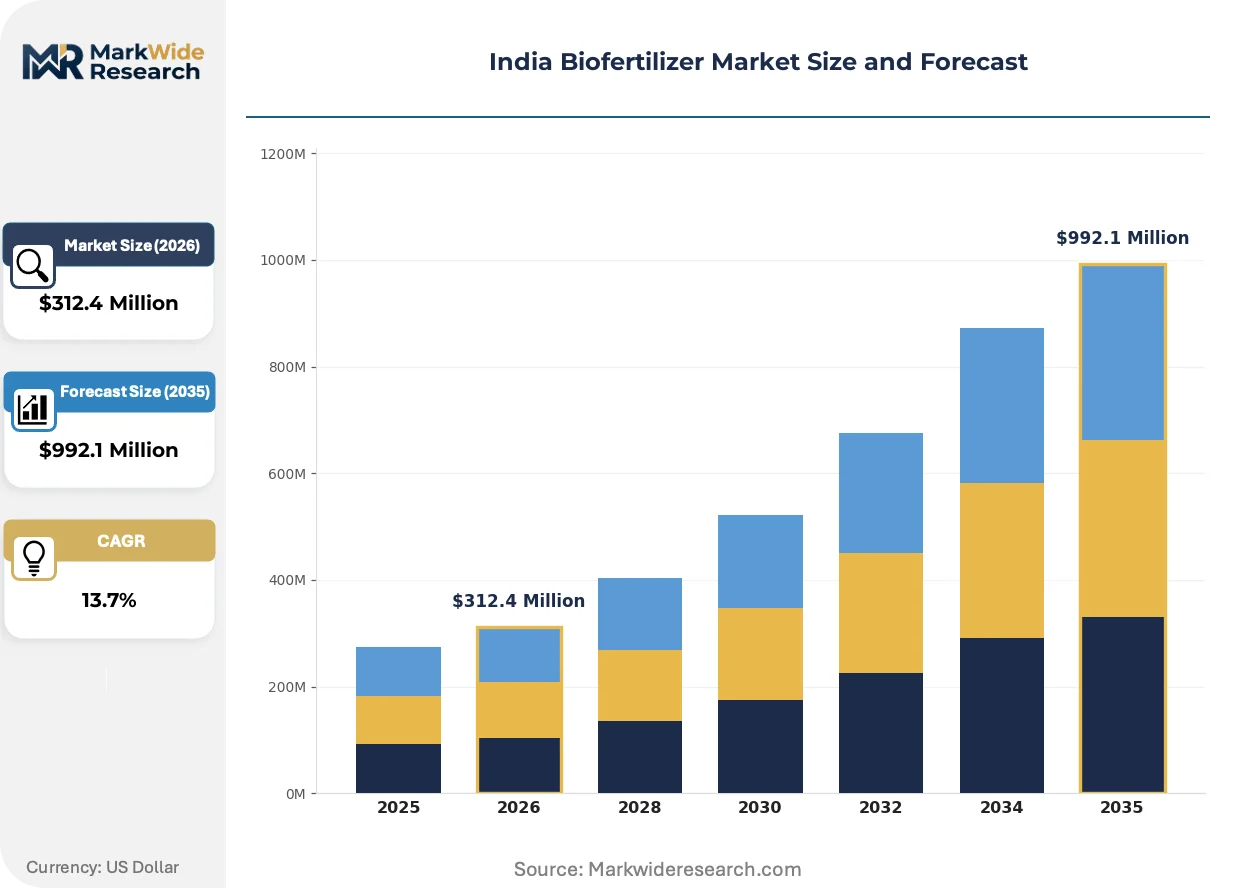
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $992.1 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen Fixing, Phosphate Solubilizing, Potassium Solubilizing, Mycorrhiza End User: Agriculture, Horticulture, Organic Farming, Greenhouse Mode of Application: Soil Application, Seed Treatment, Foliar Spray, Drip Irrigation Packaging Type: Bulk Bags, Sachets, Bottles, Pouches |
| Companies Covered | National Fertilizers Limited, Gujarat State Fertilizers & Chemicals Ltd, Indian Farmers Fertiliser Cooperative Limited, IPL Biologicals Limited, UPL Limited, T. Stanes and Company Limited, Madras Fertilizers Limited, Biostadt India Limited, AgriLife, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biofertilizer Market Trends and Innovations
Liquid consortia formulations are displacing carrier-based powders across the Indo-Gangetic wheat belt, driven by drip-irrigation penetration and seed-treatment labor shortages. This format shift is compressing packaging costs while raising cold-chain infrastructure requirements.
Consortia-based inoculants containing nitrogen-fixing, phosphate-solubilizing, and potassium-mobilizing strains are hybridizing into single-application products. Gujarat horticulture exporters and Punjab wheat cooperatives are adopting these triple-function formulations at 2-3x the pace of single-strain alternatives. The technology is hybridizing competitive positioning around CFU stability guarantees rather than strain count alone, forcing R&D investment toward encapsulation and cryoprotectant systems.
The proposed National Mission on Natural Farming is recalibrating subsidy eligibility toward certified organic input procurement. State agricultural departments in Tamil Nadu and Karnataka are pre-qualifying consortia products for preferential reimbursement, compressing single-strain azotobacter margins. Wheat-rice system transitions in Haryana are absorbing the policy impact fastest, with panchayat-level procurement committees mandating FCO-compliant multi-microbial sourcing.
Farmer producer organizations are consolidating input purchasing through state e-procurement portals, disintermediating the dealer network that historically absorbed 35-40% of manufacturer margins. Maharashtra and Madhya Pradesh FPOs are negotiating annual volume contracts with direct manufacturer fulfillment, bypassing district cooperative societies. This channel shift is most visible in soybean-growing districts of Marathwada, where FPOs now control 60% of rhizobium offtake.
India Biofertilizer Market Segmentation
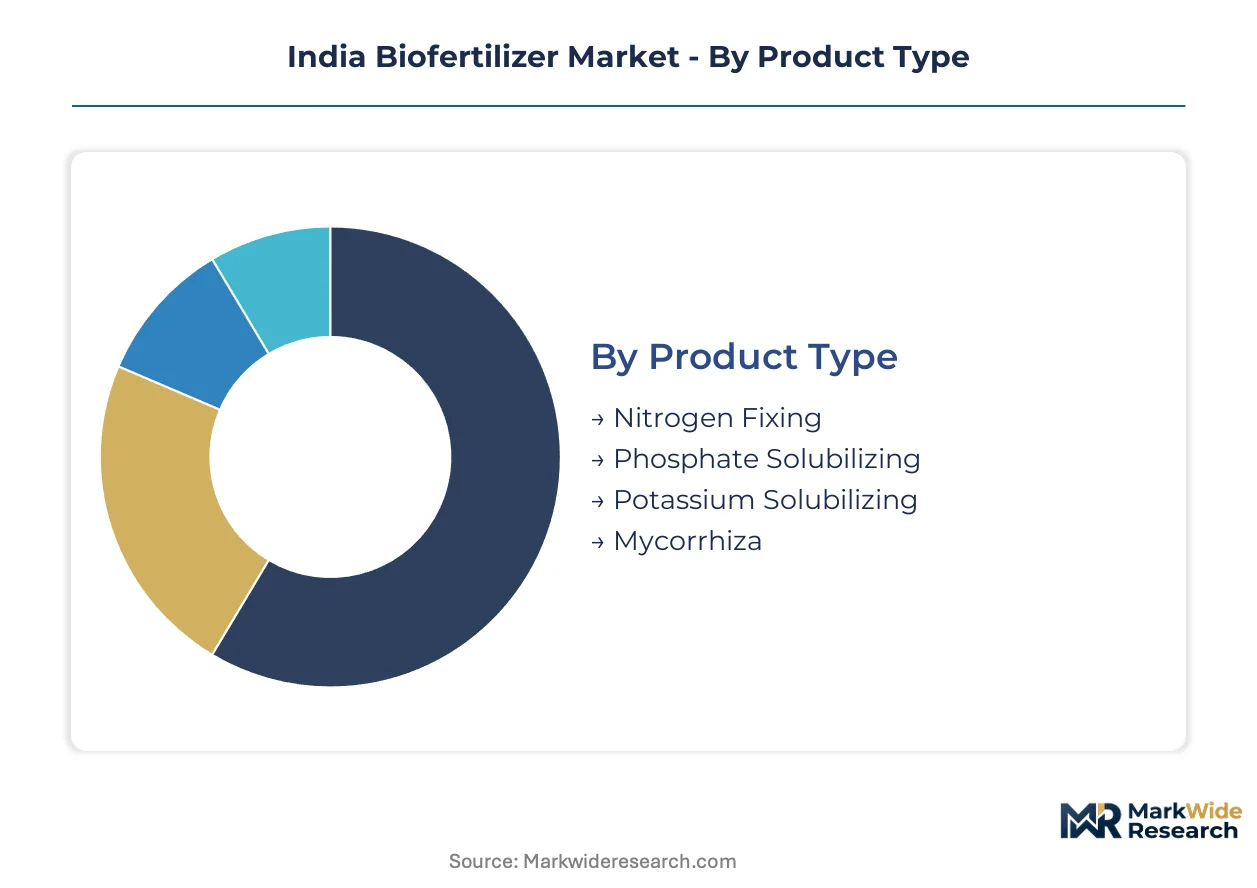
Segmentation in the India biofertilizer market tracks how microbial functionality, cropping system requirements, and logistics infrastructure intersect. Each dimension reveals distinct procurement patterns and margin structures that manufacturers must navigate.
Product Type:
Mature nitrogen-fixing formulations dominate volume flows, while emerging multi-functional consortia reshape premium positioning.
- Nitrogen Fixing:Rhizobium and azotobacter preparations contain 10^8 CFU per gram minimum viable counts for atmospheric nitrogen fixation. Pulse cultivation in Madhya Pradesh and Maharashtra absorbs rising volumes as soybean and pigeon-pea acreage expands under micro-irrigation mandates.
- Phosphate Solubilizing:Bacillus and Pseudomonas strains secrete organic acids to mobilize bound phosphorus. Wheat-rice systems across Haryana and Punjab transition toward integrated nutrient management, driving consortia adoption that pairs phosphate solubilizers with nitrogen fixers.
- Potassium Solubilizing:Frateuria aurantia-based formulations release potassium from silicate minerals through acidification.
- Mycorrhiza:Arbuscular mycorrhizal fungi colonize root cortical cells to extend phosphorus absorption networks. Grape and pomegranate belts in Maharashtra and Karnataka command premium positioning for EU-bound export compliance.
Nitrogen-fixing products handle the majority of throughput; mycorrhiza formulations are expanding most quickly on share.
End User:
Cost tier differentiation separates subsidy-dependent cereal systems from premium horticulture export zones.
- Agriculture:Cereal-legume rotations across the Indo-Gangetic Plains constitute the foundational demand base. Wheat and rice farmers under Paramparagat Krishi Vikas Yojana procurement shift toward certified organic inputs.
- Horticulture:High-value fruit and vegetable operations require residue-compliant phosphorus management for export certification. Maharashtra grape growers and Karnataka pomegranate clusters absorb mycorrhizal formulations at 2-3x the intensity of field crop applications.
- Organic Farming:Certified operations under FCO-compliant standards mandate microbial input documentation for premium market access.
- Greenhouse:Controlled-environment agriculture in Gujarat and Tamil Nadu deploys drip-compatible liquid formulations for precision nutrient delivery.
Agriculture absorbs the largest volume base; horticulture delivers the steepest margin expansion.
Mode of Application:
Volume concentration in traditional methods collides with infrastructure-driven format shifts.
- Soil Application:Direct field broadcasting of carrier-based powders remains prevalent in Bihar and eastern Uttar Pradesh where cold chain deficits constrain liquid alternatives.
- Seed Treatment:On-farm microbial coating of sowing material dominates smallholder operations. Labor shortages across the Indo-Gangetic belt accelerate demand for pre-treated certified seed.
- Foliar Spray:Aerial microbial application targets micronutrient deficiency correction in standing crops.
- Drip Irrigation:Liquid consortia formulations integrate with fertigation infrastructure under Pradhan Mantri Krishi Sinchayee Yojana expansion. This channel is climbing the fastest as micro-irrigation penetration displaces seed-treatment logistics in Gujarat and Haryana.
Soil application and seed treatment together absorb dominant share; drip irrigation is gaining share fastest.
Packaging Type:
Supply concentration in bulk formats diverges from last-mile fragmentation in small-unit distribution.
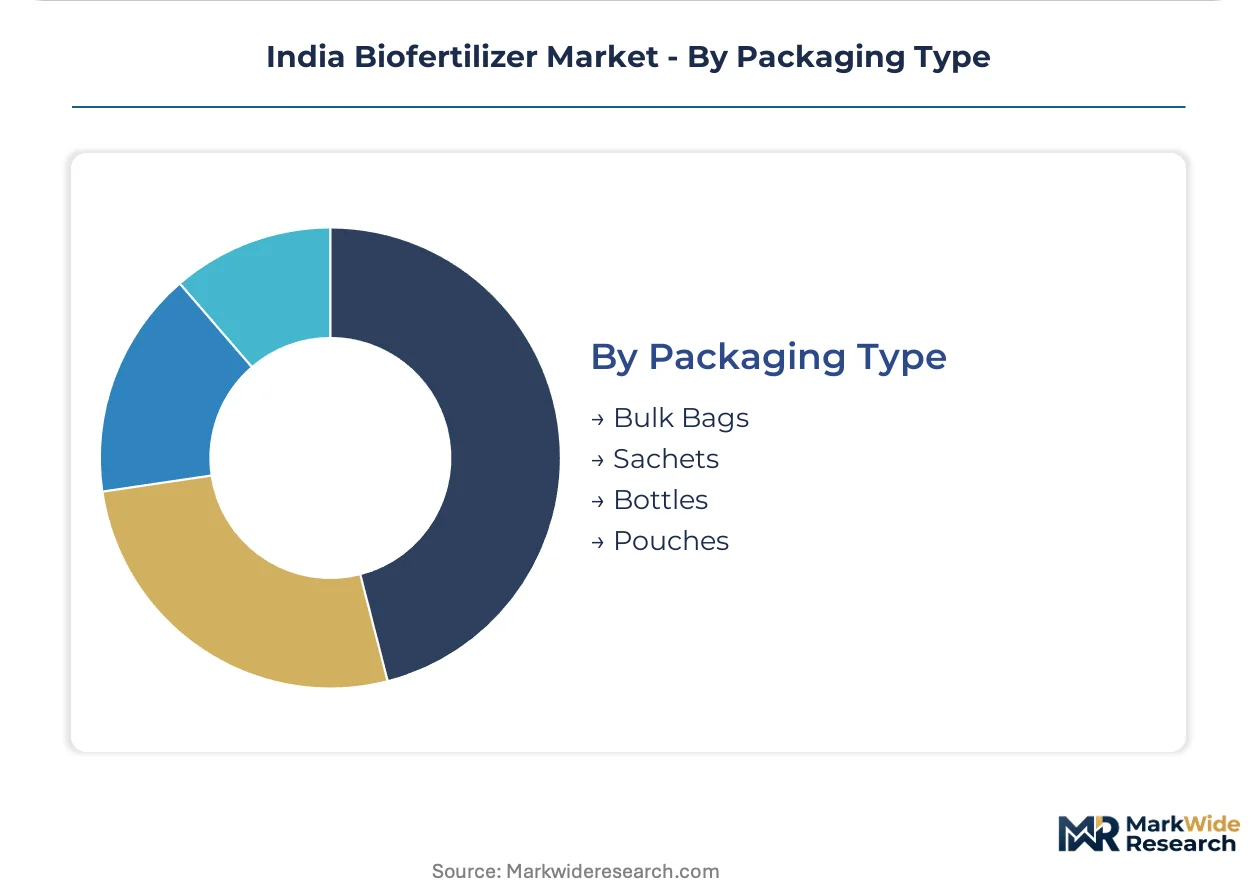
- Bulk Bags:Institutional procurement by farmer producer organizations and state agricultural departments favors 25-50 kg units for warehouse consolidation. FPO-anchored consignment models in Maharashtra and Madhya Pradesh drive this format's expansion.
- Sachets:Single-dose 200-gram packets target smallholder seed-treatment operations with precise application rates.
- Bottles:Liquid formulation containment for drip irrigation and foliar spray applications requires UV-stabilized HDPE with extended shelf-life guarantees.
- Pouches:Flexible laminate packaging reduces freight cost for remote distribution in Assam and Meghalaya organic mission zones.
Bulk bags move the largest tonnage; bottles are expanding most quickly on format share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paramparagat Krishi Vikas Yojana subsidy disbursement is redirecting procurement flows toward farmer producer organizations across state boundaries. Micro-irrigation expansion under Pradhan Mantri Krishi Sinchayee Yojana is reshaping product format preferences regionally.
Maharashtra
Soybean and pigeon-pea cultivation in Marathwada is absorbing rising rhizobium volumes as pulse acreage displaces water-intensive cereals. State agricultural department e-procurement portals are disintermediating traditional dealer networks in favor of FPO-anchored consignment models. The grape belt around Nashik commands premium mycorrhizal formulations for EU-bound export compliance with FSSAI residue thresholds.
Gujarat
Horticulture export zones in the Saurashtra region require phosphorus solubilizers to meet international certification standards. GSFC's Vadodara fermentation complex anchors production capacity with in-house molasses processing infrastructure. Drip-irrigation penetration under state micro-irrigation missions is accelerating liquid biofertilizer adoption through fertigation compatibility.
Madhya Pradesh
The Malwa plateau pulse belt is recording the fastest rhizobium volume growth as soybean cultivation expands under crop diversification mandates. State subsidy structures condition reimbursement on FCO-compliant product procurement from BIS-certified manufacturers. Indore-based warehousing hubs are consolidating distribution for eastern districts lacking cold-chain infrastructure.
Karnataka
Pomegranate clusters around Bijapur and Bagalkot are absorbing mycorrhizal formulations at intensities 2-3x field crop applications for export market access. The state's organic mission schemes in pre-qualifying consortia products for preferential reimbursement are compressing single-strain margins. Bengaluru's agri-tech corridor is incubating direct-to-FPO digital procurement platforms.
Haryana
Wheat-rice system transitions in the Indo-Gangetic belt are absorbing integrated nutrient management inputs fastest among northern states. Panchayat-level procurement committees are mandating FCO-compliant multi-microbial sourcing under revised subsidy guidelines. Karnal and Hisar agricultural universities are anchoring strain validation partnerships with commercial fermenters.
India Biofertilizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. National Fertilizers Limited leverages pan-India dealership networks to sustain last-mile distribution in subsidy-dependent markets. State-owned enterprises anchor volume through depot-based procurement pipelines, while biological specialists differentiate on consortia formulation stability. Competitive moves center on backward integration into fermentation feedstock and API-integrated inventory management for e-procurement portals.
Among public-sector incumbents, National Fertilizers Limited and Gujarat State Fertilizers & Chemicals Ltd exemplify channel-control archetypes with established state depot relationships. IPL Biologicals Limited occupies a specialist position representing the consortia-formulation tier focused on colony-forming unit stability guarantees. These three entities span the competitive spectrum from scale-driven distribution to technical differentiation in multi-strain products.
| Leading Market Players |
|---|
| National Fertilizers Limited |
| Gujarat State Fertilizers & Chemicals Ltd |
| Indian Farmers Fertiliser Cooperative Limited |
| IPL Biologicals Limited |
| UPL Limited |
| T. Stanes and Company Limited |
| Madras Fertilizers Limited |
| Biostadt India Limited |
| AgriLife |
| Others |
Pricing and Supply Chain Analysis
Molasses supply from Maharashtra and Uttar Pradesh sugar belt concentration anchors fermentation feedstock costs, directing margin pools toward manufacturers with distillery backward integration rather than standalone biological units exposed to crush cycle volatility.
Pricing Analysis
FCO certification grade creates the primary spread between BIS-validated consortia formulations and uncertified single-strain alternatives. Three-tier pricing structure separates premium mycorrhizal products for export horticulture from standard nitrogen-fixing powders and economy-grade carrier-based formulations. Pricing pressure stems from urea price controls under the New Urea Policy perpetuating a 4-6x cost gap per unit nitrogen. Smallholder cereal farmers in Bihar and eastern Uttar Pradesh exhibit highest price sensitivity, while Karnataka pomegranate exporters absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Contract manufacturing capacity clusters around Gujarat State Fertilizers & Chemicals Ltd's Vadodara fermentation complex and National Fertilizers Limited's Panipat and Nangal facilities. Geographic supply concentration centers on Gujarat, Maharashtra, and Punjab production hubs. Raw material dependencies include sugarcane molasses, carrier substrates like lignite and peat, and cryoprotectant chemicals for liquid formulation stability. Single-source vulnerability runs through molasses supply tied to monsoon-dependent crush cycles. Distribution runs through state agricultural department depots, FPO-anchored consignment models, and dealer networks with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India biofertilizer market represents an early-cycle expansion story as Paramparagat Krishi Vikas Yojana subsidy disbursement accelerates certified organic input adoption beyond the 5% penetration threshold in intensive cereal systems.
For Market Incumbents: Build regulatory moat through BIS certification pre-emption and FCO compliance infrastructure before the National Mission on Natural Farming finalizes procurement guidelines. Deepen backward integration into distillery operations to neutralize molasses price volatility threatening standalone fermenters. Anchor channel control through API-integrated inventory systems for state e-procurement portals, disintermediating dealer networks that historically captured 35-40% of manufacturer margins. For New Entrants and Emerging Players: Assam and Meghalaya organic mission zones represent the most penetrable entry point for consortia producers willing to establish Guwahati warehousing ahead of cold chain infrastructure buildout. Direct-to-FPO digital channels bypass entrenched dealer relationships in Maharashtra and Madhya Pradesh where farmer producer organizations now control 60% of rhizobium offtake. Prioritize liquid formulation capabilities aligned with Pradhan Mantri Krishi Sinchayee Yojana drip expansion rather than legacy seed-treatment powders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-strain consortia manufacturing as CDSCO-style bio-efficacy timelines extend product launch cycles by 18-24 months. Acquisition targets should emphasize PhD-level microbiology talent and encapsulation R&D capabilities rather than pure distribution scale. Monitor FPO procurement portal transaction volumes as early signal of channel power shift from state depots to farmer-controlled aggregators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Distillery Operations | Captive molasses supply from sugarcane crush neutralizes feedstock cost volatility for Gujarat and Maharashtra fermenters. |
| Consortia Formulation Stability Investment | Encapsulation and cryoprotectant R&D differentiates colony-forming unit guarantees under FCO revised standards. |
| FPO-Anchored Distribution Partnerships | Direct fulfillment contracts with Maharashtra and Madhya Pradesh farmer producer organizations disintermediate dealer margin capture. |
| North-East Warehousing Expansion | Guwahati hub establishment captures first-mover positioning in Assam and Meghalaya undersupplied organic mission schemes. |
| API-Integrated E-Procurement Systems | Real-time inventory connectivity with state agricultural department portals aligns with disintermediation of traditional dealer networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, state agricultural department procurement officers, FPO aggregation leaders, BIS certification auditors, and horticulture export zone agronomists. Secondary validation drew from FCO regulatory filings, BIS standard documentation, state subsidy disbursement records, Pradhan Mantri Krishi Sinchayee Yojana implementation reports, and customs data on molasses trade flows. Bottom-up strain-level volume estimates were triangulated against top-down state procurement budget allocations.
Calibration across the analysis window employed segment-specific growth drivers for nitrogen-fixing, phosphate-solubilizing, potassium-mobilizing, and mycorrhizal product categories crossed with mode of application shifts from seed treatment to drip irrigation. CAGRs were derived from elasticity-adjusted penetration curves in wheat-rice versus pulse-horticulture systems. Forecast inputs included micro-irrigation infrastructure buildout timelines and FPO formation rates under Paramparagat Krishi Vikas Yojana.
Practitioners should monitor monsoon crush cycle variability, FCO consortia standard finalization, and FPO portal transaction velocity for early signals of forecast revision. Quarterly review of state subsidy reimbursement rates and BIS certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Marine Biotechnology Market