
 Bio Rational Fungicides Market | 2026-2036
Bio Rational Fungicides Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Rational Fungicides Market Outlook
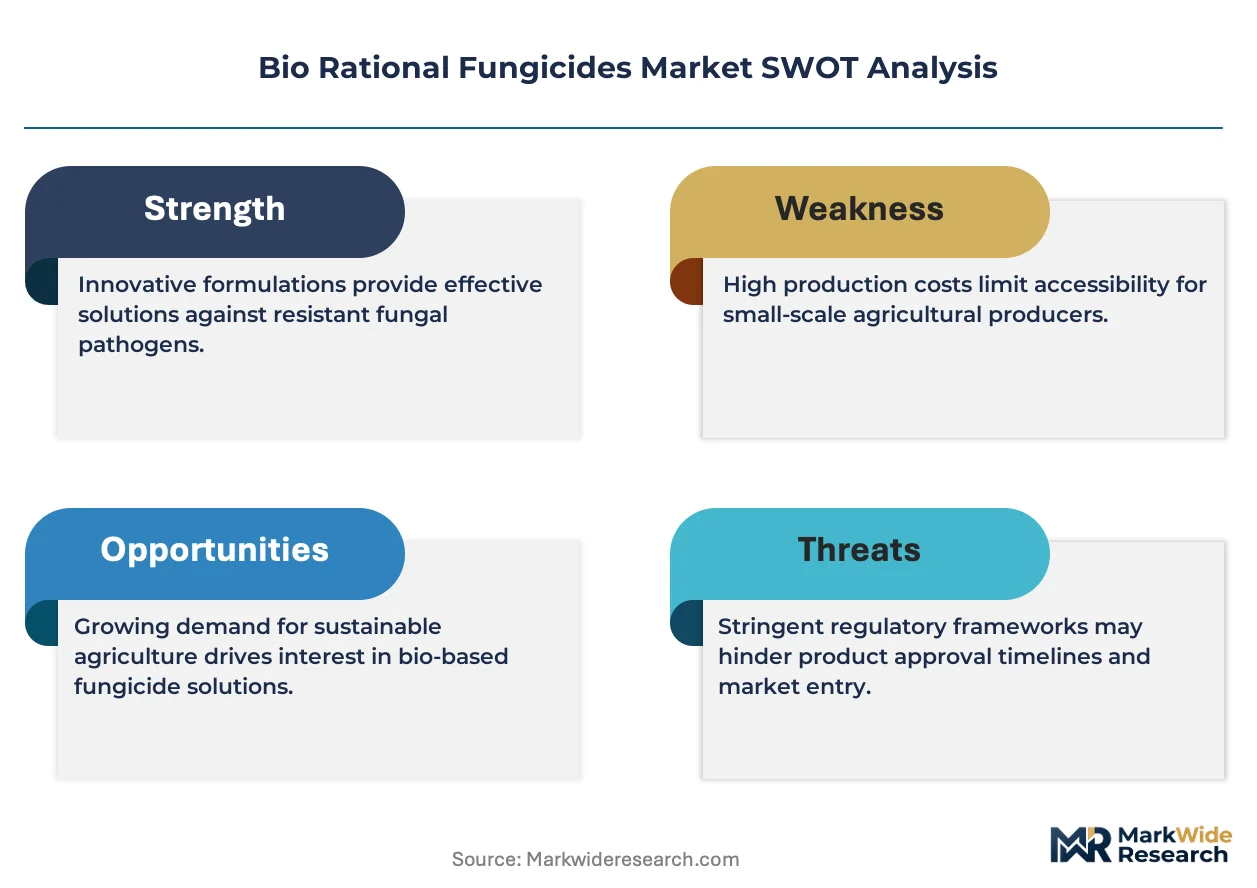
RNA interference and precision fermentation is fragmenting the active ingredient pipeline for biological crop protection. Bayer AG leverages its microbial strain library to anchor high-volume fermentation capacity across multiple continents. Syngenta AG competes through integrated seed-treatment-to-foliar platforms that bundle biologics with conventional chemistries. BASF SE specializes in lipid-based formulation science that stabilizes live microbial cells through shelf-life extremes.
Bio rational fungicides comprise biologically derived or nature-identical active substances—microbial consortia, plant extracts, and biochemical inducers—formulated to suppress fungal pathogens through competitive exclusion, antibiosis, or systemic acquired resistance at application rates typically below one kilogram per hectare. Their primary commercial purpose is to replace or rotate with synthetic fungicides in integrated pest management programs where residue limits, resistance management, or export market access constrain chemical options. Microbial fungicides occupy the deepest margin pools due to strain-ownership barriers and fermentation scale requirements that limit generic replication. Biorational and biopesticide categories track fastest growth as EPA and state-level organic certification programs expand allowable substance lists beyond traditional biologicals.
EPA registration under FIFRA and state-level organic certification through USDA-accredited bodies govern product approval and label claims across the United States, while the EU's 1107/2009 regulation and Farm to Fork Strategy's 50% pesticide reduction target reshape import demand and formulation R&D priorities. REACH compliance for inert ingredients and the EU's pending Soil Monitoring Law add downstream compliance layers that favor established players with regulatory affairs infrastructure. Stakeholders must monitor how carbon accounting frameworks treat biological manufacturing emissions relative to petrochemical synthesis, as this calculus will redirect capital toward either fermentation-based or extraction-based supply models.
Market Dynamics
EPA residue tightening under the Federal Food, Drug, and Cosmetic Act is forcing California specialty crop growers to rotate biological fungicides into integrated pest management programs, fragmenting procurement patterns and elevating strain-ownership premiums for microbial suppliers.
Growth Catalysts
- EU Farm to Fork pesticide reduction:The 50% synthetic pesticide cut mandate under EU Green Deal targets is redirecting Brazilian soybean export supply chains toward microbial residue profiles that clear EU 1107/2009 tolerances.
- RNA interference pipeline expansion:Precision fermentation platforms are compressing active ingredient development timelines for nucleic acid-based fungicides, opening new mode-of-action categories beyond competitive exclusion.
- California Central Valley cluster conversion:Specialty vegetable and nut growers in Fresno and Kern counties are expanding biological program acres as groundwater quality regulations restrict synthetic runoff.
Market Restraints
- Fermentation feedstock volatility:Molasses and corn steep liquor price swings directly compress margins for microbial manufacturers operating multi-continent production networks.
- Shelf-life formulation constraints:Lipid-based stabilization science remains concentrated among three European specialty chemical suppliers, creating input bottlenecks for live cell products.
- REACH inert ingredient compliance:ECHA registration requirements for formulation adjuvants add 18-24 month lead times for new product introductions in EU member states.
Strategic Opportunities
- Seed-treatment biologic bundling:Integrated platforms combining microbial inoculants with foliar biologicals capture premium positioning in Brazilian and Argentinian row crop markets.
- Carbon accounting arbitrage:Fermentation-based manufacturing emissions profiles may achieve favorable treatment under emerging EU Carbon Border Adjustment Mechanism rules relative to petrochemical synthesis.
- India horticulture expansion:Protected cultivation acreage growth in Maharashtra and Karnataka states creates first-mover openings for residue-compliant biological programs targeting EU export channels.
Industry Challenges
- Strain characterization bottlenecks:Whole-genome sequencing and metabolite profiling capabilities remain scarce among mid-tier manufacturers, slowing EPA FIFRA registration submissions.
- Field efficacy variability:Microbial establishment rates fluctuate with soil microbiome composition, complicating label claim substantiation and grower retention programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Rational Fungicides Market |
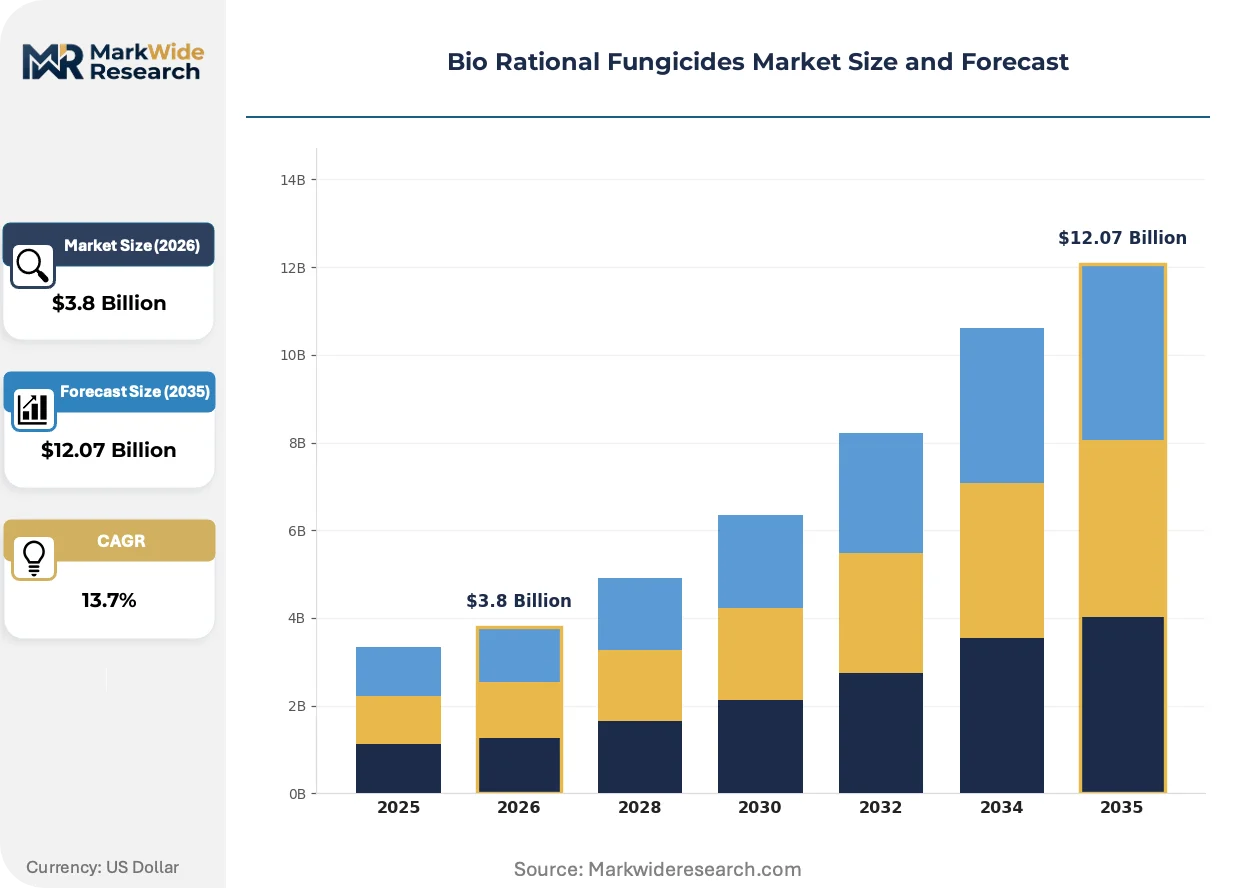
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biorational, Biopesticides, Organic Fungicides, Microbial Fungicides Application: Agricultural Crops, Fruits, Vegetables, Ornamentals Formulation: Liquid, Powder, Granular, Emulsifiable Concentrate Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply Stores, Direct Sales |
| Companies Covered | Bayer AG, Syngenta AG, BASF SE, FMC Corporation, Valent BioSciences, Certis Biologicals, Koppert Biological Systems, Marrone Bio Innovations, UPL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Rational Fungicides Market Strategic Shifts
Digital biology tools and regulatory chemistry are converging to compress biological fungicide development cycles while fragmenting legacy agrochemical distribution hierarchies.
Precision fermentation infrastructure is virtualizing the active ingredient supply chain for RNA-based and protein fungicides. Contract development and manufacturing organizations in Switzerland and Singapore are capturing strain optimization and scale-up work previously performed in-house by integrated agrochemical majors. This virtualization is displacing capital-intensive captive fermentation networks and enabling mid-scale players to access multi-ton production capacity without fixed asset exposure.
REACH authorization sequences for inert ingredients are extending product development timelines for biological formulations seeking EU market access. ECHA's pending restrictions on certain surfactant classes are forcing reformulation investments that favor established players with dedicated regulatory affairs infrastructure. Microbial consortia products face particular scrutiny under the agency's substance evaluation work program, compressing competitive entry for smaller developers lacking dossier preparation capabilities.
Direct procurement relationships between grower cooperatives and biological manufacturers are displacing traditional distributor intermediaries in California and Brazil. Large specialty crop operations in São Paulo state and California's Central Valley are negotiating volume contracts that bundle technical advisory services with product supply. This channel compression is most visible in high-value permanent crop segments where residue compliance documentation carries explicit price premiums.
Bio Rational Fungicides Market Segmentation
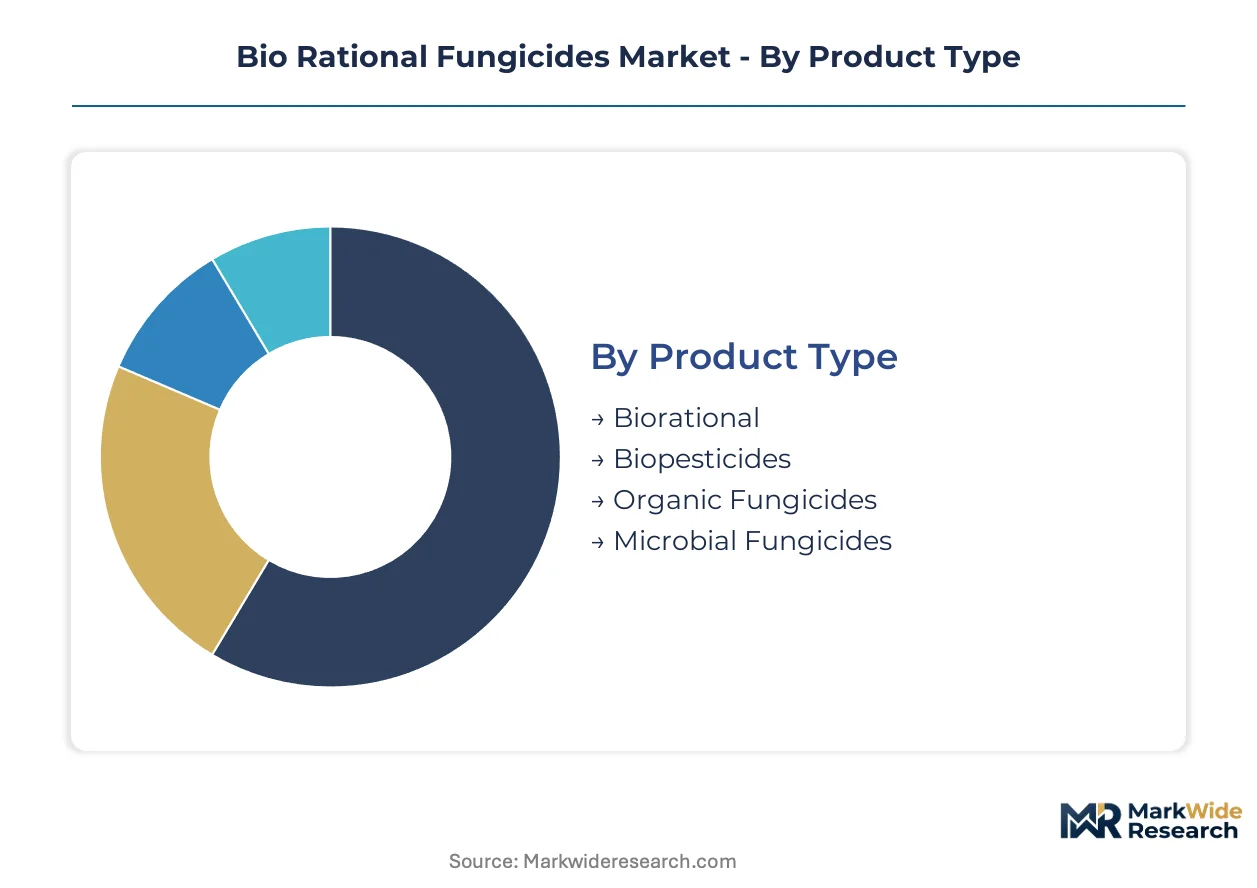
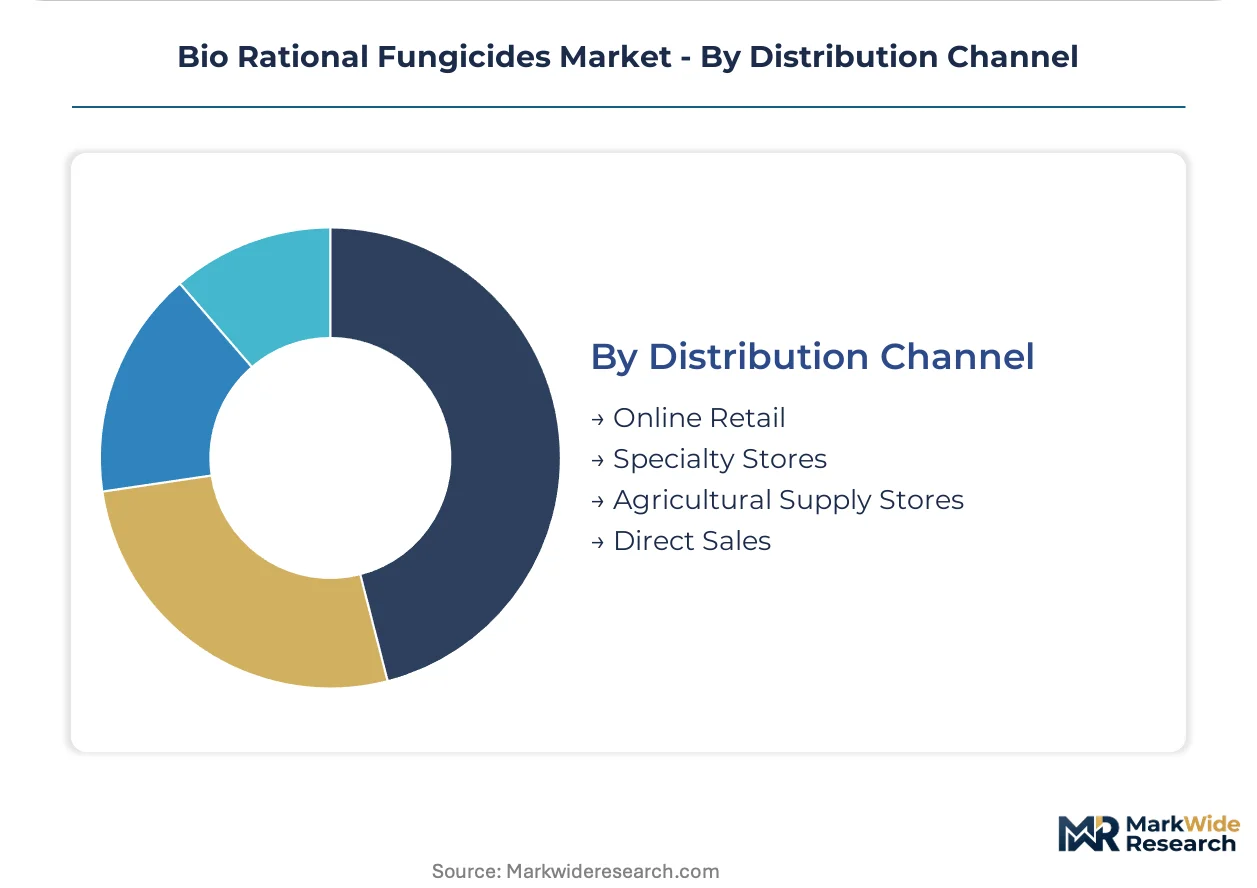
Segmentation in bio rational fungicides reveals how regulatory pressure and residue compliance fragment procurement across crop types and distribution channels. Manufacturers calibrate strain portfolios and formulation science to match the shelf-life and efficacy demands of distinct end-use clusters.
Product Type:
Mature microbial platforms anchor current revenue while emerging biochemical categories reshape R&D allocation.
- Microbial Fungicides:Live bacterial and fungal consortia formulated for competitive exclusion and antibiosis against soilborne pathogens. California specialty vegetable growers in Fresno County deploy these strains to meet EPA residue limits under tightening Federal Food, Drug, and Cosmetic Act enforcement.
- Biopesticides:Fermentation-derived actives including nucleic acid-based and protein fungicides advancing through precision fermentation pipelines. Brazilian soybean operations in Mato Grosso state source these formulations to clear EU 1107/2009 import tolerances on chemical residues.
- Biorational:Nature-identical biochemical inducers that trigger systemic acquired resistance in host plants.
- Organic Fungicides:Plant-extract formulations approved under USDA-accredited organic certification programs.
Microbial Fungicides handles the majority of throughput; Biopesticides is the fastest mover on share.
Application:
Volume concentration tracks export-oriented crop clusters where residue documentation commands explicit price premiums.
- Fruits:Permanent crop applications in California's Central Valley and São Paulo state drive demand for lipid-stabilized live cell products with extended field persistence.
- Vegetables:Specialty row crops in Maharashtra and Karnataka states require rapid-residue-clearance biological programs for EU export channel access.
- Agricultural Crops:Broad-acre soybean and corn rotations in Brazil's Cerrado biome.
- Ornamentals:Greenhouse and nursery operations with lower regulatory exposure but high aesthetic quality thresholds.
Fruits absorbs the dominant share of formulation R&D investment; Vegetables is climbing the fastest as protected cultivation acreage expands.
Formulation:
Margin pools concentrate where stabilization science overcomes shelf-life constraints in extreme climate zones.
- Liquid:Aqueous suspensions of live microbial cells requiring cold-chain integrity through distribution. Kern County nut growers favor liquid delivery for foliar application timing precision.
- Emulsifiable Concentrate:Oil-based carriers that shield biological actives from UV degradation and desiccation stress.
- Powder:Lyophilized or spray-dried preparations for long-term storage stability.
- Granular:Soil-incorporated delivery systems for rhizosphere establishment.
Liquid commands the largest installed application equipment base; Emulsifiable Concentrate is gaining share fastest in tropical row-crop belts.
Distribution Channel:
Channel compression accelerates where grower cooperatives internalize technical advisory and residue compliance documentation.
- Direct Sales:Volume contracts between manufacturers and large specialty crop operations bundling technical services with supply. São Paulo citrus cooperatives negotiate direct procurement to secure strain-specific residue profiles.
- Agricultural Supply Stores:Traditional distributor networks with localized agronomic support capabilities.
- Specialty Stores:Niche retailers serving organic-certified and smallholder segments.
- Online Retail:E-commerce platforms capturing price-sensitive hobbyist and small-acreage growers.
Direct Sales captures the highest-margin throughput; Agricultural Supply Stores remains the volume backbone in fragmented smallholder markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty crop exporters and residue-constrained growers cluster in distinct geographies where biological fungicide procurement carries explicit compliance premiums. Regulatory divergence between import markets and domestic enforcement fragments regional demand patterns.
United States
California Central Valley vegetable and nut growers anchor domestic biological fungicide consumption as EPA tightens residue enforcement under the Federal Food, Drug, and Cosmetic Act. Fresno County operations rotate microbial formulations into integrated pest management programs to secure export clearance for EU and Japanese markets. Kern County pistachio and almond orchards deploy lipid-stabilized live cell products to meet groundwater quality regulations restricting synthetic runoff.
Brazil
Mato Grosso soybean operations drive Latin American demand as farmers face tightening EU 1107/2009 import tolerances on conventional chemical residues. São Paulo state citrus cooperatives negotiate direct procurement contracts bundling technical advisory with strain-specific residue documentation. The Cerrado biome's broad-acre rotations increasingly substitute microbial formulations for synthetic fungicides in pre-export conditioning programs.
Germany
REACH compliance infrastructure and formulation science capabilities concentrate biological fungicide R&D investment in Baden-Württemberg and North Rhine-Westphalia. ECHA's pending restrictions on surfactant classes force reformulation investments that favor established players with dedicated regulatory affairs teams. Bavarian precision fermentation contract manufacturers capture strain optimization work previously performed in-house by integrated agrochemical majors.
India
Maharashtra and Karnataka protected cultivation expansion creates first-mover openings for residue-compliant biological programs targeting EU export channels. The country's national agricultural regulator evaluates microbial consortia under evolving biopesticide registration guidelines. Gujarat contract research organizations build whole-genome sequencing capabilities to accelerate strain characterization for FIFRA-equivalent submissions.
China
Yangtze River Delta fermentation capacity anchors microbial active ingredient supply for export formulation. The national environmental ministry's dual carbon goals redirect capital toward fermentation-based manufacturing emissions profiles. Shandong Peninsula biomanufacturing clusters scale precision fermentation infrastructure for nucleic acid-based fungicide candidates.
Bio Rational Fungicides Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Consolidation pressure concentrates among integrated agrochemical majors with captive fermentation networks and regulatory affairs infrastructure. Three archetypes dominate: strain-ownership specialists leveraging proprietary microbial libraries, formulation-science players commanding lipid-based stabilization IP, and seed-treatment integrators bundling biologicals with conventional chemistries. Dominant competitive moves include backward integration into precision fermentation capacity and geographic expansion through contract manufacturing partnerships.
Within the integrated-major tier, Bayer AG and Syngenta AG exemplify divergent strategic postures toward biological fungicide commercialization. BASF SE occupies a position emphasizing formulation-science specialization. Among mid-scale biological specialists, Valent BioSciences and Certis Biologicals represent the product-focused archetype competing through strain differentiation rather than channel control.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta AG |
| BASF SE |
| FMC Corporation |
| Valent BioSciences |
| Certis Biologicals |
| Koppert Biological Systems |
| Marrone Bio Innovations |
| UPL |
| Others |
Value Chain & Pricing Dynamics
Molasses and corn steep liquor supply concentration in Brazil and India directly determines margin distribution between microbial manufacturers and formulation specialists downstream. Fermentation feedstock indexation clauses in multi-year supply contracts transfer commodity volatility risk upstream while lipid-based stabilization IP holders capture fixed-price premiums.
Pricing Analysis
Cost-plus contracts with molasses price indexation dominate microbial fungicide procurement between Brazilian soybean cooperatives and fermentation suppliers. Three-tier pricing structure across premium, standard, and economy levels separates strain-ownership specialists from generic microbial blenders and unformulated active ingredient traders. Pricing pressure stems from REACH compliance investments that extend EU product registration timelines. Smallholder agricultural supply store segments exhibit highest price sensitivity, while direct-contract specialty crop operations accept residue-documentation premiums.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Swiss and Singapore-based precision fermentation CDMOs that captured strain scale-up work from integrated agrochemical majors. Active ingredient supply draws from Yangtze River Delta fermentation clusters in China, Bavarian precision manufacturing in Germany, and emerging Indian biomanufacturing in Gujarat. Raw material dependencies center on agricultural carbohydrate feedstocks, European specialty lipid suppliers, and REACH-compliant surfactant classes. Single-source vulnerability concentrates in lipid-based stabilization science where three European suppliers control live cell shelf-life extension. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in California and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs biological fungicide competition as seed-treatment-to-foliar integrated platforms create interoperability lock-in between microbial inoculants and foliar biologicals.
For Market Incumbents: Insulate strain-ownership advantages through captive fermentation capacity expansion in Brazil and India, and preempt regulatory compliance investments ahead of ECHA surfactant restrictions. Precision fermentation virtualization threatens integrated majors' capital-intensive networks; backward integration into CDMO partnerships secures scale-up access without fixed asset exposure. For New Entrants and Emerging Players: Build out whole-genome sequencing and metabolite profiling capabilities to accelerate EPA FIFRA registration submissions, targeting mid-tier manufacturers lacking dossier preparation infrastructure. India's Maharashtra and Karnataka protected cultivation expansion offers first-mover openings for residue-compliant biological programs. Direct procurement channel compression in São Paulo citrus cooperatives enables technical advisory bundling as entry mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation CDMOs in Switzerland and Singapore that captured outsourced scale-up work from Bayer and Syngenta. Long-term viability hinges on carbon accounting arbitrage where fermentation-based manufacturing achieves favorable EU CBAM treatment. Monitor EPA state-level organic certification expansion as inflection signal for biopesticide category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | CDMOs in Singapore capture strain optimization work from integrated majors. |
| REACH Surfactant Reformulation Investment | ECHA restrictions force 18-24 month lead times favoring established players. |
| Direct Procurement Channel Compression | São Paulo citrus cooperatives bundle technical advisory with strain-specific residue documentation. |
| Seed-Treatment Biologic Bundling | Integrated platforms capture premium positioning in Brazilian row crop markets. |
| Carbon Accounting Arbitrage Positioning | Fermentation emissions profiles may achieve favorable EU CBAM treatment. |
Study Parameters
Cross-validation between primary interviews with fermentation plant managers, regulatory affairs leads at biological manufacturers, procurement directors at Brazilian soybean cooperatives, and California specialty crop agronomists anchors the qualitative findings. Secondary validation draws from EPA FIFRA registration databases, ECHA REACH dossier filings, USDA organic certification records, and customs trade data for fermentation feedstock flows. Bottom-up strain-level production estimates and top-down market size triangulation reconcile volume outputs.
Calibration against historical EPA registration timelines and EU 1107/2009 approval patterns validates projection assumptions across the analysis window. Segmentation dimensions model product type, application crop cluster, formulation chemistry, and distribution channel structure. CAGRs derive from penetration rate modeling in residue-constrained export corridors and organic certification expansion trajectories. Industry-specific inputs include molasses price volatility indices and groundwater quality regulation enforcement intensity in California's Central Valley.
Sensitivities concentrate around EPA residue enforcement acceleration, EU Farm to Fork pesticide reduction timeline adjustments, and fermentation feedstock commodity price spikes. Forecasts reflect documented assumptions on regulatory approval velocity and grower adoption curves in export-oriented crop clusters. Quarterly review of EPA state-level organic certification expansion, ECHA substance evaluation work program updates, and EU CBAM implementation rules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Horticulture Bioplastic Market