
 North America Bioherbicides Market | 2026-2036
North America Bioherbicides Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bioherbicides Market Intelligence
Organic row-crop growers is rotating toward bioherbicide procurement faster than conventional commodity farmers across North America. Certis USA leverages its microbial fermentation infrastructure to supply agricultural co-ops throughout the Midwest. Marrone Bio Innovations anchors its position through specialized biofungicide-bioherbicide combinations for specialty vegetable markets. FMC Corporation competes by extending its synthetic herbicide distribution channels into biological adjacencies.
North America bioherbicides comprise living microorganisms, plant-derived allelochemicals, and formulated biological solutions that disrupt weed germination or growth through metabolic interference rather than synthetic chemical toxicity. Manufacturing relies on submerged fermentation for bacterial and fungal propagules, followed by stabilization in liquid suspensions or desiccated granular carriers, with shelf-life sensitivity driving cold-chain requirements for viable inoculants. Microbial formulations lead volume due to established production economics, while plant-based extracts capture premium positioning in organic horticulture where residue limits are strictest. Liquid formulations dominate application infrastructure compatibility, though granular delivery is expanding in turf management where broadcast spreader equipment prevails.
EPA biopesticide registration guidelines shape product development timelines and label claims for microbial active ingredients across the United States. Health Canada's PMRA maintains parallel but non-identical data requirements that condition cross-border product launches, while the USDA National Organic Program standards determine eligibility for certified organic operations. State-level 24(c) registrations in California and New York create additional regulatory layers for localized weed targets. Stakeholders must monitor how EPA cumulative risk assessments for synthetic chemistries accelerate grower switching thresholds toward biological alternatives.
Market Dynamics
The EPA's accelerated biopesticide registration timeline is compressing product development cycles and forcing microbial formulation investments across the North American agricultural input sector.
Growth Catalysts
- Regulatory Streamlining:The EPA's reduced biopesticide review periods cut time-to-market for microbial active ingredients. This regulatory efficiency draws venture capital toward fermentation-based manufacturing infrastructure.
- No-Till Expansion:Corn Belt farmers adopting continuous no-till systems require pre-emergent biological alternatives that do not persist in soil microbiomes. This agronomic shift creates dedicated demand for microbial bioherbicides.
- Organic Certification Thresholds:USDA National Organic Program standards prohibit synthetic herbicide residues on certified operations. Specialty crop growers in California and Florida convert procurement toward plant-derived allelochemical formulations.
Market Restraints
- Cold-Chain Infrastructure Gaps:Viable microbial inoculants require temperature-controlled distribution from fermentation facilities to farmgate applicators. Rural co-ops lack refrigerated storage capacity in the Dakotas and Nebraska.
- Technical Efficacy Windows:Biological actives demonstrate narrower environmental condition ranges for germination disruption than synthetic chemistries. Humidity and temperature sensitivity limits reliable performance in variable Midwestern springs.
- Cross-Border Regulatory Friction:Health Canada's PMRA maintains distinct efficacy data requirements from EPA guidelines. Dual registration burdens delay product launches in Ontario and Quebec specialty vegetable markets.
Strategic Opportunities
- State-Level 24(c) Registrations:California and New York permit localized label expansions for weed-specific targets. These regulatory pathways enable premium pricing for narrow-spectrum bioherbicides against invasive species.
- Turf Management Channel Expansion:Granular formulation compatibility with broadcast spreader equipment opens golf course and municipal park segments. This application infrastructure differs from agricultural sprayer requirements.
- Synthetic Chemistry Cumulative Risk Assessments:EPA re-evaluations of legacy herbicide toxicology profiles accelerate grower switching thresholds. Biological alternatives capture displaced acreage as label restrictions tighten.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial microbiology expertise for submerged culture optimization concentrates at legacy pharmaceutical and enzyme manufacturing sites. Agricultural biotechnology firms compete for limited bioprocess engineering capacity.
- Shelf-Life Stability Certification:Viable propagule count maintenance through distribution chains requires accelerated aging protocols not standardized across state agricultural extension services. Inconsistent testing methodologies delay product approvals.
- Legacy Equipment Integration:Biological suspension viscosity and nozzle clogging characteristics differ from synthetic herbicide formulations. Retrofitting existing sprayer fleets imposes capital costs on mid-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bioherbicides Market |
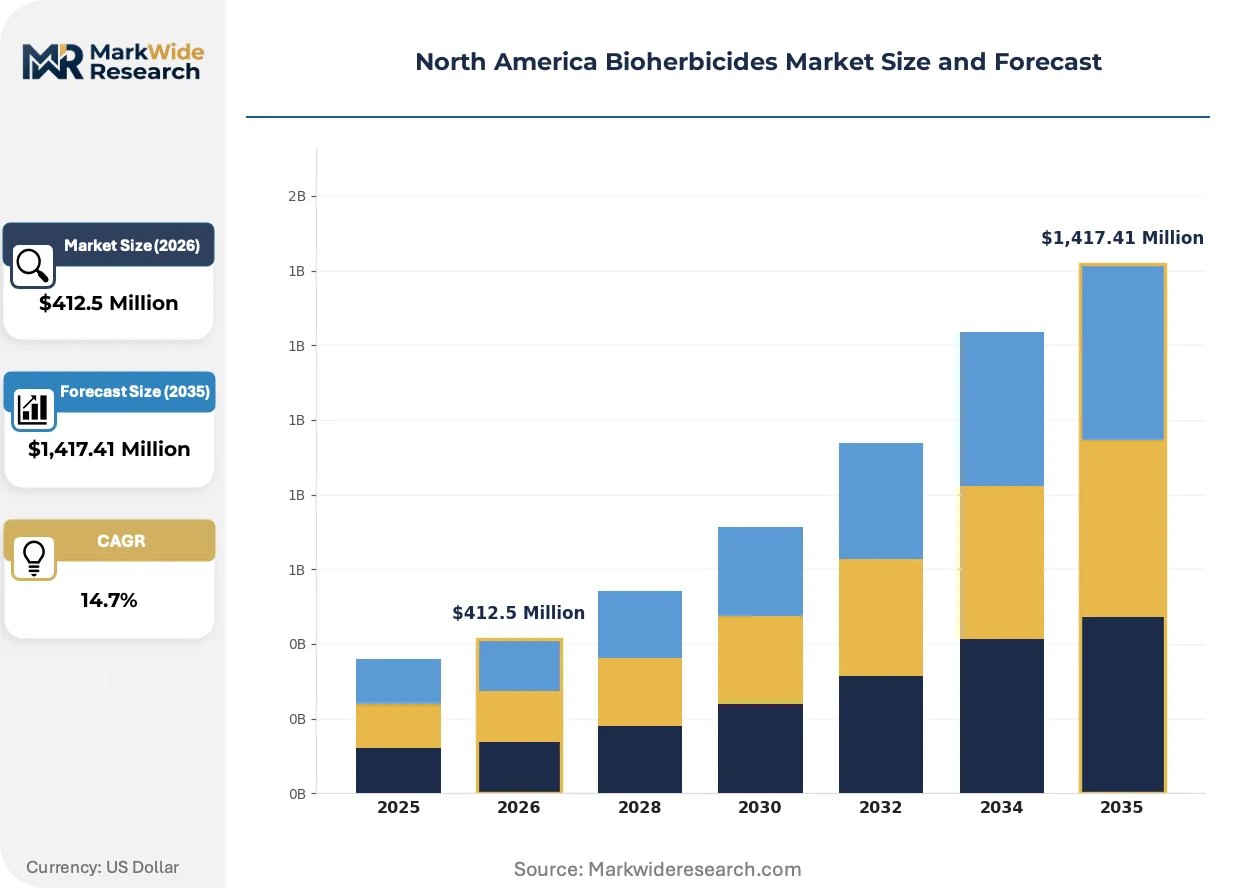
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,417.41 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Plant-Based, Bio-Solutions, Organic Application: Agricultural Fields, Horticulture, Turf Management, Forestry Formulation: Granular, Liquid, Capsule, Powder Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Certis USA, FMC Corporation, Marrone Bio Innovations, Deer Creek Holdings, Verdesian Life Sciences, BASF, Emery Oleochemicals, EcoPesticides International, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bioherbicides Market Strategic Shifts & Innovations
Biological weed control is fragmenting into distinct technical branches as manufacturers pursue divergent formulation strategies for commodity row crops versus premium horticulture markets.
Microbial fermentation platforms is bifurcating between high-volume bacterial spore production for broadacre corn and soybean applications versus specialized fungal metabolite extraction for high-value organic vegetable systems. Midwest agricultural co-ops prioritize cost-competitive bacterial formulations with standardized application protocols. This technical divergence is compressing R&D resource allocation toward platform-specific optimization rather than universal biological solutions.
The EPA's 2024 updated biopesticide data requirements for microbial pesticides alter submission thresholds for whole-genome sequencing and metabolite profiling. These documentation burdens extend pre-registration timelines for novel fungal strains. Small-scale manufacturers in the specialty crop segment absorb compliance costs through premium pricing in California's Central Valley organic lettuce and strawberry operations.
Direct-to-grower digital platforms are displacing traditional distributor relationships for biological input procurement. Large-scale corn operations in Iowa and Illinois negotiate volume contracts through agricultural technology marketplaces that bypass regional agronomy retailers. This channel compression concentrates price transparency and technical support burdens onto manufacturer field staff across the Corn Belt.
North America Bioherbicides Market Segmentation
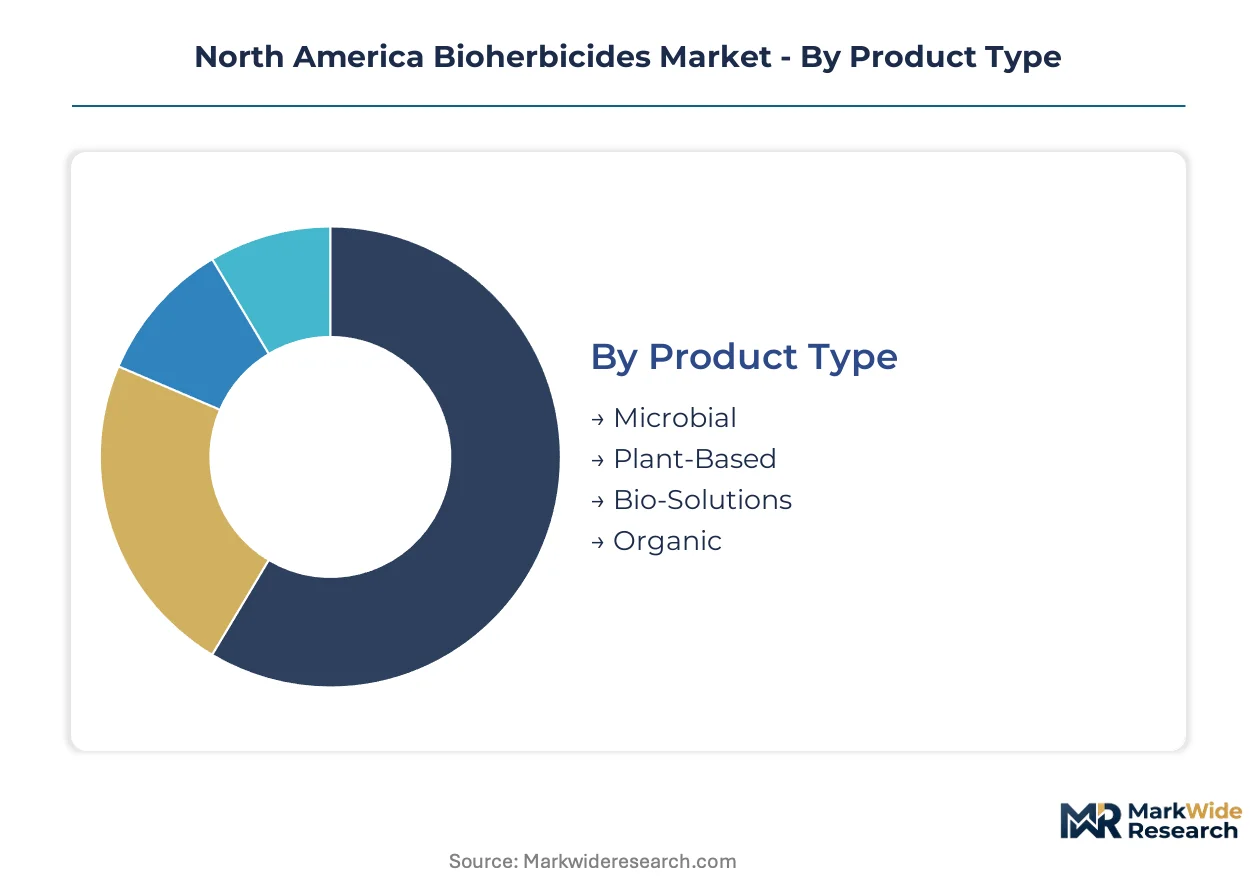
Bioherbicide segmentation reveals divergent margin structures between broadacre commodity applications and premium horticultural markets. Manufacturers optimize fermentation platforms and formulation chemistry around distinct price tolerance and performance requirements across end-use categories.
Product Type:
Margin pools concentrate in microbial formulations where production scale economies offset R&D amortization, while plant-derived extracts command premium positioning in residue-sensitive organic channels.
- Microbial:Living bacterial and fungal propagules manufactured through submerged fermentation disrupt weed germination via metabolic interference. Demand concentrates in the United States Corn Belt where no-till corn and soybean operations require pre-emergent biological alternatives that degrade without soil persistence. EPA registration streamlining accelerates bacterial spore product launches.
- Plant-Based:Extracted allelochemicals from competitive plant species provide non-living active ingredients with extended shelf stability. California and Florida specialty crop growers rotate procurement toward these formulations as USDA National Organic Program standards tighten residue scrutiny on certified operations.
- Bio-Solutions:Formulated combinations integrating multiple biological modes of action. Turf management contracts in municipal parks and golf courses absorb these premium-priced tank-mix alternatives.
- Organic:Certified-compliant formulations meeting strict input material traceability requirements. Pacific Northwest organic vegetable cooperatives specify these products for export-bound produce.
Microbial holds installed capacity. Plant-Based is rotating up the share rankings.
Application:
Volume distribution tracks divergent equipment infrastructure and agronomic practice adoption across commodity versus specialty production systems.
- Agricultural Fields:Row-crop deployment across corn, soybean, and wheat systems. Iowa and Illinois large-scale operations negotiate volume contracts through direct-to-grower digital procurement platforms.
- Horticulture:High-value fruit and vegetable production in California's Central Valley and Florida's winter vegetable belt. Organic certification thresholds force rapid substitution away from synthetic chemistries.
- Turf Management:Golf course superintendents and municipal park managers deploy granular formulations compatible with broadcast spreader equipment. This application infrastructure bypasses agricultural sprayer retrofit costs.
- Forestry:Reforestation site preparation and invasive species suppression on public lands. Federal land management agencies specify narrow-spectrum bioherbicides against targeted noxious weeds.
Agricultural Fields anchors volume throughput. Horticulture is climbing the fastest as organic acreage expands.
Formulation:
Application equipment compatibility and shelf-life sensitivity drive formulation selection, with cold-chain availability constraining viable microbial delivery options.
- Liquid:Suspensions and emulsifiable concentrates dominating existing agricultural sprayer infrastructure. Corn Belt cooperatives prioritize these formulations for seamless integration with synthetic herbicide application protocols.
- Granular:Desiccated carriers enabling broadcast spreader deployment. Turf management segments in the Northeast and Mid-Atlantic expand procurement as municipal budgets shift toward biological maintenance programs.
- Capsule:Encapsulated active ingredients providing controlled release and extended field persistence. Specialty crop consultants in California specify these for precision drip irrigation integration.
- Powder:Dry flowable formulations requiring reconstitution prior to application. Smaller organic operations in the Upper Midwest favor these for reduced shipping costs and storage flexibility.
Liquid maintains equipment compatibility dominance. Granular is gaining share fastest through turf channel expansion.
Distribution Channel:
Channel structure fragments between legacy agricultural retail relationships and emerging digital procurement pathways that compress price transparency.
- Wholesale:Regional agricultural distributors maintaining inventory and technical support infrastructure across the Corn Belt. These intermediaries aggregate demand from county-level cooperatives.
- Direct Sales:Manufacturer field staff contracting directly with large-scale corn and soybean operations. Iowa and Illinois growers leverage agricultural technology marketplaces to bypass traditional retail markups.
- Retail:Farm supply stores and garden centers serving small-scale organic producers and hobby farmers. Urban agriculture expansion in Texas and Arizona metro areas supports these outlets.
- Online:E-commerce platforms enabling specialty crop growers to source narrow-spectrum products unavailable through local distribution. California organic lettuce and strawberry operations utilize these channels for expedited procurement.
Wholesale retains infrastructure depth. Direct Sales is rotating up the share rankings as platform adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian bioherbicide manufacturers export microbial formulations to United States Corn Belt buyers through cross-border agricultural supply chains. This trade corridor concentrates demand around EPA-registered bacterial spore products for no-till corn and soybean operations.
United States
Iowa and Illinois large-scale corn operations drive procurement of pre-emergent microbial alternatives through direct-to-grower digital platforms. EPA biopesticide registration streamlining accelerates product launches for bacterial formulations targeting glyphosate-resistant weed populations. The Corn Belt's continuous no-till adoption creates dedicated demand for biological actives that degrade without soil persistence.
Canada
Ontario and Quebec specialty vegetable growers absorb dual registration burdens as Health Canada's PMRA maintains distinct efficacy data requirements from EPA guidelines. The country's organic acreage expansion in British Columbia's Fraser Valley concentrates demand for plant-derived allelochemical formulations. Prairie Provinces wheat producers trial microbial bioherbicides through provincial agricultural extension networks.
Mexico
Jalisco and Sinaloa winter vegetable exporters rotate procurement toward residue-compliant biological inputs for United States-bound produce. The country's national agricultural regulator evaluates microbial active ingredients under harmonized data protocols with EPA guidelines. Bajío Region strawberry operations pilot granular bioherbicide formulations through state-level agricultural development programs.
North America Bioherbicides Market Key Industry Players
Player mix skews toward diversified agricultural input conglomerates with legacy synthetic herbicide distribution infrastructure. Market structure concentrates around three strategic tiers: microbial fermentation specialists leveraging submerged culture platforms, synthetic chemistry incumbents extending into biological adjacencies, and plant extract processors serving premium organic horticulture channels. Dominant competitive moves include capacity expansion in Midwest fermentation facilities and strategic partnerships between microbial manufacturers and agricultural technology procurement platforms.
Within the microbial specialist tier, Certis USA and Marrone Bio Innovations occupy positions anchored by fermentation infrastructure and specialized formulation capabilities. FMC Corporation exemplifies the synthetic incumbent archetype extending distribution channels into biological alternatives. BASF represents the diversified multinational segment with integrated crop science portfolios spanning conventional and biological chemistries.
| Leading Market Players |
|---|
| Certis USA |
| FMC Corporation |
| Marrone Bio Innovations |
| Deer Creek Holdings |
| Verdesian Life Sciences |
| BASF |
| Emery Oleochemicals |
| EcoPesticides International |
| Corteva Agriscience |
| Others |
Cost & Logistics Intelligence
Microbial fermentation capacity replacing synthetic chemistry manufacturing infrastructure simultaneously concentrates supply geography in the United States Corn Belt and compresses pricing economics for biological actives. This substitution dynamic shifts procurement power toward agricultural co-ops with cold-chain capabilities while squeezing margins for plant-derived extract processors competing on residue compliance premiums.
Pricing Analysis
Next-generation bacterial spore formulations command 15-25% premiums over established fungal metabolite products, while prior-generation plant extracts face commoditization pressure from microbial alternatives. Three-tier pricing structure across premium microbial inoculants, standard bacterial suspensions, and economy plant-based concentrates dominates contract negotiations. Cost compression in the economy tier intensifies as EPA registration streamlining floods the market with competing bacterial products. Large-scale corn operations in Iowa and Illinois exhibit lowest price sensitivity through volume contracting, while small organic vegetable growers in California's Central Valley absorb highest cost burden for certified-compliant formulations.
Supply Chain Analysis
The United States anchors submerged fermentation capacity for bacterial spore production, Canada supplies specialized fungal strain development, and Mexico provides winter vegetable market access for residue-compliant formulations. Active ingredient production draws from agricultural co-product streams, pharmaceutical-grade fermentation equipment, and desiccated carrier substrates. Single-source vulnerability concentrates in cold-chain logistics providers serving the Dakotas and Nebraska rural distribution nodes. Distribution runs through agricultural technology marketplaces displacing traditional wholesale relationships across the Corn Belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as synthetic herbicide manufacturers extend distribution channels into biological alternatives, threatening to commoditize microbial formulations through scale advantages.
For Market Incumbents: Consolidate fermentation capacity in Midwest agricultural co-op territories to secure captive offtake agreements before synthetic chemistry incumbents retrofit distribution infrastructure. Lock in exclusive supply relationships with cold-chain logistics providers serving Nebraska and the Dakotas to defend against price erosion from new microbial entrants. Prioritize backward integration into agricultural co-product feedstock sourcing to insulate margin structures from commodity substrate volatility.
For New Entrants and Emerging Players: Differentiate on state-level 24(c) registration specialization for invasive weed targets in California and New York, where narrow-spectrum premiums persist. Target turf management segments in the Northeast and Mid-Atlantic with granular formulations bypassing agricultural sprayer retrofit barriers. Pursue direct-to-grower digital platform partnerships to circumvent wholesale distributor margin capture in the Corn Belt.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed microbial fermentation specialists facing EPA metabolite profiling compliance cost escalation. Five-to-ten year viability hinges on successful navigation from premium horticulture niches toward broadacre commodity volume contracts. Watch for inflection signals in Iowa and Illinois co-op procurement committee adoption rates for bacterial spore standardization protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Midwest facility investments capture Corn Belt co-op demand as no-till adoption accelerates. |
| State-Level 24(c) Registration Pursuit | California and New York localized labels enable premium pricing against invasive weed targets. |
| Cold-Chain Logistics Partnership | Refrigerated distribution agreements secure viable inoculant delivery to rural Nebraska and Dakota markets. |
| Direct-to-Grower Platform Integration | Agricultural technology marketplace partnerships bypass traditional wholesale margin structures in Iowa and Illinois. |
| Plant Extract Premium Positioning | USDA Organic Program certification investments defend California Central Valley residue-sensitive market share. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with EPA regulatory affairs specialists, agricultural co-op procurement managers, fermentation facility operations directors, and specialty crop consultants in California's Central Valley. Secondary validation incorporated EPA biopesticide registration databases, USDA National Organic Program certification records, Health Canada PMRA submission filings, and agricultural extension trial reports from Iowa State University and University of California systems. Bottom-up volume estimates from county-level cooperative procurement data triangulated against top-down market sizing from fermentation capacity utilization metrics.
Across the analysis window, projections integrated product type segmentation by viable propagule formulation, application segmentation by equipment infrastructure requirements, and channel segmentation by digital platform penetration rates. CAGRs were derived from regression analysis of historical EPA registration velocity against no-till acreage expansion curves, with scenario weighting for synthetic herbicide cumulative risk assessment timing. Forecast inputs included bacterial spore production yield improvements and granular formulation stability extension protocols.
Material uncertainties — EPA metabolite profiling requirement amendments, Health Canada PMRA data harmonization shifts, and Corn Belt spring weather volatility — sit outside the modeled envelope. Forecasts reflect assumptions regarding cold-chain infrastructure buildout rates and agricultural co-op consolidation trajectories. Recalibration cycles align with material shifts in EPA biopesticide review period policies and synthetic chemistry label restriction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Plant Based Biosurfactants Market