
 Bionematicides Market | 2026-2036
Bionematicides Market Size, Share, and Industry Trends Forecast 2026-2036
Bionematicides Market Analysis
Biological active ingredients are restructuring cost structures in nematode management as fermentation-derived metabolites replace synthetic carbamates and organophosphates in premium soil-health programs. Corteva Agriscience leverages its microbial pipeline to anchor positions in row-crop biologicals across North American corn and soybean acres. BASF SE competes through integrated seed-treatment-to-soil-applied portfolios that bundle bionematicides with conventional chemistries. Koppert Biological Systems specializes in greenhouse and high-value vegetable systems where zero-residue protocols command price premiums.
Bionematicides comprise living organisms or their derived metabolites formulated to suppress plant-parasitic nematode populations, typically delivered as spore suspensions with colony-forming unit counts exceeding 10^8 per milliliter for soil-drench or in-furrow application. Their primary purpose centers on protecting root architecture and nutrient-uptake capacity without triggering resistance cycles common to fumigant nematicides. Bacterial formulations dominate volume as Bacillus firmus and Pasteuria penetrans strains demonstrate consistent efficacy against cyst and root-knot nematodes across diverse soil chemistries. Fungal products occupy faster-growing niches where Trichoderma harzianum and Purpureocillium lilacinum expand into permanent-crop orchards and vineyards with multi-year root-protection requirements.
The EPA's biopesticide registration framework and the EU's Sustainable Use Directive shape formulation standards and residue-testing protocols that determine market access for new microbial entrants. India's Central Insecticides Board and Brazil's ANVISA enforce country-specific toxicity and ecotoxicity thresholds that filter which strains reach commercial scale in their respective agricultural sectors. Stakeholders must monitor evolving soil-carbon measurement methodologies and carbon-credit eligibility rules that could revalue biological inputs as climate-smart agriculture investments beyond their pest-control utility.
Market Dynamics
The phase-out of methyl bromide under the Montreal Protocol and EPA fumigant restrictions are compressing grower options and redirecting capital toward microbial fermentation infrastructure. This regulatory compression is accelerating biological nematode control adoption across specialty crop regions where soil fumigation once dominated.
Growth Catalysts
- EPA Biopesticide Registration Streamlining:The agency's reduced data requirements for microbial active ingredients compresses commercialization timelines for new Bacillus and Pasteuria strains targeting soybean cyst nematode.
- Brazilian Soybean Belt Resistance Pressure:Intensive glyphosate and synthetic nematicide rotation failures in Mato Grosso and Paraná drive grower willingness to trial microbials as resistance-breaker tools in integrated pest management programs.
- Seed-Treatment Integration:Precision application technology enables liquid spore suspensions to coat soybean and corn seed at rates exceeding 10^8 colony-forming units per milliliter, embedding biologicals into standard planting workflows.
Market Restraints
- Fermentation Input Cost Volatility:Molasses and soy-based nutrient media prices fluctuate with commodity grain markets, compressing margins for bacterial spore production at commercial scale.
- Strain Supply Concentration:Master seed banks for Pasteuria penetrans and Purpureocillium lilacinum concentrate in European and North American germplasm repositories, creating biosecurity and access bottlenecks for Asian and Latin American formulators.
- Soil Chemistry Incompatibility:Extreme pH conditions below 5.5 or above 8.0 in alkaline western US soils and acidic tropical laterites degrade spore viability and limit efficacy consistency across geography.
Strategic Opportunities
- India Horticulture Expansion:Protected cultivation of tomatoes, capsicum, and cucurbits in Karnataka and Maharashtra creates demand for zero-residue nematode control as FSSAI tightens maximum residue limits for export-bound produce.
- Carbon Credit Eligibility:Emerging soil-carbon measurement protocols under voluntary carbon standards could reclassify biological nematicide applications as climate-smart agriculture investments eligible for offset revenue streams.
- Drone-Based Soil Application:Unmanned aerial systems equipped with precision spray nozzles enable targeted delivery of fungal spore suspensions to orchard and vineyard root zones previously inaccessible to ground equipment.
Industry Challenges
- Microbial Formulation Expertise Gap:Shortage of fermentation scientists and spore stabilization chemists delays strain scale-up from laboratory to commercial bioreactor volumes exceeding 10,000 liters.
- Multi-Year Efficacy Certification:Perennial crop growers in viticulture and tree nut sectors require multi-season field trial data to justify biological nematicide adoption, extending sales cycles beyond synthetic product replacement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bionematicides Market |
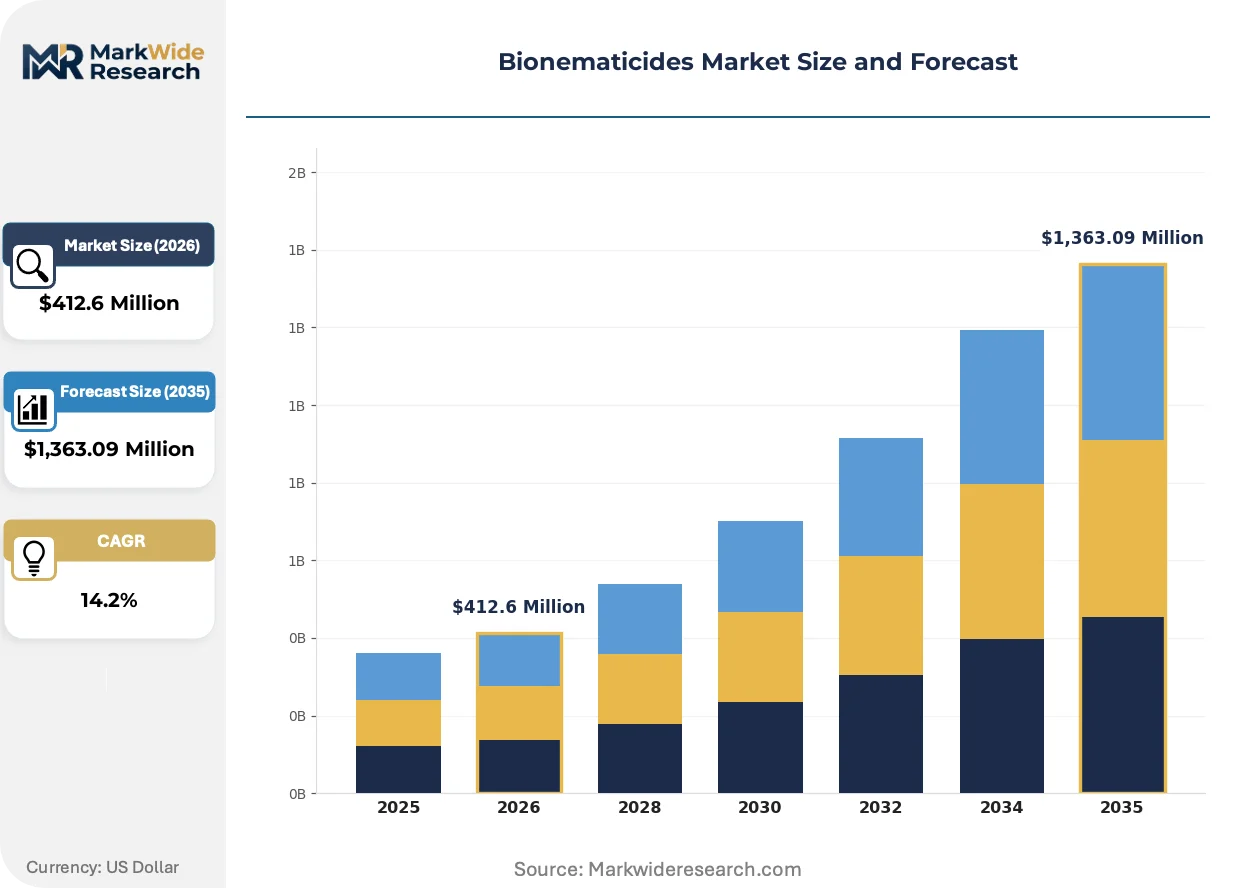
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Nematodes, Plant Extracts Application: Agricultural Crops, Ornamental Plants, Turf, Greenhouses End User: Farmers, Agricultural Cooperatives, Research Institutions, Commercial Growers Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Corteva Agriscience, FMC Corporation, BASF SE, Koppert Biological Systems, Marrone Bio Innovations, Bayer AG, UPL Limited, Novozymes A/S, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bionematicides Market Emerging Trajectories
Biological nematode control is transitioning from standalone curative applications to preventive soil-health infrastructure embedded at the planting interface. This shift demands new formulation science, delivery hardware, and grower education architectures.
Metabolite-based biopesticides derived from Bacillus fermentation supernatants are rewriting efficacy expectations for biological nematode management. These non-living extracts bypass spore viability constraints in harsh soil chemistries. Large-scale corn operations in Iowa and Illinois are piloting metabolite seed treatments at commercial planting rates. The technology is compressing the performance gap between biological and synthetic carbamate standards.
EU Sustainable Use Directive mandates are tightening residue thresholds for soil-applied synthetics in member-state horticulture sectors. The regulation forces Dutch and Spanish greenhouse operators to substitute fumigant programs with Trichoderma-based protocols. Vegetable export supply chains serving German and French retailers are accelerating biological nematicide certification to maintain shelf access.
Specialty crop procurement officers now require nematode management providers to bundle soil health monitoring with product supply. California Central Valley almond and pistachio growers negotiate multi-year service contracts incorporating root-zone sampling and microbial population tracking. This performance-accountability model displaces transactional chemical purchasing in high-value permanent crop segments.
Bionematicides Market Segmentation
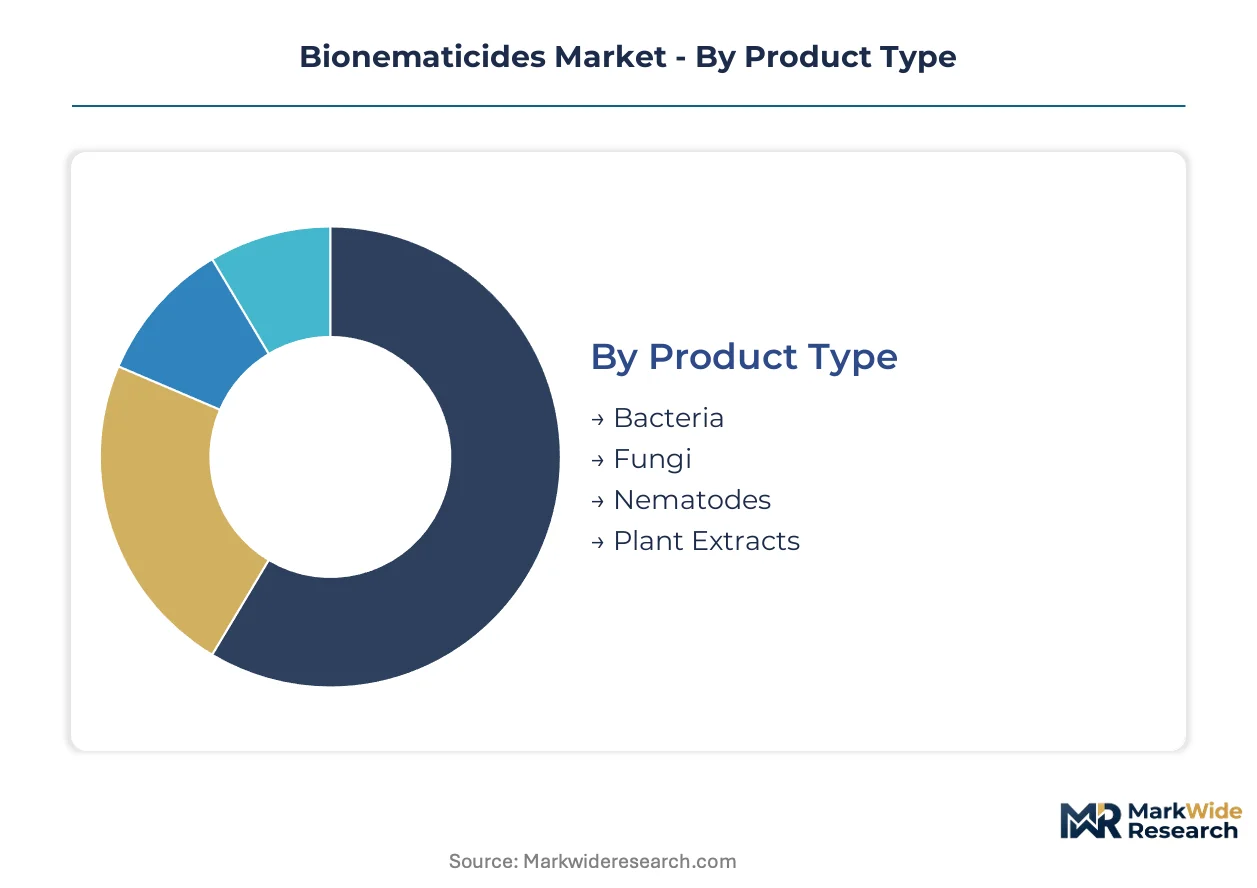
Segmentation in bionematicides reflects divergent regulatory pathways and application economics. Microbial categories face distinct EPA biopesticide registration tiers, while end-user channels determine whether products reach field-scale agriculture or precision greenhouse systems.
Product Type:
Bacterial formulations carry the lightest EPA data requirements under the biopesticide registration framework, while nematode-based products trigger extended ecotoxicity protocols. Fungal and plant-derived segments occupy intermediate certification tiers with variable residue-testing obligations.
- Bacteria:Formulations center on Bacillus firmus and Pasteuria penetrans spore suspensions exceeding 10^8 colony-forming units per milliliter. Demand concentrates in Brazil's Mato Grosso soybean belt where Corteva and Bayer field teams position these as resistance-breakers against soybean cyst nematode. EPA streamlining for microbial actives accelerates strain commercialization timelines.
- Fungi:Trichoderma harzianum and Purpureocillium lilacinum dominate this segment, formulated for multi-year root protection in permanent crops. California Central Valley almond and pistachio growers drive adoption as methyl bromide phase-out compresses fumigant options. Soil pH compatibility constraints limit efficacy in alkaline western US soils.
- Nematodes:Entomopathogenic nematodes formulated for biological control occupy niche greenhouse and high-value vegetable applications. ANVISA registration complexity restricts Brazilian commercial scale for this category.
- Plant Extracts:Botanical nematicides derived from neem and other species face FSSAI residue scrutiny in India's export-oriented horticulture sectors.
Bacteria sits at the top of the volume ranking, with fungi climbing the fastest.
Application:
Application segments split by infrastructure intensity and residue-protocol stringency. Field-scale row crops tolerate higher variability in biological performance, while controlled-environment systems demand zero-failure nematode suppression.
- Agricultural Crops:Corn and soybean acres in Iowa and Illinois pilot metabolite-based seed treatments at commercial planting rates. The segment absorbs volume from fermentation-derived bacterial products displacing synthetic carbamates.
- Ornamental Plants:Nursery operations in Florida and California face tightening EPA soil-fumigant restrictions. Biological alternatives command premium pricing where aesthetic root quality determines crop value.
- Turf:Golf course and sports field maintenance programs in water-restricted US Southwest municipalities adopt microbial nematicides to maintain playability without synthetic runoff concerns.
- Greenhouses:Dutch and Spanish operators under EU Sustainable Use Directive mandates substitute fumigant programs with Trichoderma-based protocols. Vegetable export supply chains serving German retailers accelerate certification to maintain shelf access.
Agricultural crops holds the dominant share position, though greenhouses demonstrate the steepest expansion trajectory.
End User:
End-user economics determine whether biological nematicides enter through capital-intensive service contracts or transactional input purchasing. Scale and technical sophistication shape procurement patterns across farmer categories.
- Farmers:Individual growers in India's Karnataka and Maharashtra protected cultivation sectors seek zero-residue solutions as FSSAI tightens maximum residue limits for export-bound tomatoes and capsicum.
- Agricultural Cooperatives:Brazilian cooperatives in Paraná aggregate demand for resistance-management toolkits combining microbials with synthetic rotation strategies.
- Research Institutions:University extension programs in California and Brazil generate multi-season field trial data required for perennial crop grower adoption in viticulture and tree nut sectors.
- Commercial Growers:California Central Valley almond and pistachio operations negotiate multi-year service contracts incorporating root-zone sampling and microbial population tracking.
Farmers represent the largest addressable base, with commercial growers gaining share fastest through performance-accountability contracting.
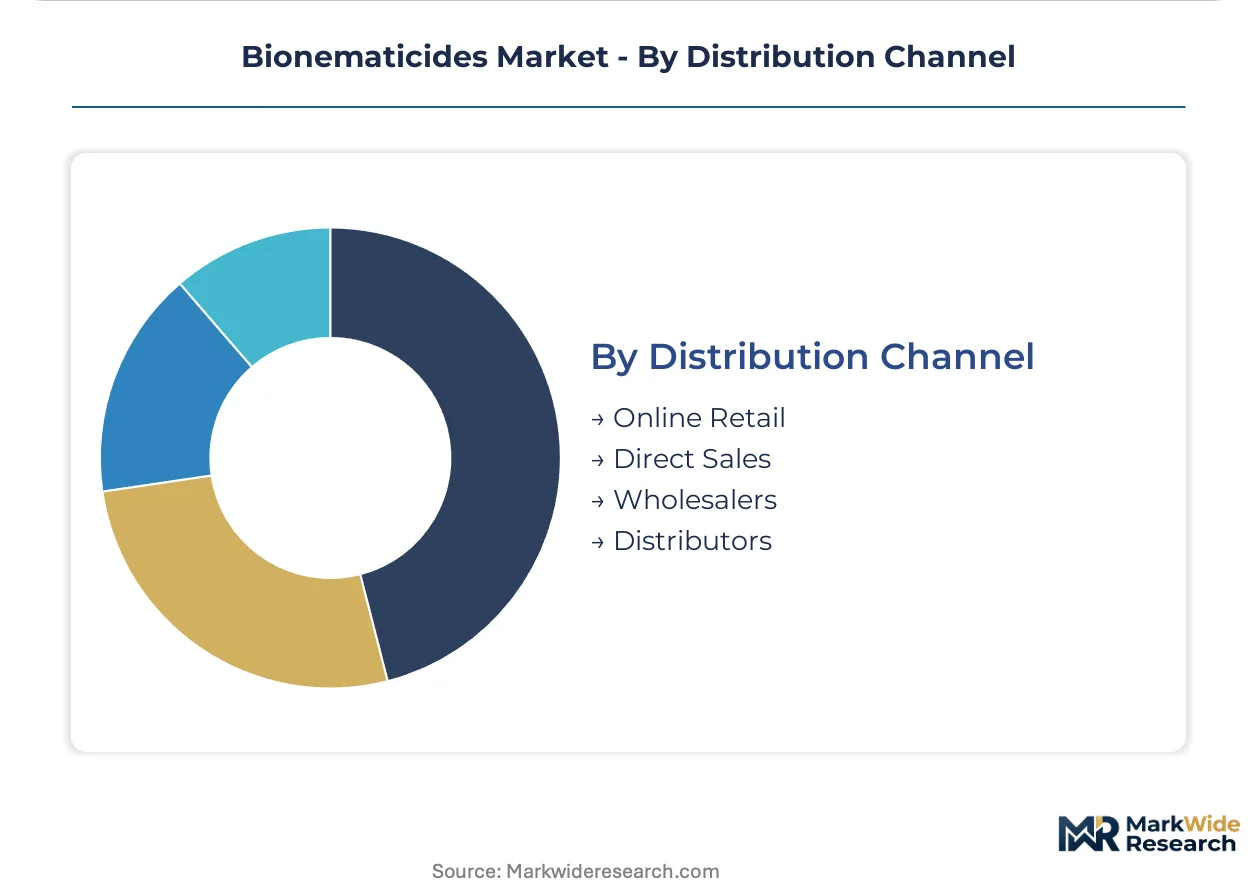
Distribution Channel:
Channel selection reflects product stability requirements and technical support intensity. Spore viability constraints favor shorter supply chains with cold-chain or rapid-turnover characteristics.
- Online Retail:E-commerce platforms serve smallholder greenhouse operators in India with packaged bacterial formulations for protected vegetable cultivation.
- Direct Sales:Corteva and Bayer field teams deploy direct technical salesforces across Brazil's soybean belt to embed microbials into integrated pest management programs.
- Wholesalers:Agricultural input wholesalers in US Midwest corn states handle metabolite-based seed treatment formulations at volume scale.
- Distributors:Specialized biological distributors maintain cold-chain infrastructure for fungal spore suspensions serving California permanent crop sectors.
Direct sales leads in value capture, while online retail expands most quickly in emerging horticulture markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt anchors global bionematicide demand as resistance pressure intensifies against synthetic chemistries. Regulatory compression across major agricultural economies is redirecting capital toward microbial fermentation infrastructure.
United States
California's Central Valley specialty crop growers expand biological nematode control as EPA tightens restrictions on soil fumigants like methyl bromide. The agency's biopesticide registration framework streamlines microbial active ingredient approvals. Iowa and Illinois corn operations pilot metabolite-based seed treatments at commercial planting rates.
Brazil
Intensive glyphosate and synthetic nematicide rotation failures in Mato Grosso and Paraná drive grower willingness to trial microbials as resistance-breaker tools. ANVISA enforces country-specific toxicity thresholds that filter which strains reach commercial scale. Corteva and Bayer field teams embed biologicals into integrated pest management programs across the soybean belt.
India
Protected cultivation of tomatoes, capsicum, and cucurbits in Karnataka and Maharashtra creates demand for zero-residue nematode control. FSSAI tightens maximum residue limits for export-bound produce, forcing biological substitution. The country's national agricultural regulator enforces ecotoxicity standards that favor bacterial formulations over synthetics.
Germany
EU Sustainable Use Directive mandates tighten residue thresholds for soil-applied synthetics in member-state horticulture sectors. Dutch and Spanish greenhouse operators substitute fumigant programs with Trichoderma-based protocols. BASF SE leverages its integrated seed-treatment-to-soil-applied portfolios that bundle bionematicides with conventional chemistries.
Netherlands
Vegetable export supply chains serving German and French retailers accelerate biological nematicide certification to maintain shelf access. The country's greenhouse infrastructure demands zero-failure nematode suppression under stringent residue protocols. Koppert Biological Systems specializes in these controlled-environment systems where zero-residue protocols command price premiums.
Bionematicides Market Vendor Landscape
Global majors compete with regional champions across microbial strain portfolios and fermentation capacity. The vendor base spans consolidated agrochemical conglomerates, specialized biological firms, and emerging fermentation technology providers. Three archetypes dominate: integrated seed-treatment players, standalone microbial specialists, and diversified crop protection conglomerates. Capacity expansion and strategic partnerships represent the primary competitive moves as firms secure master seed bank access and bioreactor scale.
Among integrated agrochemical conglomerates, Corteva Agriscience and Bayer AG occupy positions exemplifying the seed-treatment-anchored archetype, while BASF SE represents the diversified portfolio approach. These firms anchor competitive dynamics through their microbial pipelines and field technical salesforces. Koppert Biological Systems exemplifies the specialized biological systems archetype, concentrating on greenhouse and high-value vegetable segments where zero-residue protocols create pricing power. The competitive terrain rewards firms that combine fermentation scale with application-technology integration.
| Leading Market Players |
|---|
| Corteva Agriscience |
| FMC Corporation |
| BASF SE |
| Koppert Biological Systems |
| Marrone Bio Innovations |
| Bayer AG |
| UPL Limited |
| Novozymes A/S |
| Syngenta AG |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up fermentation specialists in North America and Europe anchor supply discipline through consolidated bioreactor networks, translating molasses and soy-based nutrient media volatility into tiered pricing structures that penalize spot buyers while rewarding multi-year offtake commitments from Brazil's soybean cooperatives and California's permanent crop growers.
Pricing Analysis
Molasses and soy-based nutrient media cost pass-through dominates contract negotiations between bacterial spore producers and agricultural input distributors. Pricing stratifies across premium, standard, and economy tiers based on CFU concentration guarantees and cold-chain integrity certifications. Cost compression in economy-grade bacterial formulations is intensifying because Brazilian formulators face ANVISA registration bottlenecks. Smallholder greenhouse operators in India exhibit highest price sensitivity, while California almond growers negotiating multi-year service contracts demonstrate lowest sensitivity due to performance-accountability bundling.
Supply Chain Analysis
Fermentation scientist shortages in the Netherlands, Germany, and California constrain bioreactor scale-up from laboratory to commercial volumes exceeding 10,000 liters. Master seed banks for Pasteuria penetrans and Purpureocillium lilacinum concentrate in European and North American germplasm repositories, creating single-source vulnerability for Asian and Latin American formulators. Distribution runs through specialized biological distributors maintaining cold-chain infrastructure for fungal spore suspensions serving permanent crop sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bionematicides market functions as a regulatory compounder where EPA biopesticide registration streamlining and EU Sustainable Use Directive mandates mechanically expand addressable demand as methyl bromide phase-out eliminates incumbent chemical alternatives.
For Market Incumbents: Anticipate strain supply concentration risks in European germplasm repositories by securing captive master seed bank access through backward integration into fermentation infrastructure. Defend margin position against metabolite-based biopesticide substitutes by embedding multi-year soil health monitoring services into standard product supply contracts for California Central Valley growers. For New Entrants and Emerging Players: Launch via direct technical salesforces targeting India's Karnataka and Maharashtra protected cultivation sectors where FSSAI residue tightening creates immediate zero-residue substitution demand. Exploit underpenetrated drone-based soil application channels in California orchard and vineyard root zones previously inaccessible to ground equipment. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone microbial specialists lacking seed-treatment integration capabilities relative to integrated agrochemical conglomerates. Acquisition targets should emphasize fermentation scale and master seed bank control. Watch EPA registration timeline compression for novel Bacillus strains as the inflection indicator signaling competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Master Seed Bank Acquisition | Secures strain supply independence from European germplasm repository concentration. |
| Fermentation Capacity Expansion | Enables commercial bioreactor scale-up beyond 10,000 liters for Pasteuria penetrans production. |
| Metabolite Formulation Development | Bypasses spore viability constraints in alkaline western US soils and acidic tropical laterites. |
| Seed-Treatment Integration Partnership | Embeds liquid spore suspensions into standard corn and soybean planting workflows. |
| Carbon Credit Protocol Certification | Positions biological nematicide applications as climate-smart agriculture investments eligible for offset revenue. |
Methodological Framework
Coverage spans North America, Latin America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with fermentation scientists, biological distributor technical sales leads, agricultural cooperative procurement managers, and greenhouse operator agronomists alongside secondary validation through EPA biopesticide registration databases, ANVISA strain approval records, EU Sustainable Use Directive implementation filings, and FSSAI maximum residue limit notifications. Bottom-up strain volume estimates and top-down agricultural input spending triangulation anchor market sizing.
Rate-of-change decomposition separates volume growth from price trajectory across the analysis window. Segmentation dimensions modeled include microbial category, application infrastructure intensity, end-user procurement sophistication, and distribution channel technical support requirements. CAGRs derive from strain adoption curve analysis and replacement rate assumptions for synthetic carbamate and organophosphate nematicides. Forecast inputs incorporate EPA registration pipeline velocity and EU residue threshold tightening schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme soil pH degradation scenarios and master seed bank biosecurity disruptions. Forecasts reflect assumptions regarding regulatory compression continuity and fermentation input cost normalization. Material deviation in EPA biopesticide registration timeline acceleration or EU member-state implementation heterogeneity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Mycelium Market