
 Red Seaweed Extract Market | 2026-2036
Red Seaweed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Red Seaweed Extract Market Analytics
Modular ingredient bundling is recalibrating how food manufacturers procure hydrocolloid systems. CP Kelco leverages its integrated supply chain from raw seaweed to refined carrageenan to sustain pricing leverage across dairy and meat applications. Gelymar anchors its position through specialized agar extraction for pharmaceutical-grade specifications, while Cargill competes via broad distribution networks spanning Latin American and Asian food processors.
Red seaweed extract comprises sulfated polysaccharides—primarily kappa, iota, and lambda carrageenans—harvested from Rhodophyta species and processed through alkaline extraction, filtration, and precipitation into standardized gelling agents with gel strengths ranging from 200 to 1500 g/cm². Carrageenan dominates commercial volumes due to its irreversible thermal gelation in dairy systems, while agar occupies premium tiers where high clarity and low syneresis command margin pools in microbiological media and confectionery. Nutraceuticals represent the fastest-growing product type as marine bioactive peptides gain traction in functional food formulations.
The FDA's GRAS notification pathway and the EU's REACH registration requirements for polymer imports govern market access, with EFSA evaluations on carrageenan safety in infant formula periodically reshaping formulation strategies. Indonesia's national seaweed roadmap and the Philippines' Bureau of Fisheries standards further structure raw material flows through designated coastal cultivation zones. Stakeholders must monitor evolving marine stewardship certifications and regional aquaculture quotas that will determine sustainable supply availability.
Market Dynamics
Clean-label dairy alternatives are forcing hydrocolloid processors to rebuild supply chains around traceable Indonesian seaweed cooperatives rather than spot-market procurement. This demand migration is compressing margins for traders while rewarding integrated extractors with captive cultivation assets.
Growth Catalysts
- EU Green Deal traceability mandates:Sustainable sourcing requirements are redirecting procurement toward certified Indonesian cooperatives with documented chain-of-custody systems.
- Plant-based dairy expansion:Formulators require carrageenan with irreversible thermal gelation to replicate mouthfeel in oat and almond milk applications.
- Pharmaceutical-grade agar specifications:Microbiological media manufacturers are absorbing premium-priced high-clarity extracts with low syneresis thresholds.
Market Restraints
- Input cost volatility:Potassium hydroxide prices fluctuate with energy markets, directly squeezing alkaline extraction margins.
- Supply concentration risk:Sulawesi farming cooperatives control disproportionate raw material flows, creating single-point vulnerability to climate events.
- Substitution threat:Locust bean gum and tara gum are displacing lambda carrageenan in select neutral pH applications.
Strategic Opportunities
- Underpenetrated Brazilian food processing:Latin American meat and dairy manufacturers remain underdeveloped consumers of refined hydrocolloid systems.
- Nutraceutical marine bioactives:Functional food formulators are requesting standardized sulfated polysaccharide fractions for immune-positioned products.
- EU CSRD disclosure requirements:Mandatory sustainability reporting is creating preference premiums for ESG-documented supply chains.
Industry Challenges
- Marine stewardship certification timelines:ASC and MSC accreditation processes extend 18-24 months, delaying market access for new cultivation zones.
- Alkaline extraction capex intensity:Continuous filtration and precipitation equipment requires substantial capital deployment for food-grade compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Seaweed Extract Market |
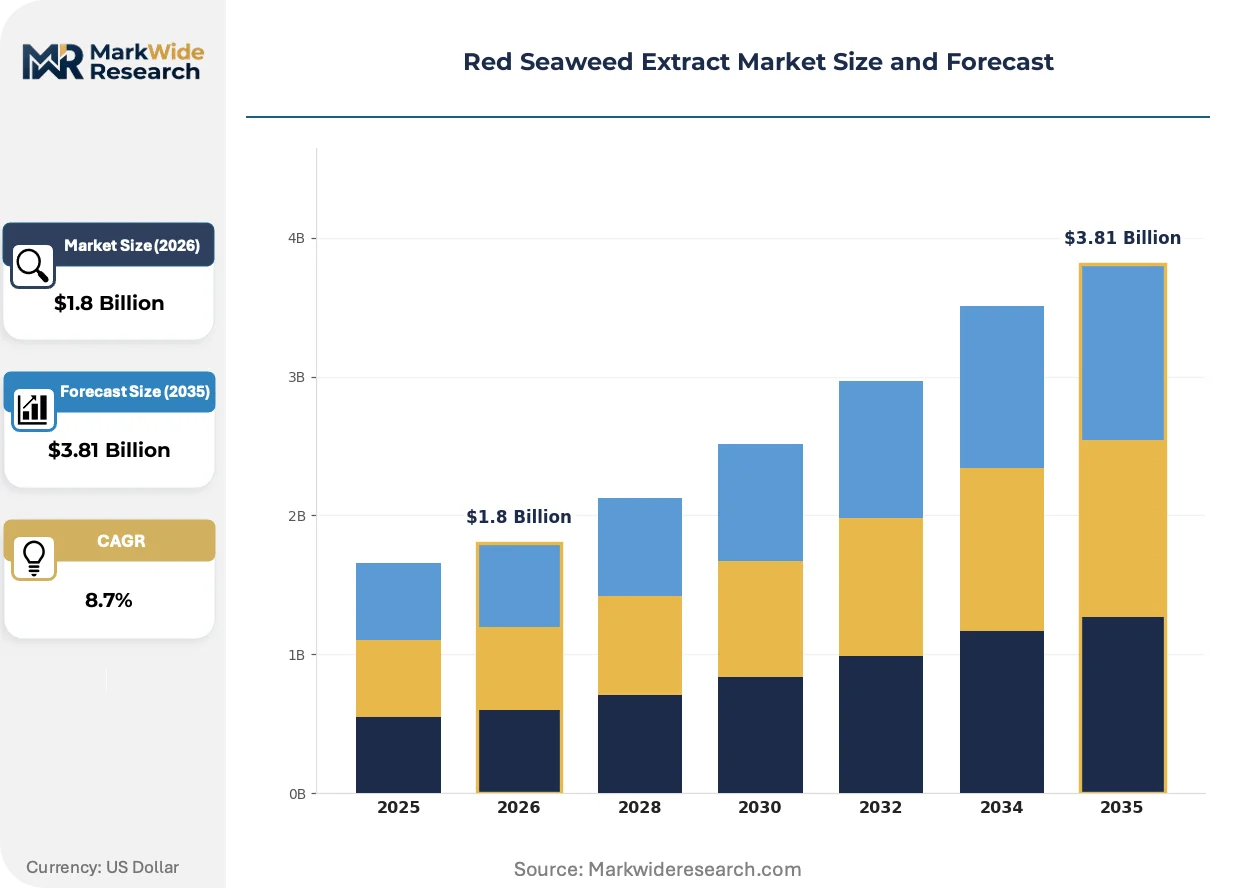
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar, Carrageenan, Alginates, Nutraceuticals End User: Food Industry, Cosmetics Industry, Pharmaceutical Sector, Agriculture Form: Powder, Liquid, Granules, Tablets Application: Food Additives, Thickening Agent, Gelling Agent, Biofertilizers |
| Companies Covered | CP Kelco, Cargill, DuPont, Gelymar, Algaia, Ingredion, Shemberg, Qingdao Nanshan Seaweed, Ceamsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Seaweed Extract Market Evolving Landscape
Enzymatic refinement and precision fermentation are compressing traditional extraction timelines while regulatory disclosure mandates restructure how buyers evaluate supplier credentials.
Membrane filtration technology is consolidating quality differentiation in pharmaceutical-grade agar production. Biotech laboratories in Germany and Switzerland are specifying sub-micron filtered extracts with endotoxin specifications below 10 EU/g. This filtration standard is consolidating supplier tiers, forcing commodity extractors toward captive food-service contracts while premium processors capture microbiological media margins.
EFSA's periodic re-evaluations of carrageenan safety in infant formula are compressing formulation flexibility across European dairy applications. Manufacturers are hedging with dual-source hydrocolloid strategies incorporating gellan gum alternatives. The infant nutrition segment is responding with accelerated clean-label repositioning away from sulfated polysaccharide dependencies.
Direct contracting between end-users and Indonesian farming cooperatives is displacing layered trader networks. Major hydrocolloid processors are establishing technical field offices in Sulawesi to secure volume commitments. This channel compression is most visible in Dutch and Danish dairy alternative manufacturing, where sustainability audit requirements now specify farm-level traceability.
Red Seaweed Extract Market Segmentation
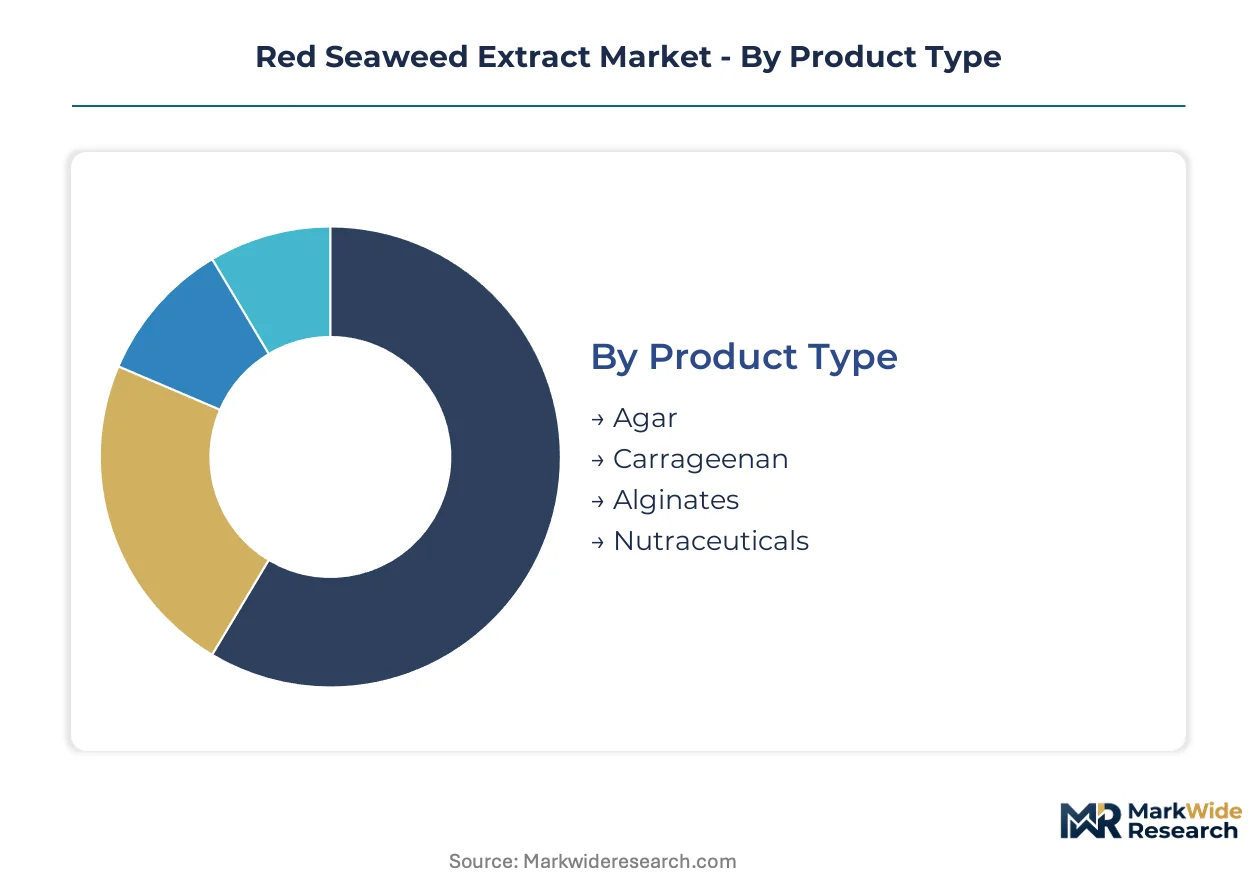
Red seaweed extract procurement patterns diverge sharply across product chemistry and end-use specifications. Formulators select hydrocolloid grades based on gel strength thresholds, thermal stability requirements, and regulatory clearance pathways for target applications.
Product Type:
Chemical structure and sulfation degree determine functional performance across dairy, pharmaceutical, and nutraceutical systems.
- Carrageenan:Kappa, iota, and lambda variants provide irreversible thermal gelation with gel strengths spanning 200 to 1500 g/cm². Dairy alternative manufacturers in the Netherlands and Denmark specify kappa grades for oat milk mouthfeel replication.
- Agar:High-clarity extracts with low syneresis command premium positioning in microbiological media production. German and Swiss biotech laboratories now require sub-micron filtration with endotoxin specifications below 10 EU/g.
- Alginates:Brown seaweed-derived polysaccharides compete in overlapping thickening applications with distinct calcium-reactive gelation profiles.
- Nutraceuticals:Marine bioactive peptide fractions are expanding most quickly as functional food formulators standardize sulfated polysaccharide inputs for immune-positioned products.
Mature deployment sits with carrageenan. Newer deployment is concentrated in nutraceuticals.
End User:
Customer technical requirements range from commodity food-grade compliance to pharmaceutical validation protocols.
- Food Industry:Clean-label dairy alternative processors drive specification tightening around Indonesian cooperative traceability. EFSA safety evaluations periodically reshape infant formula formulation strategies.
- Pharmaceutical Sector:Microbiological media manufacturers absorb premium-priced high-clarity agar with documented endotoxin controls. REACH registration requirements govern polymer import compliance.
- Cosmetics Industry:Personal care formulators utilize carrageenan for texture modification in rinse-off applications with moderate performance thresholds.
- Agriculture:Biofertilizer applications represent emerging demand for sulfated polysaccharide soil amendments with documented microbial activity enhancement.
Volume concentration aligns with food industry procurement. Margin expansion tracks pharmaceutical sector adoption.
Form:
Physical presentation dictates handling economics and dissolution kinetics in downstream processing.
- Powder:Standardized particle size distributions dominate bulk hydrocolloid procurement for dairy and meat processing applications.
- Liquid:Pre-hydrated concentrates reduce processing time for high-throughput beverage manufacturers with continuous production lines.
- Granules:Intermediate flow properties serve specialty confectionery and pet food applications requiring controlled dispersion.
- Tablets:Compressed formats address nutraceutical encapsulation and direct-compression supplement manufacturing.
Powder maintains incumbent position. Liquid formats are gaining share fastest in beverage sector integration.
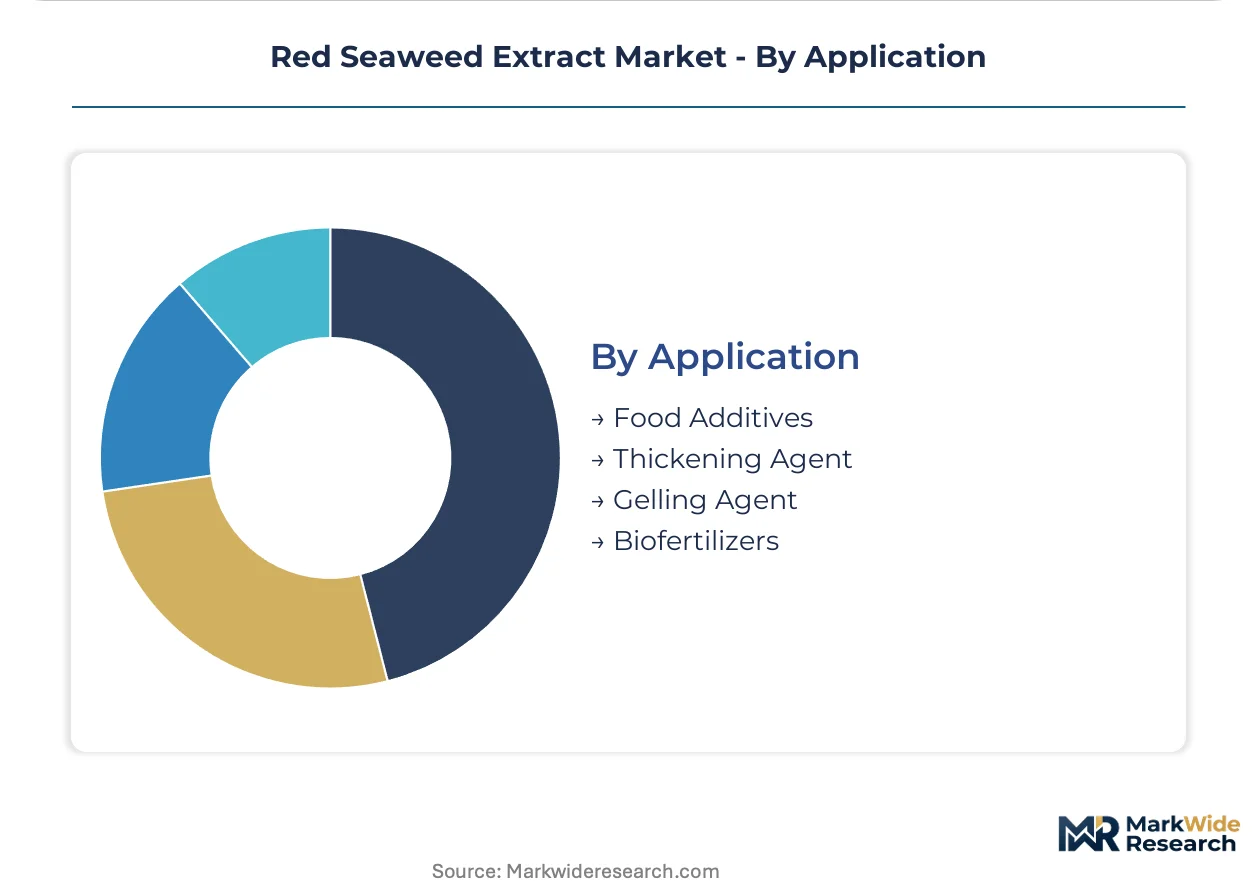
Application:
Functional role determines specification stringency and certification requirements for target use cases.
- Gelling Agent:Irreversible thermal gelation specifications anchor dairy alternative and dessert applications with defined gel strength minimums.
- Thickening Agent:Viscosity-building functionality serves sauces, dressings, and neutral pH systems where locust bean gum substitution threatens lambda carrageenan.
- Food Additives:GRAS notification pathways and EFSA clearance requirements structure market access for direct food contact applications.
- Biofertilizers:Agricultural biostimulant applications leverage polysaccharide film-forming properties for seed coating and soil conditioning.
Established penetration centers on gelling functions. Biofertilizers demonstrate steepest expansion trajectory among application categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia harvests the majority of raw red seaweed while European and North American processors command refined extract value. This geographic split concentrates cultivation risk in Sulawesi farming cooperatives. Downstream formulators in the Netherlands, Denmark, and Germany now mandate farm-level traceability through direct contracting arrangements.
Indonesia
Sulawesi seaweed farming cooperatives supply the bulk of global carrageenan-grade raw material to hydrocolloid processors. The country's national seaweed roadmap designates specific coastal cultivation zones with documented chain-of-custody requirements. Makassar and surrounding South Sulawesi districts host technical field offices established by major extractors seeking volume commitments.
Netherlands
Dutch dairy alternative manufacturers specify kappa carrageenan grades for oat milk mouthfeel replication in clean-label formulations. EFSA safety evaluations on carrageenan in infant formula periodically reshape formulation strategies across the food sector. Rotterdam serves as the primary European import hub for Indonesian seaweed extracts with sustainability audit documentation.
Denmark
Danish plant-based dairy processors drive specification tightening around Indonesian cooperative traceability for ESG compliance. The EU Green Deal's sustainable sourcing mandates redirect procurement toward certified suppliers with documented chain-of-custody systems. Copenhagen-area formulators lead European adoption of direct contracting models that displace layered trader networks.
Germany
German biotech laboratories specify sub-micron filtered agar extracts with endotoxin thresholds below 10 EU/g for microbiological media production. REACH registration requirements govern polymer import compliance for pharmaceutical-grade applications. Hamburg and northern industrial clusters concentrate premium agar processing capacity serving life science markets.
United States
American food additive manufacturers expand carrageenan procurement for clean-label dairy alternatives under FDA GRAS notification pathways. The FDA's regulatory framework structures market access for direct food contact applications. California and Northeast dairy alternative production facilities anchor domestic demand for standardized gelling agents.
Red Seaweed Extract Market Competitive Landscape
The competitive structure tilts toward integrated extractors with captive cultivation assets rather than spot-market traders. Tiered supplier tiers have consolidated around three strategic archetypes: multinational hydrocolloid processors with backward integration into seaweed farming, specialized agar refiners serving pharmaceutical specifications, and regional commodity extractors competing on volume scale. Dominant competitive moves include direct contracting with Indonesian cooperatives to secure traceable supply and membrane filtration technology investments to capture premium pharmaceutical-grade margins.
Among integrated processors with upstream control, CP Kelco represents the captive cultivation archetype through its supply chain spanning raw seaweed to refined carrageenan. Cargill occupies a position exemplifying broad distribution network competition across Latin American and Asian food processing markets. Gelymar sits within the specialized refinement tier, anchoring premium positioning through pharmaceutical-grade agar extraction capabilities. These three company profiles illustrate how competitive advantage increasingly depends on traceability documentation and filtration technology rather than commodity volume alone.
| Leading Market Players |
|---|
| CP Kelco |
| Cargill |
| DuPont |
| Gelymar |
| Algaia |
| Ingredion |
| Shemberg |
| Qingdao Nanshan Seaweed |
| Ceamsa |
| Others |
Value Network & Pricing Analysis
EU Green Deal traceability mandates are forcing hydrocolloid processors to abandon spot-market procurement in favor of certified Indonesian cooperatives with documented chain-of-custody systems, compressing trader margins while rewarding integrated extractors with captive cultivation assets and pricing leverage.
Pricing Analysis
Margin tightening in commodity carrageenan reflects potassium hydroxide cost volatility tied to energy markets. Pricing stratifies across pharmaceutical-grade agar, food-grade carrageenan, and industrial alginates based on filtration standards and endotoxin specifications. Cost-down pressure on lambda carrageenan intensifies because locust bean gum substitution threatens neutral pH applications. Dairy alternative manufacturers show lowest price sensitivity; commodity food processors show highest.
Supply Chain Analysis
Single-source vulnerability sits with Sulawesi farming cooperatives controlling disproportionate raw material flows. Supply draws from Indonesia, the Philippines, and Tanzania for red seaweed biomass. Potassium hydroxide, membrane filtration equipment, and precipitation chemicals constitute critical input dependencies. Climate event exposure in South Sulawesi creates structural risk. Distribution runs through Rotterdam and Hamburg as primary European import hubs with sustainability audit documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's CSRD disclosure requirements and REACH registration mandates for polymer imports have erected a cost-of-compliance barrier that rewards incumbent extractors with existing certification infrastructure while filtering out undercapitalized commodity traders.
For Market Incumbents: Extend backward integration into Indonesian cultivation zones through technical field office deployments that secure volume commitments under direct contracting arrangements. Deepen membrane filtration capabilities to capture pharmaceutical-grade agar premiums as microbiological media specifications tighten. Defend against gellan gum substitution in infant formula by accelerating clean-label repositioning investments. For New Entrants and Emerging Players: Brazilian meat and dairy processors represent the most penetrable white-space target given underdeveloped hydrocolloid adoption in Latin American food manufacturing. Nutraceutical marine bioactives offer secondary entry path through standardized sulfated polysaccharide fractions for immune-positioned functional foods. Partner with Dutch or Danish dairy alternative formulators seeking farm-level traceability compliance. For Investors and Strategic Acquirers: Re-rating potential sits with specialized agar refiners possessing sub-micron filtration capabilities given EFSA safety evaluation cycles reshaping European formulation strategies. Five-to-ten-year viability favors processors with captive Indonesian supply rather than trader-dependent competitors. Monitor ASC and MSC certification timelines as inflection indicator for new cultivation zone market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | CP Kelco's captive cultivation model secures traceable supply chains for EU Green Deal compliance. |
| Membrane Filtration Technology Investment | German biotech laboratories now demand sub-micron agar extracts with endotoxin thresholds below 10 EU/g. |
| Direct Cooperative Contracting | Dutch and Danish dairy alternative manufacturers bypass layered trader networks for farm-level traceability. |
| Pharmaceutical-Grade Certification Pathway | REACH registration requirements govern polymer import compliance for life science applications. |
| Nutraceutical Bioactive Fraction Development | Functional food formulators standardize sulfated polysaccharide inputs for immune-positioned products. |
Research Methodology
Trade databases, regulatory filings, and industry association reports formed the secondary backbone for this analysis. Primary fieldwork engaged hydrocolloid procurement managers at dairy alternative manufacturers, technical directors at Indonesian seaweed cooperatives, pharmaceutical-grade agar specification officers at German biotech laboratories, and sustainability compliance leads at Dutch food processors. Bottom-up volume estimates triangulated against top-down value projections derived from customs records and extraction capacity assessments.
Historical trendline analysis established baseline growth patterns across carrageenan, agar, and nutraceutical product categories. The analytical framework modeled segmentation dimensions including sulfation degree chemistry, end-use industry specifications, physical form factors, and functional application roles throughout the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EFSA safety evaluation impacts and EU CSRD disclosure adoption curves.
Caveats apply where EFSA carrageenan safety re-evaluations, Indonesian aquaculture quota adjustments, or potassium hydroxide energy market volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding certification timeline completion and cooperative contract renewal rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Genistein Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Casein Peptone Market