
 Europe Bioethanol Market | 2026-2036
Europe Bioethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bioethanol Market Foresight
Project finance tied to EU green bond frameworks is rewriting capital access for bioethanol producers across the continent. CropEnergies AG leverages its integrated grain-to-ethanol model to sustain margin control from feedstock through distribution. VERBIO AG anchors its position through advanced biogas and bioethanol co-production at its German facilities. Tereos SCA competes via its extensive beet sugar processing network in France and Belgium.
Bioethanol denotes ethanol produced from biological feedstocks such as corn, wheat, or sugar beet, typically refined to purity levels exceeding 99% for fuel applications or lower grades for industrial solvents. Fuel ethanol dominates volume flows across European blending pools, while industrial ethanol commands premium pricing in pharmaceutical and cosmetic solvent markets. Wheat-based production occupies significant capacity in Central Europe, whereas barley feedstocks are gaining traction in Nordic regions with limited corn cultivation.
The EU Green Deal, the revised Renewable Energy Directive, and the F-Gas Regulation collectively mandate escalating renewable content in transport fuels and restrict high-global-warming-potential alternatives. EMA and national regulators in Germany and France enforce sustainability certification through mass-balance chain-of-custody requirements. Stakeholders must monitor feedstock cost volatility against carbon credit pricing mechanics to calibrate long-term capacity commitments.
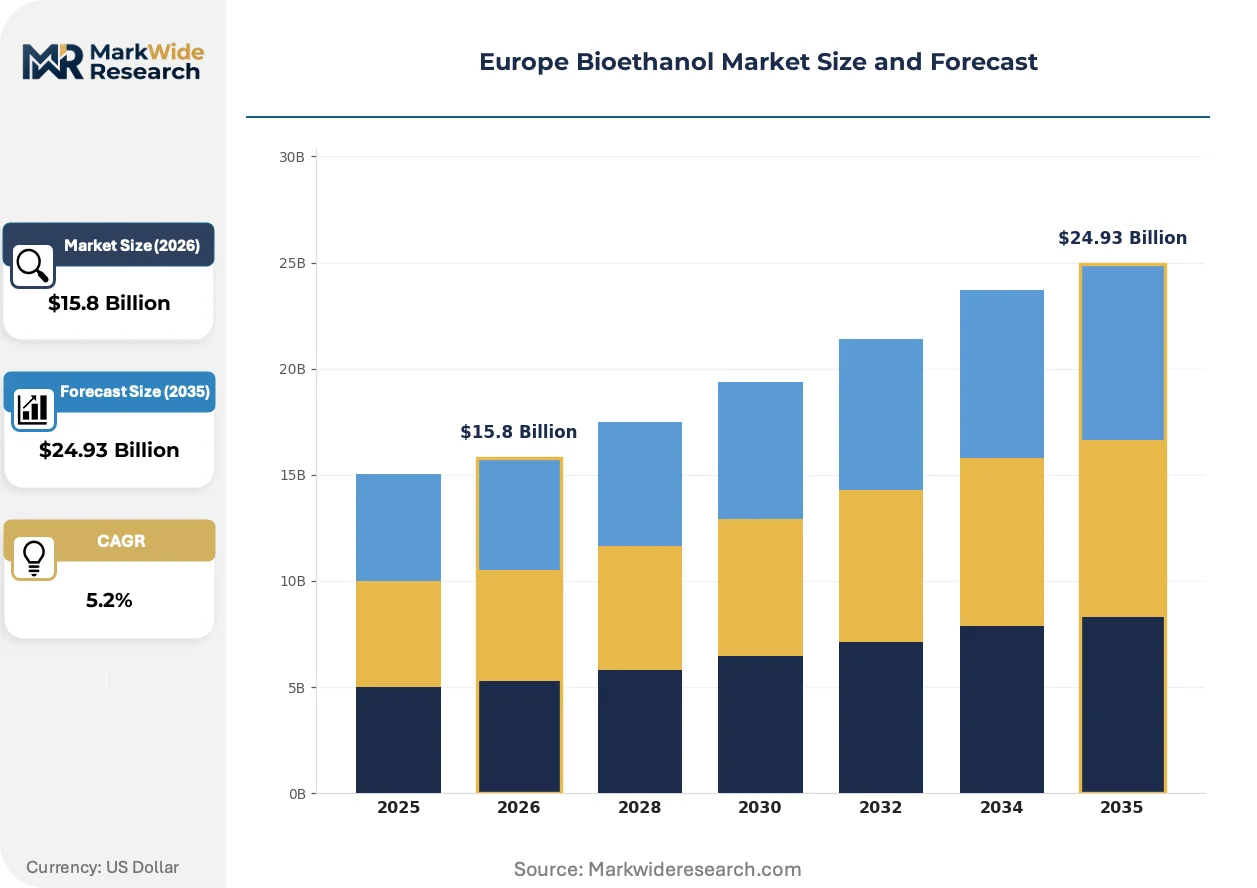
Market Dynamics
The EU Green Deal's escalating carbon intensity thresholds for transport fuels are compressing refining margins and forcing capacity reconfiguration across European bioethanol producers. Feedstock cost volatility against carbon credit pricing mechanics now dictates investment timing and technology selection.
Growth Catalysts
- EU Green Deal mandates:The revised Renewable Energy Directive tightens renewable content requirements for transport fuels, compelling refiners to expand bioethanol blending volumes.
- German biofuel quota schemes:National blending obligations concentrate demand through strategic infrastructure investments, anchoring volume flows in Central Europe.
- Advanced biogas co-production:Integrated fermentation systems capture waste heat and CO2 streams, improving plant-level energy efficiency and margin structure.
Market Restraints
- Wheat feedstock volatility:Central European grain prices swing with weather patterns and Black Sea supply disruptions, squeezing producer margins.
- F-Gas Regulation restrictions:Limits on high-global-warming-potential alternatives create technical friction in certain industrial solvent applications.
- First-generation technology lock-in:Existing starch-to-ethanol assets face stranded risk as cellulosic pathways mature, constraining capital redeployment.
Strategic Opportunities
- Nordic barley feedstocks:Sweden and Finland cultivate limited corn but maintain barley surpluses, opening regional production capacity.
- Pharmaceutical solvent grades:Premium purity ethanol for vaccine and API manufacturing commands pricing multiples above fuel applications.
- EU green bond frameworks:Project finance through sustainable debt instruments lowers cost of capital for capacity expansion.
Industry Challenges
- Mass-balance certification complexity:EMA and national regulators enforce chain-of-custody documentation that strains legacy tracking systems.
- Biorefinery capex intensity:Fermentation train upgrades and distillation column expansions require multi-year payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bioethanol Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $24.93 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Ethanol, Industrial Ethanol, Beverage Ethanol, Extractive Ethanol Feedstock: Corn, Sugarcane, Wheat, Barley Application: Transportation, Food & Beverage, Pharmaceuticals, Cosmetics Distribution Channel: Direct Sales, Retail, Wholesale, E-commerce |
| Companies Covered | Pannonia Bio Zrt., Vertex Bioenergy, CropEnergies AG, St1, British Sugar, Tereos SCA, Lantmännen Agroetanol, AGRANA, VERBIO AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bioethanol Market Shifts & Advancements
Digital process control and advanced analytics are reshaping how European bioethanol producers optimize fermentation yields and energy consumption. Three developments are compressing operational variance and redefining competitive position.
Process analytical technology (PAT) is digitizing real-time monitoring of yeast health and sugar conversion rates. German and French refiners deploy spectroscopic sensors and machine learning models to adjust pH and temperature setpoints automatically. This compression of batch-to-batch variability is reducing off-spec production and energy overconsumption.
The EU's Corporate Sustainability Reporting Directive now mandates granular Scope 3 emissions disclosure for fuel suppliers. This regulatory burden forces bioethanol producers to deploy blockchain-enabled traceability systems from farm to pump. French beet processors and German grain distillers are investing most heavily to secure REDcert and ISCC sustainability certifications ahead of enforcement deadlines.
Fleet operators in the Netherlands and Belgium are consolidating procurement through long-term offtake agreements with fixed carbon intensity clauses. This contractual innovation shifts volume risk onto producers while guaranteeing blenders price stability. The model is displacing spot-market purchasing in coastal logistics hubs where marine fuel blending dominates.
Europe Bioethanol Market Segmentation
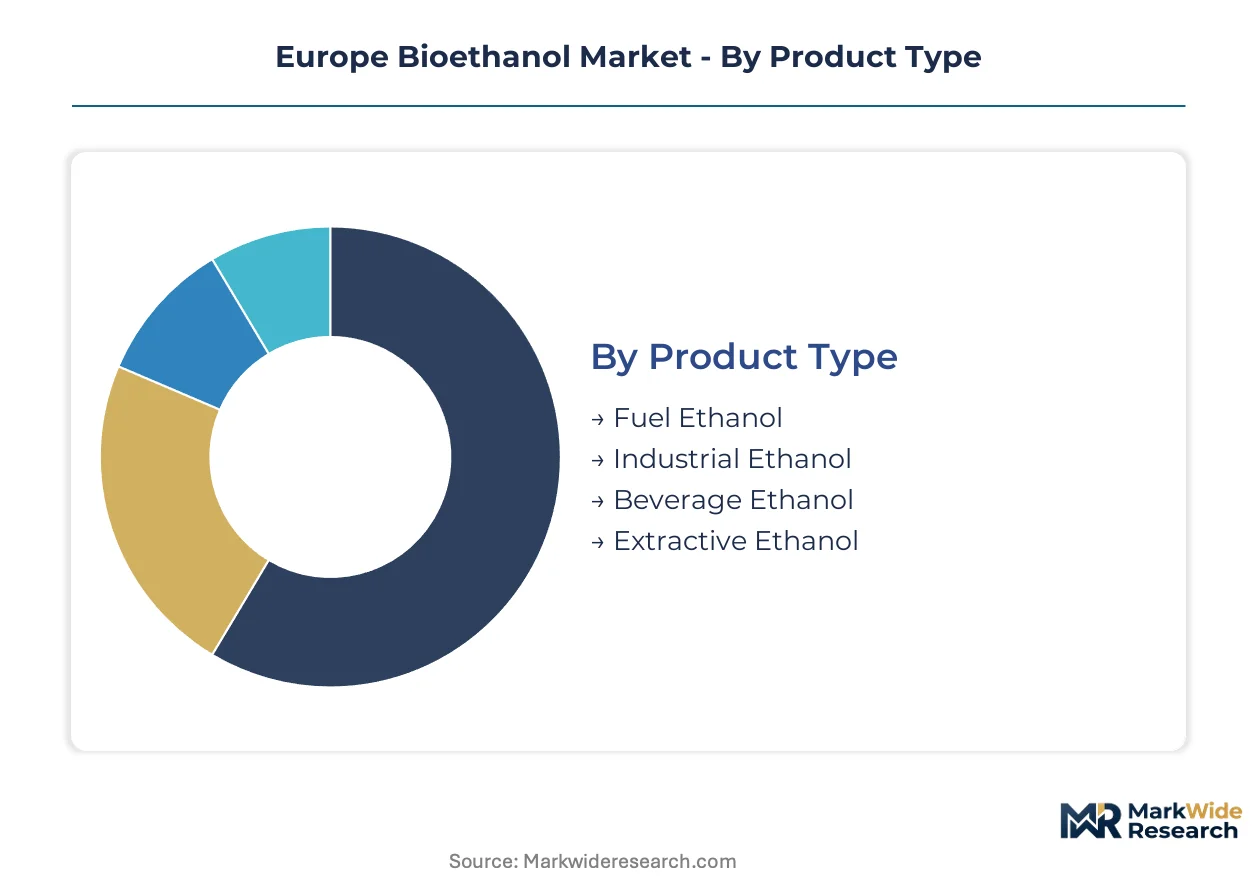
Segmentation reveals how EU regulatory mandates and feedstock geography split value capture across the European bioethanol value chain. Producers calibrate product purity grades and distribution models against diverging margin structures in fuel versus industrial applications.
Product Type:
Mature fuel-grade volumes dominate throughput while emerging specialty grades command premium positioning.
- Fuel Ethanol:Refined to minimum 99% purity for blending with gasoline at rates up to E10 or E85. German and French refiners concentrate demand through national quota schemes that mandate renewable content thresholds. The EU Green Deal's tightening carbon intensity targets force continuous volume expansion.
- Industrial Ethanol:Lower purity grades serve solvent applications in pharmaceutical API manufacturing and cosmetic formulation. Belgian and Dutch chemical clusters anchor demand where REACH compliance restricts petrochemical alternatives.
- Beverage Ethanol:Food-grade production for spirits manufacturing carries excise tax complications that vary by member state.
- Extractive Ethanol:Specialist grades for botanical and herbal extraction processes serve niche pharmaceutical and nutraceutical supply chains.
Fuel ethanol handles the majority of throughput; industrial ethanol is the fastest mover on share.
Feedstock:
Cost tier structures align with regional agricultural endowments and import dependency ratios.
- Wheat:Dominates Central European capacity with established grain-to-ethanol infrastructure across Germany and Poland. Black Sea supply disruptions and weather volatility squeeze margin predictability for starch-based producers.
- Corn:Higher starch conversion efficiency drives adoption where cultivation permits, particularly in Hungarian and Romanian processing corridors.
- Barley:Nordic surplus regions in Sweden and Finland deploy this feedstock where corn cultivation faces climatic limits.
- Sugarcane:Import-dependent pathway subject to EU sustainability certification requirements under REDcert and ISCC mass-balance schemes.
Wheat commands the largest installed base; barley is expanding most quickly as Nordic capacity comes online.
Application:
Volume concentration versus margin premium splits the addressable market into diverging strategic postures.
- Transportation:Fleet operators and oil majors drive bulk procurement through long-term offtake agreements with fixed carbon intensity clauses. Marine fuel blending in Rotterdam and Antwerp logistics hubs concentrates coastal demand.
- Pharmaceuticals:Vaccine and active pharmaceutical ingredient manufacturing requires premium purity grades that command pricing multiples above fuel applications.
- Cosmetics:Formulation-grade ethanol for personal care products faces F-Gas Regulation restrictions that create technical friction in solvent selection.
- Food & Beverage:Spirits production and food processing applications carry member-state-specific excise regimes that complicate cross-border supply planning.
Transportation absorbs the dominant volume share; pharmaceuticals shows the steepest expansion trajectory on value per liter.
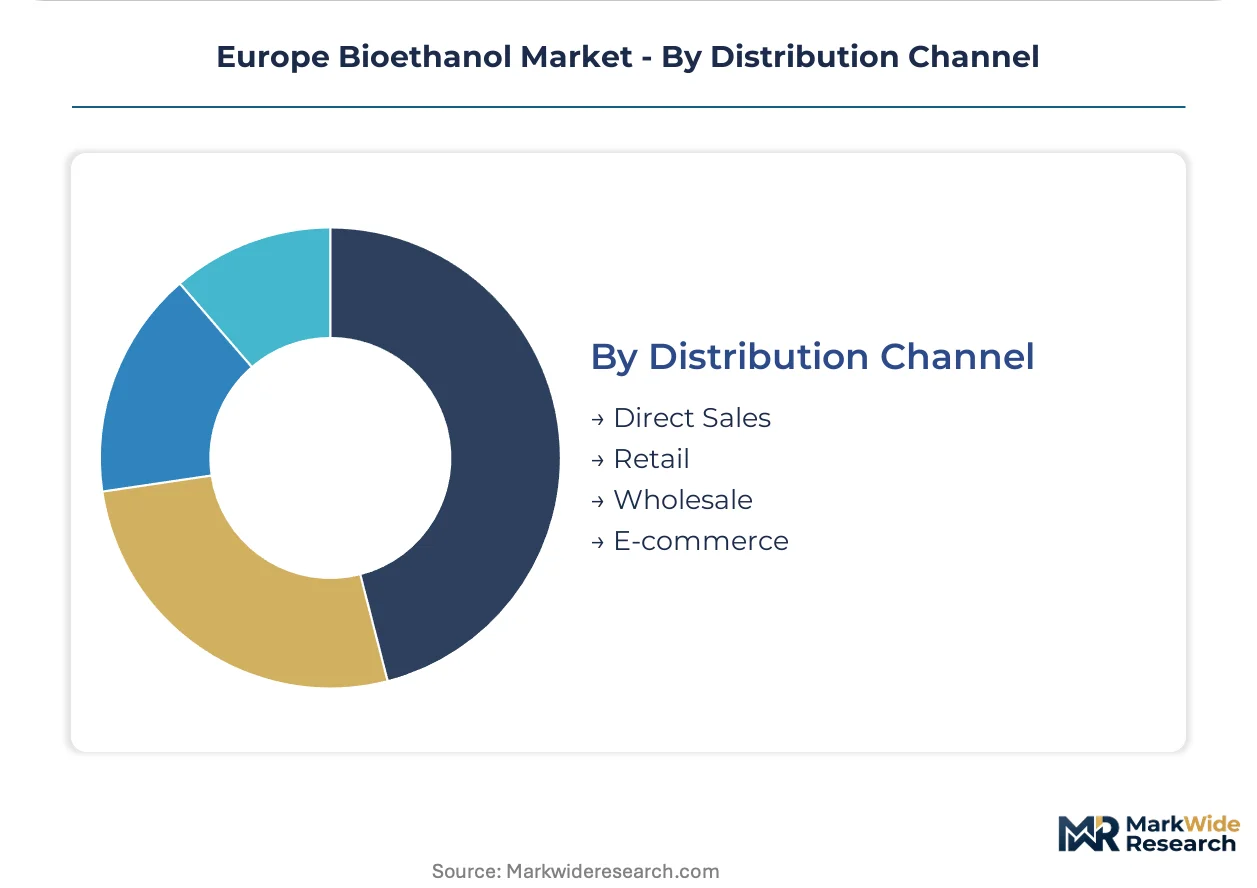
Distribution Channel:
Customer scale and certification requirements determine channel selection across the value chain.
- Direct Sales:Integrated producers supply refiners and chemical majors through pipeline-connected terminals and dedicated tanker arrangements.
- Wholesale:Regional distributors aggregate smaller blender demand across Central European inland markets.
- Retail:Specialty chemical and laboratory supply houses serve pharmaceutical and cosmetic formulators requiring documentation packages.
- E-commerce:Emerging channel for specialty grades and small-batch industrial solvents where documentation digitization reduces transaction friction.
Direct sales captures the bulk of literage; e-commerce is gaining share fastest among specialty grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's tightening carbon intensity thresholds are redistributing bioethanol investment across member states with varying feedstock endowments and refining infrastructure. National blending mandates and sustainability certification requirements now determine where capacity expansion concentrates.
Germany
Domestic biofuel quota schemes under the Federal Immission Control Act sustain demand concentration in Central Europe. The KBA enforces sustainability certification through REDcert mass-balance requirements that strain legacy tracking systems. The Zeitz biorefinery corridor and Mannheim processing cluster anchor starch-to-ethanol capacity expansion.
France
Beet sugar processing networks in the Champagne-Ardenne and Picardy regions leverage established agricultural supply chains. ANSM and national regulators enforce REACH compliance for industrial solvent grades serving pharmaceutical clusters near Lyon and Strasbourg. Tereos SCA facilities exemplify integrated beet-to-ethanol production.
Spain
Strategic refining infrastructure investments in Castilla y León and Andalusia exploit wheat and barley cultivation zones. National renewable energy mandates align with EU Green Deal trajectories. The Salamanca biorefinery complex processes regional grain surpluses into fuel ethanol for Iberian blending pools.
Sweden
Nordic barley feedstocks substitute for corn in climatic conditions that limit starch crop cultivation. Lantmännen Agroetanol facilities near Norrköping demonstrate regional adaptation of fermentation technology. The country's national energy agency enforces sustainability criteria that exceed baseline EU requirements.
Netherlands
Rotterdam and Antwerp logistics hubs concentrate marine fuel blending demand through long-term offtake agreements. The Human Environment and Transport Inspectorate enforces chain-of-custody documentation for biofuel imports. Coastal terminals handle bulk flows from Central European producers and overseas suppliers.
Europe Bioethanol Market Competitive Landscape
On the supply side, the industry is consolidating around integrated grain processors and specialized biorefinery operators with captive feedstock access. Three archetypes dominate: starch-based distillers with backward integration into grain trading, beet sugar processors with seasonal co-production flexibility, and biogas-ethanol hybrid operators capturing waste stream value. Capacity expansion and sustainability certification investments represent the dominant competitive moves as carbon intensity thresholds tighten.
Among Central European integrated producers, CropEnergies AG and VERBIO AG exemplify divergent strategic postures. CropEnergies AG represents the grain-to-ethanol archetype with Zeitz facility concentration. VERBIO AG anchors the biogas-ethanol co-production model at German sites. Tereos SCA occupies the beet sugar processor position through French and Belgian network density. These three structures illustrate how feedstock geography and regulatory compliance capabilities determine competitive position.
| Leading Market Players |
|---|
| Pannonia Bio Zrt. |
| Vertex Bioenergy |
| CropEnergies AG |
| St1 |
| British Sugar |
| Tereos SCA |
| Lantmännen Agroetanol |
| AGRANA |
| VERBIO AG |
| Others |
Supply & Pricing Matrix
Undercapacity in Nordic barley-to-ethanol processing is tightening supplier leverage across northern Europe while German wheat-based facilities contend with margin compression from Black Sea supply disruptions. This utilization asymmetry between feedstock regions shapes how producers negotiate long-term offtake terms and calibrate spot-market exposure.
Pricing Analysis
Certification level under REDcert and ISCC mass-balance schemes creates the primary spread between fuel-grade and pharmaceutical-grade ethanol in European markets. Three-tier pricing structure across premium pharmaceutical, standard industrial, and economy fuel grades segments buyer willingness-to-pay. Cost compression in fuel-grade volumes is intensifying because wheat feedstock volatility outpaces carbon credit pricing mechanics. Fleet operators and marine blenders exhibit highest price sensitivity; vaccine manufacturers show lowest sensitivity due to purity requirements.
Supply Chain Analysis
EU sustainability certification requirements under the F-Gas Regulation and revised Renewable Energy Directive limit flows of non-compliant feedstocks into European processing corridors. Supply concentrates in Germany, France, and Spain where established grain-to-ethanol infrastructure anchors capacity. Raw material dependencies rest on Black Sea wheat, domestic beet sugar, and Nordic barley surpluses. Single-source vulnerability in Ukrainian grain imports poses structural risk. Distribution runs through Rotterdam and Antwerp marine terminals for coastal blending, with pipeline-connected terminals serving inland refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the European bioethanol landscape as the EU Green Deal's carbon intensity tiering creates distinct compliance niches for feedstock-specific producers. Diverging national quota schemes and certification timelines reward specialized positioning over scale.
For Market Incumbents: Pre-empt cellulosic pathway maturation by securing captive barley supply contracts in Sweden and Finland before Nordic capacity expansion accelerates. Defend margin position through backward integration into grain trading operations that buffer wheat price volatility. Prioritize REDcert-plus certification investments to capture pharmaceutical-grade premium tiers before enforcement deadlines tighten. For New Entrants and Emerging Players: Pursue pharmaceutical solvent grade production in Belgian and Dutch chemical clusters where REACH compliance restricts petrochemical alternatives and premium purity commands pricing multiples. Target extractive ethanol for botanical and nutraceutical supply chains as the fastest-penetrable specialty segment. Deploy blockchain-enabled traceability systems as a differentiated go-to-market angle for sustainability-conscious formulators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biogas-ethanol co-production facilities where waste heat capture systems require multi-year payback periods. Long-term viability over the coming decade hinges on positioning within integrated fermentation platforms rather than standalone starch-to-ethanol assets. Target acquisition archetype: Nordic barley processors with established sustainability certifications and pipeline access to coastal marine blending hubs. The signal to watch is carbon credit pricing convergence against wheat feedstock futures as an inflection indicator for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Trading | CropEnergies AG and similar integrated producers buffer margin volatility through captive feedstock sourcing. |
| REDcert-Plus Certification Investment | French beet processors secure pharmaceutical-grade market access ahead of EU Green Deal enforcement deadlines. |
| Nordic Barley Capacity Expansion | Lantmännen Agroetanol facilities demonstrate regional adaptation where climatic limits constrain corn cultivation. |
| Blockchain Traceability Deployment | German grain distillers meet Corporate Sustainability Reporting Directive Scope 3 disclosure requirements. |
| Long-Term Offtake Agreements | Netherlands and Belgium fleet operators consolidate procurement through fixed carbon intensity clauses. |
Research Methodology
Cross-validation between primary interviews with biorefinery plant managers, grain procurement leads at integrated processors, downstream fuel blenders, and EPC contractors anchors the qualitative findings. Secondary validation draws from EU customs/trade data, REDcert and ISCC certification registries, national biofuel quota filings under the Federal Immission Control Act, and corporate sustainability disclosures under the CSRD. Bottom-up capacity modeling triangulates against top-down demand projections from transportation fleet electrification scenarios.
Calibration against historical capacity utilization rates and feedstock price volatility bands informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product purity grade, feedstock type, application end-use, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines. Industry-specific forecast inputs incorporate carbon credit pricing mechanics and wheat futures volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cellulosic pathway developers or Black Sea supply disruption responses would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
China Biopesticides Market