
 Bacillus Coagulans Market | 2026-2036
Bacillus Coagulans Market Size, Share, and Industry Trends Forecast 2026-2036
Bacillus Coagulans Market Analysis
Subscription-based formulation support is repositioning how probiotic suppliers monetize Bacillus coagulans beyond raw ingredient sales. Sanzyme Biologics leverages its Indian manufacturing base to supply heat-stable strains for beverage applications. Kerry Group anchors European demand through integrated probiotic solutions for functional food brands. Sabinsa Corporation differentiates via patented extraction processes that enhance spore viability in finished products.
Bacillus coagulans is a Gram-positive, spore-forming bacterium that survives gastric acid and bile salts, enabling shelf-stable probiotic delivery without refrigeration through pH-resistant endospore structures. The organism primarily serves gastrointestinal health applications, immune modulation, and protein assimilation in human and animal nutrition. Powdered form dominates production volumes due to blending flexibility across bakery, beverage, and supplement matrices, while capsules capture premium positioning in pharmaceutical channels. Functional foods represent the fastest-expanding application as brands embed probiotics into everyday consumption occasions, though dietary supplements retain the deepest margin pools through direct-to-consumer pricing power.
FDA GRAS notifications govern probiotic safety claims in the United States, while EFSA novel food assessments shape European market access timelines for new strain submissions. India's FSSAI and CDSCO jointly regulate probiotic health claims and pharmaceutical-grade formulations, creating dual compliance pathways for domestic suppliers. Stakeholders must monitor evolving strain-specific clinical evidence requirements as regulators distinguish between generic and characterized probiotic identities.
Market Dynamics
Heat-stable spore technology is compressing cold-chain dependency across probiotic value chains, forcing reformulation partnerships between ingredient suppliers and beverage manufacturers seeking ambient distribution economics.
Growth Catalysts
- Clean-label dairy alternatives:Plant-based milk and yogurt brands in the United States embed Bacillus coagulans to match conventional probiotic claims without refrigeration infrastructure.
- FDA GRAS notifications:Streamlined safety determinations accelerate strain-specific approvals, reducing time-to-market for functional food launches.
- Spore-forming advantage:The organism's endospore structures survive gastric acid and bile salts, enabling shelf-stable delivery formats that lyophilized lactobacilli cannot match.
Market Restraints
- Strain characterization costs:EFSA novel food assessments require whole-genome sequencing and clinical dossiers that burden small suppliers with six-figure compliance investments.
- Fermentation substrate volatility:Glucose and soy peptone prices fluctuate with agricultural commodity cycles, squeezing contract manufacturing margins.
- Single-strain dependence:Most commercial products rely on GBI-30 or MTCC 5856, creating genetic bottleneck risk if resistance or contamination emerges.
Strategic Opportunities
- Pet nutrition expansion:Premium dog and cat food manufacturers in Germany and Japan are embedding spore probiotics for digestive health positioning.
- Sports nutrition convergence:Protein powder brands combine Bacillus coagulans with whey isolates to claim reduced bloating and improved amino acid absorption.
- Indian PLI scheme:Domestic fermentation capacity incentives under the Production Linked Incentive program attract contract manufacturing investment for export markets.
Industry Challenges
- CFU stability validation:Finished product manufacturers struggle to demonstrate viable spore counts through 24-month shelf life under variable humidity conditions.
- Cross-contamination protocols:Multi-strain facilities face audit complexity when Bacillus coagulans spores persist in equipment despite standard CIP procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacillus Coagulans Market |
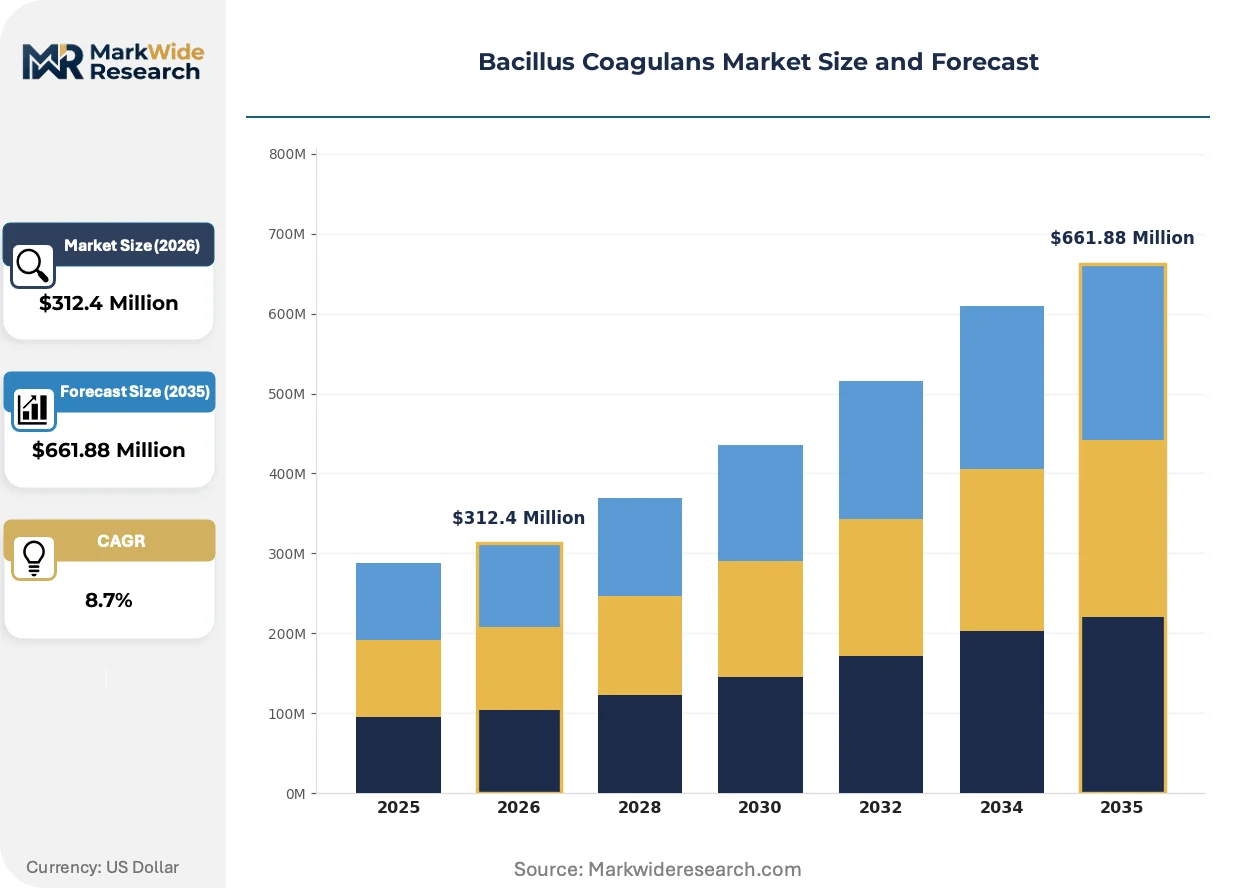
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Form, Liquid Form, Capsules, Tablets Application: Probiotics, Dietary Supplements, Functional Foods, Animal Feed End User: Healthcare, Food & Beverages, Animal Nutrition, Pharmaceutical Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Sanzyme Biologics, UAS Laboratories, Kerry Group, Syngen Biotech, WECARE-PROBIOTICS, Sabinsa Corporation, Unique Biotech Limited, Nebraska Cultures, Mitsubishi Chemical Foods Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacillus Coagulans Market Emerging Trajectories
Bioprocess engineering and regulatory science are converging to expand addressable applications beyond traditional supplement formats into mainstream food matrices.
Continuous fermentation technology is automating seed train operations that previously required manual inoculation and batch monitoring. Mid-scale ingredient suppliers in Denmark and the Netherlands deploy single-use bioreactors with real-time biomass sensors, cutting production cycle times from 72 to 48 hours. This compression is automating capacity expansion decisions and reducing minimum viable scale thresholds for regional entrants.
EFSA's 2023 guidance on qualified presumption of safety for bacterial strains tightens whole-genome toxicity screening requirements. European functional food brands now demand CRISPR-based deletion documentation for antibiotic resistance genes before contract execution. Dairy alternative manufacturers in France and the Netherlands absorb 12-18 month assessment timelines into product development roadmaps, prioritizing characterized strains with existing dossiers over novel isolates.
Direct-to-consumer subscription models are fragmenting bulk ingredient procurement patterns. Smaller supplement brands bypass traditional distributors to source spore powders through digital B2B marketplaces with certificate-of-analysis transparency. This channel shift concentrates in the United States and United Kingdom where e-commerce penetration in wellness categories exceeds 35 percent, forcing legacy suppliers to unbundle minimum order quantities and offer flexible packaging formats.
Bacillus Coagulans Market Segmentation
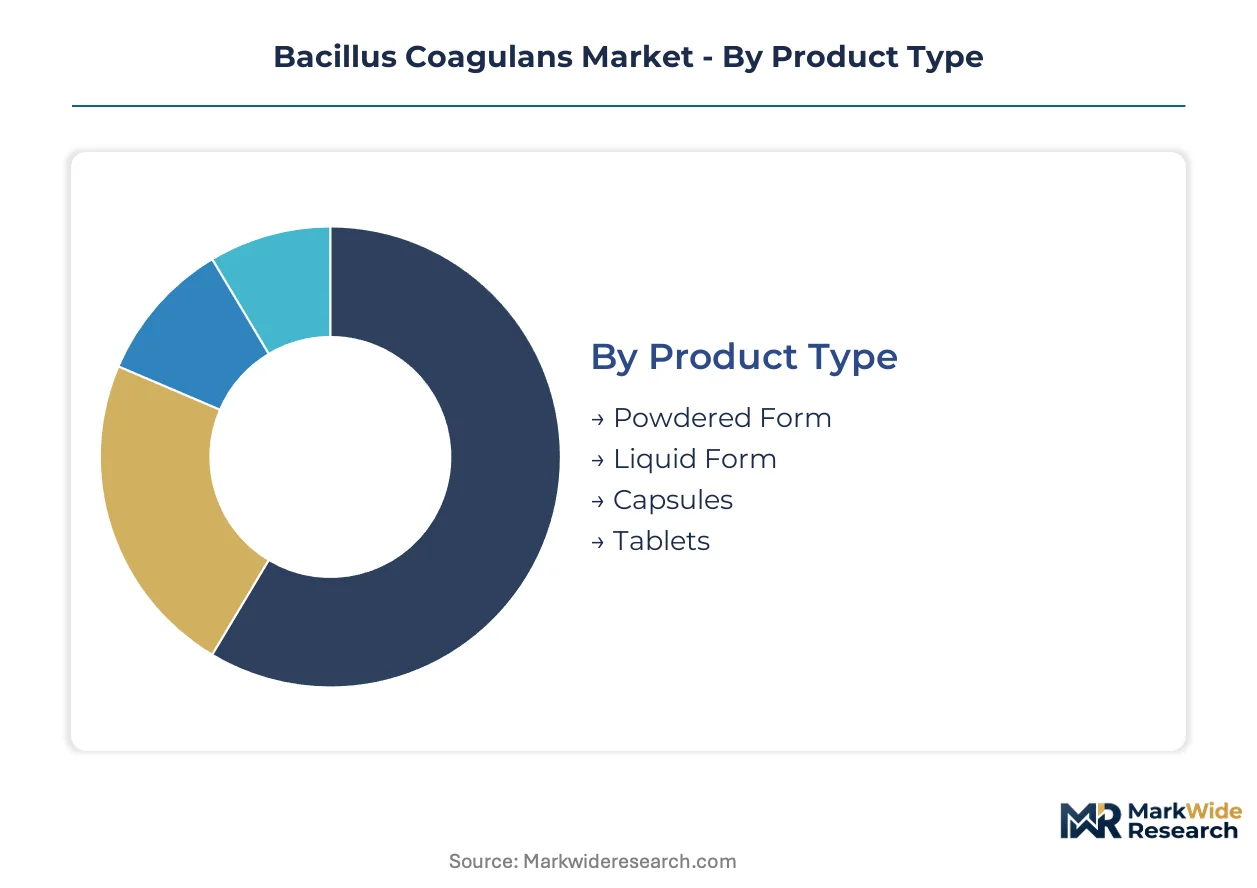
Bacillus coagulans suppliers configure production lines around physical form factors and stability requirements. Segmentation choices determine cold-chain economics, shelf-life claims, and regulatory pathway complexity.
Product Type:
Customization intensity varies from bulk powder commoditization to precision-dosed pharmaceutical formats requiring dedicated encapsulation suites.
- Powdered Form:Spray-dried spore concentrates blend into bakery, beverage, and supplement matrices without refrigeration. Functional food manufacturers in the United States specify heat-stable powders for ambient distribution networks.
- Capsules:Hard-shell gelatin and vegetable capsules deliver measured CFU counts for pharmaceutical channels. Clean-label positioning drives demand for delayed-release polymer coatings that protect spores through gastric transit.
- Liquid Form:Aqueous suspensions serve beverage fortification where dry blending is impractical. Short shelf life limits adoption to refrigerated supply chains.
- Tablets:Compressed powder formats target mass-market supplement shelves with cost-optimized unit economics. Compression heat requires strain selection for spore survivability.
Most installed capacity flows through Powdered Form. Expansion is steepest in Capsules.
Application:
Margin structures diverge sharply between commodity feed additives and premium human health positioning.
- Functional Foods:Probiotic embedding into everyday consumption occasions—plant-based yogurts, fortified juices, snack bars—commands formulation partnerships. Dairy alternative brands leverage Bacillus coagulans to match conventional probiotic claims without cold-chain dependency.
- Dietary Supplements:Direct-to-consumer pricing power sustains the deepest margin pools. E-commerce penetration exceeding 35 percent in United States and United Kingdom wellness categories fragments bulk procurement patterns.
- Probiotics:Standalone therapeutic positioning requires strain-specific clinical dossiers. EFSA novel food assessments and FDA GRAS notifications govern market access timelines.
- Animal Feed:Poultry and swine operations embed spore probiotics for feed conversion efficiency. Price sensitivity limits strain selection to high-yield fermentation outputs.
Volume concentrates in Dietary Supplements. Value capture is climbing fastest in Functional Foods.
End User:
Regulatory sophistication separates pharmaceutical-grade compliance from food-grade flexibility.
- Food & Beverages:Clean-label dairy alternatives and fortified beverages drive formulation partnerships. Brands embed probiotics into ambient-distribution products using heat-stable spore technology.
- Pharmaceutical:Rx and OTC probiotic drugs require CDSCO, FDA, or EMA drug master file submissions. Strain characterization costs burden small suppliers with six-figure compliance investments.
- Healthcare:Clinical nutrition and hospital formulary positioning demands batch-level certificate-of-analysis transparency. Procurement concentrates through group purchasing organizations.
- Animal Nutrition:Premium pet food manufacturers in Germany and Japan embed spore probiotics for digestive health positioning. Regulatory oversight is lighter than human applications.
Production volume skews toward Food & Beverages. Regulatory investment intensity peaks in Pharmaceutical.
Distribution Channel:
Channel selection determines margin retention versus reach trade-offs.
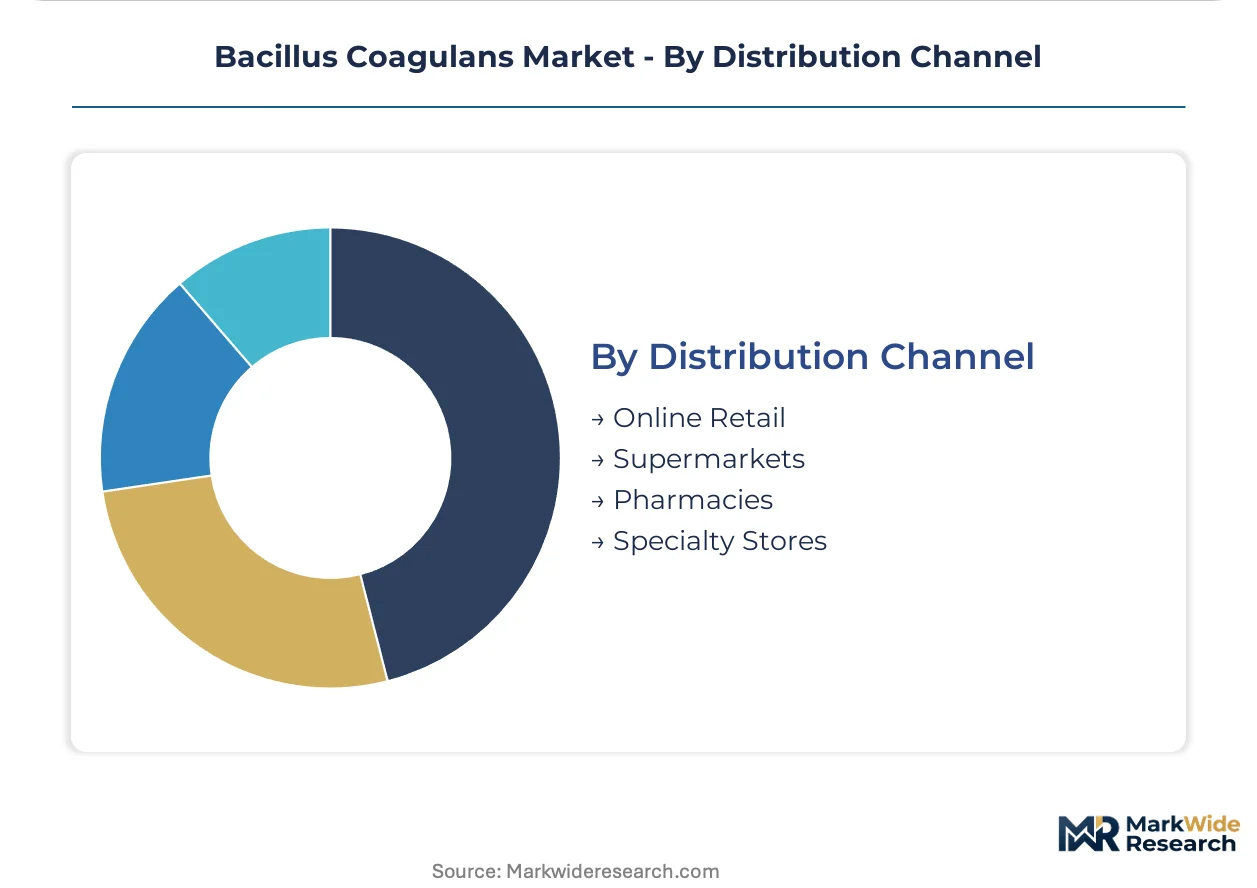
- Online Retail:Digital B2B marketplaces with certificate-of-analysis transparency enable smaller supplement brands to bypass traditional distributors. Flexible packaging formats and unbundled minimum order quantities concentrate in United States and United Kingdom markets.
- Pharmacies:Brick-and-mortar drugstore chains demand established brand recognition and pharmacist education support. Cold-chain products retain placement advantages here.
- Supermarkets:Mass-market functional food placement requires slotting fees and promotional spend. Ambient-stable Bacillus coagulans formats reduce retail handling complexity.
- Specialty Stores:Health food and natural product retailers prioritize non-GMO and organic certifications. Premium pricing tolerates smaller production runs.
Revenue share is consolidating in Online Retail. Physical channel expansion is most aggressive in Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States functional food brands embed Bacillus coagulans into ambient-distribution products, while Indian suppliers leverage fermentation capacity incentives to capture export contract manufacturing. Regulatory divergence between FDA GRAS pathways and EFSA novel food assessments shapes where new strains achieve commercial traction first.
United States
Clean-label dairy alternatives and fortified beverages drive formulation partnerships between probiotic suppliers and plant-based brands. FDA GRAS notifications streamline strain-specific safety determinations, compressing time-to-market for functional food launches. Chicago and Minneapolis host concentrated R&D facilities where beverage manufacturers test heat-stable spore integration.
Germany
Premium pet food manufacturers embed spore probiotics for digestive health positioning in dog and cat nutrition segments. EFSA novel food assessments require whole-genome sequencing and clinical dossiers that burden small suppliers with compliance investments. Bavaria anchors production clusters where mid-scale ingredient suppliers deploy single-use bioreactors.
India
Domestic fermentation capacity expands under Production Linked Incentive program incentives targeting export market supply. FSSAI and CDSCO jointly regulate probiotic health claims and pharmaceutical-grade formulations, creating dual compliance pathways. Hyderabad and Bangalore concentrate contract manufacturing facilities serving North American and European brand customers.
Japan
Protein powder brands combine Bacillus coagulans with whey isolates for sports nutrition applications claiming reduced bloating. METI oversees functional food labeling standards that distinguish characterized probiotic strains from generic identities. Tokyo and Osaka host formulation laboratories where beverage manufacturers validate spore viability through 24-month shelf life protocols.
Netherlands
Dairy alternative manufacturers absorb extended assessment timelines into product development roadmaps, prioritizing characterized strains with existing dossiers. EFSA guidance on qualified presumption of safety tightens antibiotic resistance gene screening requirements. Wageningen anchors bioprocess engineering clusters where continuous fermentation technology automates seed train operations.
Bacillus Coagulans Market Vendor Landscape
Top-tier vendors anchor integrated probiotic solutions, while mid-scale specialists compete on strain characterization speed and flexible minimum order quantities. The vendor base stratifies across fermentation capacity owners, formulation technology licensors, and regional distribution intermediaries. Three archetypes dominate: spore technology originators with patent estates, contract manufacturers with single-use bioreactor infrastructure, and ingredient platforms with direct-to-consumer channel reach. Competitive moves concentrate on backward integration into captive fermentation capacity and geographic expansion through distributor partnerships.
Among fermentation-origin specialists, Sanzyme Biologics and Syngen Biotech represent the Indian manufacturing base archetype, supplying heat-stable strains for beverage applications. Kerry Group occupies a position exemplifying the European integrated solutions tier, anchoring demand through functional food brand relationships. Sabinsa Corporation sits within the extraction-technology specialist category, differentiating via patented processes that enhance spore viability in finished products.
| Leading Market Players |
|---|
| Sanzyme Biologics |
| UAS Laboratories |
| Kerry Group |
| Syngen Biotech |
| WECARE-PROBIOTICS |
| Sabinsa Corporation |
| Unique Biotech Limited |
| Nebraska Cultures |
| Mitsubishi Chemical Foods Corporation |
| Others |
Supply Flow & Price Mechanics
Fermentation engineering talent pools in Hyderabad and Bangalore compress production cost differentials between Indian contract manufacturers and Western integrated suppliers, widening pricing-tier spreads for pharmaceutical-grade versus food-grade Bacillus coagulans strains.
Pricing Analysis
Capacity additions in India are reshaping price floors for heat-stable spore concentrates as domestic suppliers leverage PLI scheme incentives to undercut European fermentation economics. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels stratifies the market, with FDA drug master file submissions and EFSA novel food dossiers commanding premiums over generic strain offerings. Cost compression in commodity feed-grade powders is intensifying because glucose and soy peptone input volatility squeezes contract manufacturing margins. Animal nutrition buyers exhibit the highest price sensitivity, while pharmaceutical channel procurement tolerates premium positioning for characterized strains with clinical documentation.
Supply Chain Analysis
India's Production Linked Incentive scheme for active pharmaceutical ingredients is reshaping sourcing patterns by mandating domestic fermentation capacity expansion for export eligibility. Bacillus coagulans supply concentrates in India, the United States, and Germany, with Hyderabad and Chicago anchoring contract manufacturing clusters. Fermentation substrate supply draws from agricultural commodity markets in Brazil and the United States, while specialized spore-drying equipment sources from German and Dutch engineering firms. Single-source vulnerability concentrates in GBI-30 and MTCC 5856 strain lineages, where genetic uniformity creates contamination cascade risk. Distribution runs through direct-to-consumer digital marketplaces for supplement brands and formulation partnerships for functional food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bacillus coagulans market functions as a geographic-arbitrage play where Indian fermentation capacity incentives undercut European cost structures by 30-40 percent for equivalent spore viability specifications.
For Market Incumbents: Deploy backward integration into captive glucose and soy peptone supply to insulate margins from agricultural commodity volatility. Anchor formulation partnerships with plant-based dairy alternative brands in the United States to defend against emerging Indian exporters capturing North American beverage contracts. CDSCO pharmaceutical-grade certification investments differentiate incumbent positioning from food-grade commoditization pressures. For New Entrants and Emerging Players: Capture premium pet nutrition positioning in Germany and Japan where regulatory oversight remains lighter than human applications and formulation partnerships command margin premiums. Target sports nutrition convergence opportunities where protein powder brands seek reduced-bloating claims through spore probiotic co-formulation. Direct-to-consumer subscription models enable bypass of established distributor minimum order quantity thresholds. For Investors and Strategic Acquirers: Functional food ingredient platforms are the most active acquirer in this space, consolidating fermentation-origin specialists to secure characterized strain dossiers and beverage formulation capabilities. Five-to-ten year viability hinges on clinical evidence accumulation for strain-specific health claims beyond generic probiotic positioning. The signal to watch is EFSA qualified presumption of safety guidance tightening, which will accelerate consolidation around suppliers with existing whole-genome sequencing documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Captive glucose and soy peptone supply insulates margins from Brazilian and US agricultural commodity cycles. |
| EFSA Novel Food Dossier Accumulation | Pre-qualified strain libraries compress European brand customer time-to-market by 12-18 months. |
| Continuous Fermentation Technology Deployment | Single-use bioreactor automation in Danish and Dutch facilities cuts production cycles from 72 to 48 hours. |
| Direct-to-Consumer Channel Expansion | Digital B2B marketplaces with certificate-of-analysis transparency fragment legacy distributor concentration in US and UK wellness categories. |
| Pet Nutrition Formulation Partnerships | Premium dog and cat food manufacturers in Germany embed spore probiotics for digestive health positioning. |
Methodological Framework
Multiple input streams — primary interviews with fermentation engineering directors, regulatory affairs leads at probiotic suppliers, functional food brand formulation managers, and contract manufacturing procurement officers; secondary validation through FDA GRAS notification databases, EFSA novel food assessment registers, FSSAI approval filings, and Indian PLI scheme beneficiary disclosures; plus customs trade data for spore concentrate imports — were reconciled through bottom-up production capacity modeling and top-down demand segmentation triangulation.
Historical volume trajectories were cross-referenced against expert panel input across product type, application, end user, and distribution channel segmentation dimensions to derive expansion rates over the projection horizon. Fermentation yield improvements, strain characterization cost curves, and ambient-distribution adoption patterns in plant-based dairy alternatives served as industry-specific forecast inputs.
Regulatory timeline delays, strain contamination events, and agricultural commodity price spikes are the dominant revision risks that could compress or extend the analytical envelope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Lactic Acid Bacteria Market