
 Mycelium Market | 2026-2036
Mycelium Market Size, Share, and Industry Trends Forecast 2026-2036
Mycelium Market Outlook
ASTM D6400 compostability certification is collapsing the supplier base for mycelium-based packaging entrants, raising barriers for unqualified producers. Ecovative LLC leverages its early patent position in mycelium composite cultivation to dominate North American supply contracts for protective packaging. MycoWorks sustains premium positioning through controlled fungal biology processes that yield leather-grade material consistency. Meati Inc. anchors the food production segment with fermentation-scale mycoprotein manufacturing.
Mycelium comprises the vegetative root structure of filamentous fungi, typically cultivated on lignocellulosic substrates under controlled humidity and temperature parameters to produce dense, chitinous matrices with tensile properties rivaling petroleum-derived foams. Its primary commercial purpose centers on displacing synthetic polymers in protective packaging, construction insulation, and animal-hide substitutes across fashion and automotive interiors. Packaging Solutions commands the largest current revenue pool given immediate brand substitution demand from e-commerce fulfillment networks, while Textiles generates the highest margin concentration as luxury goods houses contract for mycelium leather at premium price points. Fermentation technology leads capital deployment as venture funding flows toward mycoprotein scale-up, though Mycoremediation remains nascent with concentrated pilot activity in post-industrial soil treatment.
The EPA regulates mycelium agricultural substrates under the Federal Insecticide, Fungicide, and Rodenticide Act, creating compliance costs that favor established cultivators over garage-scale entrants. REACH compliance in Europe restricts chemical inputs in mycelium dyeing and finishing processes, directly shaping product development roadmaps for textile-oriented suppliers. Stakeholders must monitor evolving FDA guidance on novel mycoprotein ingredients, as clearance timelines will determine which fermentation players achieve restaurant and retail shelf placement ahead of competitors.
Market Dynamics
ASTM D6400 compostability certification is collapsing the supplier base for mycelium-based packaging entrants, raising barriers for unqualified producers and concentrating contract awards among early patent holders with validated cultivation protocols.
Growth Catalysts
- EU F-Gas Regulation:Mandates substitution away from synthetic foams in protective packaging, creating immediate pull-through for mycelium composites in e-commerce fulfillment networks.
- Fermentation-scale mycoprotein:Food production applications are gaining traction among major consumer brands seeking alternative protein supply chain diversification.
- New York and California innovation clusters:Concentrated venture funding and pilot manufacturing infrastructure are accelerating commercial scale-up timelines for domestic suppliers.
Market Restraints
- Lignocellulosic substrate cost volatility:Agricultural waste feedstock pricing fluctuates with seasonal crop yields and competing biofuel demand, compressing margin predictability for cultivators.
- Patent concentration risk:Early intellectual property holders control core composite cultivation methods, limiting freedom to operate for second-wave entrants in North America.
- Chitinous matrix consistency:Batch-to-batch tensile property variation in uncontrolled fungal biology processes constrains textile-grade material qualification rates.
Strategic Opportunities
- Post-industrial soil remediation:Mycoremediation pilot activity in contaminated land treatment represents nascent white space with concentrated regulatory tailwinds from EPA brownfield programs.
- Automotive interior contracts:Premium vehicle manufacturers are sourcing mycelium leather for seat and panel applications, opening volume channels beyond fashion houses.
- Construction insulation standards:Evolving fire-resistance ratings for bio-based thermal barriers are creating certification pathways previously blocked by petroleum-foam incumbent lobbying.
Industry Challenges
- Fermentation bioprocess engineering talent:Scarcity of specialists capable of scaling submerged mycelium cultivation from pilot to commercial bioreactor operations is constraining food-segment expansion.
- FDA novel ingredient clearance timelines:Regulatory uncertainty around mycoprotein GRAS determinations is delaying restaurant and retail shelf placement commitments from national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycelium Market |
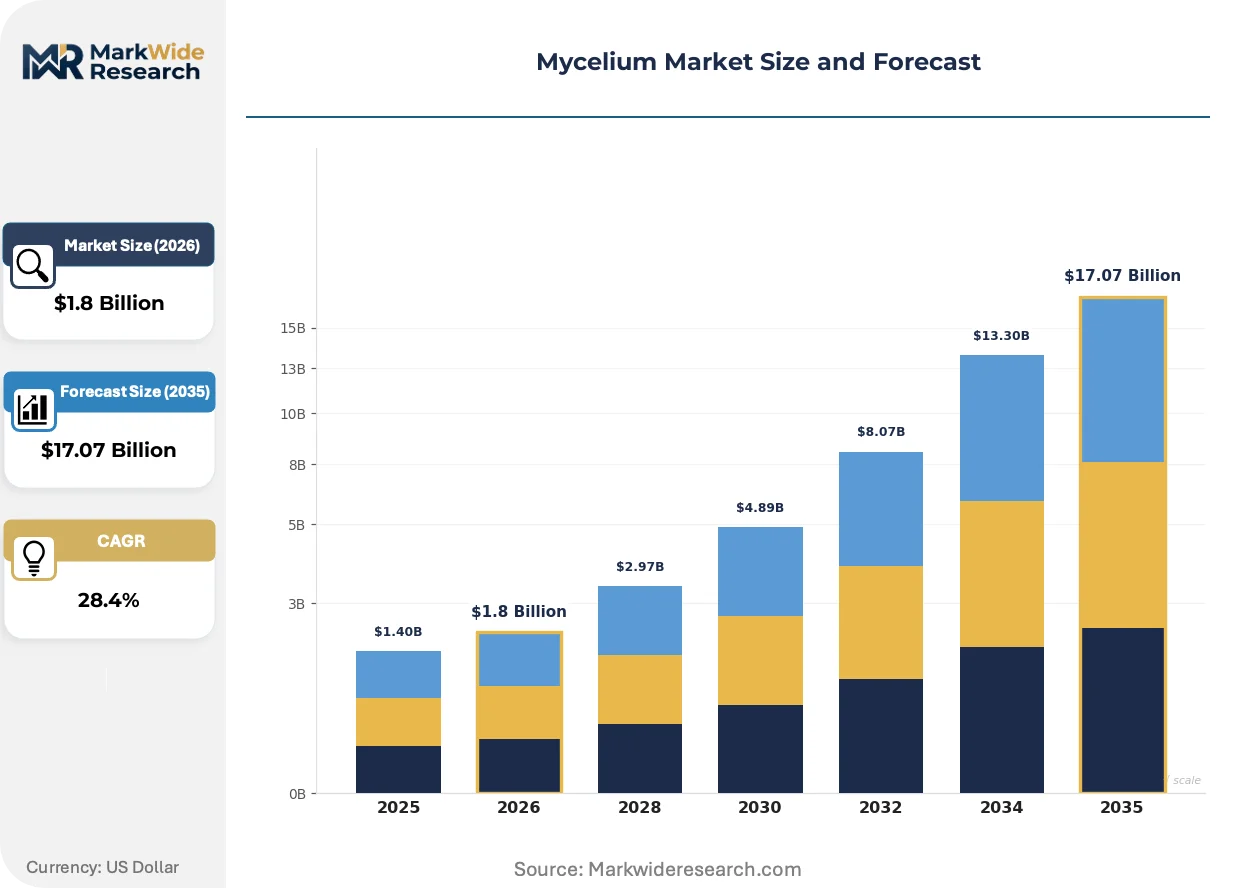
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Materials, Packaging Solutions, Textiles, Nutritional Supplements Application: Biodegradable Packaging, Agricultural Substrates, Fashion, Food Production End User: Agriculture, Construction, Food Industry, Retail Technology: Fermentation, Cultivation, Fungal Biology, Mycoremediation |
| Companies Covered | Magical Mushroom Company, Meati Inc., Ecovative LLC, Mycotech Lab, Mycelia NV, MycoWorks, MycoTechnology, Inc., MyForest Foods, Bolt Threads Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycelium Market Strategic Shifts
Fermentation technology leads capital deployment as venture funding flows toward mycoprotein scale-up, though controlled-environment agriculture patents and bioprocess automation are simultaneously reshaping competitive positioning across material categories.
Continuous-flow bioreactor systems for submerged mycelium cultivation are supplanting batch fermentation methods in food-grade mycoprotein manufacturing. Alternative protein processors are adopting these systems to achieve the cell densities required for cost parity with commodity meat inputs. The shift is compressing unit economics and enabling contract manufacturing arrangements that bypass captive facility investments.
REACH compliance in Europe restricts chemical inputs in mycelium dyeing and finishing processes, directly shaping product development roadmaps for textile-oriented suppliers. ECHA substance restrictions on conventional tanning agents are forcing leather-grade material producers to validate bio-based color fixation methods. German and Italian finishing houses are responding by integrating enzymatic treatment protocols that eliminate synthetic auxiliaries.
Brand-led sustainable packaging mandates are compressing supplier qualification cycles for protective foam substitutes. E-commerce fulfillment networks are consolidating vendor panels around ASTM D6400-certified producers, displacing uncertified regional cultivators. This concentration is most visible in United States coastal logistics corridors where retailer sustainability scorecards govern procurement decisions.
Mycelium Market Segmentation
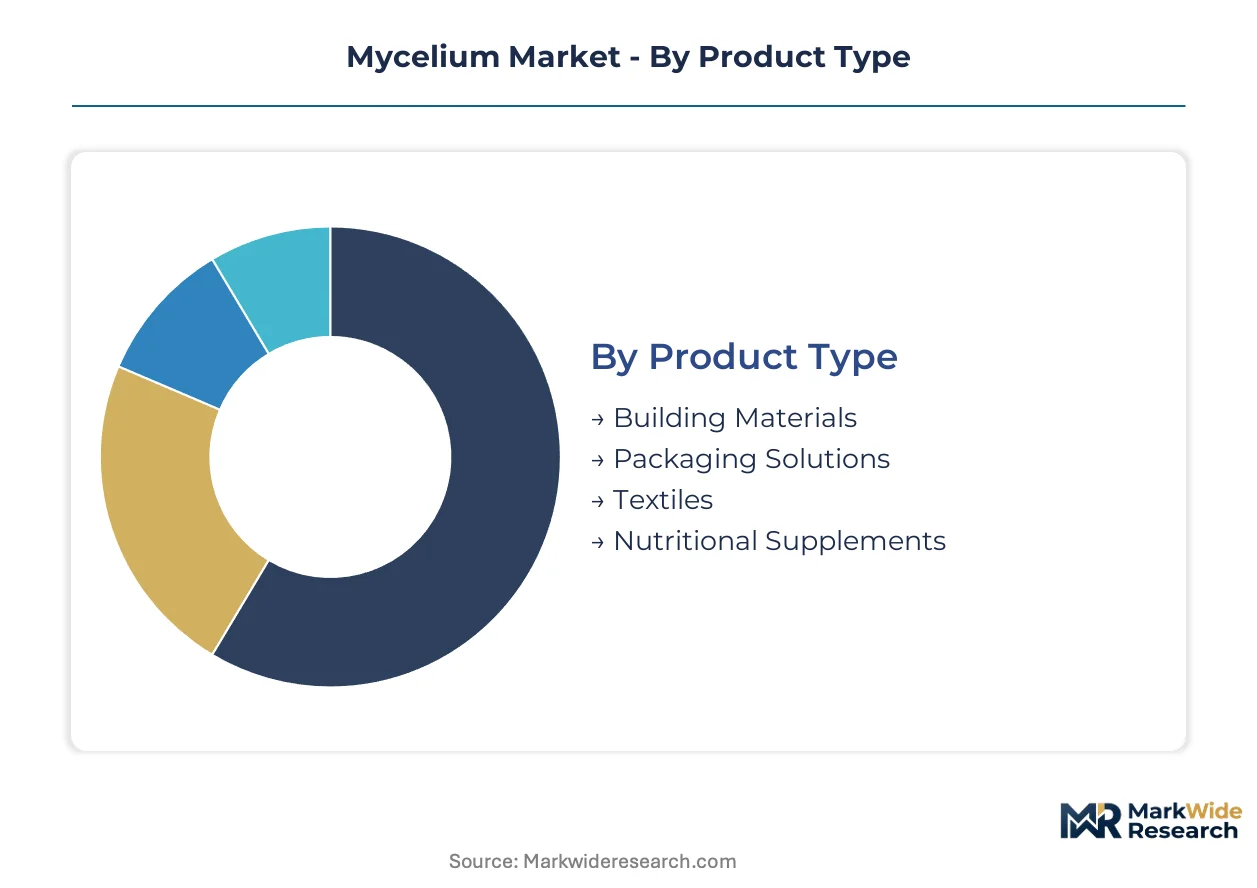
Mycelium applications diverge sharply by supply chain maturity and geographic concentration. Some segments serve export-heavy luxury goods networks, while others anchor domestic agricultural and construction markets with localized substrate sourcing.
Product Type:
Domestic production dominates Building Materials and Packaging Solutions, whereas Textiles and select Nutritional Supplements flow through international luxury and wellness distribution channels.
- Building Materials:Dense chitinous matrices replace petroleum-derived insulation boards and acoustic panels. Construction contractors in Germany and the United States specify these for LEED certification credits, though fire-resistance rating gaps limit high-rise adoption.
- Packaging Solutions:Protective foam substitutes cultivated on agricultural waste streams. E-commerce fulfillment networks in California and New York mandate ASTM D6400 compostability, collapsing supplier qualification to early patent holders with validated protocols.
- Textiles:Leather-grade material for fashion and automotive interiors. Italian and French luxury houses contract at premium price points, with German finishing houses integrating enzymatic dyeing to meet REACH compliance.
- Nutritional Supplements:Mycelium-derived beta-glucan extracts and powders. Wellness brands in Japan and South Korea drive formulation demand, with domestic cultivation in North America serving functional food integration.
Packaging Solutions holds the largest share; momentum sits with Textiles as automotive interior contracts expand beyond fashion applications.
Application:
Cost tiers separate high-volume commodity substitutes from premium positioning in lifestyle and nutrition categories.
- Biodegradable Packaging:Protective foam replacements for electronics and consumer goods fulfillment. Retailer sustainability scorecards in United States coastal corridors govern procurement consolidation around certified producers.
- Agricultural Substrates:Soil amendment and hydroponic growth media. Greenhouse operators in the Netherlands and Spain integrate mycelium-based substrates for controlled-environment vegetable production, with substrate cost volatility tracking seasonal crop yields.
- Fashion:Apparel and accessories utilizing leather-grade mycelium. Brand-led sustainable material mandates compress supplier qualification cycles, with Italian tanneries validating bio-based color fixation methods under ECHA restrictions.
- Food Production:Mycoprotein ingredients for alternative protein formulations. FDA novel ingredient clearance timelines determine which fermentation players achieve national restaurant and retail shelf placement ahead of competitors.
Biodegradable Packaging commands volume leadership; Food Production climbs fastest as venture capital flows toward fermentation scale-up.
End User:
Customer procurement sophistication varies from commodity spot purchasing in Agriculture to long-term contracting with sustainability audits in Retail.
- Agriculture:Substrate buyers and soil amendment users. Seasonal demand patterns align with planting cycles, with pricing fluctuating against competing biofuel feedstock offtake.
- Construction:Insulation and panel specification by general contractors and developers. Building code adoption for bio-based thermal barriers varies by municipality, creating fragmented qualification requirements.
- Food Industry:Alternative protein processors and ingredient suppliers. Continuous-flow bioreactor adoption compresses unit economics, enabling contract manufacturing that bypasses captive facility investment.
- Retail:E-commerce and brick-and-mortar networks with published sustainability targets. Vendor panel consolidation around certified producers displaces uncertified regional cultivators in procurement decisions.
Retail holds the largest share; momentum concentrates in Food Industry as mycoprotein manufacturing achieves cost parity milestones.
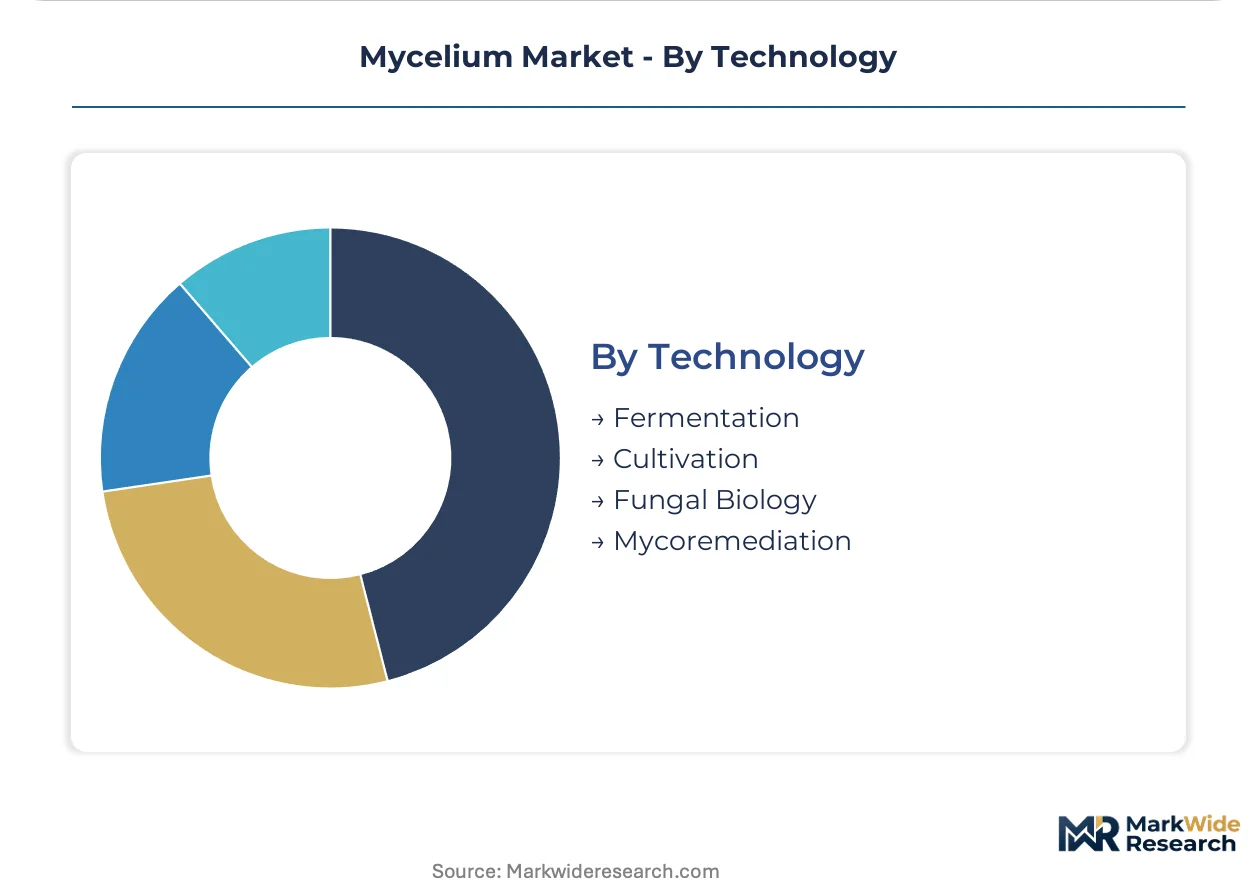
Technology:
Patent concentration and capital intensity separate mature cultivation methods from emerging bioprocess platforms.
- Fermentation:Submerged mycelium cultivation in controlled bioreactor environments. Food-grade mycoprotein manufacturing demands scarce bioprocess engineering talent capable of scaling from pilot to commercial operations.
- Cultivation:Solid-state growth on lignocellulosic substrates for composite materials. Early intellectual property holders in North America control core methods, limiting freedom to operate for second-wave entrants.
- Fungal Biology:Strain selection and genetic optimization for material consistency. Batch-to-batch tensile property variation constrains textile-grade qualification rates without controlled-environment protocols.
- Mycoremediation:Contaminant sequestration in post-industrial soil treatment. EPA brownfield program tailwinds support pilot activity, though commercial scale remains nascent against remediation contracting incumbents.
Cultivation holds the largest share; Fermentation gains share fastest as continuous-flow systems supplant batch methods in protein manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation and EPA brownfield incentives are redirecting capital toward mycelium substitution markets across major economies. National procurement standards and building code adoptions vary sharply, fragmenting qualification requirements for cross-border suppliers.
United States
ASTM D6400 compostability mandates from major retailers are collapsing supplier panels around certified producers. EPA brownfield program funding accelerates mycoremediation pilot activity in post-industrial zones. New York and California innovation clusters concentrate venture deployment toward fermentation-scale mycoprotein manufacturing.
Germany
Construction contractors specify mycelium insulation for LEED certification credits in commercial developments. REACH compliance restricts chemical inputs in dyeing processes, forcing enzymatic treatment adoption. Bavaria and North Rhine-Westphalia host finishing houses validating bio-based color fixation methods for textile-grade materials.
Netherlands
Greenhouse operators integrate mycelium-based substrates for controlled-environment vegetable production. The country's national agricultural regulator monitors substrate safety under EU organic certification frameworks. Randstad logistics corridors consolidate procurement decisions around retailer sustainability scorecards.
Italy
Fashion houses contract for leather-grade mycelium at premium price points for luxury goods. ECHA substance restrictions on conventional tanning agents accelerate bio-based finishing validation. Lombardy and Tuscany tanneries pioneer enzymatic protocols eliminating synthetic auxiliaries.
China
Dual carbon goals pressure packaging manufacturers toward bio-based foam substitutes. The Ministry of Ecology and Environment monitors agricultural substrate sourcing for compliance with national sustainability standards. Yangtze River Delta manufacturing hubs pilot mycelium composite cultivation for e-commerce fulfillment networks.
Mycelium Market Competitive Environment
Listed leaders compete with private specialists across patent concentration and cultivation scale dimensions. Early intellectual property holders control core composite methods, limiting freedom to operate for second-wave entrants. Three archetypes dominate: fermentation-scale protein manufacturers, solid-state cultivation specialists, and luxury textile finishers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure substrate supply contracts and brand offtake agreements.
Within the cultivation specialist tier, Ecovative LLC and MycoWorks occupy positions reflecting divergent strategic emphases. Meati Inc. anchors the fermentation-driven protein segment with bioreactor-scale manufacturing capabilities. MycoTechnology, Inc. exemplifies the ingredient-platform archetype serving downstream food processors.
| Leading Market Players |
|---|
| Magical Mushroom Company |
| Meati Inc. |
| Ecovative LLC |
| Mycotech Lab |
| Mycelia NV |
| MycoWorks |
| MycoTechnology, Inc. |
| MyForest Foods |
| Bolt Threads Inc. |
| Others |
Value Chain & Pricing Dynamics
ASTM D6400 compostability certification gates both supplier qualification and price differentiation in mycelium-based packaging, concentrating contract awards among early patent holders while relegating uncertified cultivators to commodity spot markets with compressed margins.
Pricing Analysis
Certification level creates the primary spread between premium ASTM D6400-validated supply and uncertified regional production. Three-tier pricing structure separates validated composite cultivators from provisional qualifiers from uncertified spot suppliers, with textile-grade material consistency commanding additional premiums. Pricing pressure stems from lignocellulosic substrate cost volatility tracking seasonal crop yields and competing biofuel demand. Retail procurement panels exhibit lowest price sensitivity given sustainability scorecard mandates, while agricultural substrate buyers face highest sensitivity due to commodity feedstock alternatives.
Supply Chain Analysis
Strategic stockpiling of agricultural waste feedstock dominates over just-in-time approaches due to seasonal harvest timing and competing biofuel offtake. Supply concentrates in the United States, Germany, and China, with New York and California innovation clusters anchoring North American cultivation capacity. Raw material dependencies center on lignocellulosic substrates, fungal strain banks, and enzymatic finishing agents. Single-source vulnerability runs through early patent holders controlling core composite cultivation methods. Distribution runs through e-commerce fulfillment networks, luxury goods houses, and fermentation-scale contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against petroleum-derived foams and animal hides, with incumbents navigating displacement pressure from synthetic polymer incumbents lobbying against bio-based thermal barrier certification.
For Market Incumbents: Fortify patent positions in solid-state cultivation methods through defensive filing around process variations, while securing long-term lignocellulosic substrate contracts to buffer against agricultural commodity volatility. Capacity addition in Germany and Italy captures REACH-compliant textile finishing demand. Certification investment in ASTM D6400 validation protocols raises barriers against second-wave entrants.
For New Entrants and Emerging Players: Post-industrial soil remediation service gaps offer white-space entry where EPA brownfield program tailwinds reduce customer acquisition friction. Mycoremediation pilot contracting represents the most penetrable segment given nascent incumbent presence. Automotive interior applications beyond fashion houses provide a specific go-to-market angle through tiered supplier qualification programs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-scale mycoprotein manufacturing as continuous-flow bioreactor systems supplant batch methods. Long-term viability frames around 5-10 year protein substitution trajectories in food service and retail channels. Acquisition target archetype centers on fermentation specialists with validated GRAS determination pathways. The signal to watch is FDA novel ingredient clearance timelines as inflection indicator for restaurant and retail shelf placement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Patent Portfolio Expansion | Defensive filing around solid-state cultivation methods limits freedom to operate for second-wave entrants in North America. |
| Substrate Supply Contracting | Long-term agricultural waste offtake agreements buffer margin predictability against seasonal crop yield volatility. |
| ASTM D6400 Certification | Validated compostability protocols unlock e-commerce fulfillment network procurement panels governed by retailer sustainability scorecards. |
| Continuous-Flow Bioreactor Deployment | Submerged cultivation systems achieve cell densities required for mycoprotein cost parity with commodity meat inputs. |
| Enzymatic Finishing Integration | Bio-based color fixation methods satisfy ECHA substance restrictions on conventional tanning agents in European textile production. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and venture funding disclosures. Primary interviews engaged cultivation technology officers, fermentation bioprocess engineers, luxury goods procurement directors, and EPA brownfield program administrators. Secondary sources included FIFRA registration databases, ECHA substance restriction updates, FDA GRAS determination notices, and ASTM certification registries. Bottom-up triangulation across supplier capacity announcements and top-down validation against end-use demand aggregation ensured cross-verification.
Segmentation dimensions modeled span product type, application, end user, and technology across the projection horizon. Cultivation method maturity, certification status, and geographic regulatory cluster shaped analytical framework construction. CAGRs derived from capacity expansion announcements, substrate cost trajectories, and substitution elasticity assumptions in packaging and textile end uses. Fermentation scale-up timelines and FDA clearance velocity represented industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA FIFRA enforcement, REACH substance restrictions, and FDA novel ingredient pathways; material policy shifts would require re-modeling. Lignocellulosic feedstock cost spikes, patent litigation outcomes, or GRAS determination delays represent specific revision triggers. Revision becomes warranted when batch-to-batch tensile property variation in textile-grade materials crosses qualification rate thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market