
 Brazil Biocontrol Agents Market | 2026-2036
Brazil Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Biocontrol Agents Market Insights
RNA interference technology is reshaping how biocontrol formulations target pest species with species-specific precision, reducing off-target ecological damage. Koppert Biological Systems Inc. leverages its global germplasm library to sustain breeding programs for predatory mites tailored to Brazilian citrus and coffee systems. Promip Manejo Integrado de Pragas Ltda anchors its position through localized mass-rearing facilities that shorten delivery windows to Midwestern soybean belts. Syngenta Group competes by integrating microbial platforms into broader crop protection portfolios sold through its existing agrochemical retailer network.
Biocontrol agents comprise living organisms or naturally derived compounds that suppress pest populations through parasitism, predation, competition, or antibiotic effects, with formulations typically requiring colony-forming unit counts above 10^8 per milliliter to ensure field efficacy. Microbial agents dominate current revenue as Bacillus thuringiensis and Trichoderma products command premium pricing in high-value horticultural export chains. Biochemical agents represent the fastest-expanding category as pheromone-based mating disruption gains traction in integrated pest management protocols for fruit fly control. Plant extracts occupy a mature niche where margin pools remain thin due to inconsistent standardization of active metabolite concentrations.
ANVISA regulates product registration and toxicological assessment for biocontrol inputs entering Brazilian agriculture, while the Ministry of Agriculture enforces residue monitoring protocols that shape export eligibility for treated commodities. The EU Green Deal's Farm to Fork strategy indirectly pressures Brazilian growers to demonstrate biocontrol usage as proof of sustainable sourcing for European buyers. Stakeholders must monitor how rapidly evolving phytosanitary certificate requirements from importing nations redefine which biocontrol modalities qualify as compliant pest management.
Market Dynamics
ANVISA's tightening residue limits on synthetic pesticides are compressing demand timelines for biocontrol alternatives, forcing large-scale soybean operations in Mato Grosso to reconfigure pest management protocols mid-cycle. This regulatory pressure concentrates purchasing power among export-certified growers who can absorb validation costs.
Growth Catalysts
- EU Green Deal sourcing mandates:European buyers now require documented biocontrol usage for Brazilian soybean and coffee imports, creating compliance-driven procurement at origin.
- RNA interference formulation advances:Species-specific pest targeting reduces off-target damage and accelerates grower willingness to substitute synthetic chemistry.
- Cerrado commercial farm consolidation:Large-scale operators achieve economies of scale in microbial inoculant application that smaller holdings cannot replicate.
Market Restraints
- Colony-forming unit volatility:Microbial agent efficacy requires concentrations above 10^8 per milliliter, and temperature excursions during Brazilian transport degrade batch consistency.
- Mass-rearing facility concentration:Predatory mite and parasitoid production clusters in São Paulo state, creating single-point vulnerability for Midwestern soybean belt delivery.
- Synthetic pesticide price competition:Generic agrochemical alternatives retain cost advantage in non-export commodity channels, limiting biocontrol penetration in domestic-only production.
Strategic Opportunities
- Piauí and Maranhão expansion zones:Matopiba frontier states lack established synthetic pesticide infrastructure, enabling biocontrol-first market development without displacement costs.
- Pheromone mating disruption protocols:Fruit fly management in northeastern mango and grape export corridors represents underdeveloped biochemical agent deployment.
- ANVISA fast-track registration pathways:Expedited toxicological review for microbial agents with established safety profiles compresses time-to-market for novel formulations.
Industry Challenges
- Entomopathogenic nematode handling expertise:Specialized storage and application protocols require trained agronomists that rural extension services currently undersupply.
- Multi-modal IPM integration complexity:Synchronizing biological agent release schedules with chemical rotation windows demands precision timing that legacy farm management systems cannot execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Biocontrol Agents Market |
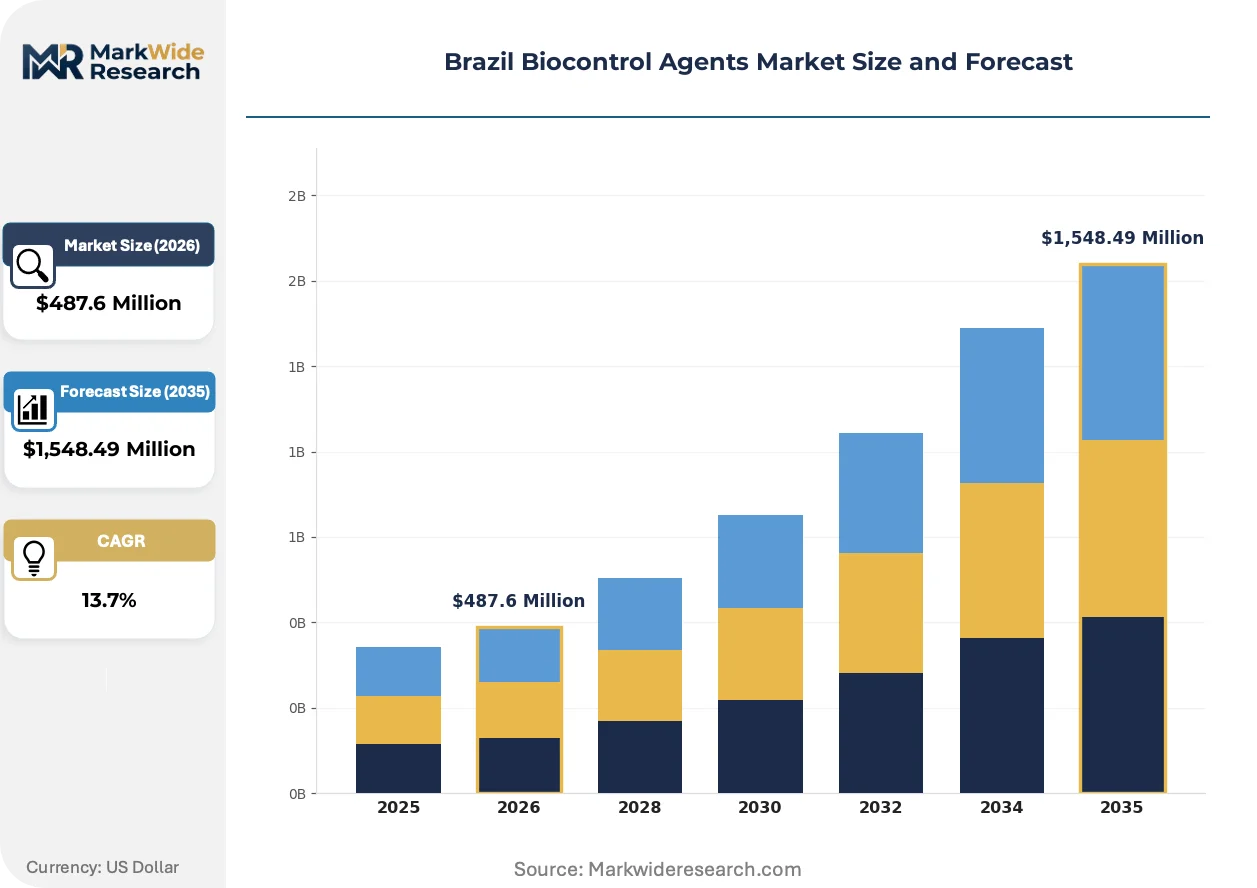
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,548.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Agents, Biochemical Agents, Insect Growth Regulators, Plant Extracts Application: Agricultural Crops, Horticultural Crops, Turf, Ornamental Plants Distribution Channel: Direct Sales, Distributors, Online Retail, Agrochemical Retailers End User: Farmers, Commercial Growers, Research Institutions, Agrochemical Companies |
| Companies Covered | Promip Manejo Integrado de Pragas Ltda, Koppert Biological Systems Inc., Agrivalle Brasil Industria e Comercio de Produtos Agricolas SA, Bio Controle - Metodos de Controle de Pragas Ltda, Vittia Group, Syngenta Group, Corteva Agriscience, FMC Corporation, Andermatt Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Biocontrol Agents Market Trends and Innovations
Digital infrastructure is penetrating Brazilian agriculture at uneven rates, with precision application technologies now separating export-certified operations from commodity producers. Three distinct vectors are compressing development cycles and reconfiguring competitive positioning.
Drone-mounted electrostatic sprayers are digitizing microbial inoculant distribution across Mato Grosso soybean plantations. Large-scale cooperatives in Sorriso and Lucas do Rio Verde deploy these systems for variable-rate Bacillus thuringiensis application. The technology is digitizing field-level data capture, enabling real-time colony viability monitoring that static ground rigs cannot match.
ANVISA's 2023 residue monitoring protocol expansion tightens enforcement scope for export-bound commodities. The regulation now mandates documented biocontrol usage in phytosanitary certificates for EU-bound shipments. Horticultural exporters in Minas Gerais and Espírito Santo are accelerating biochemical agent adoption to preempt certification delays.
Direct-to-farm distribution platforms are disintermediating traditional agrochemical retailer networks in Paraná's corn-soy rotation belts. Digital procurement aggregates demand from mid-scale operators previously excluded from volume pricing tiers. This channel shift concentrates most visibly in Cascavel and Toledo, where cooperative buying groups now source Trichoderma formulations through specialized biocontrol distributors rather than multi-brand ag retailers.
Brazil Biocontrol Agents Market Segmentation
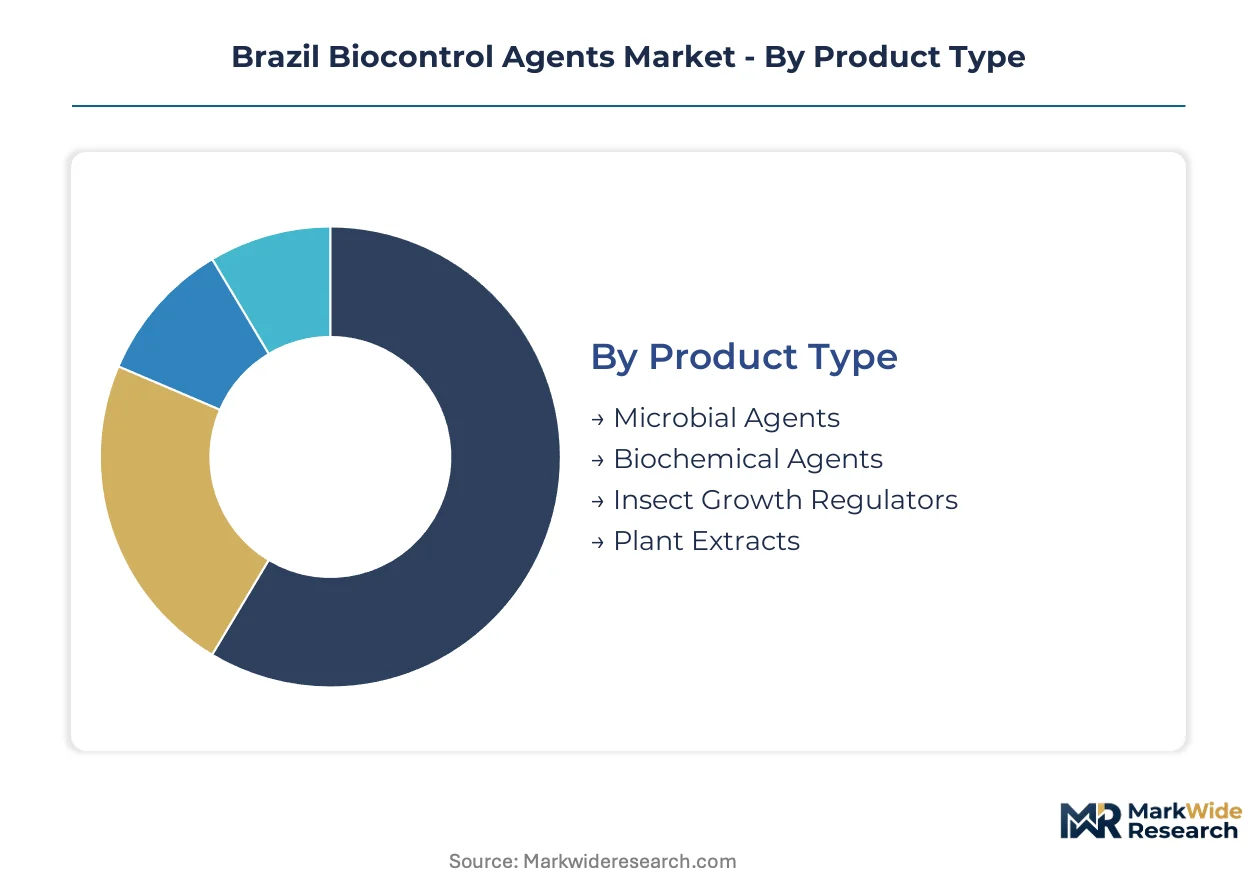
Biocontrol purchasing patterns in Brazil diverge sharply across crop value chains and buyer sophistication levels. Segmentation reveals where microbial premiumization succeeds against biochemical cost competition, and which distribution channels capture regulatory compliance premiums.
Product Type:
Formulation chemistry determines margin structure and application complexity across Brazilian agricultural systems.
- Microbial Agents:Live organism formulations require colony-forming unit concentrations above 10^8 per milliliter to maintain field efficacy. Demand concentrates in Mato Grosso soybean operations where export certification requirements favor documented biological inputs over synthetic residues.
- Biochemical Agents:Naturally derived compounds including pheromones and plant hormones enable precise pest targeting without live organism handling constraints. Northeastern mango and grape corridors are expanding mating disruption protocols for fruit fly management ahead of EU phytosanitary deadlines.
- Insect Growth Regulators:Synthetic hormone mimics disrupt insect molting processes with lower environmental persistence than conventional pesticides.
- Plant Extracts:Botanical preparations face standardization challenges that compress margins despite established grower familiarity.
The dominant share belongs to Microbial Agents, while Biochemical Agents are closing the gap fastest.
Application:
Crop value tiers separate price-sensitive commodity producers from compliance-driven export operations.
- Agricultural Crops:Soybean, corn, and cotton systems in the Cerrado dominate volume demand. Large-scale operators achieve economies of scale in microbial inoculant application that smaller holdings cannot replicate.
- Horticultural Crops:Coffee, citrus, and vegetable production commands premium pricing for specialized predatory mite and parasitoid formulations. Minas Gerais and Espírito Santo exporters accelerate adoption to meet ANVISA's expanded residue monitoring protocols.
- Turf:Golf course and sports field maintenance represents a niche with consistent but limited volume potential.
- Ornamental Plants:Floriculture operations in São Paulo state generate specialized demand for Trichoderma-based disease suppression.
Agricultural Crops absorb the majority of volume, though Horticultural Crops generate the steepest margin expansion.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements.
- Direct Sales:Large cooperatives in Sorriso and Lucas do Rio Verde procure microbial formulations directly from manufacturers, bypassing retail markups while securing technical support.
- Distributors:Specialized biocontrol distributors aggregate mid-scale demand in Paraná's corn-soy rotation belts, disintermediating traditional multi-brand ag retailers.
- Online Retail:Digital platforms penetrate unevenly, with precision application technologies separating export-certified operations from commodity producers.
- Agrochemical Retailers:Legacy networks retain synthetic pesticide dominance in domestic-only production channels where generic chemistry cost advantages persist.
Direct Sales commands the highest value per transaction, while Distributors are expanding coverage most aggressively.
End User:
Technical capability and compliance exposure shape procurement sophistication.
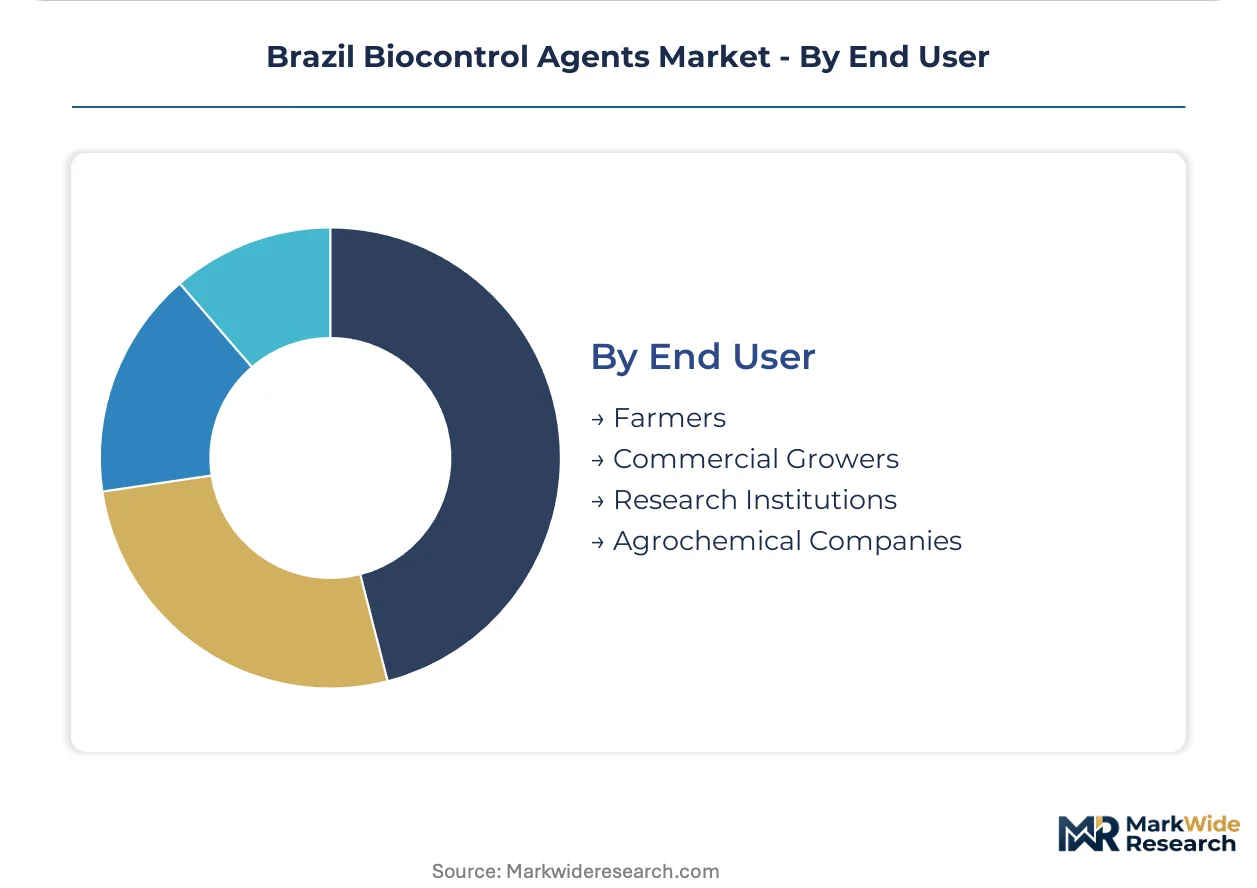
- Farmers:Small to mid-scale operators in Matopiba frontier states lack established synthetic pesticide infrastructure, enabling biocontrol-first market development without displacement costs.
- Commercial Growers:Export-certified operations in Mato Grosso and Paraná absorb validation costs for ANVISA-compliant pest management protocols. These buyers concentrate purchasing power and drive formulation innovation.
- Research Institutions:EMBRAPA and state agricultural universities anchor entomopathogenic nematode handling expertise that rural extension services currently undersupply.
- Agrochemical Companies:Integrated crop protection portfolios incorporate microbial platforms as residue limit pressures compress synthetic chemistry timelines.
Commercial Growers represent the core revenue base, while Farmers in frontier zones offer the steepest penetration trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-certified commercial growers in Mato Grosso and Paraná concentrate purchasing power for biocontrol agents, driving demand toward large-scale microbial inoculant procurement that smaller domestic-only operations cannot replicate. This buyer archetype distribution shapes regional market development across Brazil's agricultural frontier.
Mato Grosso
Soybean monocultures and corn-soy rotation systems generate concentrated demand for Bacillus thuringiensis and Trichoderma formulations. ANVISA's 2023 residue monitoring protocol expansion mandates documented biocontrol usage in phytosanitary certificates for EU-bound shipments. Large cooperatives in Sorriso and Lucas do Rio Verde deploy drone-mounted electrostatic sprayers for variable-rate microbial application.
Paraná
Corn-soy rotation belts and coffee production clusters create dual-demand channels for microbial and biochemical agents. Direct-to-farm distribution platforms disintermediate traditional agrochemical retailer networks in Cascavel and Toledo. Cooperative buying groups now source Trichoderma formulations through specialized biocontrol distributors rather than multi-brand ag retailers.
São Paulo
Predatory mite and parasitoid mass-rearing facilities cluster in this state, creating single-point vulnerability for Midwestern soybean belt delivery. Citrus and coffee systems drive specialized demand for Koppert Biological Systems' breeding programs. The state's floriculture operations generate niche demand for Trichoderma-based disease suppression in ornamental plant production.
Minas Gerais
Coffee exporters accelerate biochemical agent adoption to preempt ANVISA certification delays under expanded residue monitoring protocols. Fruit fly management in mango and grape export corridors represents underdeveloped pheromone mating disruption deployment. Horticultural operations face mounting EU Green Deal sourcing mandates requiring documented sustainable pest management.
Piauí and Maranhão
Matopiba frontier states lack established synthetic pesticide infrastructure, enabling biocontrol-first market development without displacement costs. Small to mid-scale operators in these expansion zones absorb lower validation costs for ANVISA-compliant protocols. The absence of legacy agrochemical distribution creates opening for microbial platform penetration ahead of conventional chemistry establishment.
Brazil Biocontrol Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Brazil's biocontrol market structure. Large agrochemical conglomerates leverage existing retailer networks to bundle microbial platforms with synthetic chemistry portfolios, while biological specialists build localized mass-rearing capacity and direct technical service relationships. Two strategic archetypes dominate: integrated crop protection vendors with multi-brand distribution reach, and focused biological agent developers with germplasm libraries and regional breeding programs. Competitive moves center on geographic expansion into Matopiba frontier states and technology licensing for RNA interference formulation development.
Among Brazil-based biological specialists, Promip Manejo Integrado de Pragas Ltda anchors the localized mass-rearing facility archetype with shortened delivery windows to Midwestern soybean belts. Netherlands-based Koppert Biological Systems Inc. exemplifies the global germplasm library model, sustaining breeding programs for region-specific predatory mites. Syngenta Group occupies a position within the integrated crop protection tier, competing through microbial platform integration into broader portfolios sold through established agrochemical retailer networks. These three represent distinct competitive positioning vectors without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Promip Manejo Integrado de Pragas Ltda |
| Koppert Biological Systems Inc. |
| Agrivalle Brasil Industria e Comercio de Produtos Agricolas SA |
| Bio Controle - Metodos de Controle de Pragas Ltda |
| Vittia Group |
| Syngenta Group |
| Corteva Agriscience |
| FMC Corporation |
| Andermatt Group AG |
| Others |
Pricing and Supply Chain Analysis
Predatory mite and parasitoid mass-rearing facility concentration in São Paulo state anchors margin capture for biological specialists, while synthetic pesticide generic competition compresses pricing power in domestic-only channels. Colony-forming unit volatility during Brazilian transport creates quality-tier differentiation that export-certified buyers absorb at premium levels.
Pricing Analysis
Cost-plus contracts with ANVISA registration fee indexation dominate procurement between large cooperatives and microbial formulation suppliers. Pricing stratifies across export-certified premium tiers, standard commercial grades, and economy domestic channels based on colony viability guarantees and phytosanitary documentation depth. Cost compression in the economy tier is intensifying because generic agrochemical alternatives retain field efficacy advantages for non-export commodity producers. Small to mid-scale operators in Matopiba frontier states exhibit highest price sensitivity, while Mato Grosso export-certified operations prioritize compliance documentation over unit cost minimization.
Supply Chain Analysis
Temperature excursion risks during Brazilian interstate transport dominate supply chain vulnerability for live organism formulations. Microbial agent production draws from São Paulo state facilities, Netherlands germplasm libraries, and domestic fermentation capacity for Bacillus thuringiensis concentrates. Single-source vulnerability clusters in São Paulo mass-rearing infrastructure create delivery window compression for Midwestern soybean belt procurement. Distribution runs through specialized biocontrol distributors disintermediating legacy agrochemical retailers in Paraná and direct manufacturer relationships with Mato Grosso cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized entomopathogenic nematode handling expertise scarcity constrains field-level deployment quality, creating differentiation opportunity for players who anchor technical service capacity in rural extension gaps. Mass-rearing facility concentration and RNA interference formulation development capability gaps define competitive positioning leverage points across the value chain.
For Market Incumbents: Entrench position through backward integration into São Paulo mass-rearing capacity to eliminate single-point delivery vulnerability for Midwestern soybean belt customers. Anchor technical service teams in Mato Grosso cooperative territories to preempt digital procurement platform disintermediation. Certification investment in ANVISA fast-track registration pathways defends margin position against emerging microbial platform competitors from integrated agrochemical conglomerates. For New Entrants and Emerging Players: Pursue white-space penetration in Piauí and Maranhão Matopiba frontier zones where synthetic pesticide infrastructure absence enables biocontrol-first market development without displacement costs. Target pheromone mating disruption deployment in Minas Gerais mango and grape export corridors ahead of EU phytosanitary deadline convergence. Digital direct-to-farm procurement platforms offer the most penetrable go-to-market angle for mid-scale operators previously excluded from volume pricing tiers. For Investors and Strategic Acquirers: Capital is best deployed toward biological specialists with captive germplasm libraries and localized mass-rearing infrastructure rather than distribution-dependent commodity microbial suppliers. Long-term viability across the analysis window favors players who control breeding program intellectual property and regional adaptation capability. The signal to watch is ANVISA registration velocity for RNA interference formulations as inflection indicator for technology platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mass-Rearing Facility Expansion | São Paulo capacity additions shorten delivery windows to Mato Grosso soybean cooperatives. |
| RNA Interference Licensing Agreement | Species-specific pest targeting technology accelerates substitution of synthetic chemistry portfolios. |
| ANVISA Fast-Track Registration Investment | Expedited toxicological review compresses time-to-market for novel microbial formulations. |
| Direct-to-Farm Digital Platform Launch | Disintermediation of agrochemical retailers captures mid-scale operator demand aggregation in Paraná. |
| Technical Service Network Buildout | Entomopathogenic nematode expertise deployment fills rural extension service undersupply gaps. |
Research Methodology
Initial hypotheses were tested against primary input from microbial formulation plant managers, ANVISA regulatory affairs specialists, Mato Grosso cooperative procurement directors, and Paraná distribution channel partners and refined through secondary validation. Trade flow data from Brazilian customs authorities, ANVISA registration databases, EMBRAPA technical bulletins, and SEC filings from listed agrochemical conglomerates anchored quantitative baselines. Bottom-up demand modeling from crop-specific application rates triangulated against top-down market size estimates from supply-side capacity assessments.
Demand-supply-balance dynamics across the projection horizon shaped analytical framework construction around product type, application crop value tier, distribution channel sophistication, and end-user technical capability segmentation dimensions. CAGRs emerged from growth driver elasticity modeling calibrated to regulatory timeline acceleration and export certification penetration curves. Colony-forming unit degradation rates during Brazilian transport and ANVISA residue monitoring protocol expansion timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Netherlands-based germplasm library operators or accelerated RNA interference platform development by integrated agrochemical conglomerates would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
German Biopesticides Market