
 India Agricultural Biologicals Market | 2026-2036
India Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Agricultural Biologicals Market Insights
The PLI scheme for agri-input manufacturing is shifting the cost-of-entry calculus toward domestic biological production capacity. UPL Limited leverages its pan-India distribution network to sustain market presence across multiple crop segments. Syngenta India Inc anchors its position through specialized biocontrol formulations tailored to tropical pest pressures. Coromandel International Ltd competes by extending its legacy fertilizer infrastructure into microbial product lines.
Agricultural biologicals comprise living organisms, derived metabolites, and natural substances formulated to enhance crop productivity, protect against pests and diseases, or improve soil fertility through mechanisms such as nitrogen fixation, phosphate solubilization, or induced systemic resistance. Biopesticides and biofertilizers occupy the dominant volume share, reflecting farmer familiarity and established application protocols, while biofungicides represent the fastest-expanding category as fungicide resistance intensifies in vegetable and fruit cultivation. Among applications, fruits and vegetables command premium positioning due to export-oriented quality requirements and shorter chemical residue windows, whereas cereals sustain foundational demand through government-backed food security programs and cooperative procurement structures.
BIS certification requirements and FSSAI residue standards shape product formulation standards and market access pathways for domestic manufacturers. The CEA mandates environmental compliance for production facilities, while state-level organic farming missions in Karnataka, Andhra Pradesh, and Gujarat create localized demand pull through subsidy-linked procurement. Stakeholders must monitor regulatory harmonization between central biostimulant guidelines and state-specific organic certification protocols to anticipate compliance cost trajectories and channel investment toward approved active ingredient categories.
Market Dynamics
The PLI scheme for agri-input manufacturing is redirecting capital toward domestic biological production capacity, compressing import dependence for microbial inoculants and biocontrol formulations while state-level organic farming missions accelerate localized demand formation.
Growth Catalysts
- Central subsidy architecture:The PLI scheme for agri-input manufacturing reduces capital cost barriers for domestic microbial fermentation facilities, drawing investment away from chemical formulation plants.
- Export residue compliance:FSSAI residue standards for fruits and vegetables are compelling horticulture clusters in Maharashtra and Gujarat to substitute chemical pesticides with biopesticide alternatives.
- State procurement mandates:Karnataka, Andhra Pradesh, and Gujarat organic farming missions are creating guaranteed offtake channels for biofertilizer cooperatives through subsidy-linked distribution networks.
Market Restraints
- Active ingredient import dependence:Domestic manufacturers rely on Chinese and European suppliers for concentrated microbial strains and fermentation media, exposing margins to currency volatility and shipping disruptions.
- BIS certification timelines:Bureau of Indian Standards testing protocols for novel biocontrol agents extend product launch cycles by 18-24 months versus chemical pesticide registrations.
- Farmer application knowledge gaps:Biological products require precise temperature, moisture, and timing protocols that diverge from established chemical spraying routines, slowing adoption in cereal-dependent northern states.
Strategic Opportunities
- Telangana and Andhra Pradesh horticulture expansion:Protected cultivation investments in chili, tomato, and capsicum are creating concentrated demand for biofungicides with shorter residue windows than synthetic alternatives.
- Biostimulant guideline harmonization:Pending central biostimulant regulations will clarify product categorization boundaries, enabling formulation innovators to position multi-function products without regulatory ambiguity.
- Cooperative direct procurement:Maharashtra farmer producer organizations are establishing captive microbial inoculant production units, bypassing traditional agri-dealer markups and building technical capacity at village level.
Industry Challenges
- Microbiologist talent scarcity:Industrial fermentation expertise concentrates in pharmaceutical hubs around Hyderabad and Bengaluru, leaving agritech biological facilities in smaller cities understaffed for strain optimization and quality control.
- Cold chain integrity gaps:Viable cell count degradation during last-mile distribution to southern and western hinterlands forces manufacturers to over-formulate products, eroding unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Agricultural Biologicals Market |
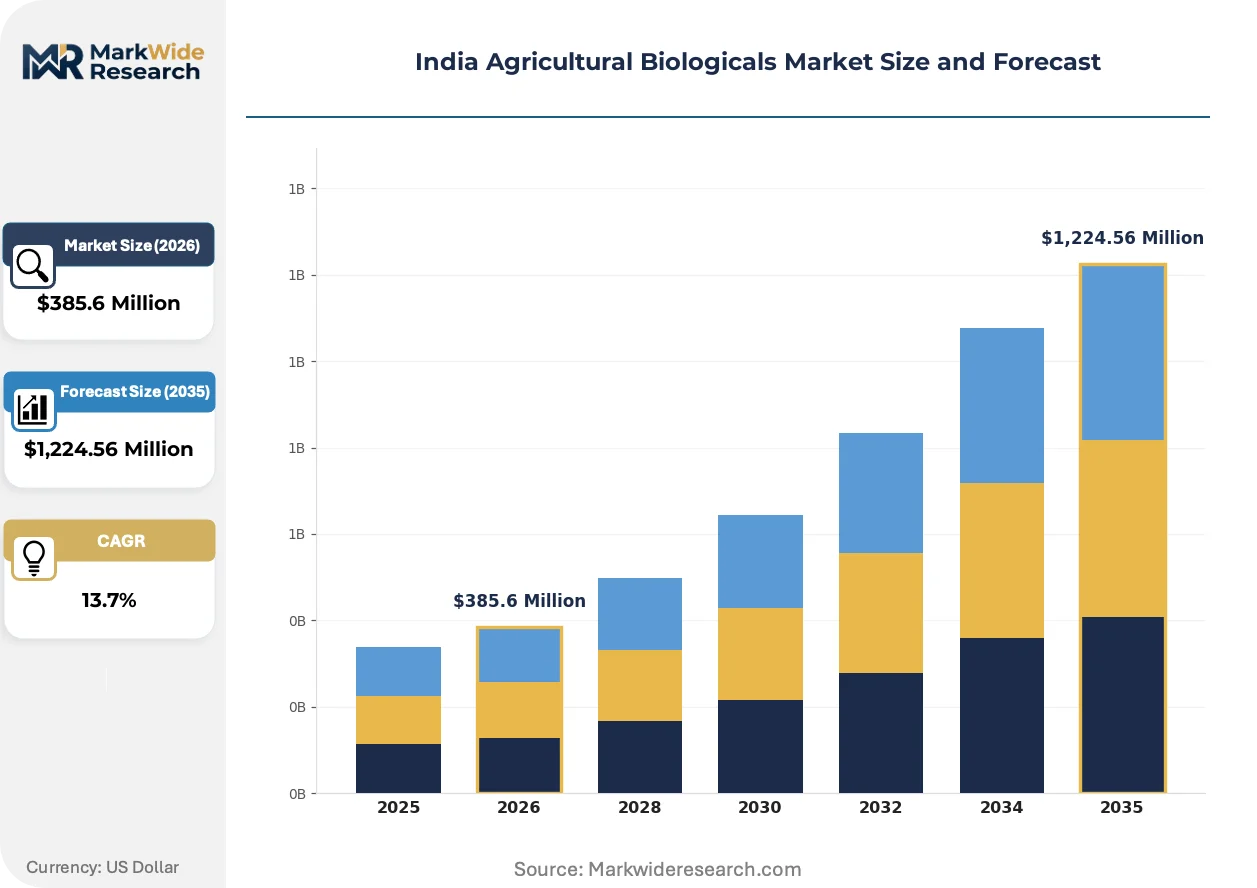
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,224.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopesticides, Biofertilizers, Biofungicides, Plant Growth Regulators Application: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Direct Sales, Online Retail, Distributors, Agriculture Expos End User: Farmers, Agricultural Cooperatives, Research Institutions, Commercial Growers |
| Companies Covered | Coromandel International Ltd, Gujarat State Fertilizers & Chemicals Limited, Madras Fertilizers Limited, UPL Limited, PI Industries Ltd, BASF India Ltd, Syngenta India Inc, SOM Phytopharma (India) Limited, IPL Biologicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Agricultural Biologicals Market Trends and Innovations
Formulation science and delivery mechanism advances are compressing the efficacy gap between biological and chemical crop protection, while regulatory pressure on residue limits accelerates substitution timelines in export-oriented horticulture.
Consortia-based microbial formulations combining nitrogen-fixing bacteria with phosphate-solubilizing fungi are displacing single-strain inoculants in soybean and groundnut cultivation. Seed treatment companies in Gujarat and Madhya Pradesh are integrating these multi-species products into standard coating protocols. This convergence with precision seeding equipment is enabling simultaneous application of biological and chemical inputs without separate field operations.
FSSAI residue standards for exported mangoes, grapes, and pomegranates are tightening maximum permissible limits for synthetic fungicides, redirecting procurement toward biocontrol alternatives in Maharashtra and Karnataka packing houses. Exporters are pre-certifying orchards under organic transition protocols to secure European and Middle Eastern market access. The compliance burden falls heaviest on smallholder aggregators lacking in-house testing infrastructure.
Horticulture farmer producer organizations are consolidating input procurement through digital platforms that aggregate demand across village clusters, disintermediating traditional agri-dealer networks. These cooperatives negotiate direct supply contracts with biological manufacturers, securing volume discounts and technical support unavailable through fragmented retail channels. The procurement transformation is most advanced in Nashik and Sangli grape belts where export quality requirements demand traceable input documentation.
India Agricultural Biologicals Market Segmentation
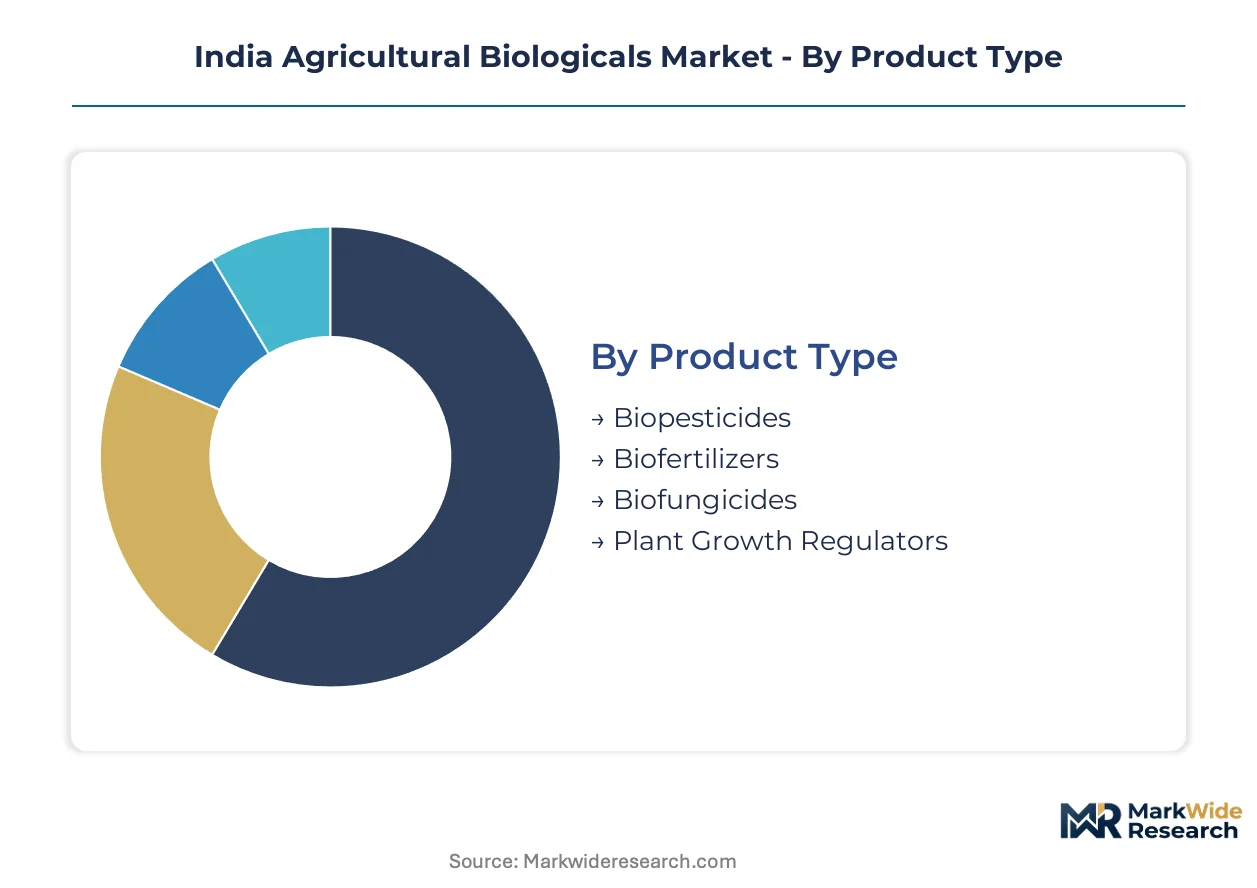
Segmentation in the India Agricultural Biologicals Market reveals how regulatory pathways, residue compliance burdens, and distribution infrastructure shape procurement patterns across product categories and end-use applications. Each segment carries distinct certification requirements from BIS, FSSAI, and state agricultural departments that determine market access timelines and cost structures.
Product Type:
BIS certification requirements vary sharply across product categories, with biopesticides facing the most stringent microbial strain documentation while plant growth regulators navigate overlapping jurisdiction between agricultural and pharmaceutical regulators.
- Biopesticides:Formulated from living organisms including bacteria, fungi, and viruses targeting specific pest species through infection or competitive exclusion. Demand clusters in Maharashtra grape belts and Karnataka mango orchards where FSSAI residue limits for European exports compel substitution away from synthetic chemicals.
- Biofertilizers:Microbial inoculants containing nitrogen-fixing rhizobia, phosphate-solubilizing bacteria, or mycorrhizal fungi that enhance nutrient availability without chemical inputs. Procurement concentrates through Gujarat and Maharashtra cooperative networks where state organic farming missions subsidize bulk distribution to soybean and groundnut cultivators.
- Biofungicides:Antagonistic microorganisms or derived metabolites suppressing fungal pathogens through hyperparasitism or antibiosis. Adoption accelerates in protected cultivation clusters around Hyderabad and Pune.
- Plant Growth Regulators:Naturally derived or fermentation-based compounds modulating physiological processes including flowering, fruit set, and stress tolerance. Application expands in high-value horticulture for export quality synchronization.
Leading the category by volume: Biofertilizers. Growing fastest: Biofungicides.
Application:
Cost tier differentiation separates residue-sensitive export crops from volume-driven food security commodities, with pricing and formulation sophistication scaling accordingly.
- Cereals:Wheat and rice cultivation under government procurement programs sustains foundational biofertilizer demand, particularly urea-reducing microbial inoculants in Punjab and Haryana. Adoption lags in northern states where chemical application routines dominate extension service training.
- Fruits:Mango, grape, and pomegranate orchards in Maharashtra and Karnataka drive premium biocontrol procurement tied to European and Middle Eastern export contracts. Pre-certification requirements under organic transition protocols force traceable input documentation through integrated packhouse systems.
- Vegetables:Chili, tomato, and capsicum cultivation in Telangana and Andhra Pradesh protected structures generates concentrated biofungicide demand. Shorter harvest cycles and residue windows favor biological alternatives with pre-harvest intervals measured in days rather than weeks.
- Oilseeds:Soybean and groundnut cultivation in Madhya Pradesh and Gujarat integrates multi-strain inoculants into standard seed treatment protocols. Cooperative procurement structures in these states aggregate smallholder demand into manufacturer-direct contracts.
Volume leadership: Cereals. Steepest expansion trajectory: Fruits.
Distribution Channel:
Channel selection correlates with customer scale and technical support requirements, with direct and digital pathways gaining share among organized cooperatives while traditional distributors retain smallholder reach.
- Direct Sales:Manufacturer-to-cooperative contracts bypassing agri-dealer markups. Nashik and Sangli grape farmer producer organizations leverage this channel for traceable documentation required by export packhouses.
- Online Retail:Digital platforms aggregating demand across village clusters with technical advisory content. Penetration concentrates in western and southern districts with smartphone-enabled extension services.
- Distributors:Traditional agri-input dealer networks with cold storage capabilities for viable cell count preservation. Remains dominant in northern cereal belts where relationship-based credit terms structure purchasing.
- Agriculture Expos:Seasonal demonstration events hosted by state agricultural universities and Krishi Vigyan Kendras. Critical for farmer education on application protocols diverging from chemical spraying routines.
Widest reach: Distributors. Fastest channel expansion: Direct Sales.
End User:
User type determines formulation packaging, technical service intensity, and regulatory documentation requirements, with commercial operators demanding batch-level traceability absent in smallholder segments.
- Farmers:Individual smallholders and mid-scale operators purchasing through retail channels or cooperative aggregation. Knowledge gaps on temperature and moisture protocols slow biological adoption in northern cereal-dependent states.
- Agricultural Cooperatives:Farmer producer organizations in Maharashtra and Gujarat establishing captive microbial production units or negotiating direct manufacturer contracts. These entities build technical capacity at village level through trained input advisors.
- Research Institutions:State agricultural universities and ICAR centers conducting strain validation and field efficacy trials. Generate data supporting BIS registration dossiers for novel biocontrol agents.
- Commercial Growers:Integrated horticulture operations and export-oriented packhouses with in-house testing infrastructure. Pre-certify orchards under organic protocols to secure premium market access.
Largest user base: Farmers. Fastest-growing engagement: Agricultural Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in western and southern state clusters where horticulture intensity intersects with export-oriented residue compliance requirements. Maharashtra and Gujarat anchor procurement volume through cooperative networks and PLI-linked manufacturing investments.
Maharashtra
Nashik and Sangli grape belts drive premium biofungicide procurement for European export contracts. The state organic farming mission subsidizes cooperative bulk purchases of microbial inoculants. Farmer producer organizations in these districts establish direct manufacturer contracts to secure traceable input documentation required by packhouses.
Gujarat
Soybean and groundnut cultivation integrates multi-strain biofertilizers into standard seed treatment protocols. The state fertilizer cooperative infrastructure redirects toward microbial product distribution under PLI scheme incentives. Domestic fermentation facilities in Anand and Vadodara supply nitrogen-fixing inoculants to western India oilseed belts.
Karnataka
Mango orchards and protected vegetable structures in Bengaluru Rural and Kolar districts generate concentrated biocontrol demand. BIS certification requirements for novel microbial strains extend registration timelines, favoring established suppliers with existing dossiers. State agricultural universities conduct field efficacy trials supporting farmer adoption.
Andhra Pradesh
Chili and tomato cultivation in Guntur and Chittoor districts creates biofungicide pull for shorter pre-harvest intervals. The state organic farming mission guarantees offtake channels for biofertilizer cooperatives through subsidy-linked distribution networks. Protected cultivation investments accelerate biological substitution away from synthetic fungicides.
Telangana
Hyderabad-centered pharmaceutical fermentation expertise supplies industrial microbiology talent to agritech biological facilities. Medak and Rangareddy districts host protected cultivation clusters demanding residue-compliant crop protection. Cold chain infrastructure gaps force manufacturers to over-formulate products for viable cell count preservation during last-mile distribution.
India Agricultural Biologicals Market Competitive Landscape
Domestic producers anchor volume supply through cooperative-linked distribution; multinational specialists hold premium positioning in export-oriented horticulture segments. The market structures around three tiers: legacy fertilizer companies extending infrastructure into microbial lines, dedicated biological manufacturers with strain optimization capabilities, and agrochemical conglomerates diversifying portfolios. Competitive moves concentrate on backward integration into fermentation capacity and direct procurement partnerships with farmer producer organizations.
Within the domestic tier, Coromandel International Ltd and Gujarat State Fertilizers & Chemicals Limited exemplify legacy infrastructure extension strategies. UPL Limited and Syngenta India Inc occupy positions bridging mass-market distribution with specialized biocontrol formulations. These anchors represent divergent archetypes: cooperative-integrated domestic suppliers versus research-intensive multinational affiliates competing on residue compliance and technical advisory intensity.
| Leading Market Players |
|---|
| Coromandel International Ltd |
| Gujarat State Fertilizers & Chemicals Limited |
| Madras Fertilizers Limited |
| UPL Limited |
| PI Industries Ltd |
| BASF India Ltd |
| Syngenta India Inc |
| SOM Phytopharma (India) Limited |
| IPL Biologicals |
| Others |
Pricing and Supply Chain Analysis
Fermentation media import costs from Chinese suppliers cascade through domestic manufacturing into three-tier pricing stratification across premium, standard, and economy levels. Maharashtra and Gujarat cooperatives negotiate volume discounts that compress dealer markups, while northern cereal states absorb higher per-unit costs through fragmented retail channels.
Pricing Analysis
Volume leadership in biofertilizers trades at compressed margins through cooperative procurement, while biofungicide premiums in export horticulture sustain wider spreads. Price differentiation hinges on BIS certification tier and cold chain integrity grade. Pricing pressure stems from Chinese strain import volatility eroding formulation economics. Smallholder farmers in Punjab and Haryana exhibit highest price sensitivity; integrated Maharashtra packhouses demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and European suppliers of concentrated microbial strains and specialized fermentation substrates. Domestic production draws from imported active ingredients, Indian carrier materials, and regional packaging substrates. Supply chain risk centers on currency-driven cost spikes disrupting margin structures. Distribution runs through cooperative-linked direct contracts in western states and traditional agri-dealer networks in northern belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race into captive fermentation capacity, with PLI scheme incentives accelerating upstream control over strain production and quality assurance.
For Market Incumbents: Anticipate biofungicide margin compression from emerging domestic specialists by locking multi-year offtake contracts with Maharashtra and Karnataka cooperatives. Invest in BIS certification pipelines for novel biocontrol strains before regulatory backlogs extend further. Channel control through direct procurement platforms offers defensive moats against dealer disintermediation.
For New Entrants and Emerging Players: Enter via Telangana and Andhra Pradesh protected cultivation clusters where biofungicide demand outpaces established supply. Target chili and tomato cultivators in Guntur and Chittoor with application-protocol advisory bundled into seed treatment offerings. Digital cooperative platforms provide the most penetrable go-to-market angle for bypassing entrenched distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fermentation specialists in Gujarat with PLI-linked capacity expansion underway. Long-term viability rests on backward integration into strain libraries and cold chain infrastructure. Watch for BIS registration timeline compression as the inflection signal indicating regulatory arbitrage windows closing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Libraries | Captive microbial strain ownership reduces Chinese import dependence and stabilizes formulation costs. |
| Direct Cooperative Procurement Platforms | Maharashtra farmer producer organizations bypass dealer markups while securing traceable input documentation. |
| Cold Chain Infrastructure Investment | Viable cell count preservation in Telangana and Karnataka hinterlands enables standard-formulation economics. |
| BIS Certification Pipeline Expansion | Novel biocontrol registration dossiers accelerate market access before competitor backlog accumulates. |
| Multi-Strain Consortia Development | Nitrogen-fixing and phosphate-solubilizing combinations displace single-strain inoculants in Gujarat oilseed belts. |
Research Methodology
Independent corroboration across state agricultural university researchers, cooperative procurement managers, and BIS certification officers underwrites the qualitative findings. Primary interviews with microbial fermentation plant managers, Krishi Vigyan Kendra extension specialists, and export packhouse quality directors combined with secondary validation from FSSAI residue compliance databases, state organic farming mission subsidy records, and PLI scheme beneficiary disclosures. Bottom-up demand aggregation across crop segments and top-down supply capacity assessment triangulate volume estimates.
Comparable-period anchoring to historical biofertilizer cooperative procurement volumes and biocontrol export certification trajectories structured the forecast window. The analytical framework models product type, application crop, distribution channel, and end-user scale dimensions throughout the forecast period. CAGRs derive from segment-level growth rate synthesis. Industry-specific inputs include BIS registration pipeline velocity and state subsidy disbursement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Chinese strain import disruptions or accelerated FSSAI residue limit tightening. Forecasts reflect documented assumptions on PLI scheme continuity and state organic mission funding levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Silage Inoculant and Enzyme Market