
 Africa Biostimulants Market | 2026-2036
Africa Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Biostimulants Market Outlook
Modular formulation packaging is repositioning buyer choice across the Africa biostimulants sector, as suppliers unbundle single-product jugs into season-specific kits combining seaweed extracts with microbial inoculants. Biolchim SPA leverages its Italian manufacturing base to sustain premium liquid concentrate exports into North African distributor networks. Koppert Biological Systems Inc anchors its position through specialized technical advisory teams embedded with commercial horticulture operations in Kenya and Morocco. Haifa Group competes on granular formulation expertise, occupying the phosphite-biostimulant crossover segment where controlled-release chemistry meets plant stress management.
Biostimulants comprise organic and inorganic substances applied to plants or soils to stimulate natural processes that enhance nutrient uptake efficiency, stress tolerance, and crop quality independent of their nutrient content, with formulations typically containing humic acids derived from leonardite oxidation, seaweed polysaccharides extracted through alkaline hydrolysis, or viable microbial cultures exceeding colony-forming unit thresholds. The primary commercial purpose centers on reducing synthetic fertilizer dependency while maintaining yield stability across rain-fed and irrigated production systems. Humic acids dominate current product volumes due to established extraction infrastructure and lower per-hectare application costs, yet microbial inoculants represent the fastest-expanding category as Rhizobium and Trichoderma strains demonstrate consistent nodulation improvement in legume rotations. Agricultural crops absorb the majority of end-user spending, though horticultural plants command superior margin pools through greenhouse tomato and berry applications where premium pricing justifies precision dosing.
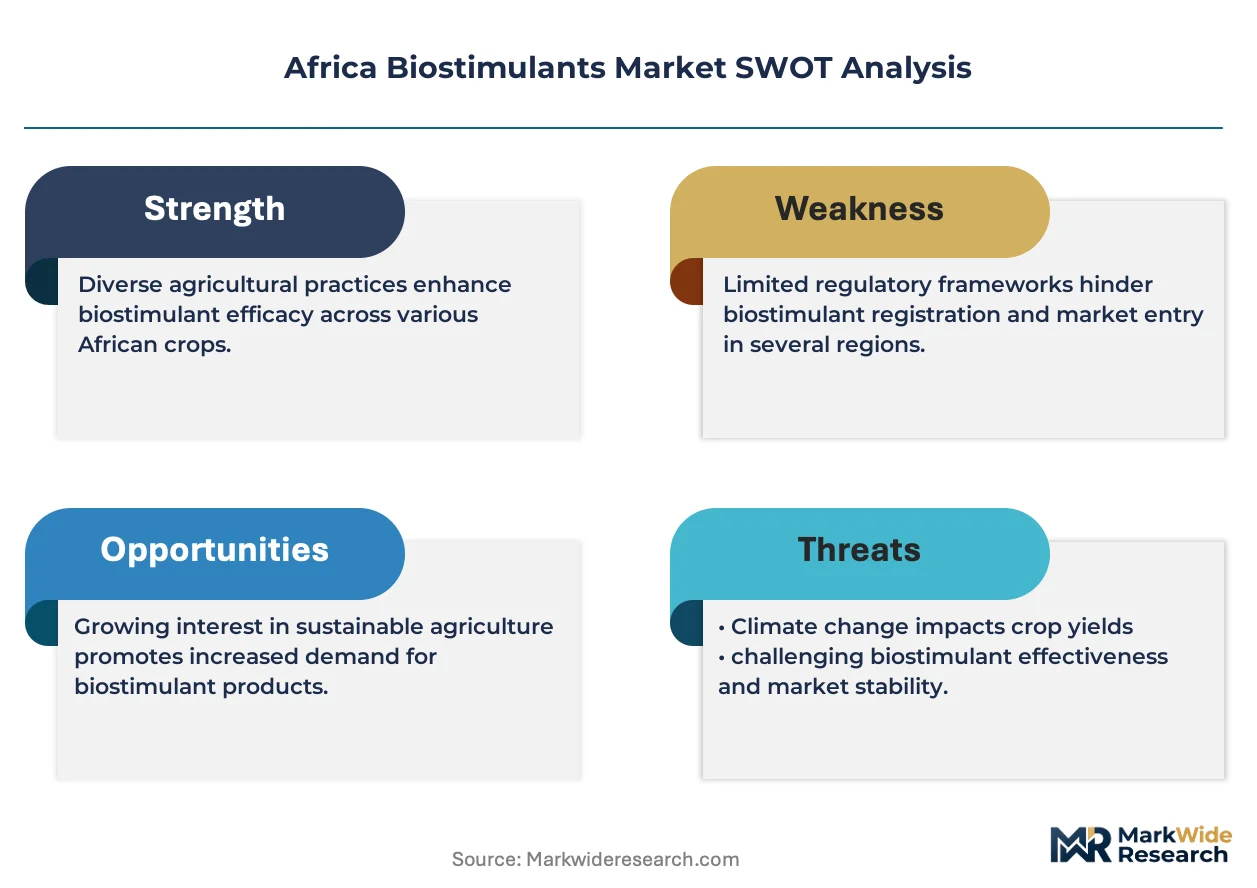
South Africa's Registrar of Act 36 of 1947 governs agricultural remedy registration, while Kenya's Pest Control Products Board enforces import quality specifications that increasingly reference OECD biopesticide guidance. The African Union's Fertilizer and Soil Health Summit framework encourages member states to integrate biostimulant efficacy data into national input subsidy programs, reshaping procurement criteria toward verified field trial results. Stakeholders must monitor how harmonization between national registries and the AU's continental standards body alters market access timelines for new microbial strain registrations.
Market Dynamics
Row crop farmers across East Africa are expanding microbial inoculant applications as phosphorus access constraints intensify, while South Africa's tightened fertilizer registration protocols force suppliers to submit full biochemical dossiers before market entry.
Growth Catalysts
- The African Union's Fertilizer and Soil Health Summit framework:Member states now integrate biostimulant efficacy data into national input subsidy programs, redirecting procurement criteria toward verified field trial results.
- Ethiopia's highland cereal belts:Agricultural cooperatives bulk-purchase liquid formulations for rain-fed wheat programs, creating concentrated demand nodes that attract distributor investment.
- Microbial inoculants:Rhizobium and Trichoderma strains demonstrate consistent nodulation improvement in legume rotations, accelerating farmer acceptance beyond established humic acid applications.
Market Restraints
- Input cost volatility:Seaweed polysaccharide extraction depends on marine biomass supply chains vulnerable to Indian Ocean temperature fluctuations.
- Regulatory friction:South Africa's Registrar of Act 36 of 1947 imposes extended registration timelines that delay new microbial strain commercialization.
- Technical limitation:Colony-forming unit viability degrades rapidly in liquid concentrates stored above 25°C, constraining distribution reach into interior markets lacking cold chain infrastructure.
Strategic Opportunities
- Kenya's commercial horticulture sector:Greenhouse tomato and berry operations justify premium pricing for precision-dosed biostimulant applications.
- Technology convergence:Controlled-release phosphite chemistry intersects with plant stress management, opening crossover formulations between fertilizer and biostimulant classifications.
- Modular formulation packaging:Suppliers unbundle single-product jugs into season-specific kits combining seaweed extracts with microbial inoculants, enabling cooperative bulk-purchase optimization.
Industry Challenges
- Technical advisory capacity:Embedded agronomist teams require sustained investment to support commercial horticulture operations across dispersed growing regions.
- Harmonization complexity:National registries operate independently of the African Union's continental standards body, fragmenting microbial strain approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Biostimulants Market |
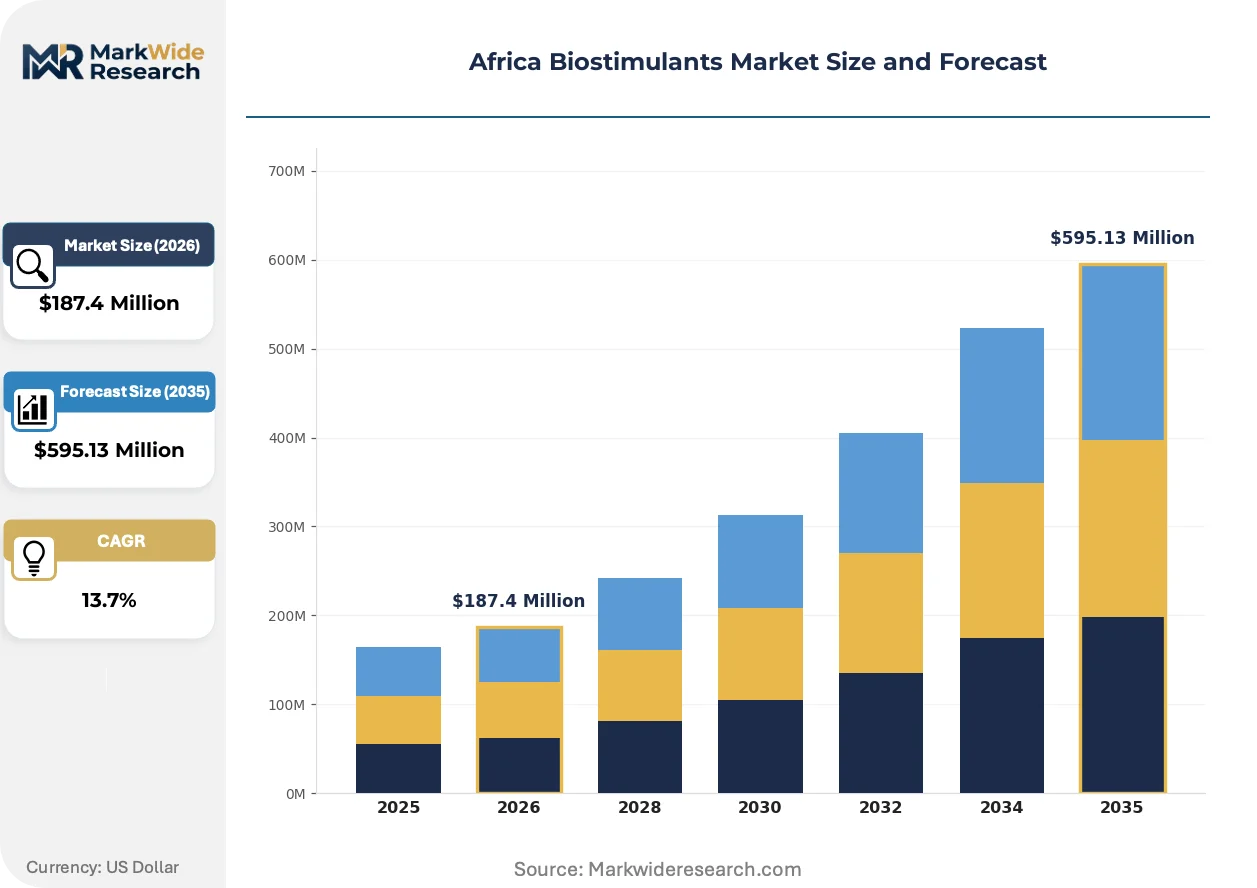
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Microbial Inoculants, Amino Acids Application: Agricultural Crops, Horticultural Plants, Turf & Ornamentals, Soil Treatment Formulation: Liquid, Granular, Powder, Gel End User: Farmers, Distributors, Retailers, Agricultural Researchers |
| Companies Covered | Biolchim SPA, Humic Growth Solutions Inc, Koppert Biological Systems Inc, Microbial Biological Fertilizers International, Trade Corporation International, Coromandel International Ltd, T Stanes and Company Limited, Atlántica Agrícola, Haifa Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Biostimulants Market Strategic Shifts
Formulation chemistry and distribution architecture are converging to reshape how biostimulants reach smallholder and commercial farms across diverse agro-ecological zones.
Microbial inoculants containing viable Trichoderma and Rhizobium cultures are overtaking humic acid derivatives as the dominant growth category. Commercial maize operations in Tanzania and Uganda now specify microbial strains in procurement tenders. This shift is compressing margins for established leonardite-based suppliers while rewarding manufacturers with fermentation capacity.
Kenya's Pest Control Products Board has tightened import quality specifications to reference OECD biopesticide guidance. The regulatory elevation disqualifies lower-grade formulations previously entering through informal channels. Distributor networks in Nairobi and Mombasa now prioritize dossier-complete suppliers to avoid customs detention.
Cooperative bulk-purchase programs are displacing individual farmer retail buying across Ethiopia's highland wheat belts. Aggregated demand concentrates negotiation leverage with liquid formulation suppliers. This procurement consolidation is most visible in Amhara and Oromia regions where rain-fed cereal expansion depends on subsidized input access.
Africa Biostimulants Market Segmentation
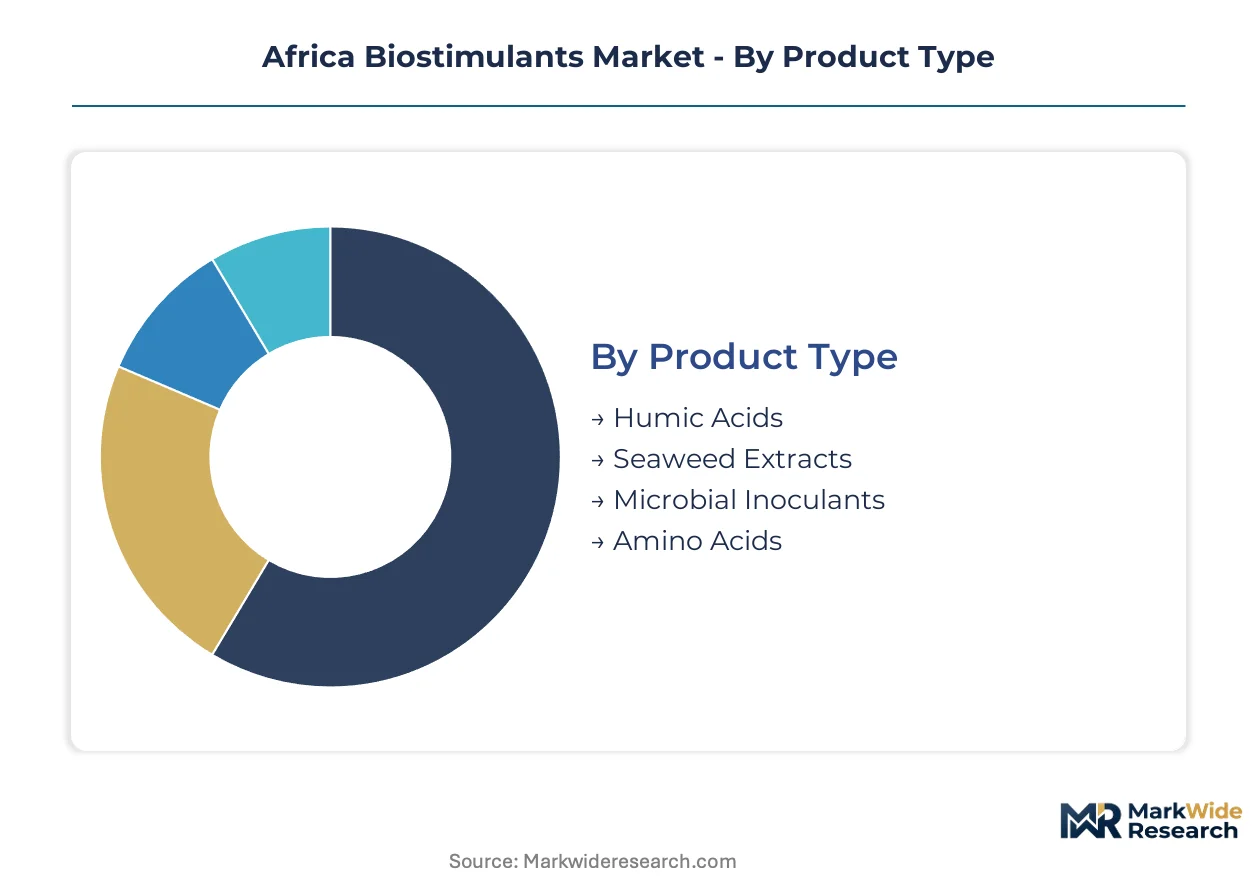
Biostimulant purchasing across Africa fragments along product chemistry, crop application, and distribution channel. Buyers weigh formulation stability against storage infrastructure, while subsidy eligibility reshapes procurement patterns in key cereal belts.
Product Type:
Cost tier drives farmer selection, with per-hectare application expense determining uptake across rain-fed and irrigated systems.
- Humic Acids:Derived from leonardite oxidation, these formulations offer established extraction infrastructure and lower unit economics. Demand concentrates in South Africa's maize belt where cooperatives prioritize proven shelf stability over novel microbial strains.
- Microbial Inoculants:Viable Rhizobium and Trichoderma cultures exceeding colony-forming unit thresholds deliver phosphorus solubilization and nodulation improvement. Ethiopia's highland wheat programs and Tanzania's commercial maize operations now specify microbial strains in procurement tenders, accelerating category expansion beyond legume rotations.
- Seaweed Extracts:Polysaccharides extracted through alkaline hydrolysis of marine biomass supply stress tolerance applications.
- Amino Acids:Protein hydrolysate formulations target precision dosing in greenhouse environments.
Volume sits with Humic Acids; growth tilts toward Microbial Inoculants.
Application:
Margin structure separates commodity grain systems from premium horticulture operations.
- Agricultural Crops:Maize, wheat, and legume rotations absorb the majority of end-user spending through bulk cooperative procurement. Rain-fed cereal expansion across Ethiopia's Amhara and Oromia regions depends on subsidized input access, creating concentrated demand nodes.
- Horticultural Plants:Greenhouse tomato and berry operations in Kenya justify premium pricing for precision-dosed applications where yield quality directly impacts export revenue. Technical advisory requirements elevate supplier stickiness in this segment.
- Turf & Ornamentals:Golf course and landscape maintenance applications concentrate in South Africa's urban centers.
- Soil Treatment:Broad-acre conditioning programs target degraded rangeland rehabilitation.
Revenue concentrates in Agricultural Crops; margin expansion favors Horticultural Plants.
Formulation:
Supply chain reach constrains choice between liquid concentrates and solid carriers.
- Liquid:Concentrated suspensions enable precise dilution and foliar application. Ethiopian cooperatives bulk-purchase liquid kits combining multiple actives, though colony-forming unit viability degrades above 25°C, limiting interior distribution without cold chain infrastructure.
- Granular:Controlled-release phosphite chemistry intersects with plant stress management, opening crossover formulations. Haifa Group occupies this intersection where fertilizer and biostimulant classifications blur.
- Powder:Dry formulations reduce transport cost for landlocked markets.
- Gel:Viscous carriers target precision placement in root zone applications.
Procurement volume favors Liquid; Granular gains share where controlled-release chemistry commands premium positioning.
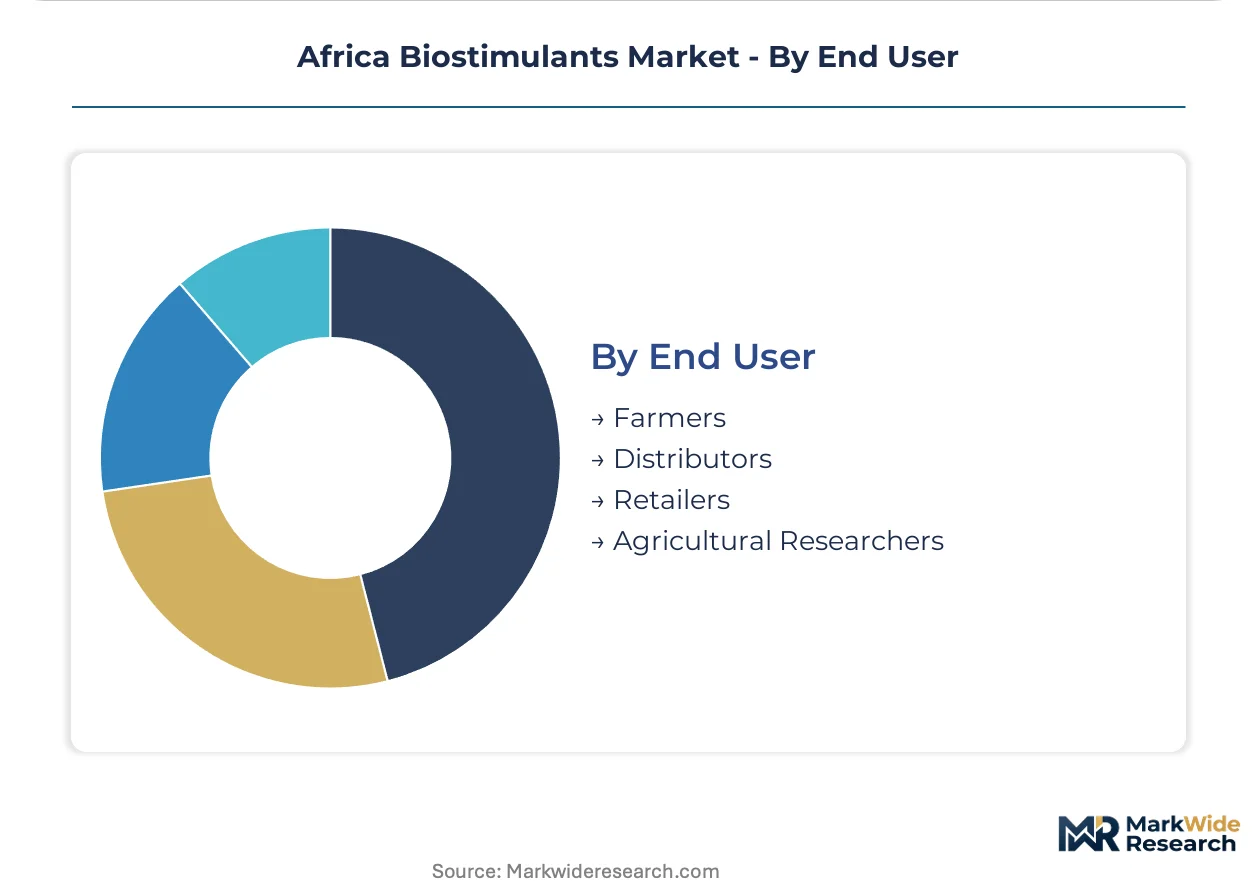
End User:
Buying power consolidation reshapes channel relationships across the value chain.
- Farmers:Smallholder and commercial operations in East Africa increasingly aggregate demand through cooperative structures. Individual retail purchasing persists where subsidy access fragments.
- Distributors:Nairobi and Mombasa networks now prioritize dossier-complete suppliers after Kenya's Pest Control Products Board tightened import specifications referencing OECD biopesticide guidance.
- Retailers:Agro-dealer stockists serve last-mile access in dispersed growing regions.
- Agricultural Researchers:Trial stations and universities generate efficacy data for registration dossiers.
Transaction volume flows through Distributors; cooperative aggregation is displacing direct Farmer procurement in Ethiopia's highland belts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East African Community's agricultural input incentive zones concentrate biostimulant demand around cooperative procurement hubs in Ethiopia and Kenya. South Africa's Western Cape and Gauteng provinces anchor southern African distribution networks through Act 36 of 1947 registration pathways.
Ethiopia
Highland wheat cooperatives in Amhara and Oromia regions bulk-purchase liquid microbial formulations for rain-fed cereal programs. The Agricultural Transformation Agency integrates biostimulant efficacy data into national input subsidy frameworks. Addis Ababa serves as the procurement coordination center where distributor networks consolidate orders for interior highland belts.
South Africa
Commercial maize operations in the Free State and Mpumalanga provinces specify humic acid derivatives with proven shelf stability. The Registrar of Act 36 of 1947 imposes extended biochemical dossier requirements that filter lower-grade imports. Cape Town anchors premium horticulture applications where greenhouse operations justify precision-dosed seaweed extract programs.
Kenya
Greenhouse tomato and berry exporters in Naivasha and Thika drive premium-tier demand for precision biostimulant applications. The Pest Control Products Board tightened import specifications referencing OECD biopesticide guidance, disqualifying informal channel entrants. Nairobi and Mombasa distributor networks now prioritize dossier-complete suppliers to avoid customs detention.
Tanzania
Commercial maize procurement tenders in the Southern Highlands now specify viable Rhizobium and Trichoderma strains for phosphorus solubilization. The Tanzania Fertilizer Regulatory Authority aligns registration protocols with East African Community harmonization frameworks. Morogoro's agricultural research stations generate field trial data supporting cooperative bulk-purchase decisions.
Morocco
Phosphite-biostimulant crossover formulations gain traction in irrigated citrus and olive operations around Marrakech and Agadir. The national fertilizer regulator requires import quality certifications that reference EU fertilizer directive standards. Casablanca's port infrastructure enables granular formulation distribution into Maghreb interior markets lacking cold chain coverage.
Africa Biostimulants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and distribution architecture. The market exhibits tiered concentration where Italian and Israeli manufacturers anchor premium liquid concentrate exports while regional distributors embed technical advisory capacity. Three archetypes dominate: fermentation-capable microbial strain developers, leonardite-based humic acid extractors, and phosphite-biostimulant crossover formulators. Competitive moves center on cooperative procurement partnerships and registration dossier completeness under tightening national protocols.
Among European-anchored specialists, Biolchim SPA and Koppert Biological Systems Inc exemplify the technical advisory archetype through embedded agronomist teams. Haifa Group occupies the phosphite-biostimulant intersection where controlled-release chemistry meets plant stress management. These three companies represent distinct competitive positioning vectors: Italian manufacturing base leverage, specialized horticulture advisory embedding, and granular formulation expertise at the fertilizer-biostimulant boundary.
| Leading Market Players |
|---|
| Biolchim SPA |
| Humic Growth Solutions Inc |
| Koppert Biological Systems Inc |
| Microbial Biological Fertilizers International |
| Trade Corporation International |
| Coromandel International Ltd |
| T Stanes and Company Limited |
| Atlántica Agrícola |
| Haifa Group |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation across microbial inoculants, humic acids, and seaweed extracts manifests in divergent supply chain configurations, where cold chain requirements for viable colony-forming unit formulations compress distribution reach into Ethiopia's interior highlands while granular phosphite crossovers exploit established fertilizer logistics through Casablanca and Durban port infrastructure.
Pricing Analysis
Short lead-time premiums attach to liquid microbial concentrates shipped direct from Italian and Israeli manufacturing bases into Nairobi and Addis Ababa distributor hubs, while spot inventory discounts emerge for humic acid derivatives warehoused in South Africa's Free State maize belt. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under Kenya's Pest Control Products Board OECD-aligned specifications versus informal channel entrants. Pricing pressure stems from cooperative bulk-purchase consolidation across Ethiopia's Amhara and Oromia regions, where aggregated demand concentrates negotiation leverage. Smallholder farmers in rain-fed cereal systems exhibit highest price sensitivity, while Kenyan greenhouse tomato exporters accept premium positioning for precision-dosed amino acid formulations.
Supply Chain Analysis
Registration dossier completeness under South Africa's Registrar of Act 36 of 1947 and Kenya's Pest Control Products Board protocols gates supplier access, filtering lower-grade imports from distributor networks in Nairobi and Mombasa. Manufacturing concentration rests on Italy, Israel, and South Africa for fermentation-capable microbial strains, leonardite oxidation infrastructure, and controlled-release phosphite chemistry respectively. Raw material dependencies draw from Indian Ocean marine biomass for seaweed polysaccharides, leonardite deposits in South Africa and Morocco, and fermentation substrates for Trichoderma and Rhizobium cultures. Single-source vulnerability concentrates in cold chain-dependent liquid concentrates where colony-forming unit viability degrades above 25°C. Distribution runs through cooperative procurement hubs in Ethiopia's highland belts and commercial horticulture advisory channels in Kenya's Naivasha and Thika clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial inoculant technology is displacing legacy humic acid dominance across East African maize and wheat systems, creating asymmetric repositioning opportunities for fermentation-capable suppliers versus established leonardite extractors.
For Market Incumbents: Lock in cooperative procurement partnerships across Ethiopia's Agricultural Transformation Agency subsidy frameworks before microbial strain specifications harden in Tanzania and Uganda commercial tenders. Invest in fermentation capacity expansion or backward integration into viable culture production to defend margin position against pure-play microbial specialists. Prioritize dossier completeness under South Africa's Act 36 protocols to maintain distributor prioritization as Kenyan import specifications tighten. For New Entrants and Emerging Players: Begin with granular phosphite-biostimulant crossover formulations targeting Morocco's irrigated citrus and olive operations where cold chain infrastructure gaps exclude liquid microbial competitors. Exploit underpenetrated cooperative channels in Tanzania's Southern Highlands where commercial maize procurement tenders now specify viable Rhizobium strains. Anchor go-to-market strategy through embedded technical advisory teams mimicking Koppert Biological Systems' horticulture support model in Kenya. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-capable microbial strain developers given African Union Fertilizer and Soil Health Summit integration of biostimulant efficacy data into national subsidy programs. Long-term viability favors suppliers with dual capability across liquid concentrate exports and granular controlled-release formulations spanning cold chain and ambient distribution environments. Watch for harmonization progress between national registries and AU continental standards body as inflection signal for accelerated microbial strain approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Procurement Partnership | Ethiopia's Agricultural Transformation Agency subsidy integration locks in volume commitments across Amhara and Oromia highland belts. |
| Registration Dossier Investment | Complete biochemical submissions under South Africa's Act 36 and Kenya's Pest Control Products Board OECD protocols secure distributor prioritization. |
| Fermentation Capacity Expansion | In-house Rhizoderma and Trichoderma culture production reduces dependency on Italian manufacturing lead times. |
| Technical Advisory Embedding | Specialized agronomist teams in Kenyan greenhouse operations replicate Koppert Biological Systems' sticky supplier positioning. |
| Modular Formulation Packaging | Season-specific kits combining seaweed extracts with microbial inoculants optimize cooperative bulk-purchase economics. |
Study Parameters
Independent corroboration across agricultural cooperative procurement managers, distributor network heads in Nairobi and Addis Ababa, fermentation plant technical directors, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews with Ethiopia's Agricultural Transformation Agency input subsidy coordinators, Kenya's Pest Control Products Board import inspectors, and South Africa's Registrar of Act 36 dossier reviewers combined with secondary validation from African Union Fertilizer and Soil Health Summit framework documents, East African Community harmonization protocols, and OECD biopesticide guidance publications. Bottom-up demand modeling across cooperative aggregation trends and top-down supply assessment through manufacturing capacity disclosures triangulate market sizing.
Comparable-period anchoring to historical registration timeline data and subsidy program rollout phases structured the projection horizon across the analysis window. Segmentation dimensions modeled include product chemistry tier, crop application intensity, formulation stability requirements, and end-user procurement consolidation patterns. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion trajectories. Industry-specific forecast inputs incorporate cold chain infrastructure penetration indices and national registry harmonization progress indicators.
Underlying measurement precision varies by segment; granular phosphite formulations and established humic acid derivatives carry tighter precision than emerging microbial inoculant categories where colony-forming unit viability data remains sparse. Forecasts reflect assumptions regarding subsidy program continuity, marine biomass supply stability, and regulatory pathway convergence that could materially revise upon disruption. A model refresh is warranted upon material change in African Union continental standards body harmonization timelines or major Indian Ocean temperature fluctuation impacting seaweed polysaccharide extraction yields.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
North America Agricultural Biologicals Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Fish Vaccines Market