
 India Biopesticides Market | 2026-2036
India Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
India Biopesticides Market Outlook
Subscription-based agronomy advisory bundled with biopesticide replenishment is repositioning how Indian farmers procure crop protection. Coromandel International Ltd leverages its deep rural dealership network to lock in recurring bio-input purchases across Andhra Pradesh and Telangana. IPL Biologicals Limited anchors its competitiveness on domestic fermentation capacity for Bacillus thuringiensis strains, cutting import dependence for active ingredients. GrowTech Agri Science Private Limited specializes in pheromone-based integrated pest management kits that command premium pricing in horticulture clusters.
Biopesticides comprise living organisms, naturally occurring substances, and semiochemicals formulated to suppress agricultural pests through non-toxic modes of action, typically requiring 48-72 hour latency periods before mortality peaks. These inputs serve commercial farming systems where export-market residue thresholds and pollinator safety protocols restrict synthetic chemical application. Microbial formulations dominate current volume flows due to established production infrastructure for bacterial and fungal agents, while plant-based extracts capture accelerating interest in organic-certified horticulture. Application patterns reveal horticultural crops as the fastest-expanding addressable pool, driven by pomegranate, grape, and mango export consignments facing EU and Middle Eastern phytosanitary scrutiny.
BIS certification requirements for biopesticide efficacy claims and the CEA's guidelines on biological agriculture input standards create dual compliance gateways that filter out substandard suppliers. The PLI scheme for agrochemical manufacturing extends eligibility to biopesticide fermentation facilities, redirecting capital toward domestic active ingredient production rather than formulated import reliance. State agricultural universities in Karnataka and Tamil Nadu operate as de facto regulatory influencers through trial data protocols that determine commercial registration timelines. Stakeholders must track how FSSAI residue limit revisions for specific crop matrices reshape which biopesticide chemistries gain rapid farmer acceptance versus those requiring extended efficacy demonstration periods.
Market Dynamics
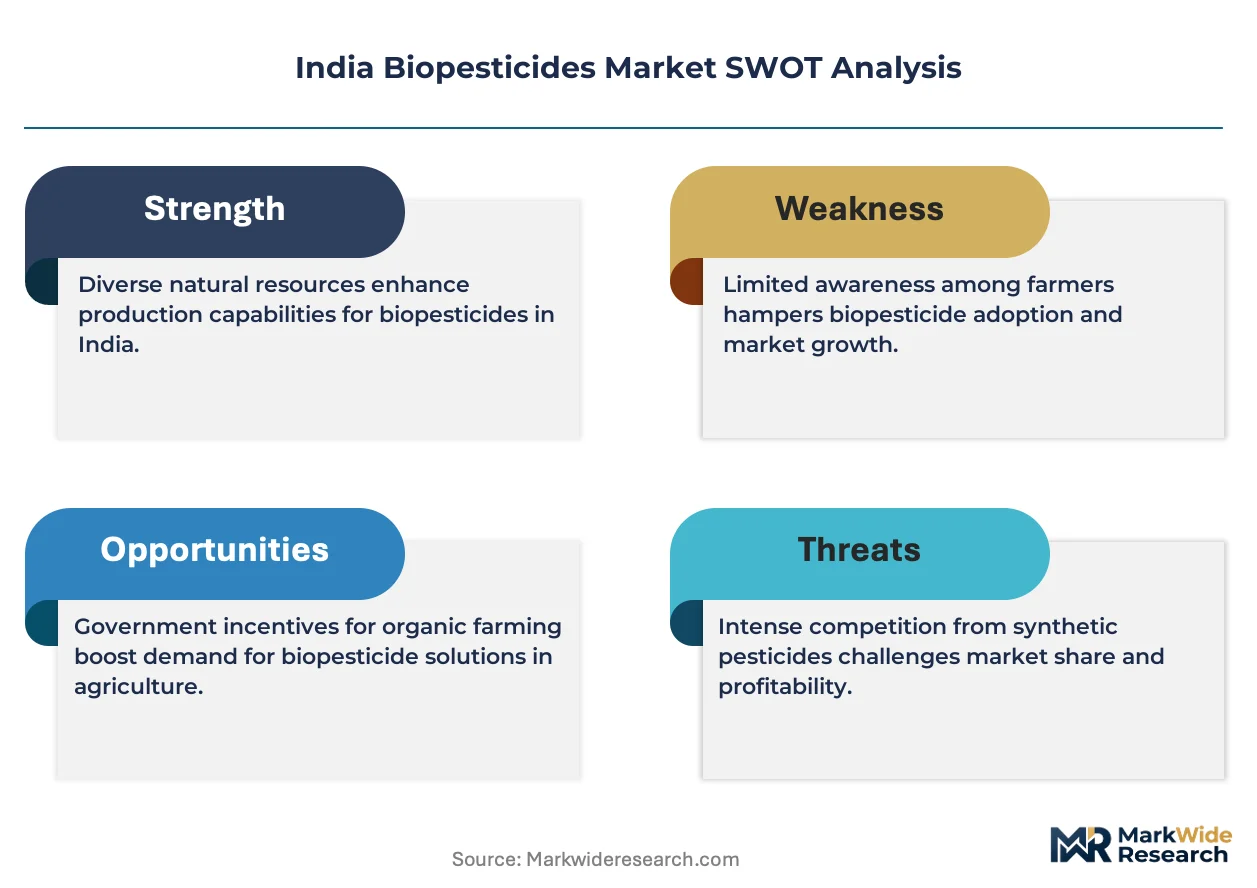
FSSAI residue limit enforcement and EU phytosanitary certification requirements are compressing synthetic chemical use windows across India's export-oriented horticulture belts, forcing rapid microbial input substitution.
Growth Catalysts
- Export Certification Pressure:European Union phytosanitary protocols for grapes and pomegranates mandate residue-free production, compelling Maharashtra farmers toward Bacillus-based formulations.
- CEA Biological Agriculture Guidelines:The Central Electricity Authority's input standards create compliance pathways that accelerate commercial registration for domestic microbial suppliers.
- PLI Scheme Eligibility:Production-linked incentives for fermentation facilities redirect capital toward in-house Bacillus thuringiensis production, reducing import dependence for active ingredients.
Market Restraints
- 48-72 Hour Efficacy Latency:Microbial biopesticides require extended mortality windows that conflict with acute pest pressure timelines in intensive cropping systems.
- BIS Certification Bottlenecks:Bureau of Indian Standards efficacy claim verification creates multi-year registration delays that filter out early-stage formulators.
- Temperature-Stability Constraints:Bacterial formulations face shelf-life degradation in ambient storage conditions prevalent across unregulated rural supply chains.
Strategic Opportunities
- Assam Tea Belt Penetration:Residue-free export protocols for orthodox tea create unmet demand for pheromone-based integrated pest management systems in currently underserved northeastern clusters.
- Subscription Advisory Bundling:Agronomy-as-a-service models lock in recurring bio-input purchases through dealer networks in Andhra Pradesh and Telangana.
- State Agricultural University Partnerships:Karnataka and Tamil Nadu trial data protocols offer accelerated registration pathways for formulators conducting localized efficacy demonstrations.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Domestic microbial production requires specialized bioprocess engineers that agricultural universities currently underproduce.
- Multi-State Registration Fragmentation:Commercial deployment across Maharashtra, Karnataka, and Andhra Pradesh demands duplicative state-level efficacy trials that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biopesticides Market |
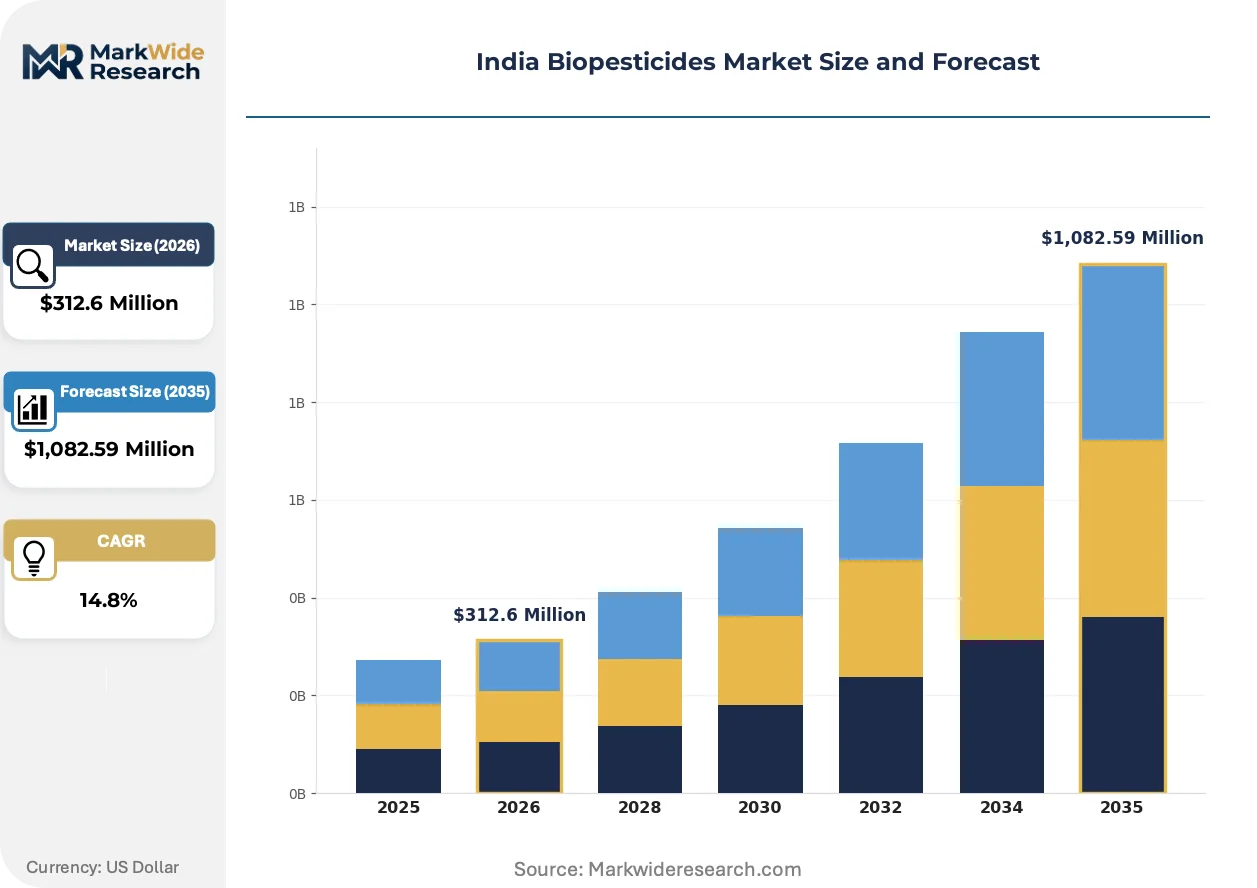
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,082.59 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Plant-Based, Bio-Chemicals, Insect Growth Regulators Application: Agronomic Crops, Horticultural Crops, Turf & Ornamentals, Others Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Distribution Channel: Online, Retail, Distributor, Direct Sales |
| Companies Covered | Coromandel International Ltd, GrowTech Agri Science Private Limited, IPL Biologicals Limited, T.Stanes and Company Limited, Gujarat State Fertilizers & Chemicals Ltd, Biotech International Limited, International Panaacea Limited, Tagros Chemicals India Limited, Fortune Biotech Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biopesticides Market Strategic Shifts
Biological input supply chains are reconfiguring around residue-compliance verification rather than purely efficacy metrics, embedding traceability infrastructure into formulation and distribution workflows.
Encapsulation technology for Bacillus thuringiensis spores is unifying thermal protection with controlled-release mechanisms, extending viable shelf life from months to years. Grape and pomegranate exporters in Maharashtra's Nashik and Solapur districts are adopting these stabilized formulations at accelerated rates despite 40-60% cost premiums over conventional microbial products. This unifying capability is compressing the addressable market for unformulated technical-grade imports while elevating domestic formulation margins.
FSSAI maximum residue limit revisions for specific crop matrices are reshaping which biopesticide chemistries gain rapid farmer acceptance versus those requiring extended efficacy demonstration periods. The 2024 tightening of mango and grape residue thresholds has triggered immediate substitution demand in export-oriented belts. Formulators with pre-positioned BIS-certified microbial portfolios capture disproportionate share in Maharashtra and Karnataka registration queues.
Dealer-network agronomy advisory is displacing standalone product transactions across Andhra Pradesh and Telangana. Coromandel International's rural dealership infrastructure now bundles biopesticide replenishment with pest monitoring services, locking in recurring purchase cycles. This model concentrates most visibly in chili and cotton belts where export certification pressure remains minimal but integrated pest management adoption accelerates through credit-linked input packages.
India Biopesticides Market Segmentation
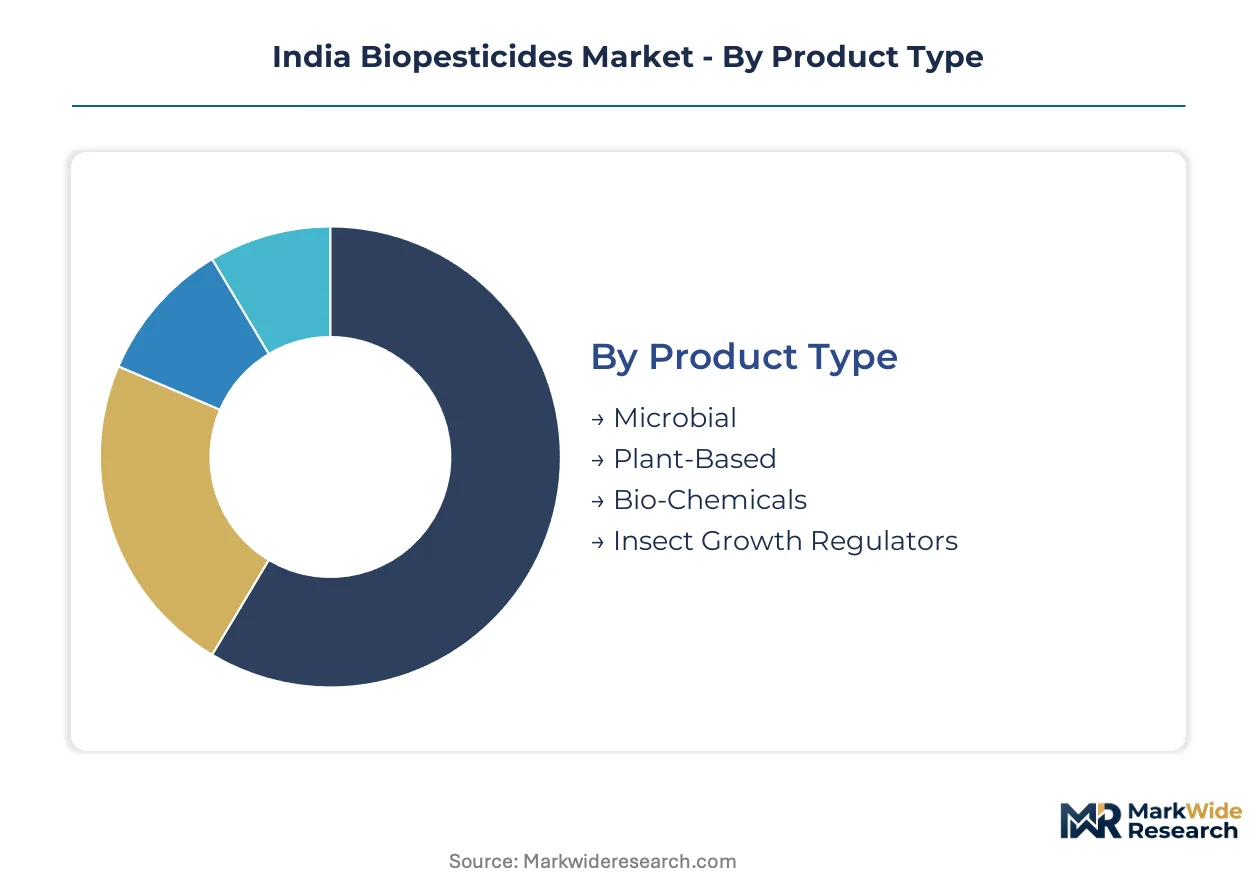
Product type determines procurement economics and registration complexity for Indian formulators, while application segmentation tracks residue-compliance pressure across export-facing versus domestic crop systems. Formulation and channel choices reflect storage infrastructure limits and dealer-network reach in unregulated rural supply chains.
Product Type:
Procurement teams prioritize active ingredient sourcing security and fermentation scale-up feasibility when selecting biopesticide categories.
- Microbial:Bacterial and fungal formulations derived from Bacillus thuringiensis, Trichoderma, and Beauveria bassiana dominate current manufacturing capacity. Maharashtra's grape and pomegranate belts drive concentrated demand as EU phytosanitary protocols mandate residue-free production windows.
- Plant-Based:Extracts from neem, karanja, and other botanical sources capture accelerating interest in organic-certified horticulture clusters. Kerala's spice-growing regions exhibit pronounced uptake as FSSAI residue limits tighten for cardamom and pepper export consignments.
- Bio-Chemicals:Naturally occurring biochemical pesticides including plant-incorporated protectants and semiochemicals.
- Insect Growth Regulators:Chitin synthesis inhibitors and juvenile hormone analogs that disrupt pest metamorphosis without acute toxicity.
Microbial leads on scale; plant-based leads on momentum.
Application:
Export certification requirements fragment demand intensity across crop categories, with horticulture commanding premium pricing and agronomic crops prioritizing cost efficiency.
- Horticultural Crops:Pomegranate, grape, and mango cultivation in Nashik and Solapur districts anchors premium bio-input adoption. European and Middle Eastern phytosanitary scrutiny forces rapid substitution away from synthetic chemicals despite 40-60% cost premiums.
- Agronomic Crops:Cotton, rice, and wheat systems across Andhra Pradesh and Telangana concentrate volume demand through subscription-based agronomy advisory bundling. Dealer networks lock in recurring purchases where export pressure remains minimal.
- Turf & Ornamentals:Golf course and landscaping applications in urban corridors.
- Others:Forestry and non-food agricultural applications with specialized registration pathways.
Horticultural crops command the steepest expansion trajectory; agronomic crops anchor baseline volume.
Formulation:
Temperature stability and shelf-life degradation risks in ambient rural storage dictate formulation selection for distribution reach.
- Liquid:Aqueous suspensions and oil-based formulations dominate commercial flows due to established mixing protocols with existing spray equipment. Encapsulation technology for Bacillus thuringiensis spores is unifying thermal protection with controlled-release mechanisms in Maharashtra export belts.
- Granular:Slow-release formulations suited for soil-dwelling pest targeting in tea and spice cultivation. Assam's orthodox tea gardens are expanding adoption as residue-free export protocols tighten.
- Powder:Technical-grade concentrates requiring on-farm reconstitution.
- Emulsifiable Concentrate:Oil-in-water formulations with enhanced adhesion properties.
Liquid formulations lead on scale; granular leads on momentum in northeastern penetration.
Distribution Channel:
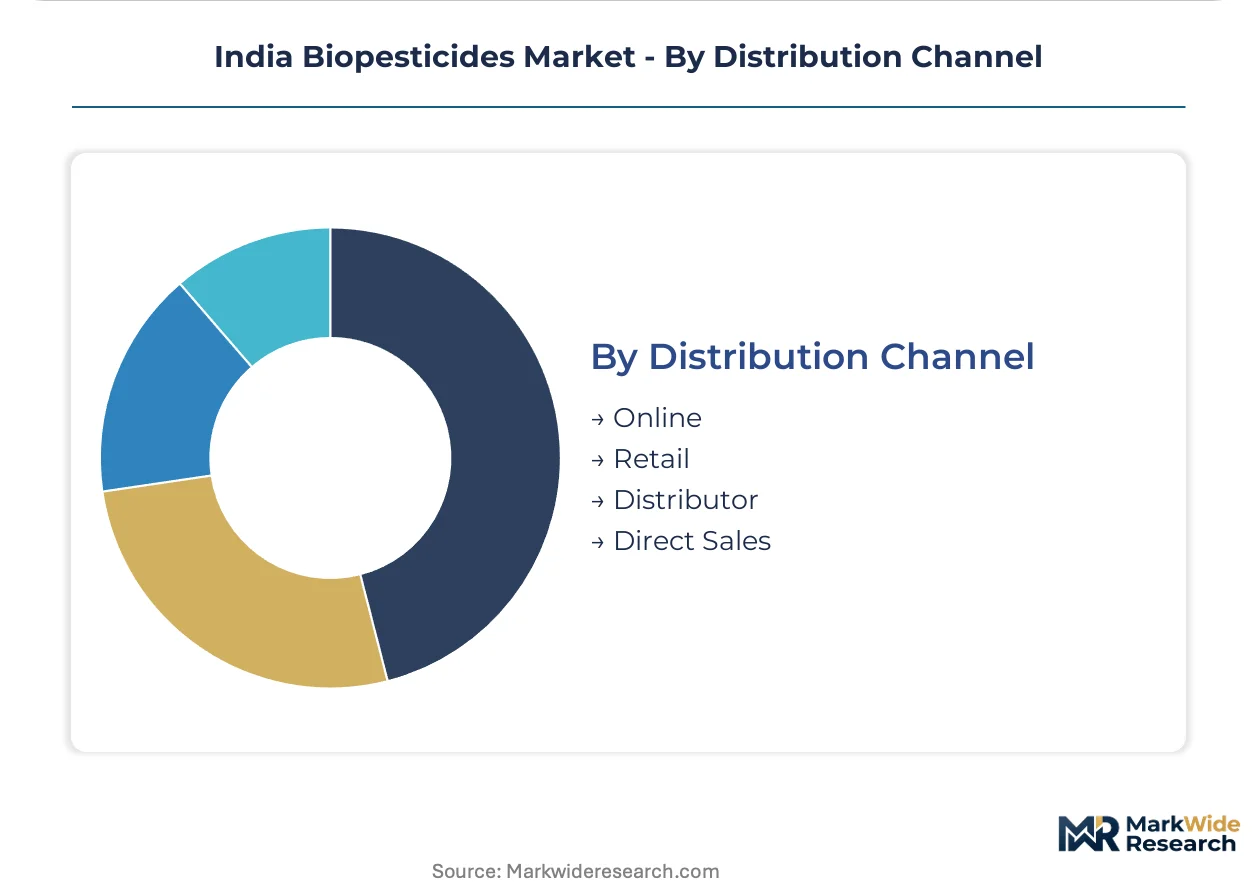
Credit access and technical advisory integration determine channel preference across farmer segments with varying risk tolerance.
- Distributor:Rural dealership networks in Andhra Pradesh and Telangana bundle biopesticide replenishment with pest monitoring services, locking in recurring purchase cycles through credit-linked input packages. Coromandel International leverages this infrastructure across chili and cotton belts.
- Retail:Kirana and agri-input shops serve smallholder procurement with immediate availability but limited technical support.
- Direct Sales:Large estate and export-oriented farm clusters in Maharashtra and Karnataka.
- Online:Emerging platform-based procurement with traceability verification for organic certification compliance.
Distributor networks lead on scale; online channels gain share fastest in certification-verified segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's biopesticide penetration outpaces neighboring agricultural economies where export certification pressure remains less acute. State-level policy divergence creates uneven adoption corridors across the subcontinent.
Maharashtra
European phytosanitary protocols for grapes and pomegranates mandate residue-free production windows. FSSAI maximum residue limit enforcement compresses synthetic chemical use in Nashik and Solapur districts. Exporters in these clusters adopt Bacillus-based formulations despite 40-60% cost premiums over conventional alternatives.
Karnataka
Mango export consignments to Middle Eastern markets face tightening phytosanitary scrutiny. State agricultural university trial data protocols determine commercial registration timelines for domestic formulators. Bengaluru-Mysuru corridor suppliers capture disproportionate share in registration queues through localized efficacy demonstrations.
Andhra Pradesh
Chili and cotton cultivation anchors volume demand through subscription-based agronomy advisory bundling. Coromandel International leverages rural dealership networks to lock in recurring bio-input purchases. Dealer infrastructure bundles pest monitoring services with credit-linked input packages across Guntur and Warangal belts.
Assam
Orthodox tea exports to European markets require residue-free production protocols. CEA guidelines on biological agriculture input standards create compliance pathways for northeastern formulators. Tea gardens in Dibrugarh and Jorhat districts expand pheromone-based integrated pest management adoption.
Kerala
Cardamom and pepper export consignments face FSSAI residue limit tightening. Spice-growing regions in Idukki and Wayanad districts exhibit pronounced uptake of plant-based extracts. Organic-certified horticulture clusters drive accelerating interest in neem and karanja formulations.
India Biopesticides Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fermentation-capable domestic formulators commanding premium positioning against import-dependent technical-grade distributors. The vendor base clusters around three strategic archetypes: integrated agrochemical conglomerates with dealership network leverage, dedicated microbial fermentation specialists with captive Bacillus thuringiensis capacity, and pheromone-based integrated pest management kit developers. Capacity expansion and subscription-based agronomy advisory bundling represent the dominant competitive moves reshaping procurement relationships.
Among domestic fermentation specialists, IPL Biologicals Limited anchors the tier of suppliers reducing import dependence through in-house active ingredient production. Coromandel International Ltd exemplifies the integrated conglomerate archetype, leveraging rural dealership infrastructure to bundle biopesticide replenishment with recurring agronomy services. GrowTech Agri Science Private Limited occupies a position within the specialized pheromone-based integrated pest management segment, commanding premium pricing in export-oriented horticulture clusters.
| Leading Market Players |
|---|
| Coromandel International Ltd |
| GrowTech Agri Science Private Limited |
| IPL Biologicals Limited |
| T.Stanes and Company Limited |
| Gujarat State Fertilizers & Chemicals Ltd |
| Biotech International Limited |
| International Panaacea Limited |
| Tagros Chemicals India Limited |
| Fortune Biotech Limited |
| Others |
Value Chain & Pricing Dynamics
Export-oriented horticulture clusters in Maharashtra and Karnataka anchor premium-tier procurement, locking in subscription-based pricing models for residue-compliant bio-inputs while ambient storage constraints force cost absorption downstream.
Pricing Analysis
Capacity additions in Andhra Pradesh and Telangana are reshaping price floors for microbial formulations as domestic fermentation scale reduces import dependence for Bacillus thuringiensis active ingredients. Pricing stratifies across premium encapsulated formulations for grape export belts, standard aqueous suspensions for cotton and chili systems, and economy-grade unformulated technical concentrates. Cost compression in economy tiers intensifies because unregulated rural supply chains degrade bacterial shelf life before application. Smallholder procurement through kirana shops exhibits acute price sensitivity, while Nashik and Solapur estate clusters absorb 40-60% premiums for EU certification compliance.
Supply Chain Analysis
BIS certification requirements for efficacy claims and CEA biological agriculture guidelines filter supplier participation, creating qualification gates that concentrate viable supply among domestic fermentation specialists and integrated agrochemical conglomerates. Manufacturing gravity centers on Maharashtra, Karnataka, and Gujarat where state agricultural university trial protocols accelerate registration timelines. Raw material dependencies span fermentation feedstocks, technical-grade spore concentrates, and encapsulation polymers. Single-source vulnerability runs through imported active ingredient strains before PLI scheme capital redirects toward captive production. Distribution runs through rural dealership networks bundling credit-linked replenishment with pest monitoring advisory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on encapsulation technology cost curves flattening and premium-tier adoption accelerating among export certification-driven estate clusters.
For Market Incumbents: Hedge fermentation capacity obsolescence by backward integration into spore strain development, reducing license dependence for Bacillus thuringiensis variants. Lock in dealer network exclusivity across Andhra Pradesh and Telangana through agronomy-as-a-service bundling before subscription models commoditize. Prioritize BIS certification pre-positioning for FSSAI residue limit revisions on mango and grape matrices.
For New Entrants and Emerging Players: Pheromone-based integrated pest management kits offer technology-first wedge into underserved Assam tea and Kerala spice belts where residue-free export protocols tighten but microbial formulation infrastructure remains sparse. Target orthodox tea gardens in Dibrugarh and Jorhat districts through direct estate sales bypassing fragmented distributor layers. Anchor go-to-market on CEA guideline compliance certification as competitive differentiator.
For Investors and Strategic Acquirers: Integrated agrochemical conglomerates with rural dealership infrastructure are the most active acquirer in this space, seeking fermentation capability to complete bio-input portfolios. Long-term viability favors domestic microbial specialists with captive active ingredient production and pre-qualified BIS efficacy dossiers. Monitor FSSAI maximum residue limit revision timing for specific crop matrices as inflection indicator for substitution demand velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Scale-Up | Extends Bacillus thuringiensis shelf life from months to years, commanding premium pricing in Maharashtra export belts. |
| Fermentation Facility Expansion | PLI scheme eligibility redirects capital toward domestic active ingredient production, cutting import dependence. |
| State Agricultural University Partnerships | Localized efficacy demonstrations in Karnataka and Tamil Nadu accelerate commercial registration queue positioning. |
| Subscription Advisory Bundling | Coromandel International's dealer networks lock recurring bio-input purchases through credit-linked pest monitoring services. |
| Pheromone Kit Specialization | GrowTech Agri Science commands premium positioning in horticulture clusters facing EU phytosanitary scrutiny. |
Study Parameters
Direct dialogue with fermentation plant managers, FSSAI regulatory affairs leads, Maharashtra grape export consortium procurement heads, and Andhra Pradesh rural dealership operators grounded qualitative insights in operational reality. Secondary validation drew from BIS efficacy claim filings, CEA biological agriculture guideline drafts, FSSAI maximum residue limit notifications, and PLI scheme beneficiary disclosures. Bottom-up demand estimation across crop-specific application rates triangulated with top-down addressable market sizing from state-level agricultural production statistics.
Bottom-up volume modeling segmented by microbial versus plant-based product chemistry, horticultural versus agronomic crop application, liquid versus granular formulation, and distributor versus direct sales channel. CAGRs derived from export certification pressure intensity indices, FSSAI enforcement trajectory assumptions, and fermentation capacity expansion pipelines across the projection horizon. Industry-specific forecast inputs incorporated EU phytosanitary protocol revision probabilities and state agricultural university trial protocol throughput rates.
The model holds under sustained FSSAI residue limit enforcement and PLI scheme capital deployment continuity; deviation in EU phytosanitary protocol relaxation or fermentation talent supply constraints would shift trajectory. Forecasts reflect documented assumptions on export market access stability and BIS certification processing timelines. A model refresh is warranted upon material change in FSSAI maximum residue limit revision scope or CEA guideline implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
South America Biofertilizers Market