
 Africa Biofertilizer Market | 2026-2036
Africa Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Biofertilizer Market Outlook
Market Context with Strategic Players
East African microbial inoculant production is broadening as local fermentation capacity expands. Novozymes A/S leverages its enzyme biotechnology platform to dominate nitrogen-fixing strain development across the continent. Lallemand Inc. anchors its position through specialized yeast and bacteria formulations tailored to arid-zone crops. UPL Limited competes via extensive distribution networks that reach remote farming cooperatives in Ethiopia and Tanzania.
Technical Definition and Structural Segments
Africa biofertilizer comprises living microbial preparations—primarily nitrogen-fixing bacteria, phosphate-solubilizing fungi, and plant-growth-promoting rhizobacteria—cultured in carrier substrates such as peat, vermiculite, or liquid broth for agricultural soil inoculation. These formulations restore soil microbiome function, reduce synthetic nitrogen dependency, and enhance nutrient availability in depleted tropical soils. Liquid formulations lead current adoption due to compatibility with existing spray equipment, while granular products represent the fastest-growing category as mechanized farming spreads in South Africa and Zambia. Soil application generates the dominant revenue pool, though seed treatment commands premium pricing where precision application infrastructure exists.
Regulatory Frame and Forward-Looking Close
Kenya's Agriculture and Food Authority, South Africa's Department of Agriculture, and Nigeria's National Agency for Food and Drug Administration and Control each enforce distinct registration pathways for microbial fertilizer imports and domestic manufacture. These frameworks determine strain approval timelines, labeling requirements, and field trial obligations that directly shape market entry costs. Stakeholders must monitor harmonization efforts under the African Union's fertilizer quality protocol while building local strain libraries to satisfy emerging origin requirements.
Market Dynamics
Soil microbiome restoration is displacing synthetic nitrogen dependency as the dominant value proposition across African agricultural input markets, with Kenya's fertilizer subsidy reforms and Nigeria's microbial inoculant trials accelerating this structural pivot.
Growth Catalysts
- Kenya's Agriculture and Food Authority subsidy reforms:Reduced synthetic fertilizer allocations are redirecting public procurement toward microbial alternatives, expanding smallholder access to nitrogen-fixing inoculants.
- Phosphate-solubilizing fungi:These organisms unlock bound phosphorus in weathered tropical soils, delivering nutrient availability gains that synthetic fertilizers cannot replicate in depleted East African croplands.
- South Africa's organic certification standards:Accelerated product registration timelines for biofertilizer manufacturers are compressing market entry barriers and validating quality claims for export-oriented horticulture.
Market Restraints
- Carrier substrate cost volatility:Peat and vermiculite prices fluctuate with global mining output, squeezing formulation margins for domestic producers lacking backward integration into substrate sourcing.
- Strain preservation limitations:Shelf stability of liquid formulations degrades rapidly above 30°C without cold chain infrastructure, restricting distribution reach in landlocked Sahelian territories.
- Substitution by subsidized synthetics:Urea and DAP remain price-competitive where government programs maintain artificial price floors, delaying biofertilizer penetration in Nigeria's northern grain belt.
Strategic Opportunities
- Ethiopian highland wheat cooperatives:These organized buyer groups present concentrated demand for rhizobium inoculants as the government expands irrigated cereal production in the Awash Valley.
- Seed treatment application infrastructure:Precision coating equipment at South African commercial farms enables premium pricing models currently unavailable to broadcast soil applications.
- African Union fertilizer quality protocol harmonization:Mutual recognition of strain approvals across member states would eliminate redundant field trials and accelerate cross-border product registration.
Industry Challenges
- Microbial fermentation technician scarcity:Qualified personnel for aseptic culture maintenance and quality control testing remain concentrated in South African and Kenyan research institutes, constraining production scale-up elsewhere.
- Multi-jurisdiction registration timelines:Separate approval processes at Nigeria's NAFDAC, Kenya's AFA, and South Africa's Department of Agriculture extend commercialization cycles beyond 24 months for new strain introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Biofertilizer Market |
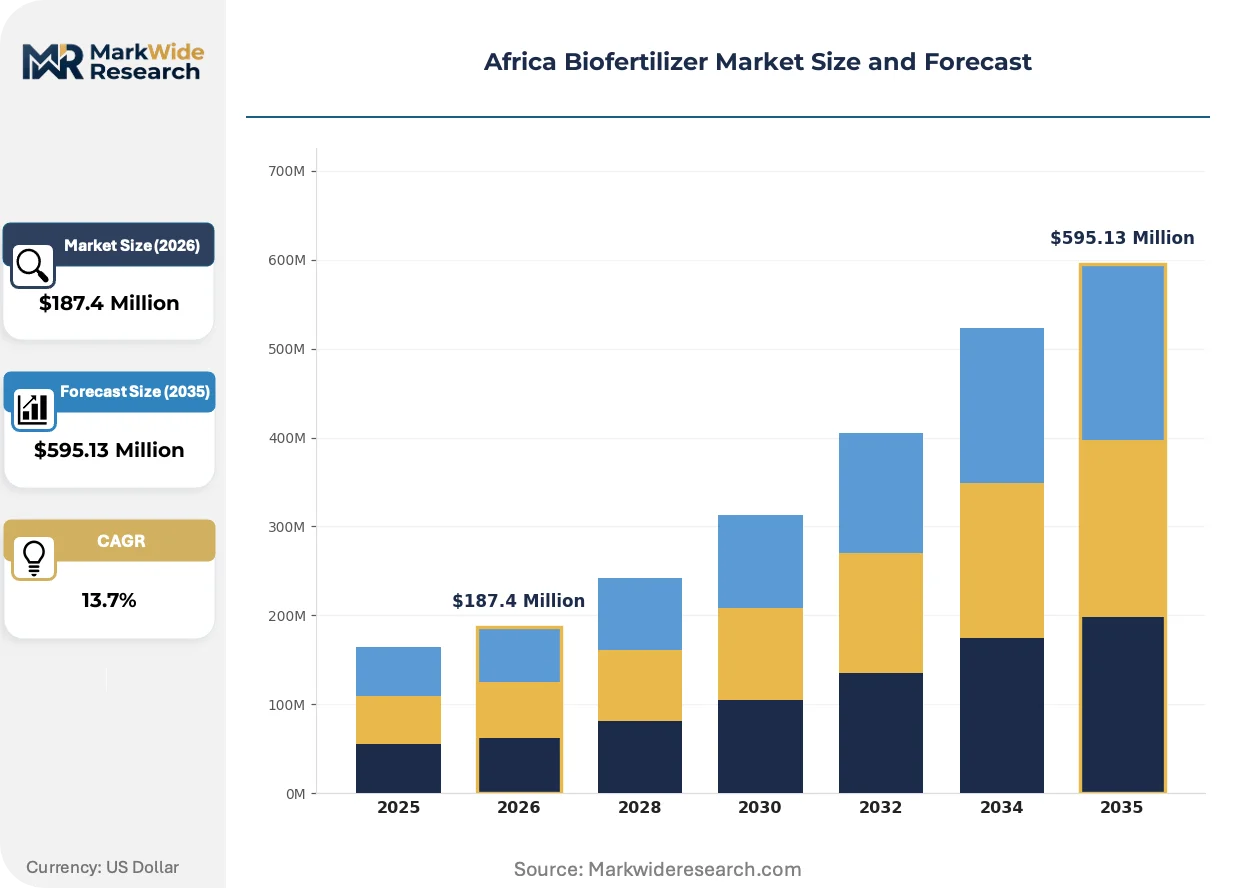
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Dry, Granular, Powder End Use Industry: Agriculture, Horticulture, Forestry, Landscaping Application Method: Soil Application, Seed Treatment, Foliar Spray, Drip Irrigation Packaging Type: Bags, Bottles, Bulk, Sachets |
| Companies Covered | Novozymes A/S, Rizobacter Argentina SA, Lallemand Inc., UPL Limited, Symborg, National Fertilizers Limited, AgriLife, Mapleton Agri Biotech Pty Ltd, IPL Biologicals Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Biofertilizer Market Strategic Shifts
Biotechnology platforms are converging with traditional fermentation methods to produce region-specific microbial consortia, while regulatory frameworks and procurement patterns simultaneously evolve to accommodate these advanced formulations.
Multi-strain consortia engineering is integrating nitrogen-fixing bacteria with phosphate-solubilizing fungi and plant-growth-promoting rhizobacteria into single carrier formulations. South African commercial maize operations and Zambian mechanized wheat farms are adopting these advanced products at twice the rate of single-strain alternatives. This integration is compressing the performance gap between biofertilizers and synthetic nutrient packages in high-input farming systems.
Kenya's Agriculture and Food Authority revised its microbial fertilizer registration guidelines to require local field efficacy data for all imported strains. This industrial consequence forces multinational suppliers to establish domestic trial partnerships or license local production facilities. Ethiopian and Tanzanian regulators are observing Kenya's implementation before drafting equivalent frameworks, creating a staggered compliance timeline across East Africa.
Cooperative procurement aggregation is consolidating smallholder demand into volume contracts with fermentation facilities. Tanzania's SAGCOT corridor farming clusters now negotiate directly with microbial inoculant manufacturers, bypassing traditional agrodealer networks. This channel shift is most visible in Kenya's Rift Valley and Ethiopia's Oromia region where cereal cooperative membership exceeds 50,000 farmers per bloc.
Africa Biofertilizer Market Segmentation
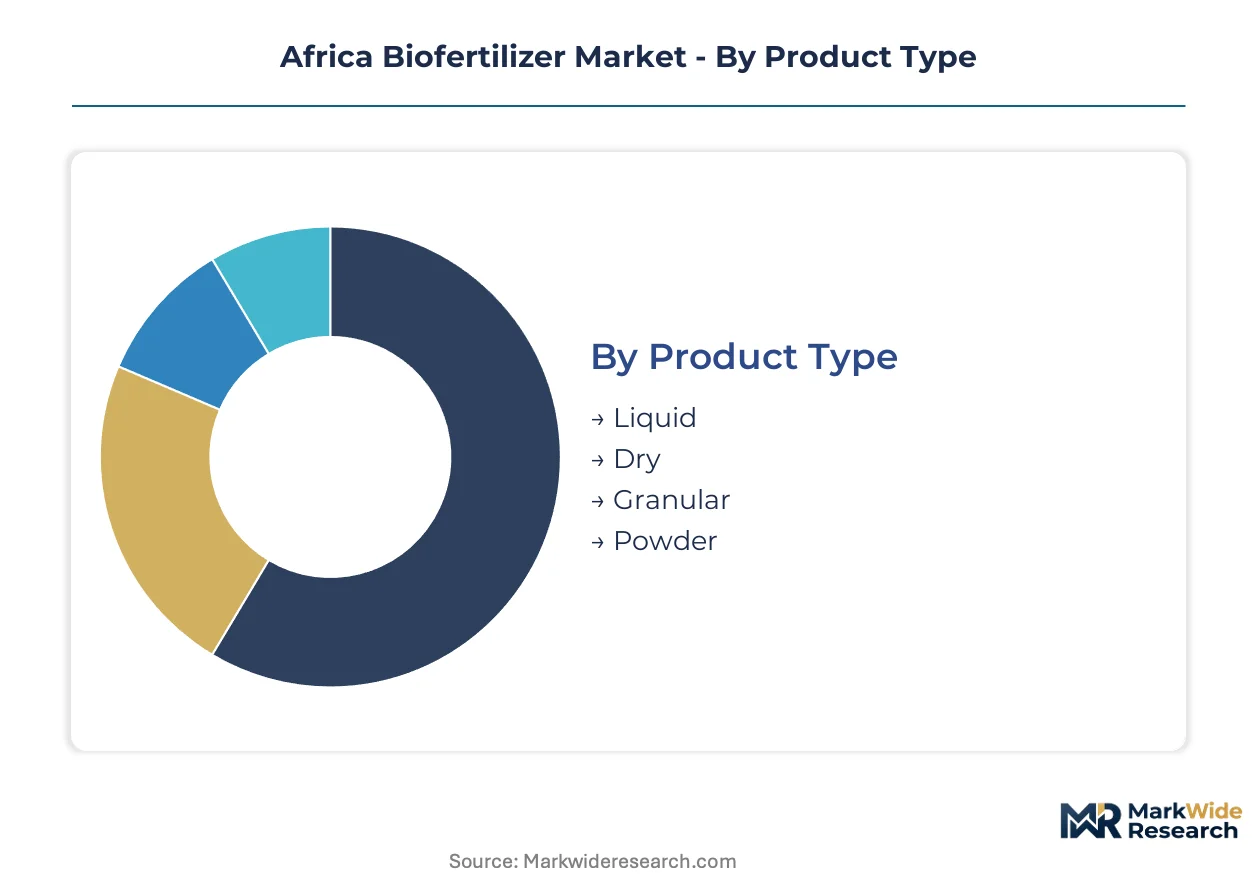
Buyer procurement patterns in African biofertilizer markets diverge sharply between smallholder cooperatives and commercial farming operations, with packaging format and application infrastructure driving fundamentally different segment preferences across the value chain.
Product Type:
Cost tier and mechanization level determine formulation selection, with liquid products commanding premium positioning in irrigated systems while dry carriers dominate rainfed smallholder channels.
- Liquid:Broth-based suspensions of nitrogen-fixing bacteria and phosphate-solubilizing fungi packaged for spray equipment compatibility. Demand concentrates in South African commercial maize operations and Zambian wheat estates where mechanized application infrastructure eliminates handling constraints.
- Granular:Clay- or peat-bound microbial pellets engineered for mechanical spreader distribution and extended soil residence time. Adoption is climbing fastest in Ethiopia's Awash Valley irrigated wheat schemes and Kenya's Rift Valley cereal cooperatives as tractor ownership spreads.
- Dry:Carrier substrates such as vermiculite or lignite hosting desiccated microbial cultures for manual broadcasting. Nigeria's northern grain belt smallholders favor this format for millet and sorghum inoculation where equipment access remains limited.
- Powder:Fine-particulate formulations requiring immediate soil incorporation to prevent UV degradation and desiccation. Tanzanian horticulture clusters near Arusha utilize powder rhizobium for bean seed coating prior to planting.
Liquid leads on scale; granular leads on momentum.
End Use Industry:
Application maturity and certification requirements segment demand, with export-oriented horticulture commanding premium microbial specifications while subsistence cereal production prioritizes cost minimization.
- Agriculture:Broad-acre cereal and legume cultivation across East African smallholder systems and Southern African commercial farms. Kenya's fertilizer subsidy reforms are redirecting public procurement toward microbial nitrogen fixation for maize and beans.
- Horticulture:High-value vegetable and fruit production subject to organic certification standards in South Africa's Western Cape and Kenya's Naivasha flower clusters. Phosphate-solubilizing consortia replace synthetic inputs for EU export compliance.
- Forestry:Eucalyptus and pine plantation establishment in South Africa's KwaZulu-Natal and Mozambique's Niassa Province. Mycorrhizal inoculants accelerate seedling establishment on acidic, phosphorus-deficient tropical soils.
- Landscaping:Urban green space maintenance and golf course turf management in Johannesburg, Cape Town, and Nairobi. This segment demands specialized formulations for salinity tolerance and drought stress mitigation.
Agriculture dominates volume capture; horticulture dominates margin extraction.
Application Method:
Precision infrastructure availability and labor cost structures determine method selection, with seed treatment requiring capital equipment that excludes most smallholder operations.
- Soil Application:Broadcast or banded incorporation of microbial formulations into root zones prior to or during planting. This method generates the dominant revenue pool across African markets due to minimal equipment requirements and compatibility with manual labor.
- Seed Treatment:Precision coating of seeds with rhizobium or phosphate-solubilizing inoculants using film-coating or pelleting equipment. South African commercial farms and Ethiopian cooperative processing centers command premium pricing through this high-efficiency approach.
- Foliar Spray:Aqueous microbial suspensions applied to plant leaf surfaces for phyllosphere colonization. Kenya's tea cooperatives in Kericho and Tanzania's coffee associations utilize foliar formulations for micronutrient mobilization.
- Drip Irrigation:Injection of liquid inoculants through pressurized irrigation systems. Moroccan citrus estates and South African wine grape operations in Stellenbosch exploit this method for targeted rhizosphere delivery.
Soil application anchors current deployment; seed treatment is gaining share fastest.
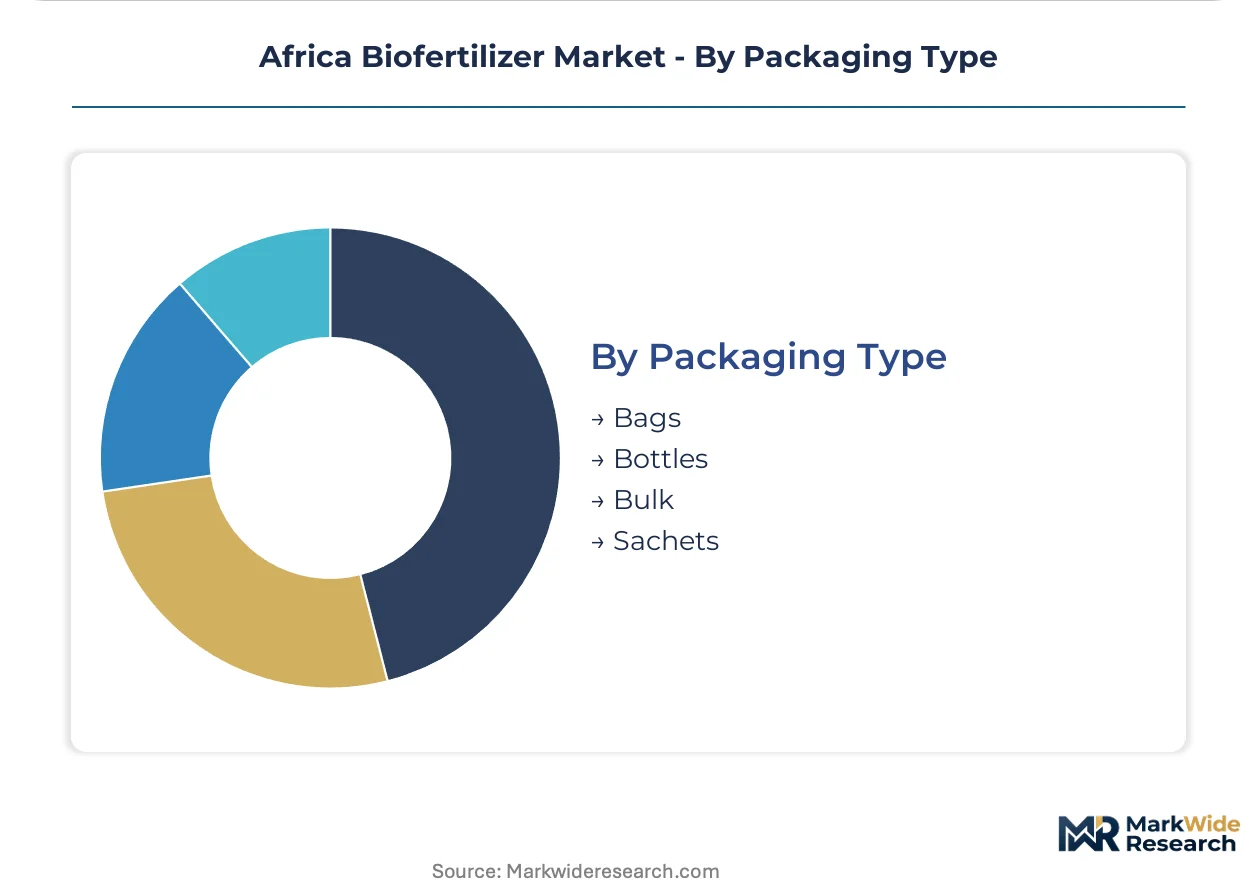
Packaging Type:
Volume scale and distribution channel density determine packaging economics, with bulk formats rewarding cooperative aggregation while sachets enable last-mile retail penetration.
- Bulk:Tanker or tote deliveries of liquid inoculants to commercial farming operations and cooperative processing facilities. Tanzania's SAGCOT corridor farming clusters negotiate direct bulk procurement, bypassing traditional agrodealer markups.
- Bags:Woven polypropylene containers for granular and dry formulations ranging from 10kg to 50kg. Kenyan cereal cooperatives in the Rift Valley utilize bagged rhizobium for member distribution at planting season.
- Bottles:HDPE containers for liquid formulations in 1-liter to 20-liter sizes. Nigerian horticulture clusters near Kano prefer bottle packaging for tomato and pepper nursery operations.
- Sachets:Laminated foil single-dose packets for powder and liquid concentrates requiring dilution. Ethiopian highland wheat cooperatives distribute sachet rhizobium to members for on-farm seed coating.
Bulk leads on volume throughput; sachets lead on access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting biofertilizer production toward jurisdictions with streamlined strain approval pathways, as Kenya's Agriculture and Food Authority compresses registration timelines relative to Nigeria's multi-agency review processes.
Kenya
Smallholder cereal cooperatives in the Rift Valley drive rhizobium demand for maize and bean inoculation. Kenya's Agriculture and Food Authority subsidy reforms redirect public procurement from synthetic nitrogen toward microbial alternatives. Nairobi-based fermentation facilities now supply SAGCOT corridor farming clusters in neighboring Tanzania.
South Africa
Commercial maize operations and wine grape estates in the Western Cape adopt multi-strain consortia at twice the regional rate. The Department of Agriculture enforces organic certification standards that accelerate product registration for export-oriented horticulture. Stellenbosch processing centers command premium pricing through precision seed coating infrastructure.
Nigeria
Soil nitrogen depletion across the northern grain belt sustains microbial inoculant trials for millet and sorghum. The National Agency for Food and Drug Administration and Control maintains separate approval processes that extend commercialization cycles beyond twenty-four months. Kano horticulture clusters prefer bottle-packaged formulations for tomato nursery operations.
Ethiopia
Highland wheat cooperatives in Oromia present concentrated demand as the government expands irrigated cereal production in the Awash Valley. The national agricultural regulator observes Kenya's field efficacy data requirements before drafting equivalent frameworks. Arusha-adjacent farming blocs negotiate direct bulk procurement, bypassing traditional agrodealer networks.
Zambia
Mechanized wheat farms in the Central Province adopt granular formulations as tractor ownership spreads across commercial operations. The national fertilizer control board lacks harmonized strain approval protocols with neighboring states. Lusaka-based distribution hubs face shelf stability constraints for liquid formulations above thirty degrees Celsius without cold chain infrastructure.
Africa Biofertilizer Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized consortia development and cooperative procurement channels. The market exhibits tiered concentration with multinational biotechnology platforms, regional fermentation specialists, and domestic substrate processors each occupying distinct competitive positions. Strategic archetypes include enzyme biotechnology developers, yeast and bacteria formulation specialists, and extensive distribution network operators. Capacity expansion and local strain library development constitute the dominant competitive moves as regulators impose origin requirements.
Among the named entities in this sector, Novozymes A/S and Lallemand Inc. occupy positions within the premium biotechnology tier, while UPL Limited exemplifies the distribution-intensive archetype. Novozymes A/S represents the enzyme biotechnology platform model dominating nitrogen-fixing strain development. Lallemand Inc. anchors the specialized formulation segment through yeast and bacteria expertise. UPL Limited sits within the network-dependent competitive set, reaching remote farming cooperatives across Ethiopia and Tanzania. These three entities collectively illustrate the strategic positioning spectrum from R&D-intensive platforms to logistics-heavy market access models.
| Leading Market Players |
|---|
| Novozymes A/S |
| Rizobacter Argentina SA |
| Lallemand Inc. |
| UPL Limited |
| Symborg |
| National Fertilizers Limited |
| AgriLife |
| Mapleton Agri Biotech Pty Ltd |
| IPL Biologicals Limited |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between Kenya's AFA-registered microbial consortia and unregistered commodity inoculants shapes divergent pricing power and supply chain configurations across East Africa. Premium formulations command distributor margins of 35-45% through formal agrodealer networks, while commodity dry carriers circulate through informal trader channels with minimal quality verification.
Pricing Analysis
Distributor margin layers absorb 25-40% of ex-factory value before reaching smallholder cooperatives, with formal agrodealer networks in Kenya and Tanzania extracting higher markups than direct bulk procurement by Ethiopian cooperative federations. Three-tier pricing structure across premium consortia, standard single-strain, and economy dry formulations reflects Kenya's AFA registration status and South Africa's organic certification tier. Pricing pressure stems from subsidized urea flooding Nigeria's northern grain belt, compressing microbial inoculant willingness-to-pay among millet and sorghum growers. Smallholder cereal cooperatives exhibit highest price sensitivity, while South African export-oriented horticulture operations absorb premium pricing for NAFDAC-equivalent strain documentation.
Supply Chain Analysis
Dual-sourcing requirements from Kenyan cooperative procurement officers now mandate qualified supply from both Nairobi-based fermentation facilities and South African strain libraries to mitigate batch failure risk. Geographic supply concentration centers on Kenya, South Africa, and India, with Novozymes A/S and Lallemand Inc. strain libraries feeding regional formulation plants. Raw material dependencies include peat and vermiculite carrier substrates, nitrogen-fixing rhizobium master cultures, and phosphate-solubilizing fungal spores. Single-source vulnerability persists for cold-chain liquid formulations above 30°C in landlocked Sahelian territories. Distribution runs through cooperative aggregation hubs bypassing traditional agrodealer networks in Tanzania's SAGCOT corridor and Ethiopia's Awash Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
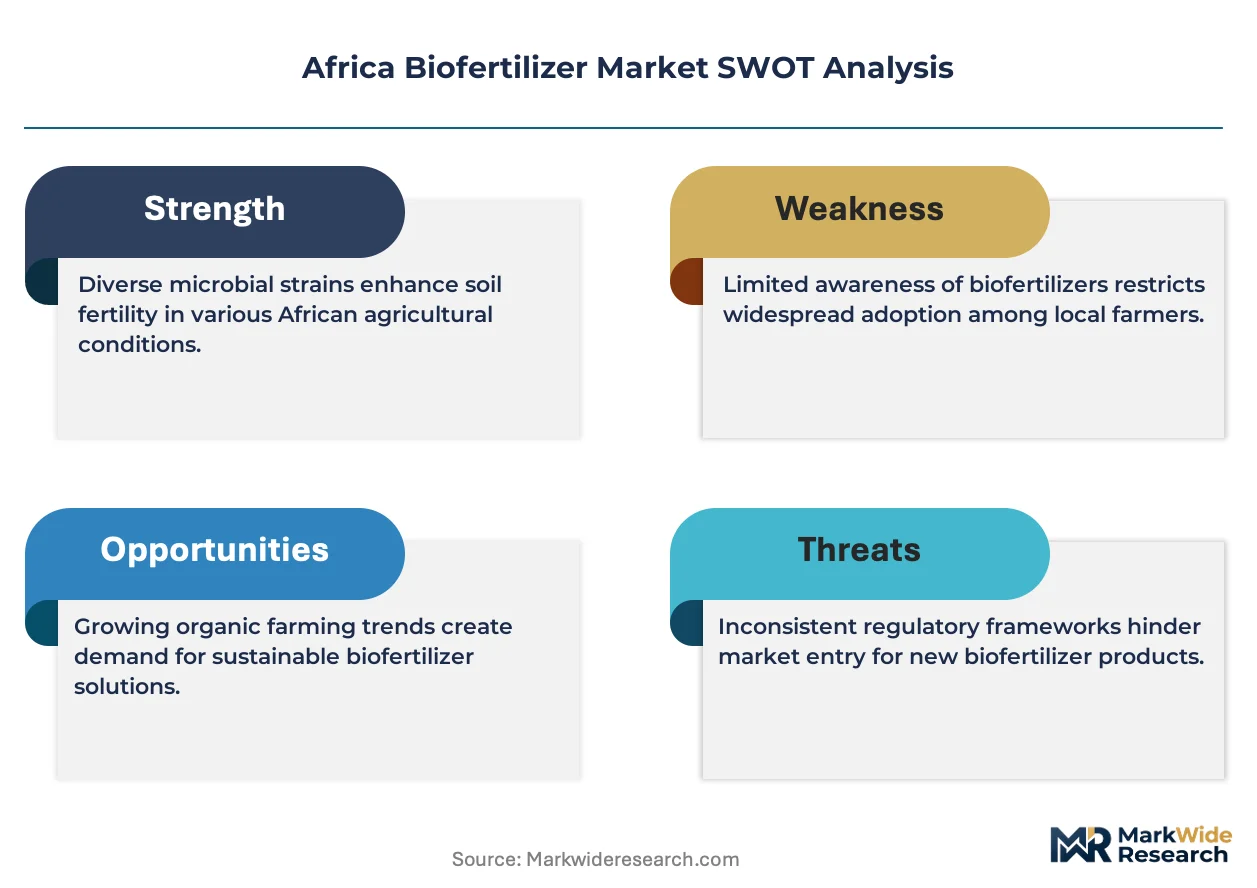
This market functions as a regulatory compounder where Kenya's Agriculture and Food Authority subsidy reforms and Nigeria's NAFDAC registration timelines simultaneously create demand acceleration and entry barriers. The interplay between public procurement redirection and multi-jurisdiction approval requirements rewards early regulatory positioning.
For Market Incumbents: Hedge against subsidized synthetic nitrogen erosion by securing backward integration into Nairobi and Johannesburg fermentation capacity before Kenya's local field efficacy requirements expand. Prioritize AFA registration maintenance and South African organic certification tier elevation to defend margin position against commodity inoculant traders. Strain library localization in Ethiopia and Tanzania addresses emerging origin requirements as regulators observe Kenya's implementation. For New Entrants and Emerging Players: Launch via cooperative direct-procurement channels in Ethiopia's Oromia highland wheat blocs and Zambia's mechanized Central Province farms, bypassing agrodealer margin extraction. White-space targets include granular formulation supply to tractor-spreading operations and seed-treatment coating services for South African commercial maize estates. Precision application infrastructure partnerships unlock premium pricing unavailable to broadcast soil applications. For Investors and Strategic Acquirers: Consolidation pressure builds where microbial fermentation technician scarcity concentrates production capability in South African and Kenyan research institutes. Long-term viability hinges on regulatory arbitrage capture as African Union fertilizer quality protocol harmonization eliminates redundant field trials. Acquisition target archetype: regional fermentation specialists with existing AFA or NAFDAC strain approvals and cooperative channel relationships. Watch Kenya's Agriculture and Food Authority implementation timeline as the inflection signal for staggered East African compliance waves.| Strategic Initiative | Industry Significance |
|---|---|
| Local Strain Library Development | Kenya's AFA field efficacy requirements force domestic trial partnerships or licensed production facilities. |
| Cooperative Procurement Channel Capture | Tanzania's SAGCOT corridor farming clusters now negotiate direct bulk contracts bypassing agrodealer networks. |
| Multi-Strain Consortia Engineering | South African commercial maize operations adopt advanced formulations at twice the rate of single-strain alternatives. |
| Cold Chain Infrastructure Investment | Shelf stability above 30°C without refrigeration restricts liquid formulation distribution in Sahelian territories. |
| Regulatory Harmonization Positioning | African Union fertilizer quality protocol mutual recognition would accelerate cross-border product registration timelines. |
Study Parameters
Coverage spans East Africa, Southern Africa, and West Africa, with primary inputs from each regional cluster combining fermentation facility managers, cooperative procurement officers, and regulatory affairs specialists at Kenya's Agriculture and Food Authority, South Africa's Department of Agriculture, and Nigeria's NAFDAC. Secondary validation draws from African Union fertilizer quality protocol documentation, national strain registration databases, and cooperative membership records. Bottom-up demand modeling from smallholder cooperative consumption patterns triangulates against top-down synthetic nitrogen substitution targets in Kenya's subsidy reform frameworks.
Rate-of-change decomposition separates volume expansion from price realization across the projection horizon, with segmentation dimensions spanning product type, end-use industry, application method, and packaging format. Modeled variables include cooperative aggregation penetration, tractor mechanization rates, and regulatory approval timeline compression. CAGRs derive from strain adoption curves in comparable subsidy-transition markets and microbial inoculant efficacy trial data from Nairobi and Stellenbosch research stations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Nigeria's NAFDAC registration backlog extension or Kenya's AFA requirements replication across Ethiopia and Tanzania. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
China Biofertilizer Market