
 South America Biological Organic Fertilizers Market | 2026-2036
South America Biological Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Biological Organic Fertilizers Market Analytics
Specialty horticulture demand is hardening across the Andean ridge as export-oriented avocado and berry operations seek residue-free certification. Rizobacter Argentina S.A dominates microbial inoculant development through its Buenos Aires R&D campus. Symborg leverages its yeast-derivative technology platform to anchor premium positioning in Chilean table grape vineyards. Lallemand Inc sustains manufacturing scale through its yeast fermentation infrastructure adapted for agricultural biologicals.
South America biological organic fertilizers comprise living or dormant microorganisms, plant-derived compounds, and animal-processed residues formulated to enhance soil nutrient availability through nitrogen fixation, phosphate solubilization, or phytohormone production, typically requiring colony-forming unit counts above 10^8 per gram for commercial efficacy. Liquid fertilizers lead volume due to compatibility with existing spray equipment across Brazilian mega-farms, while microbial inoculants from specialized fermentation plants capture the fastest expansion as soybean growers seek Bradyrhizobium alternatives to imported urea. Dry formulations retain margin strength in Argentina's interior provinces where storage stability outweighs application convenience.
Brazil's Ministry of Agriculture (MAPA) enforces registration under Normative Instruction 46/2011 for all biological inputs, while ANVISA monitors heavy metal thresholds in animal-waste derivatives; Argentina's SENASA administers equivalent safety protocols through Resolution 33/2023. These frameworks elevate compliance costs for smaller formulators but simultaneously protect incumbent producers with established regulatory dossiers. Stakeholders must weigh MAPA's accelerating bioinput simplification agenda against the persistent fragmentation of state-level organic standards when allocating commercialization resources.
Market Dynamics
Biological nitrogen fixation technology is displacing synthetic urea dependency across Brazil's soybean belt, restructuring input procurement patterns and elevating microbial inoculants from niche additives to primary fertility tools.
Growth Catalysts
- MAPA Normative Instruction 46/2011:Brazil's streamlined bioinput registration framework reduces compliance timelines for microbial formulations, accelerating commercialization of new Bradyrhizobium strains.
- Export-oriented avocado operations:Andean ridge specialty horticulture seeks residue-free certification for EU and North American markets, driving demand for yeast-derivative and plant-extract formulations.
- Phosphate solubilizing bacteria:Argentina's interior grain belts deploy Bacillus and Pseudomonas consortia to unlock fixed phosphorus in alkaline soils, reducing diammonium phosphate import reliance.
Market Restraints
- Specialized fermentation infrastructure:Microbial inoculant production requires capital-intensive bioreactor capacity concentrated in São Paulo and Buenos Aires provinces, limiting regional supply diversification.
- SENASA Resolution 33/2023:Argentina's tightened organic certification protocols impose extended product registration timelines and elevated documentation burdens on smaller formulators.
- Synthetic urea price volatility:Imported nitrogen fertilizer cost fluctuations create intermittent price competition that compresses biological premium capture during commodity downturns.
Strategic Opportunities
- Chilean table grape vineyards:Premium fruit export channels reward biological input adoption with price premiums and preferential market access, creating white space for yeast-derivative platform expansion.
- MAPA bioinput simplification agenda:Brazil's regulatory streamlining initiative proposes reduced colony-forming unit verification requirements for established microbial strains, lowering market entry barriers.
- Liquid formulation compatibility:Existing spray equipment infrastructure across Brazilian mega-farms enables biological integration without capital retrofit, accelerating microbial adoption velocity.
Industry Challenges
- Microbial strain stability:Formulators struggle to maintain 10^8 CFU/g viability through South American temperature extremes during storage and transport, requiring cold chain investments.
- Legacy synthetic fertility programs:Agronomic advisory networks remain anchored to chemical input protocols, creating knowledge gaps in biological application timing and compatibility management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Biological Organic Fertilizers Market |
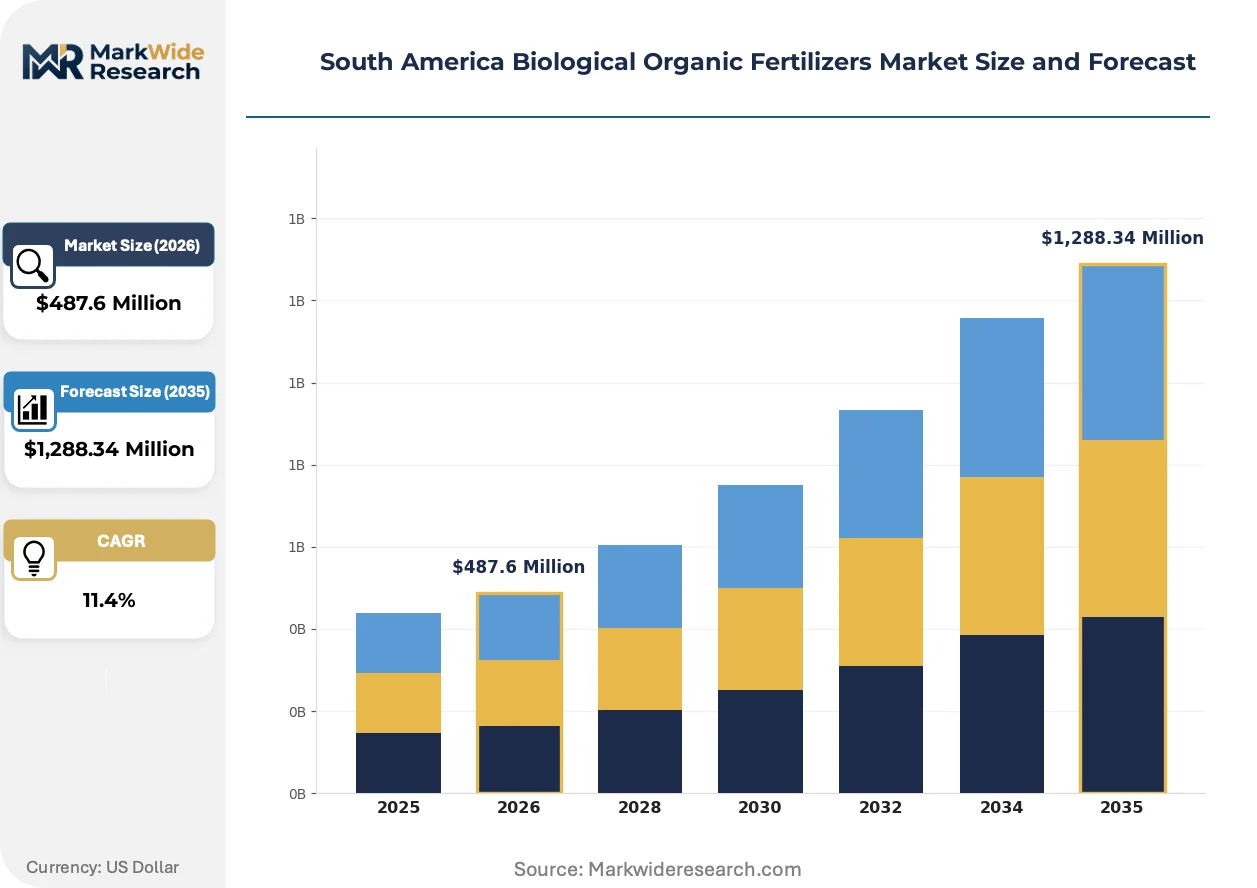
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fertilizers, Dry Fertilizers, Granular Fertilizers, Powder Fertilizers Source: Animal Waste, Plant Residues, Compost, Microbial Inoculants Application Method: Foliar Spray, Soil Application, Drip Irrigation, Seed Treatment Target Crop: Cereals, Fruits, Vegetables, Ornamental Plants |
| Companies Covered | Bio Protan, Symborg, Rizobacter Argentina S.A, Antibiotice SA, Lallemand Inc, Embrafos, Mabiotec, Biofosfatos do Brasil, T Stanes & Company Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Biological Organic Fertilizers Market Evolving Landscape
Multi-strain microbial consortia are supplanting single-organism inoculants, while regulatory harmonization efforts and precision application technologies reshape how biological fertility reaches field scale.
Consortium-based inoculant design is integrating nitrogen-fixing, phosphate-solubilizing, and phytohormone-producing microorganisms into unified formulations. Argentine wheat and barley producers in Buenos Aires province are adopting these triple-function products at accelerating rates. This convergence is compressing the addressable market for standalone single-strain products while elevating technical barriers for undifferentiated suppliers.
SENASA Resolution 33/2023 establishes equivalence protocols between Argentine and Mercosur organic certification standards. The regulation mandates third-party audit trails for microbial production batches and restricts animal-waste derivative sourcing to approved rendering facilities. Chilean berry exporters seeking SENASA-compliant inputs are reallocating procurement toward Buenos Aires-based formulators with established dossiers.
Specialty crop growers are consolidating input purchasing through integrated agronomic service providers rather than direct manufacturer relationships. Brazilian avocado operations in Minas Gerais now bundle biological fertility with precision irrigation and monitoring services. This channel shift concentrates volume with distributors possessing technical advisory capacity, marginalizing transactional resellers.
South America Biological Organic Fertilizers Market Segmentation
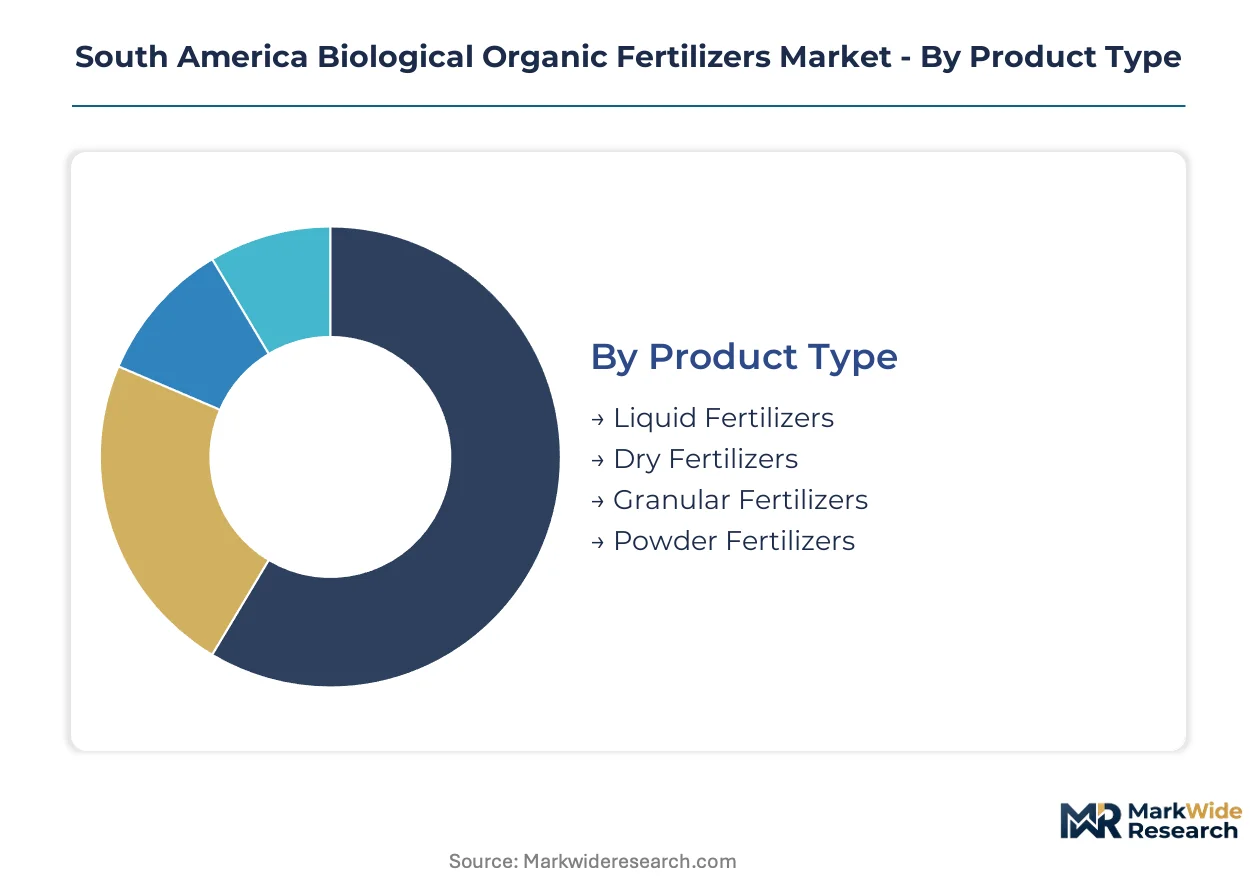
Biological organic fertilizer purchasing decisions in South America hinge on equipment compatibility, storage infrastructure, and crop-specific residue requirements. Formulation type and application method determine whether growers can integrate biologicals into existing operations without capital retrofit.
Product Type:
Technology specifications around handling equipment and shelf stability separate these categories across Brazilian mega-farms and Argentina's interior provinces.
- Liquid Fertilizers:Suspensions or solutions with microbial densities above 10^8 CFU per milliliter designed for direct tank-mixing with agrochemicals. Compatibility with existing spray equipment across Mato Grosso soybean operations eliminates capital barriers to adoption. Tank-mix stability with fungicides remains the critical specification hurdle.
- Dry Fertilizers:Pelletized or flaked formulations combining organic matter with dormant microbial cultures, requiring ambient storage conditions without cold chain dependency. Argentina's interior grain belts favor these for warehouse stability through seasonal temperature swings.
- Granular Fertilizers:Hard-pressed formulations engineered for mechanical spreader application with controlled release characteristics.
- Powder Fertilizers:Fine-ground organic substrates requiring dissolution or direct soil incorporation, common in smallholder vegetable systems.
Mature deployment sits with liquid formulations. Newer deployment is concentrated in dry variants.
Source:
Raw material origin dictates regulatory pathway, heavy metal thresholds, and organic certification eligibility across MAPA and SENASA jurisdictions.
- Microbial Inoculants:Pure culture formulations of Bradyrhizobium, Bacillus, or Pseudomonas strains produced through submerged fermentation. Brazil's soybean belt is accelerating uptake as nitrogen fixation alternatives to imported urea displace synthetic dependency.
- Animal Waste:Processed manure and rendering byproducts rich in nitrogen and phosphorus, subject to ANVISA heavy metal monitoring in Brazil.
- Plant Residues:Composted agricultural byproducts and crop processing waste streams.
- Compost:Stabilized organic matter from controlled aerobic decomposition processes.
Mature deployment sits with animal waste derivatives. Newer deployment is concentrated in microbial inoculants.
Application Method:
Equipment integration requirements and timing flexibility determine adoption feasibility across large-scale mechanized operations versus specialty crop holdings.
- Soil Application:Direct ground incorporation through broadcasting, banding, or in-furrow placement. Brazil's cerrado soybean operations deploy this method for pre-plant Bradyrhizobium establishment, leveraging existing tillage and planting equipment without modification.
- Foliar Spray:Leaf-surface application of soluble organic compounds and microbial suspensions. Chilean table grape vineyards utilize this method for targeted nutrient delivery during critical phenological stages.
- Drip Irrigation:Continuous fertigation through subsurface or surface drip lines.
- Seed Treatment:Direct coating of propagation material with microbial inoculants prior to planting.
Mature deployment sits with soil application. Newer deployment is concentrated in drip irrigation integration.
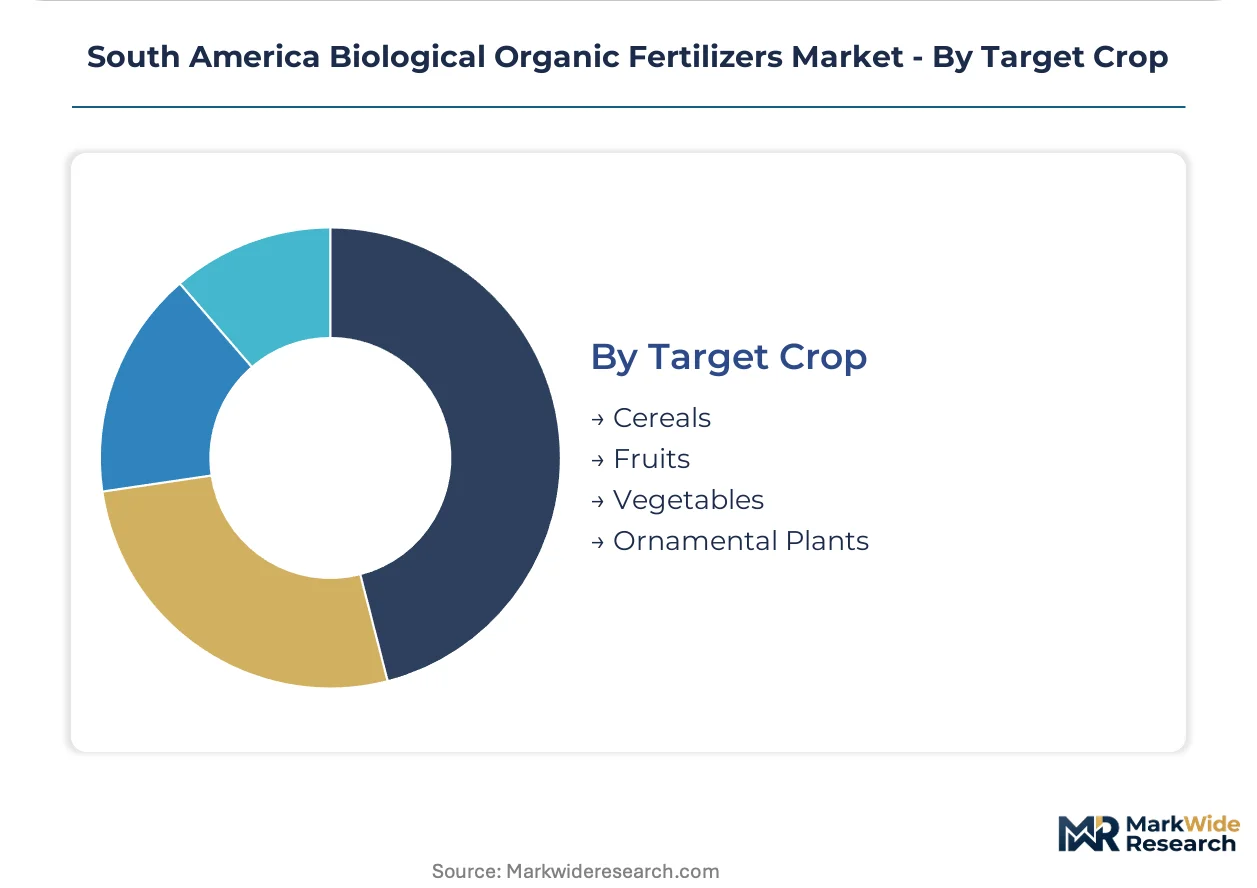
Target Crop:
Residue tolerance thresholds and export certification requirements create divergent demand intensity across commodity versus specialty production systems.
- Fruits:Avocado and berry operations across the Andean ridge seek residue-free certification for EU and North American export channels. Yeast-derivative and plant-extract formulations command premium positioning in Chilean table grape vineyards.
- Cereals:Wheat, barley, and soybean production systems where biological nitrogen fixation displaces synthetic urea. Argentina's Buenos Aires province grain belts deploy phosphate-solubilizing consortia to unlock fixed phosphorus in alkaline soils.
- Vegetables:Leafy and root crops with concentrated domestic consumption markets.
- Ornamental Plants:Nursery and landscape applications with aesthetic quality specifications.
Mature deployment sits with cereals. Newer deployment is concentrated in fruits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates microbial inoculant production capacity while Argentina and Chile drive differentiated consumption patterns shaped by export certification requirements and specialty crop expansion.
Brazil
Mato Grosso soybean operations deploy Bradyrhizobium formulations as primary nitrogen sources, displacing imported urea across 15 million hectares. MAPA Normative Instruction 46/2011 streamlines bioinput registration, reducing compliance timelines for new microbial strains. São Paulo province hosts concentrated fermentation infrastructure serving domestic demand and regional export.
Argentina
Buenos Aires grain belts adopt phosphate-solubilizing Bacillus consortia to unlock fixed phosphorus in alkaline soils. SENASA Resolution 33/2023 tightens organic certification protocols, extending product registration timelines for smaller formulators. The Buenos Aires R&D corridor anchors microbial strain development for Mercosur markets.
Chile
Table grape vineyards in the Central Valley integrate yeast-derivative formulations for residue-free EU export certification. The national agricultural service enforces maximum residue limits aligned with European Union standards. Precision irrigation corridors around Santiago enable drip-integrated biological fertigation at scale.
Colombia
Andean ridge avocado operations seek organic certification for North American market access, driving demand for plant-extract formulations. The national organic agriculture program subsidizes biological input adoption through technical assistance grants. Antioquia and Valle del Cauca provinces concentrate export-oriented specialty horticulture expansion.
Peru
Coastal desert agriculture deploys microbial inoculants in intensive asparagus and blueberry export zones. The Ministry of Agriculture enforces phytosanitary protocols for organic product equivalence with US and European markets. Ica and La Libertad valleys anchor biological input demand from integrated agro-exporters.
South America Biological Organic Fertilizers Market Competitive Landscape
Top-tier vendors anchor microbial strain development and fermentation scale, while mid-tier regional formulators compete on distribution proximity and crop-specific advisory. The market structures around three tiers: multinational biological platforms with integrated R&D, Mercosur-focused specialists with established regulatory dossiers, and commodity organic matter processors. Consolidation pressures intensify as MAPA streamlines registration requirements, favoring incumbents with existing compliance infrastructure. Capacity expansion and strategic partnerships dominate competitive moves, with fermentation asset control and distributor technical advisory capabilities serving as primary differentiation vectors.
Among Mercosur-based specialists, Rizobacter Argentina S.A and Embrafexemplify the integrated development-and-manufacturing archetype, occupying positions where regulatory dossier depth and strain library breadth create defensive moats. Symborg represents the premium technology platform segment, anchoring yeast-derivative positioning in high-value fruit export channels. Lallemand Inc sits within the multinational fermentation scale tier, leveraging adapted yeast infrastructure to serve agricultural biological demand across the continent. These three patterns—regional specialist, premium platform, and global scale—capture the competitive geometry shaping procurement decisions among Brazilian mega-farms and Andean specialty crop exporters.
| Leading Market Players |
|---|
| Bio Protan |
| Symborg |
| Rizobacter Argentina S.A |
| Antibiotice SA |
| Lallemand Inc |
| Embrafos |
| Mabiotec |
| Biofosfatos do Brasil |
| T Stanes & Company Limited |
| Others |
Value Network & Pricing Analysis
Family-owned fermentation specialists across São Paulo and Buenos Aires provinces anchor supply discipline through generational capital allocation patterns that resist price-undercutting pressures even during commodity downturns. Their patient financing structures buffer margin compression while sustaining colony-forming unit quality thresholds above regulatory minimums.
Pricing Analysis
Cost-down pressure on standard-grade microbial inoculants accelerates because Brazilian mega-farms consolidate procurement through integrated agronomic service providers. Three-tier pricing structure across premium, standard, and economy levels separates SENASA-certified formulations from MAPA-registered alternatives and unregistered commodity organics. Certification grade and volume scale drive price differentiation, with export-oriented berry operations absorbing premium multiples while domestic soybean growers prioritize per-hectare unit economics. Price erosion runs through economy-tier animal-waste derivatives as synthetic urea import costs fluctuate.
Supply Chain Analysis
Dual-sourcing requirements from Chilean table grape exporters mandate qualified suppliers in both Buenos Aires and São Paulo fermentation corridors to mitigate batch-failure risk. Geographic supply concentration centers on Brazil, Argentina, and Chile for microbial strain development and finished formulation. Raw material dependencies rest on specialized yeast fermentation substrates, Bradyrhizobium culture media, and phosphate-solubilizing Bacillus precursors. Single-source vulnerability concentrates in São Paulo bioreactor capacity. Distribution runs through technical advisory-anchored distributors rather than transactional resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation infrastructure scarcity props pricing power for incumbent producers, constraining supply response even as Mato Grosso soybean acreage expands biological nitrogen fixation demand.
For Market Incumbents: Anticipate MAPA bioinput simplification accelerating new strain commercialization by streamlining colony-forming unit verification requirements. Defensive consolidation through backward integration into yeast substrate production in São Paulo province secures margin against input cost volatility. Channel control investments in technical advisory capacity protect volume against integrated agronomic service provider consolidation. For New Entrants and Emerging Players: Enter via Colombia's subsidized organic agriculture program, where technical assistance grants lower adoption barriers for plant-extract formulations in Antioquia avocado operations. White-space concentration sits with drip-integrated microbial consortia for Peruvian coastal desert asparagus exporters seeking US market equivalence certification. Go-to-market positioning through precision irrigation equipment bundling bypasses established distributor relationships. For Investors and Strategic Acquirers: SENASA Resolution 33/2023 equivalence protocol implementation is the leading indicator that Buenos Aires-based formulators with established dossiers will capture Chilean berry procurement reallocation. Long-term viability frames around regulatory compliance infrastructure as the scarcest capability across the projection horizon. Acquisition targets center on Mercosur specialists with strain library breadth and ANVISA-aligned manufacturing protocols. Watch MAPA registration queue acceleration as the signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Investment | Brazilian distributors with refrigerated transport networks capture microbial viability premiums in Mato Grosso. |
| Strain Library Acquisition | Consolidation of Argentine Bacillus consortia developers accelerates triple-function product pipelines for Buenos Aires grain belts. |
| Regulatory Dossier Expansion | SENASA-aligned documentation investments unlock Chilean table grape vineyard procurement reallocation toward compliant suppliers. |
| Precision Irrigation Partnership | Integration with Santiago-area fertigation equipment manufacturers embeds biological formulations in premium fruit export channels. |
| Backward Integration into Substrate Production | Captive yeast fermentation substrate supply insulates São Paulo manufacturers from input cost volatility. |
Research Methodology
Independent corroboration across MAPA registration databases, SENASA organic certification filings, and Brazilian customs trade records underwrites the qualitative findings on commercial strain adoption velocity. Primary interviews with fermentation plant managers, agronomic service provider procurement leads, and Chilean table grape vineyard operations directors combined with secondary validation from ANVISA bioinput safety disclosures and Argentine grain belt extension service reports. Bottom-up strain shipment tallies triangulate against top-down agricultural input expenditure surveys.
Comparable-period anchoring to historical bioinput registration timelines under MAPA Normative Instruction 46/2011 establishes baseline commercialization velocity assumptions across the analysis window. Segmentation modeling incorporates formulation type, microbial strain category, application method, and target crop residue requirements. CAGRs derive from triangulated shipment volume trajectories and farmer input expenditure surveys. Industry-specific forecast inputs include synthetic urea import price volatility indices and Mercosur organic certification expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt synthetic fertilizer price collapse or SENASA protocol enforcement disruption. Deviation in MAPA simplification implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Bacterial Biopesticides Market