
 Cytokinins Market | 2026-2036
Cytokinins Market Size, Share, and Industry Trends Forecast 2026-2036
Cytokinins Market Analysis
Market Dynamics
Capital-intensity divergence between integrated agrochemical conglomerates and focused biostimulant specialists is redrawing competitive boundaries in the cytokinins space. BASF SE leverages its Ludwigshafen-based fermentation infrastructure to sustain captive kinetin production, while Syngenta Group anchors its position through proprietary formulation chemistry that extends molecule stability under field stress. Valent BioSciences LLC differentiates via its dedicated plant physiology R&D campus in Libertyville, Illinois, occupying a narrow but defensible niche in high-value horticultural cytokinin blends.
Product Landscape
Cytokinins comprise a class of adenine-derived plant hormones that regulate cell division, shoot initiation, and senescence delay, with synthetic variants such as benzyladenine and thidiazuron manufactured through purine alkylation or urea cyclization routes to achieve precise activity thresholds. Zeatin and its riboside forms dominate commercial volumes due to established efficacy in tissue culture and post-harvest preservation, while thidiazuron commands premium positioning in cotton defoliation and ornamental propagation where auxin-cytokinin ratio control determines margin pools. Kinetin retains mature demand in cosmetic and dermatological applications, though agricultural supply outlets increasingly favor benzyladenine formulations for apple and pear fruitlet thinning programs.
Regulatory Environment
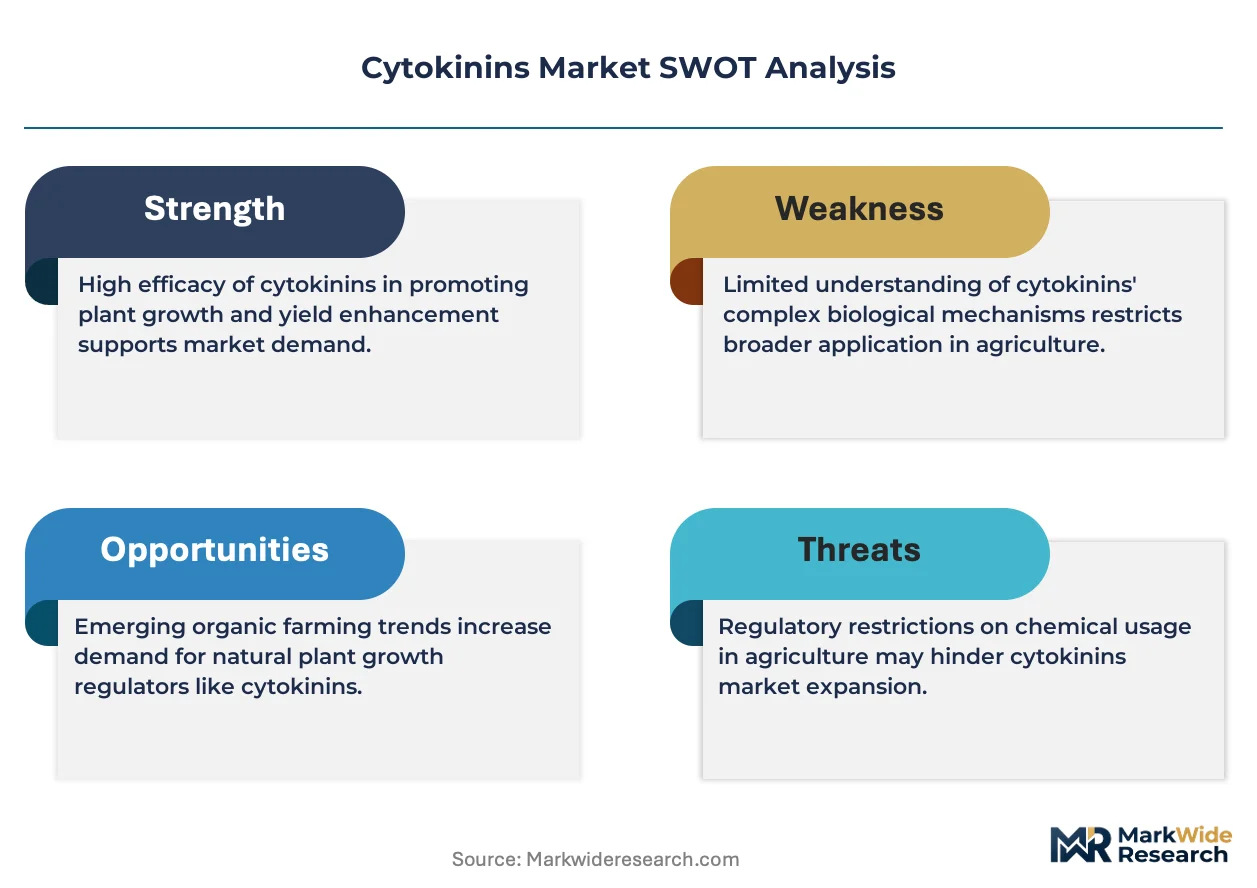
The EPA governs cytokinin registration under FIFRA with residue tolerance thresholds that shape formulation strategies for US field crop applications, while the EU's REACH framework and pending Sustainable Use of Pesticides Regulation are tightening data requirements for plant biostimulant claims across member states. China's Ministry of Agriculture and Rural Affairs implements GB standard compliance for microbial and biochemical pesticide categories, creating divergent approval timelines that fragment market access for imported active ingredients. Stakeholders must monitor regulatory recalibration in Brazil and India, where accelerating biostimulant registration pathways could reorder competitive priority for novel cytokinin analog development.
Market Dynamics
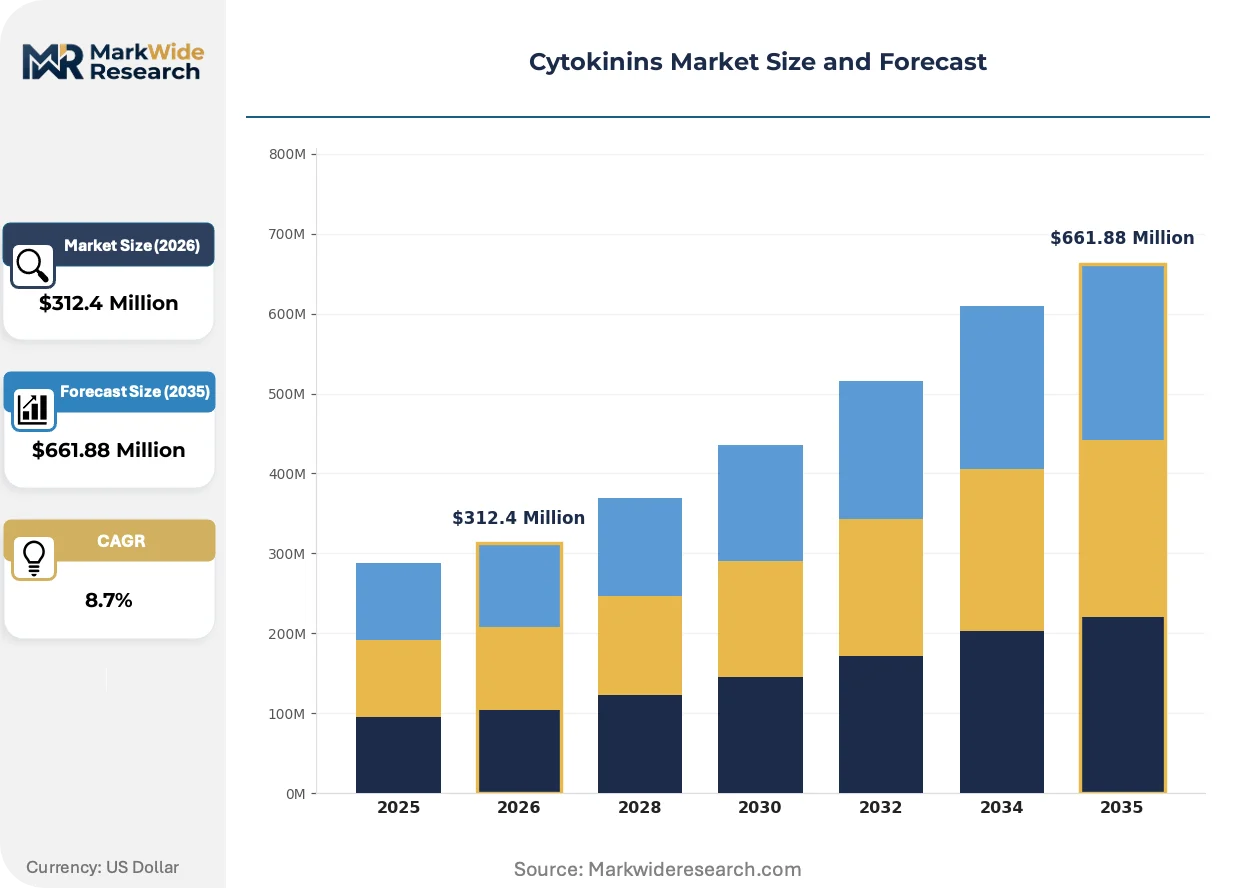
The cytokinins market faces structural pressure from the EU's Sustainable Use of Pesticides Regulation, which reclassifies plant biostimulant claims and forces reformulation investments across synthetic and natural product lines.
Growth Catalysts
- EU Farm to Fork Strategy:The European Green Deal's residue limit tightening accelerates biological input registrations, opening premium positioning for cytokinin-based biostimulants in specialty crop segments.
- Protected horticulture expansion:China's Shandong and Xinjiang provinces scale protected cultivation and cotton seed treatment programs, concentrating demand for zeatin and benzyladenine formulations.
- Fermentation infrastructure:Advances in microbial cytokinin production reduce dependency on synthetic purine alkylation, enabling cost-competitive natural analog supply for tissue culture laboratories.
Market Restraints
- Adenine feedstock volatility:Purine base supply concentrates among Chinese chemical intermediates manufacturers, exposing formulation costs to input price swings.
- REACH data requirements:The EU's evolving biostimulant classification demands expanded toxicological dossiers, extending registration timelines and freezing market access for novel analogs.
- Auxin-cytokinin combination products:Fixed-ratio hormone blends in generic agrochemical portfolios threaten standalone cytokinin margins in commodity crop applications.
Strategic Opportunities
- Brazil biostimulant pathway:ANVISA's accelerating registration framework for biological inputs creates first-mover advantage for cytokinin specialists establishing local formulation partnerships.
- Post-harvest preservation:Zeatin riboside applications in cold chain logistics for tropical fruit exports represent an underdeveloped vertical with premium pricing potential.
- Cosmetic dermatology crossover:Kinetin's established efficacy in skin cell renewal protocols enables dual-use manufacturing economics across agricultural and personal care supply chains.
Industry Challenges
- Plant physiologist scarcity:Formulation development requires specialized expertise in hormone interaction modeling that outpaces university training program output.
- Multi-jurisdiction dossier management:Divergent GB standard compliance in China, EPA FIFRA tolerance thresholds in the US, and REACH obligations in Europe force parallel regulatory investment streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytokinins Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzyladenine, Kinetin, Zeatin, Thidiazuron Application: Fruits, Vegetables, Ornamental Plants, Field Crops Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply Outlets, Distributors End User: Farmers, Nurseries, Horticulturists, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Corteva Agriscience, Valent BioSciences LLC, Nufarm Ltd, Sumitomo Chemical Co., Ltd., Redox Industries, Sichuan Guoguang Agrochemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytokinins Market Emerging Trajectories
Biostimulant regulation divergence across major economies is forcing technology platform bets that favor either synthetic precision or natural fermentation pathways, reshaping R&D allocation and partnership strategies.
Nano-encapsulation delivery systems for cytokinin active ingredients is fragmenting the formulation landscape. Specialty crop producers in Mediterranean olive and table grape cultivation adopt lipid-shell and polymer-matrix carriers to extend hormone release under field stress. This technology is fragmenting competitive advantage away from pure molecule suppliers toward integrated delivery platform developers with proprietary coating chemistry.
REACH framework recalibration under the EU's pending Sustainable Use of Pesticides Regulation tightens residue tolerance thresholds for synthetic cytokinins in food crops. Formulators must generate expanded environmental fate data or pivot toward microbial-derived alternatives. High-value horticultural segments in Spain and Italy absorb compliance costs through premium positioning, while commodity crop applications face margin compression.
Direct-to-grower digital channels displace traditional agrochemical distributor networks for cytokinin biostimulant procurement. Specialty crop cooperatives in Italy's Emilia-Romagna region and Spain's Andalusia cluster purchase customized blends through platform-enabled agronomy services. China's Alibaba-backed agricultural marketplaces extend this pattern, connecting Shandong greenhouse operators with formulation laboratories for batch-specific orders.
Cytokinins Market Segmentation
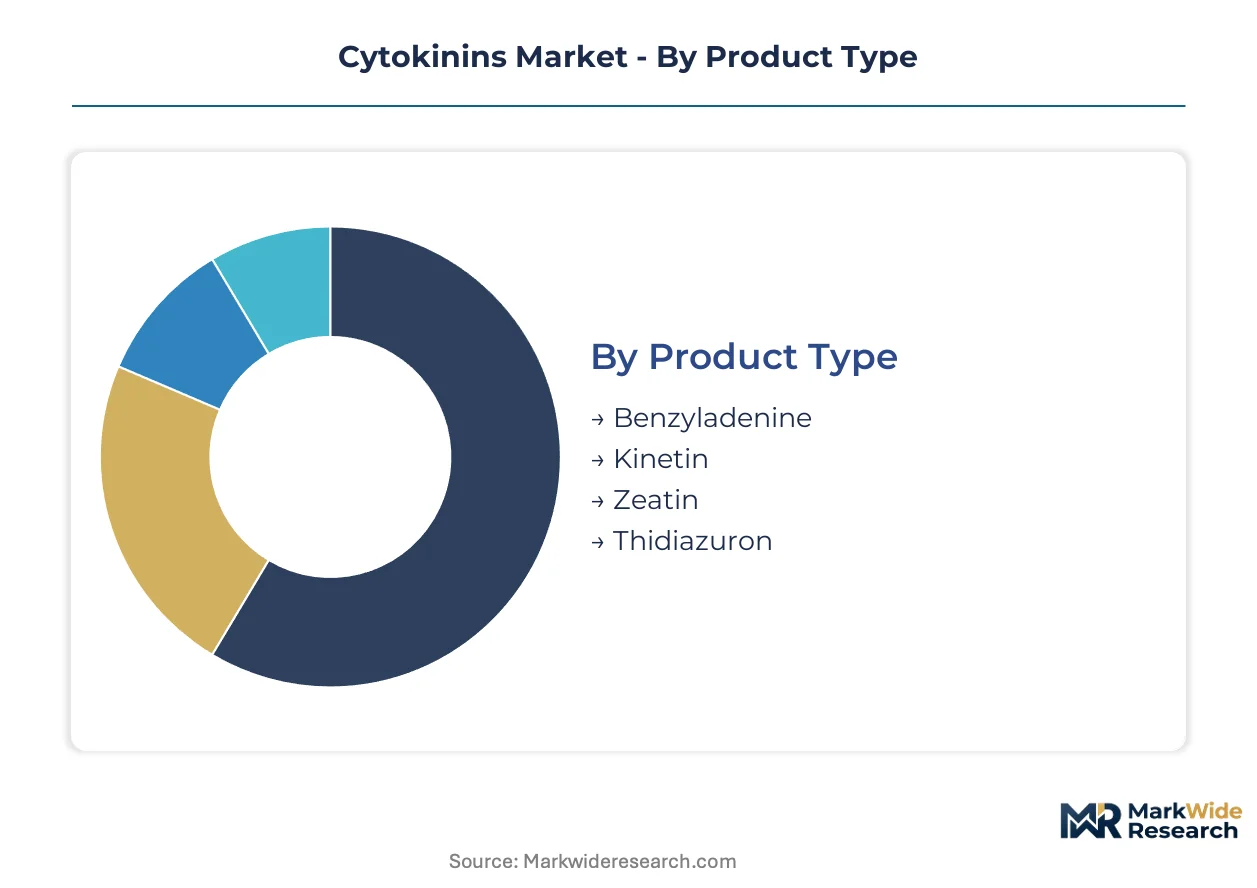
Cytokinin segmentation reveals divergent substitution pressures across product chemistries and application contexts. Hormone-specific efficacy profiles and regulatory tolerance thresholds determine where formulation investments concentrate versus where generic alternatives erode margins.
Product Type:
Natural fermentation-derived cytokinins face intensifying competition from synthetic purine alkylation routes, though residue tolerance regulations in export-oriented horticulture preserve premium positioning for specific analogs.
- Zeatin:Riboside and trans-isomer forms extracted through microbial fermentation or plant tissue sources. Demand concentrates in China's Shandong province protected horticulture and tropical fruit post-harvest preservation chains where EU residue limits favor natural-origin claims.
- Benzyladenine:Synthetic adenine derivative manufactured through purine alkylation with precise activity thresholds. Apple and pear fruitlet thinning programs in Washington State and Italy's Emilia-Romagna absorb volumes, though auxin-cytokinin combination generics threaten standalone margins in commodity applications.
- Kinetin:First-generation synthetic cytokinin retaining stable demand in cosmetic dermatology and tissue culture laboratories. Dual-use manufacturing economics across agricultural and personal care supply chains sustain production scale.
- Thidiazuron:Urea-cyclized phenyl derivative commanding premium positioning in cotton defoliation and ornamental propagation. Auxin-cytokinin ratio control requirements in vegetative cutting programs defend margin pools against generic hormone blends.
Zeatin retains volume leadership across fermentation infrastructure investments; thidiazuron holds the steepest expansion curve in high-value ornamental and industrial crop segments.
Application:
Cost-tier stratification separates protected cultivation inputs from broad-acre commodity treatments, with compliance burden distribution determining where biological premium claims justify formulation expenditure.
- Fruits:Table grape cultivation in Spain's Andalusia region and olive groves across Italy absorb cytokinin investments for berry sizing and harvest synchronization. EU Farm to Fork Strategy residue tightening accelerates biological input registrations in export-oriented Mediterranean production.
- Vegetables:Protected greenhouse operations in China's Xinjiang province scale benzyladenine and zeatin applications for transplant establishment and yield consistency. Direct-to-grower digital procurement channels displace traditional distributor networks in this segment.
- Ornamental Plants:Thidiazuron-driven tissue culture propagation and cutting establishment programs concentrate in Dutch floriculture clusters and Colombian export nurseries. Nano-encapsulation delivery systems extend hormone release under controlled-environment stress.
- Field Crops:Cotton defoliation in Xinjiang and seed treatment programs absorb standardized cytokinin volumes. Generic auxin-cytokinin combination products compress standalone margins in this commodity-facing tier.
Fruits command premium formulation investment per hectare; vegetables gain share fastest through protected horticulture expansion in Asia-Pacific production clusters.
Distribution Channel:
Customer-type fragmentation between precision agronomy adopters and price-sensitive commodity producers drives channel bifurcation toward platform-enabled direct procurement versus traditional agricultural supply relationships.
- Agricultural Supply Outlets:Established distributor networks serving broad-acre field crop operators with standardized benzyladenine and kinetin formulations. Inventory concentration in cotton and grain production regions sustains volume throughput.
- Distributors:Multi-brand aggregators supplying specialty crop cooperatives in Italy and Spain with portfolio breadth across hormone classes and combination products. Technical agronomy support services defend margin capture against direct channels.
- Specialty Stores:Horticulture-focused retailers serving nursery and greenhouse operators with tissue culture-grade zeatin and precision-formulated thidiazuron products. Product expertise and application guidance differentiate positioning.
- Online Retail:Alibaba-backed agricultural marketplaces and platform-enabled agronomy services connect Shandong greenhouse operators with formulation laboratories for batch-specific orders. Customized blend procurement accelerates in specialty crop segments.
Agricultural supply outlets retain volume leadership in commodity crop penetration; online retail climbs the fastest in high-value horticulture cluster adoption.
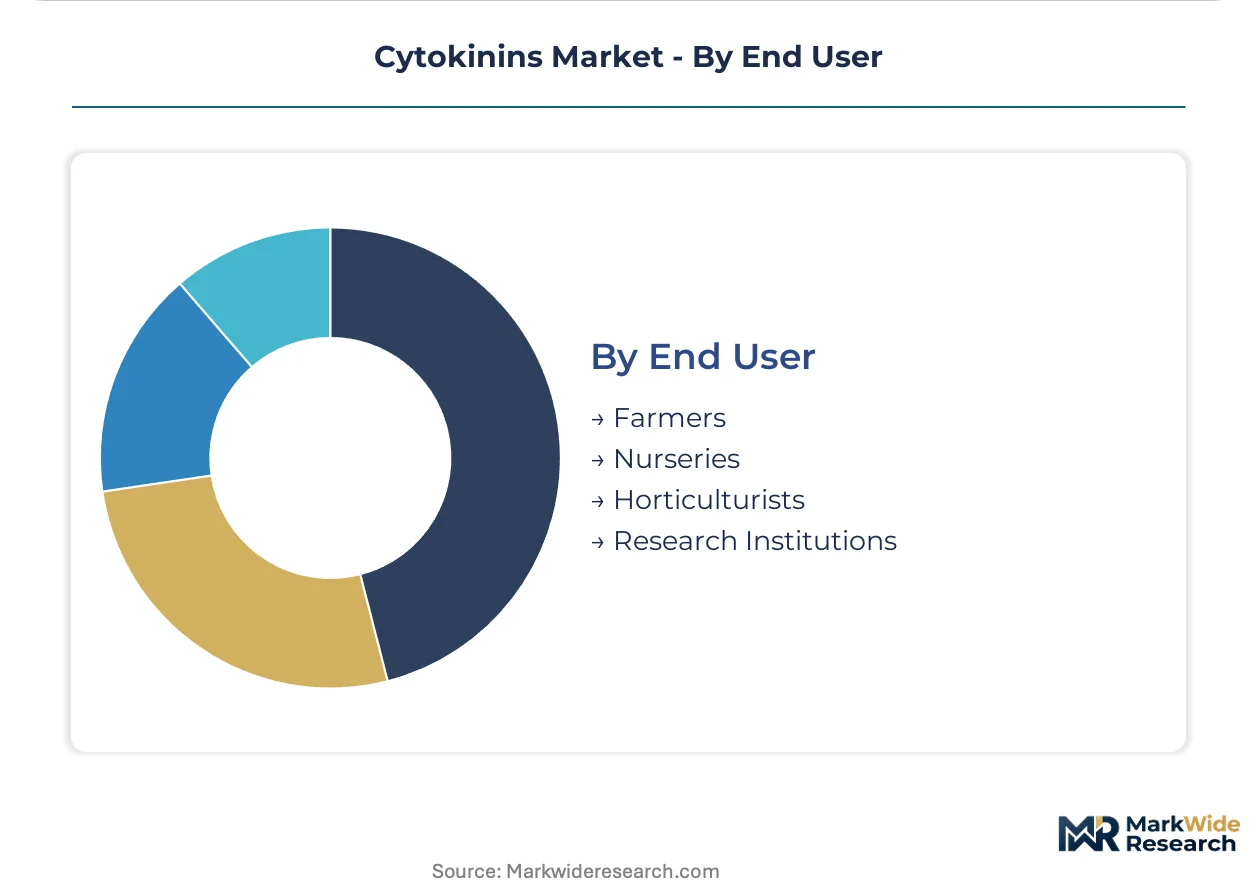
End User:
Maturity-stage differentiation separates research-driven specification demand from field-scale operational procurement, with capability scarcity in plant physiology expertise constraining formulation development partnerships.
- Farmers:Broad-acre operators in cotton and grain systems utilizing standardized cytokinin applications through distributor-supplied programs. Price sensitivity and generic combination product availability limit standalone hormone adoption.
- Nurseries:Ornamental and fruit tree propagation specialists requiring precise auxin-cytokinin ratio control in cutting establishment and grafting programs. Technical specification adherence determines supplier selection.
- Horticulturists:Protected cultivation specialists in Spain, Italy, and China's Shandong province demanding customized blends for table grape, olive, and vegetable production. Platform-enabled direct procurement channels gain traction in this segment.
- Research Institutions:Universities and biotechnology laboratories driving specification requirements for tissue culture-grade zeatin and novel cytokinin analog development. Fermentation infrastructure partnerships and proprietary formulation chemistry investments concentrate here.
Farmers retain absolute volume leadership across hectare coverage; horticulturists expand most quickly through premium protected cultivation scaling in Mediterranean and Asia-Pacific production clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese greenhouse operators absorb price premiums for zeatin formulations, while US cotton growers prioritize cost-minimized benzyladenine generics. European specialty crop producers occupy the middle ground, paying formulation premiums for residue-compliant natural analogs.
China
Shandong and Xinjiang provinces drive zeatin and benzyladenine consumption through protected horticulture scaling and cotton seed treatment programs. The Ministry of Agriculture and Rural Affairs enforces GB standard compliance for microbial pesticide categories, fragmenting approval timelines for imported actives. Alibaba-backed agricultural marketplaces in Shandong connect greenhouse operators directly with formulation laboratories for batch-specific cytokinin orders.
United States
Washington State apple and pear fruitlet thinning programs absorb standardized benzyladenine volumes, while cotton defoliation in Texas and the Mid-South sustains thidiazuron demand. The EPA governs registration under FIFRA with residue tolerance thresholds that shape formulation strategies for field crop applications. Valent BioSciences maintains its dedicated plant physiology R&D campus in Libertyville, Illinois, serving high-value horticultural cytokinin blends.
Spain
Andalusia's table grape cultivation and olive groves absorb premium cytokinin investments for berry sizing and harvest synchronization. The EU's Farm to Fork Strategy under the European Green Deal tightens residue limits and accelerates biological input registrations. Specialty crop cooperatives in Andalusia increasingly procure customized blends through platform-enabled agronomy services displacing traditional distributor networks.
Italy
Emilia-Romagna's pear and apple orchards represent concentrated demand for benzyladenine-based fruitlet thinning programs. REACH framework obligations under the pending Sustainable Use of Pesticides Regulation demand expanded toxicological dossiers for biostimulant claims. Direct-to-grower digital channels gain traction among horticulturists in the Po Valley seeking residue-compliant natural cytokinin formulations.
Brazil
Cotton and soybean seed treatment programs in Mato Grosso and Goiás scale cytokinin applications for stress mitigation and early vigor enhancement. ANVISA's accelerating registration framework for biological inputs creates first-mover positioning for cytokinin specialists establishing local formulation partnerships. The Cerrado expansion corridor concentrates demand for cost-competitive synthetic analogs amid price-sensitive broad-acre procurement patterns.
Cytokinins Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cytokinins space. Integrated agrochemical conglomerates with captive fermentation infrastructure compete against focused biostimulant specialists with dedicated plant physiology R&D capabilities. The market structure fragments across three strategic archetypes: purine-based synthetic manufacturers, microbial fermentation specialists, and formulation-integrated delivery platform developers. Dominant competitive moves include backward integration into adenine feedstock supply and proprietary nano-encapsulation coating chemistry investments.
Among European-based integrated conglomerates, BASF SE and Bayer AG exemplify the scale-driven archetype with Ludwigshafen-based fermentation infrastructure sustaining captive production economics. Syngenta Group anchors the formulation-technology tier through proprietary chemistry extending molecule stability under field stress. Valent BioSciences LLC occupies the specialist position with its Illinois-based R&D campus dedicated to high-value horticultural cytokinin blends.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Valent BioSciences LLC |
| Nufarm Ltd |
| Sumitomo Chemical Co., Ltd. |
| Redox Industries |
| Sichuan Guoguang Agrochemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Shandong greenhouse operators and fermentation-based zeatin suppliers lock in feedstock access and price visibility across volatile purine base markets. These arrangements concentrate procurement power among buyers with scale, while spot-market exposure punishes smaller horticulturists in Xinjiang and Italy's Emilia-Romagna.
Pricing Analysis
After-sales agronomy advisory services drive lifetime value for cytokinin formulators more than molecule margins alone. Three-tier pricing structure across premium, standard, and economy levels separates residue-certified natural analogs for EU export horticulture from generic benzyladenine for domestic Chinese cotton. Cost compression in commodity-grade synthetic cytokinins is intensifying because fixed-ratio auxin-cytokinin generics erode standalone pricing. Broad-acre cotton growers in Brazil and Xinjiang exhibit highest price sensitivity; Mediterranean table grape cooperatives absorb premium tiers for compliance-certain formulations.
Supply Chain Analysis
Adenine feedstock concentration in Chinese chemical intermediates manufacturers exposes global cytokinin production to input price volatility and regulatory interruption. Purine base synthesis draws from coal-derived chemical complexes in Shandong and Hebei provinces, while fermentation infrastructure for natural zeatin concentrates in Denmark and the United States. Single-source vulnerability in adenine supply creates acute formulation cost risk when environmental inspections shutter Chinese chemical parks. Distribution runs through agricultural supply outlets for commodity crop penetration and platform-enabled direct channels for specialty horticulture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cytokinin market functions as a service-attach opportunity where recurring agronomy advisory contracts expand faster than standalone molecule sales. Formulation laboratories bundling batch-specific blend development with growing-season technical support capture margin pools unavailable to pure suppliers.
For Market Incumbents: Shield market position by deepening captive fermentation infrastructure in low-cost jurisdictions and accelerating proprietary nano-encapsulation coating chemistry investments. Generic auxin-cytokinin combination products threaten standalone margins in commodity applications; certification investment for EU Farm to Fork Strategy compliance defends premium positioning in Mediterranean horticulture.
For New Entrants and Emerging Players: Differentiate on microbial-derived natural analog supply with residue-certain origin claims for EU export-oriented producers. Brazil's accelerating ANVISA registration pathway for biological inputs represents the most penetrable geography; partner with established Cerrado formulation distributors for rapid hectare coverage without parallel regulatory investment.
For Investors and Strategic Acquirers: Capital is best deployed toward fermentation specialists with dual-use manufacturing economics spanning agricultural and cosmetic dermatology supply chains. Long-term viability across the analysis window hinges on backward integration into adenine feedstock or proprietary delivery platform technology; monitor REACH framework recalibration under the EU's pending Sustainable Use of Pesticides Regulation as inflection indicator for natural versus synthetic pathway returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adenine Feedstock | Captive purine base supply insulates BASF and Bayer from Chinese chemical intermediate price volatility. |
| Proprietary Nano-Encapsulation Development | Lipid-shell carriers extend hormone release for Spanish olive groves under field stress conditions. |
| EU Biostimulant Registration Acceleration | REACH compliance investment opens premium positioning for residue-certified zeatin in Italian export horticulture. |
| Direct-to-Grower Platform Partnership | Alibaba-backed agricultural marketplaces connect Shandong greenhouse operators with batch-specific formulation laboratories. |
| Dual-Use Manufacturing Scale-Up | Kinetin production serving cosmetic dermatology protocols generates agricultural supply chain economies. |
Methodological Framework
Cross-validation between executive interviews at fermentation specialists and customs trade data anchors the qualitative findings in measurable input-output flows. Plant physiology R&D directors, agricultural supply outlet procurement managers, greenhouse cooperative technical officers, and regulatory affairs leads at biostimulant registrants provided primary perspective. Secondary validation drew from EPA FIFRA tolerance threshold filings, ECHA REACH dossier submissions, China's GB standard compliance records, and SEC 10-K disclosures from integrated agrochemical conglomerates. Bottom-up hectare adoption modeling and top-down input-output analysis triangulate volume estimates.
Sensitivity analysis around adenine feedstock price scenarios and regulatory approval timeline distributions tests forecast robustness across the projection horizon. Segmentation dimensions include product chemistry type, application crop category, distribution channel structure, and end-user capability tier. CAGRs derive from fitted adoption curves calibrated against historical biostimulant penetration patterns in comparable hormone classes. Modeled inputs incorporate protected horticulture expansion rates in Shandong and Xinjiang, EU Farm to Fork Strategy implementation pace, and ANVISA registration throughput for biological inputs.
Material uncertainties — adenine supply disruption, REACH recalibration scope, and Brazil registration pathway execution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and feedstock price mean-reversion that sustained deviation would invalidate. Practitioners should keep alternative scenarios live as EU Sustainable Use of Pesticides Regulation enforcement intensity and Chinese environmental inspection frequency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Microphytes Market