
 Welding Equipment and Consumables Market | 2026-2036
Welding Equipment and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Equipment and Consumables Market Analysis
Project finance for automated welding cells is tilting competitive dynamics toward capital-rich suppliers. Lincoln Electric leverages captive financing programs to anchor large fleet deployments across North American automotive plants. ESAB competes through backward integration into filler metal production, controlling raw material cost exposure. Fronius International specializes in laser-hybrid systems for e-mobility battery tray assembly, differentiating on arc stability algorithms.
Welding equipment and consumables encompass power sources, torches, electrodes, and shielding gases engineered to join metals through controlled thermal fusion, typically operating at temperatures exceeding melting points by controlled amperage delivery. The primary purpose spans structural fabrication, component repair, and continuous production across heavy industry. Welding consumables generate recurring revenue streams with higher margin stability than capital equipment sales. MIG technology dominates volume in automotive production due to speed and operator efficiency, while TIG systems command premium positioning in aerospace precision work. Plasma arc adoption accelerates in thin-material fabrication where heat-affected zone minimization determines quality grades.
OSHA exposure limits for hexavalent chromium and manganese fumes directly shape consumable formulation R&D budgets across US-based manufacturers. EU F-Gas Regulation and REACH compliance force reformulation of shielding gas blends and electrode coatings for European market access. China's GB standards and MEE enforcement tighten local production quality thresholds, raising barriers for imported equipment without localized certification. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs become a decisive factor in regional sourcing strategies.
Market Dynamics
Automotive OEMs are consolidating welding cell procurement into multi-year fleet contracts, concentrating purchasing power among capital-rich suppliers and compressing margins for equipment-only vendors.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP shielding gas blends are accelerating inverter power source upgrades across German and Italian fabrication shops.
- Battery tray welding:E-mobility manufacturers in China and Mexico are installing laser-hybrid systems for aluminum structural bonding at unprecedented scale.
- Shipbuilding clusters:Jiangsu and Guangdong provinces are driving consumables volume through infrastructure and vessel construction programs.
Market Restraints
- Copper and lithium price volatility:Electrode coating materials and battery-grade metals face input cost swings that erode consumables margin predictability.
- Supply concentration in tungsten:Over 80% of global tungsten ore processing sits in China, creating chokepoint risk for TIG electrode availability.
- Technical limitation in thin-steel laser welding:Porosity control below 1.2mm thickness remains unresolved, blocking full substitution of arc processes in automotive body-in-white.
Strategic Opportunities
- India's PLI scheme for auto components:Localized welding equipment manufacturing incentives are opening captive supply arrangements for multinational consumables producers.
- Wind tower fabrication:Offshore turbine monopile construction is creating demand for submerged arc and flux-cored wire systems at Baltic and North Sea ports.
- AI-driven weld monitoring:Machine vision integration with power sources enables predictive maintenance contracts and recurring software revenue streams.
Industry Challenges
- Certified welder shortage:AWS and IIW qualification pipelines are failing to replenish retiring skilled labor in North American and European fabrication yards.
- Legacy system integration:Retrofitting Industry 4.0 data collection into 1990s-era resistance welding lines requires costly controller replacement and production downtime.
- Multi-jurisdiction compliance:Manufacturers must maintain parallel certification tracks for OSHA hexavalent chromium limits, REACH substance restrictions, and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Equipment and Consumables Market |
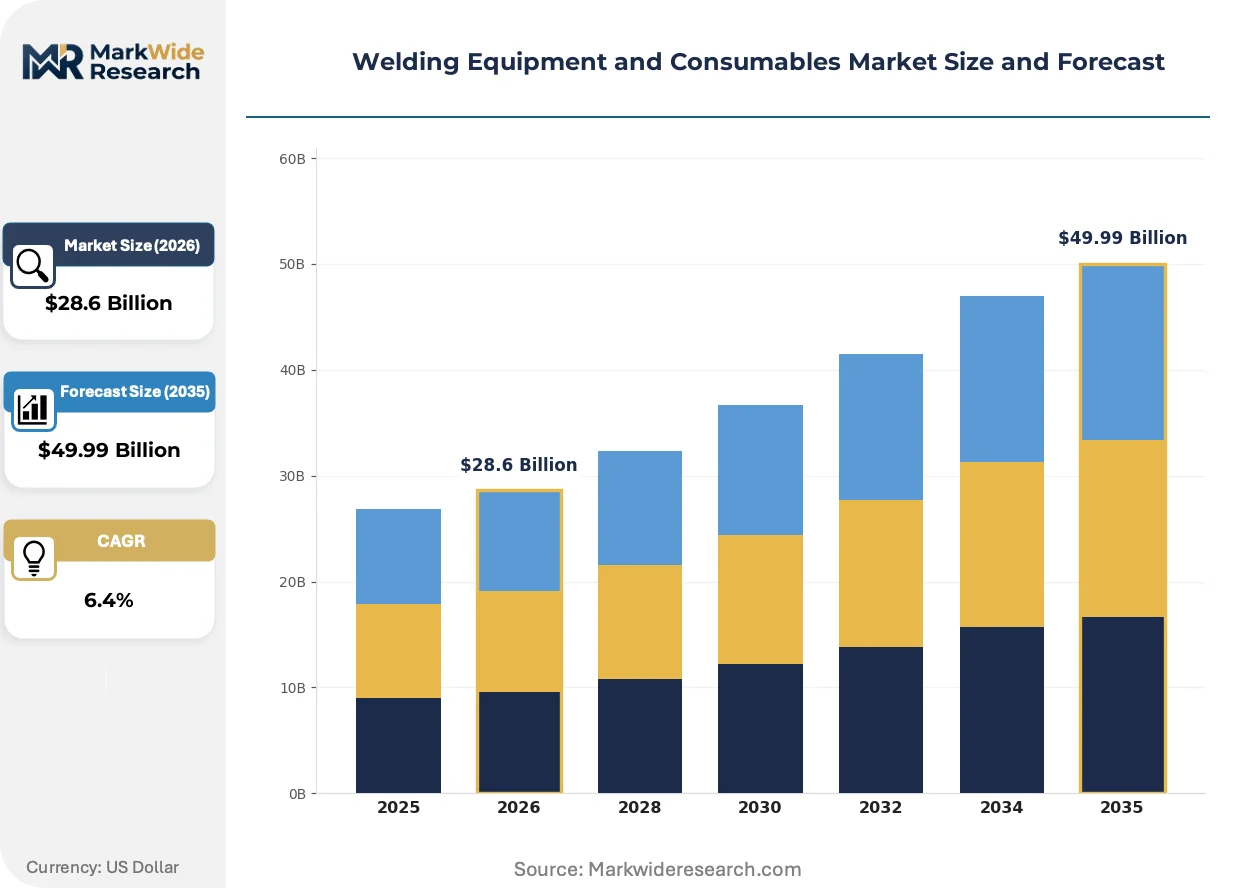
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Welding Machines, Welding Accessories, Welding Consumables, Safety Equipment Technology: MIG, TIG, Stick, Plasma Arc End User: Manufacturing, Construction, Automotive, Aerospace Application: Fabrication, Repair, Maintenance, Production |
| Companies Covered | Illinois Tool Works Inc., Panasonic Industry Co., Ltd., Lincoln Electric, Voestalpine Bohler Welding Group GmbH, OTC DAIHEN Inc., ESAB, Fronius International, Kemppi Oy., Miller Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Equipment and Consumables Market Emerging Trajectories
Welding technology is bifurcating between high-speed automation for volume production and precision systems for quality-critical applications, with software-defined arc control becoming the primary differentiation vector.
Advanced waveform control in inverter power sources is rendering obsolete traditional transformer-based machines in automotive production environments. Tier-1 suppliers in Michigan and Bavaria are completing fleet conversions to pulse-MIG systems that adjust amperage in millisecond intervals. The technology is rendering obsolete manual parameter setting, compressing training cycles and reducing defect rates below 0.3% in high-volume lines.
REACH substance restrictions on nickel and cobalt compounds are forcing reformulation of hardfacing consumables across European oil and gas repair sectors. Manufacturers must submit updated safety data sheets and obtain re-certification from notified bodies before market re-entry. Hardbanding wire producers serving North Sea drilling contractors face the steepest compliance timelines and inventory write-downs.
Equipment-as-a-service contracts are displacing outright purchase for automated welding cells in capital-constrained fabrication shops. Lincoln Electric and Fronius are piloting per-meter-welded pricing models with Mexican automotive suppliers. This shift is most visible in Guanajuato and Puebla, where OEMs prefer operational expenditure classification for balance sheet optimization.
Welding Equipment and Consumables Market Segmentation
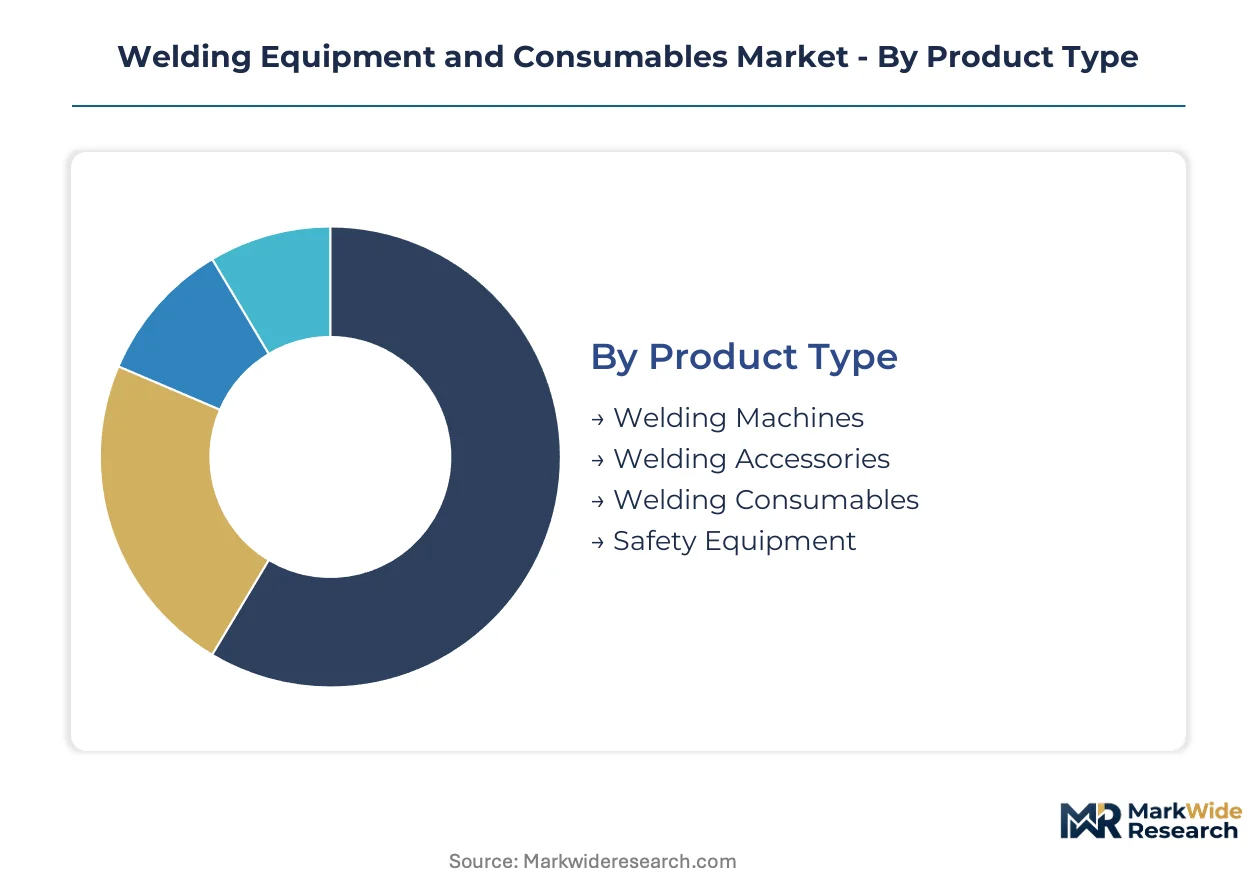
Segmentation in welding equipment reveals how capital intensity, regulatory exposure, and automation requirements fragment purchasing behavior across end-use verticals. Equipment buyers prioritize arc stability algorithms and software integration, while consumables procurement responds to fume exposure limits and alloy price volatility.
Product Type:
Capital deployment cycles diverge sharply between installed-base equipment and recurring consumables, with financing structures and margin profiles dictating supplier strategy.
- Welding Machines:Inverter-based power sources with pulse-MIG waveform control dominate automotive fleet upgrades in Michigan and Bavaria. German and Italian fabrication shops are replacing transformer-based units ahead of EU F-Gas Regulation deadlines, compressing payback periods through energy efficiency gains.
- Welding Consumables:Electrodes, filler wires, and flux-cored products generate recurring revenue streams with higher margin stability than capital equipment. Shipbuilding clusters in Jiangsu and Guangdong provinces drive volume through infrastructure programs, while REACH nickel and cobalt restrictions force hardfacing reformulation for North Sea oil and gas contractors.
- Welding Accessories:Torches, cables, and regulators face price pressure from commoditized Asian manufacturing.
- Safety Equipment:Powered air-purifying respirators and fume extraction arms gain share as OSHA hexavalent chromium enforcement tightens across US fabrication yards.
The dominant share belongs to Welding Consumables, while Welding Machines is closing the gap fastest through equipment-as-a-service contract expansion.
Technology:
Process selection hinges on heat-affected zone requirements, material thickness, and operator certification availability, with automation readiness increasingly filtering technology choice.
- MIG:Metal inert gas systems deliver speed and operator efficiency for high-volume automotive body-in-white production. Pulse-MIG adoption accelerates in Guanajuato and Puebla as Mexican OEMs consolidate welding cell procurement into multi-year fleet contracts.
- TIG:Tungsten inert gas welding commands premium positioning in aerospace precision work where arc stability determines quality grades. Over 80% of global tungsten ore processing concentrates in China, creating chokepoint risk for electrode availability and pricing volatility.
- Stick:Shielded metal arc welding retains share in field construction and repair applications with limited power infrastructure.
- Plasma Arc:Concentrated heat input enables thin-material fabrication below 1.2mm thickness where porosity control blocks full laser substitution.
MIG retains the largest installed base, though Plasma Arc is expanding most quickly in battery tray and electronics enclosure applications.
End User:
Vertical-specific quality certifications and production scale separate price-sensitive construction procurement from aerospace's zero-defect tolerance.
- Automotive:E-mobility manufacturers in China and Mexico are installing laser-hybrid systems for aluminum structural bonding at unprecedented scale. Battery tray welding demands arc stability algorithms that Fronius and Lincoln Electric are embedding into power source firmware.
- Aerospace:Precision TIG requirements and NADCAP certification barriers sustain premium equipment pricing. AWS and IIW qualification pipelines are failing to replenish retiring skilled labor, compressing available contractor capacity.
- Manufacturing:General fabrication spans MIG-dominant volume production and specialty repair work with mixed automation levels.
- Construction:Field portability and generator compatibility favor stick welding in infrastructure and commercial building frameworks.
Automotive commands the highest equipment revenue per welding station, while Construction generates the largest consumables volume through maintenance intensity.
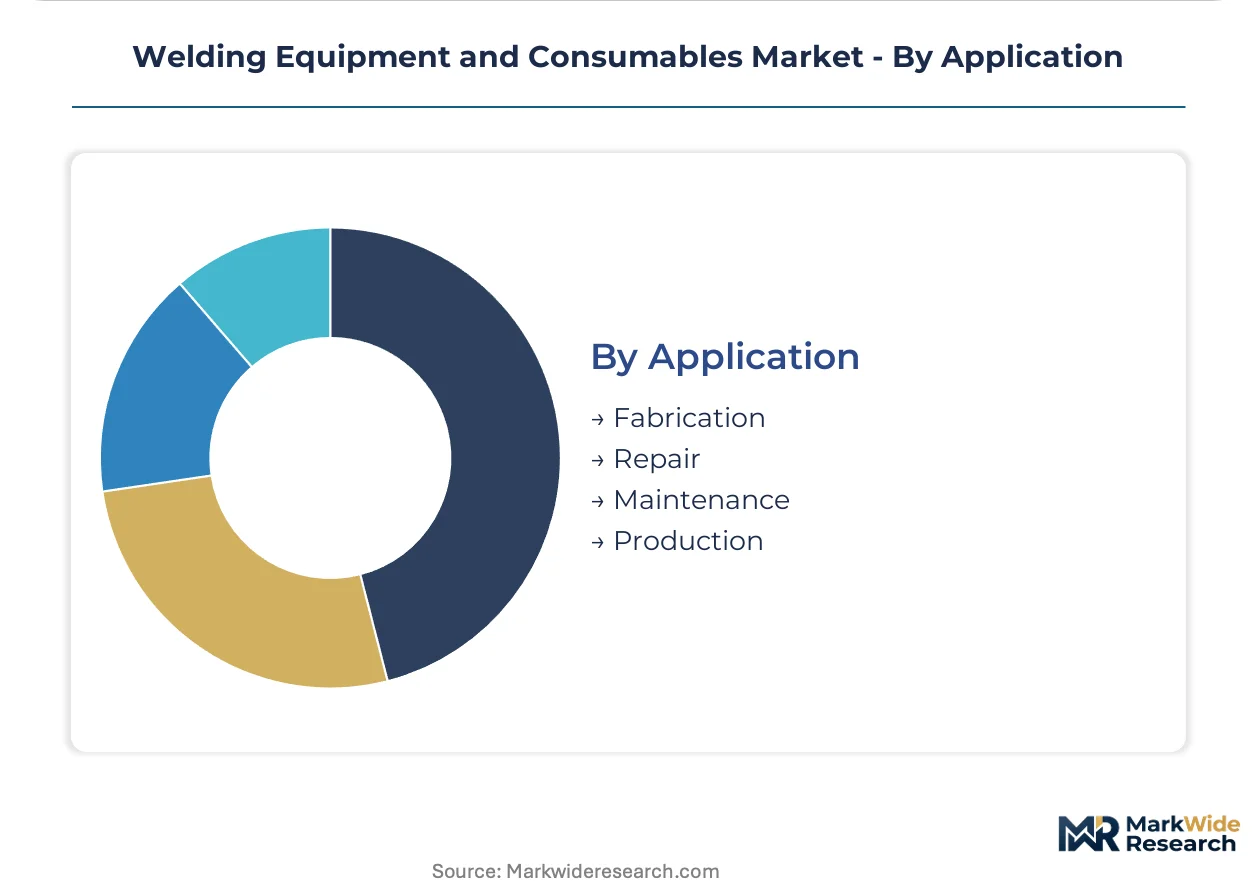
Application:
Workflow economics separate continuous production environments from intermittent repair cycles, with data collection requirements diverging sharply.
- Production:Continuous manufacturing lines in automotive and shipbuilding demand predictive maintenance contracts and machine vision integration. AI-driven weld monitoring enables per-meter-welded pricing models with software-defined arc control as the primary differentiation vector.
- Fabrication:Job shop environments balance setup flexibility against throughput targets, with pulse-MIG systems reducing defect rates below 0.3% in high-volume lines.
- Repair:Field service work prioritizes equipment portability and rapid parameter adjustment over automation integration.
- Maintenance:Scheduled downtime windows in process industries create demand for hardfacing consumables and submerged arc systems in power generation and mining equipment.
Production absorbs the majority of capital equipment investment, yet Fabrication is gaining share fastest through contract manufacturing expansion in Eastern Europe and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial policy incentives are redirecting welding equipment procurement toward subsidized manufacturing zones. China's coastal provinces anchor consumables volume through shipbuilding programs. German and Italian fabrication shops face compressed upgrade timelines under EU F-Gas Regulation mandates.
China
Jiangsu and Guangdong provinces drive consumables demand through infrastructure and vessel construction programs. MEE enforcement of GB standards tightens local production quality thresholds, raising barriers for imported equipment without localized certification. Yangtze River Delta shipyards are installing automated welding cells at unprecedented density for commercial vessel output.
Germany
Bavarian automotive Tier-1 suppliers are completing fleet conversions to pulse-MIG systems ahead of EU F-Gas Regulation deadlines. The regulation mandates lower-GWP shielding gas blends, accelerating inverter power source upgrades across German fabrication shops. Munich and Stuttgart industrial corridors concentrate laser-hybrid system deployment for e-mobility battery tray assembly.
United States
Michigan automotive plants are consolidating welding cell procurement into multi-year fleet contracts with captive financing programs. OSHA exposure limits for hexavalent chromium and manganese fumes directly shape consumable formulation R&D budgets across US-based manufacturers. Detroit-area OEMs prefer operational expenditure classification for balance sheet optimization through equipment-as-a-service contracts.
Mexico
Guanajuato and Puebla automotive suppliers are installing laser-hybrid systems for aluminum structural bonding at scale. OEMs in these states prefer per-meter-welded pricing models to optimize balance sheet treatment of welding expenditures. Mexican robotic welding line expansion concentrates in export-oriented assembly corridors serving North American vehicle markets.
India
Maharashtra and Gujarat fabrication shops are capturing PLI scheme incentives for localized welding equipment manufacturing. The scheme opens captive supply arrangements for multinational consumables producers establishing domestic production. Pune and Ahmedabad industrial belts are scaling MIG-dominant volume production for contract manufacturing expansion.
Welding Equipment and Consumables Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base separates into capital-rich fleet financiers, consumables-integrated manufacturers, and precision-system technologists. Strategic archetypes include backward-integrated filler metal producers, software-defined arc control specialists, and per-unit pricing service providers. Dominant competitive moves encompass captive financing program expansion and consumables reformulation for multi-jurisdiction compliance.
Within the precision-system tier, Fronius International and Kemppi Oy. exemplify technology-differentiated positioning through arc stability specialization. ESAB occupies a position representing backward-integrated consumables control, while Lincoln Electric anchors the capital-deployment archetype with fleet financing dominance. Panasonic Industry Co., Ltd. and OTC DAIHEN Inc. sit within the automation-integrated tier serving high-volume Asian manufacturing corridors. These groupings reflect how competitive advantage concentrates in either consumables margin stability, equipment financing scale, or waveform control precision rather than undifferentiated hardware distribution.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Panasonic Industry Co., Ltd. |
| Lincoln Electric |
| Voestalpine Bohler Welding Group GmbH |
| OTC DAIHEN Inc. |
| ESAB |
| Fronius International |
| Kemppi Oy. |
| Miller Electric |
| Others |
Supply Flow & Price Mechanics
Over 80% of global tungsten ore processing concentrates in China, anchoring electrode pricing volatility and pushing margin pools toward consumables-integrated suppliers who control upstream filler metal production. This concentration forces buyers into long-term offtake arrangements or captive supply deals to stabilize input costs.
Pricing Analysis
Certification level (ISO/CE-grade) creates the primary spread between premium and standard equipment tiers. Equipment-as-a-service contracts with per-meter-welded pricing are displacing outright purchase in capital-constrained fabrication shops. Cost compression in standard inverter power sources intensifies as Chinese manufacturers scale pulse-MIG production. Automotive OEMs consolidating fleet procurement show lowest price sensitivity, while job shop fabricators exhibit highest sensitivity to consumables unit costs.
Supply Chain Analysis
Extended payment terms from Lincoln Electric and Fronius are reshaping supplier-buyer power dynamics across Mexican and Eastern European automotive corridors. Tungsten electrode supply draws from China, with secondary processing in Vietnam and Austria. Copper and lithium price volatility erodes consumables margin predictability. Distribution runs through authorized distributor networks with regional service depots for spare parts and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software and consumables subscription layers are expanding faster than hardware sales, making service-attach revenue the critical value capture mechanism for welding equipment portfolios.
For Market Incumbents: Pre-empt consumables margin erosion by securing captive tungsten supply through offtake agreements with Chinese processors. Accelerate equipment-as-a-service contract penetration in Guanajuato and Puebla to lock out emerging Asian competitors before fleet procurement consolidates further. For New Entrants and Emerging Players: India's PLI scheme for auto components represents the most penetrable entry point for localized welding equipment manufacturing. Contract manufacturing expansion in Maharashtra and Gujarat offers white-space demand for mid-tier pulse-MIG systems. Partner with established consumables distributors to bypass direct sales infrastructure buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed consumables producers lacking software-defined arc control capabilities. Five-to-ten year viability hinges on recurring revenue mix exceeding hardware dependency. Monitor OSHA hexavalent chromium enforcement intensity as signal for consumables reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Metals | Captive electrode production insulates ESAB and Voestalpine from tungsten price volatility. |
| Equipment-as-a-Service Expansion | Per-meter-welded contracts in Mexico optimize balance sheet treatment for automotive suppliers. |
| Laser-Hybrid System Development | Fronius battery tray specialization commands premium positioning in e-mobility manufacturing. |
| AI-Driven Weld Monitoring Integration | Machine vision partnerships create predictive maintenance recurring revenue beyond hardware sales. |
| Multi-Jurisdiction Certification Investment | Parallel OSHA, REACH, and GB standard compliance secures access to US, EU, and Chinese markets. |
Methodological Framework
A spread of perspectives from welding equipment procurement managers, aftermarket service directors, consumables R&D leads, and fabrication shop plant engineers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from SEC filings of listed industrial equipment manufacturers, customs trade data on tungsten and copper wire imports, and OSHA enforcement action databases. Bottom-up welding cell deployment counts across automotive facilities triangulated against top-down consumables volume estimates from distributor channel checks.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions encompassed product type (equipment versus consumables), technology (MIG, TIG, plasma arc), end user vertical (automotive, aerospace, shipbuilding), and application workflow (production, fabrication, repair). CAGRs derived from fitted growth curves applied to base-year equipment installation data and consumables consumption intensity ratios. Battery tray welding demand and EU F-Gas Regulation compliance timelines served as industry-specific forecast inputs.
Practitioners should monitor tungsten supply chain disruption, REACH substance restriction expansion, and automotive OEM fleet procurement consolidation for early signals requiring forecast adjustment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dozer Tire Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Winch Market
Construction Equipment
US Rental Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Mortar Testing Equipment Market