
 Wood Chipping Machinery Market | 2026-2036
Wood Chipping Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Chipping Machinery Market Analytics
ISO 9001 certification is unwinding as a baseline qualifier for OEMs bidding on municipal and utility-scale chipper contracts. Bandit Industries leverages in-house manufacturing of disc chipper drums to control lead times and aftermarket parts availability. Vermeer anchors its position through a dense North American dealer network that sustains service revenue across the machine lifecycle. Morbark competes on raw throughput metrics, specializing in high-capacity drum configurations for biomass terminals.
Wood chipping machinery encompasses stationary and mobile systems that reduce logs, branches, and wood waste into uniform chips through mechanical cutting action, typically employing rotating drums or discs with hardened steel knives operating at 1,000–2,200 RPM for dimensional consistency. These machines serve biomass fuel preparation, pulp and paper feedstock supply, and land clearing operations where particle size distribution determines downstream processing efficiency. Drum chippers dominate industrial biomass applications where throughput rates above 100 tons per hour command premium pricing and long order backlogs. Disc chippers lead in forestry contracting segments requiring portability and rapid setup on uneven terrain. Electric technology installations are accelerating at fixed-site pellet mills where grid connectivity and carbon accounting favor zero-direct-emission operation over diesel alternatives.
EPA Tier 4 Final and Stage V emission frameworks from the European Commission are elevating aftertreatment costs and compressing margins on diesel-powered mobile chipper models. OSHA machine guarding standards and CE marking requirements under the EU Machinery Directive shape design priorities for feed table dimensions, emergency stop placement, and operator visibility. Stakeholders must weigh electrification roadmaps against residual value risks in diesel fleets as carbon border adjustments and renewable fuel credit programs reshape total cost of ownership calculations.
Market Dynamics
Electrification pressure from decarbonization mandates is compressing diesel chipper residual values while forcing OEMs to split R&D budgets across parallel powertrain development tracks. Biomass utilities now specify carbon intensity thresholds in procurement tenders, shifting competitive advantage toward manufacturers with certified low-emission product lines.
Growth Catalysts
- EU Green Deal biomass targets:Member state renewable heat obligations are accelerating pellet plant capacity additions in Germany, Poland, and the Baltic states, driving drum chipper fleet procurement for feedstock preparation.
- Land clearing contractors:Wildfire mitigation budgets across California, Australia, and Mediterranean Europe are expanding mechanical vegetation management contracts, favoring portable disc chipper deployments on steep terrain.
- Hardened alloy knife metallurgy:Extended wear life between sharpenings is reducing downtime costs for high-throughput biomass terminals operating on thin margin structures.
Market Restraints
- EPA Tier 4 Final aftertreatment costs:Diesel particulate filters and selective catalytic reduction systems are adding fifteen to twenty percent to mobile chipper bill-of-materials, eroding manufacturer margins on mid-size units.
- Specialized foundry concentration:Precision castings for chipper drums and flywheels concentrate among German and Japanese suppliers, exposing lead time vulnerability to energy price shocks.
- Electrification infrastructure gaps:Rural pellet mill sites in Brazil and Southeast Asia lack grid capacity for fixed-site electric chippers, delaying technology transition timelines.
Strategic Opportunities
- Indonesia palm oil waste valorization:Empty fruit bunch and trunk biomass remains underutilized for pellet export, creating first-mover openings for chipper OEMs with tropical corrosion-resistant designs.
- US Inflation Reduction Act clean fuel credits:Renewable biomass electricity generation qualifies for production tax credits, incentivizing chipper investment for dedicated energy crop processing.
- Predictive maintenance sensor integration:Vibration monitoring and knife-wear algorithms bundled with equipment finance packages are creating recurring revenue streams distinct from traditional parts sales.
Industry Challenges
- Certified service technician scarcity:EPA and Stage V aftertreatment diagnostics require specialized training that dealer networks struggle to staff in remote forestry regions.
- Legacy fleet retrofit complexity:Tier 3 diesel chipper owners face stranded asset risk as carbon border adjustments in the EU and UK penalize high-emission biomass supply chains.
Report Scope
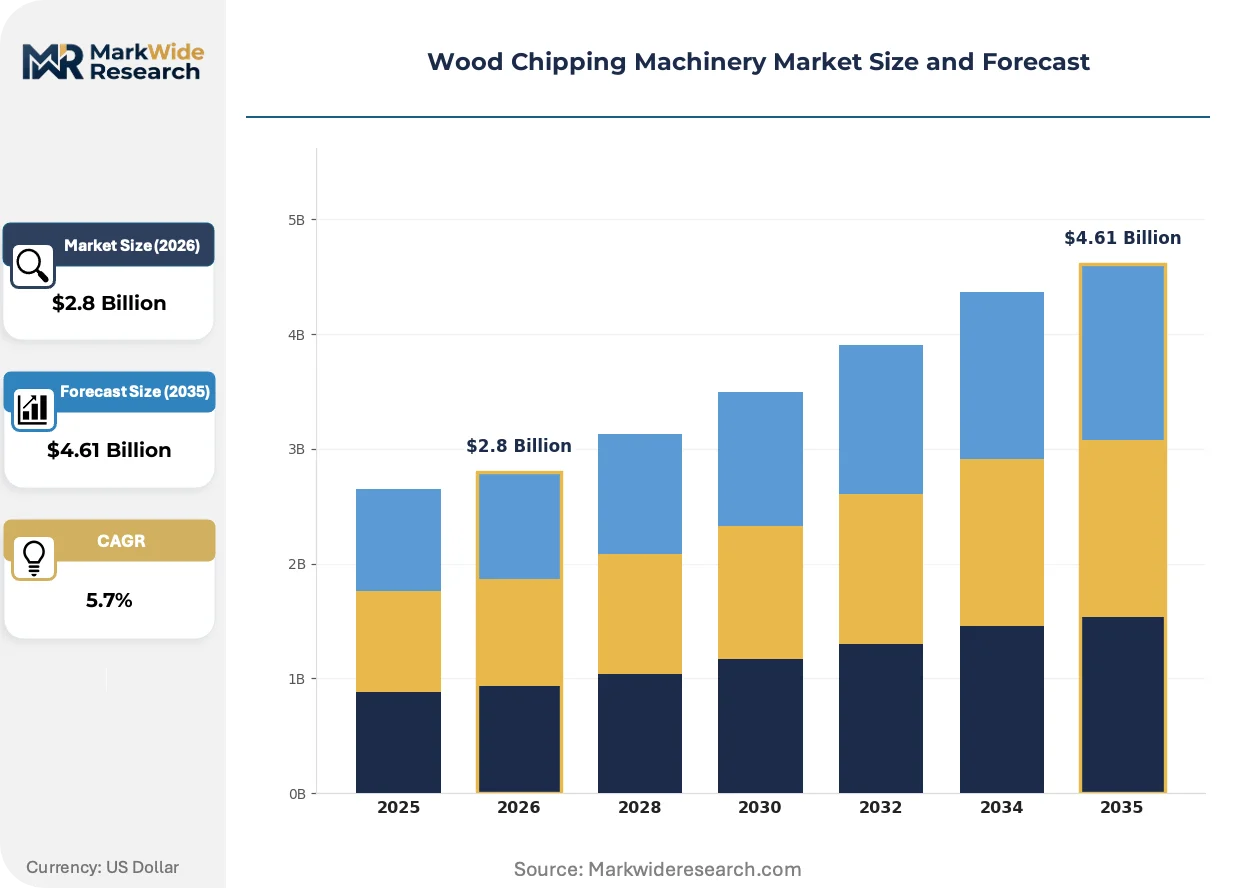
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Chipping Machinery Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Chippers, Disc Chippers, Knife Chippers, Flail Chippers End User: Forestry, Landscaping, Recycling, Construction Technology: Hydraulic, Electric, Diesel, Gasoline Application: Wood Waste Reduction, Biomass Production, Land Clearing, Mulching |
| Companies Covered | Terex, Bandit Industries, Vermeer, Morbark, Peterson, J.P. Carlton, MTD Products, ECHO Bear Cat, Bruks Siwertell Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Chipping Machinery Market Evolving Landscape
Digitalization and powertrain diversification are fragmenting traditional equipment categories, creating new competitive battlegrounds around data ownership and energy flexibility rather than raw throughput specifications alone.
Modular electric powerpacks for mobile chippers is miniaturizing battery and motor assemblies to fit existing chassis footprints without sacrificing chip quality. Pellet producers with grid access are piloting these systems in Germany and the Pacific Northwest, compressing the total cost gap against diesel alternatives to under three years at current carbon credit valuations.
REACH chemical restrictions on lubricants and hydraulic fluids are forcing reformulation of biodegradable oils for forestry machinery operating near watercourses. Chipper OEMs serving Nordic and Alpine markets are redesigning seal systems and tank materials to accommodate higher-viscosity bio-based alternatives, adding six to nine months to product validation cycles.
Biomass procurement teams are consolidating vendor relationships from equipment-only transactions to full-service throughput contracts. Pellet mill operators in the US Southeast and British Columbia now specify guaranteed tons-per-hour minimums with penalty clauses, transferring operational risk to manufacturers while locking in multi-year service revenue streams.
Wood Chipping Machinery Market Segmentation
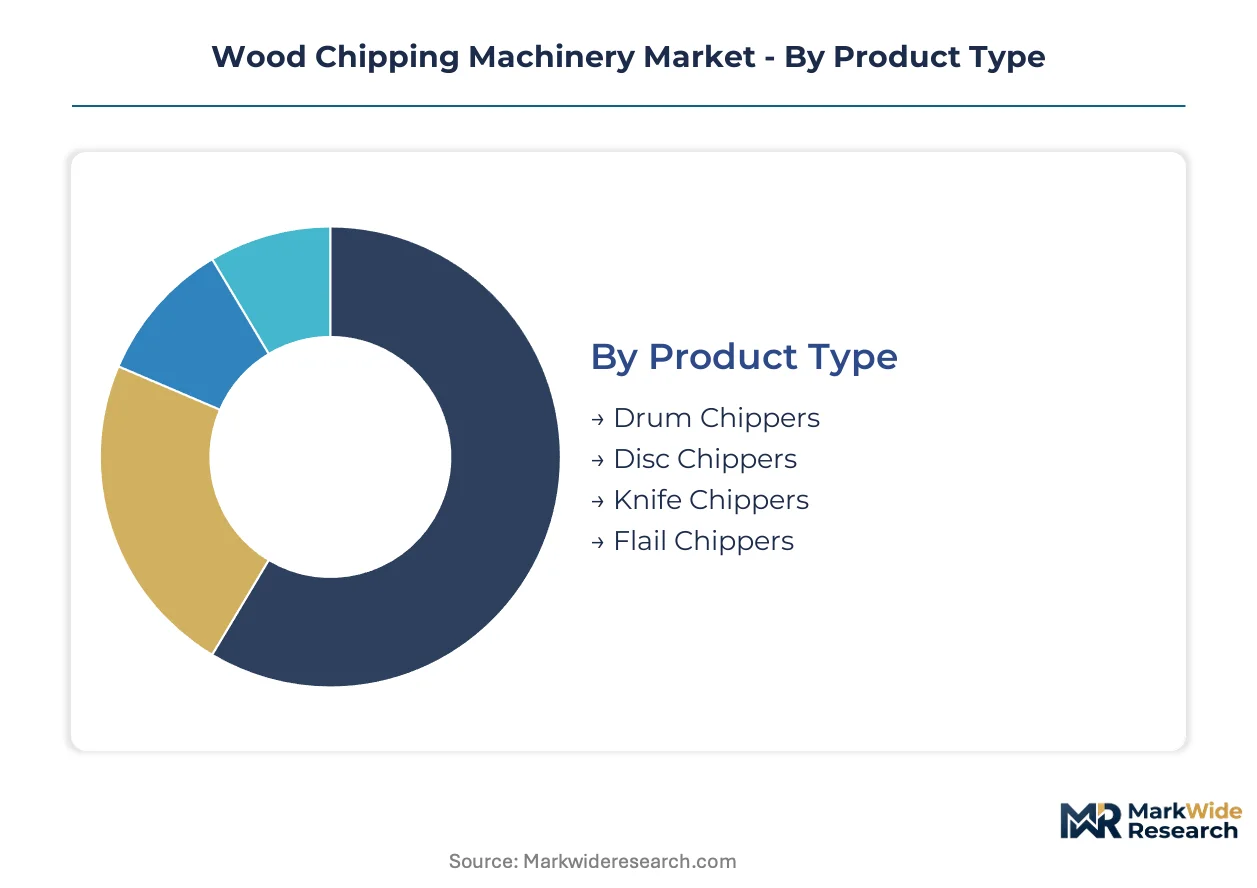
Segmentation in wood chipping machinery reveals divergent channel strategies across powertrain technologies and end-use applications. Procurement patterns vary sharply between fixed-site pellet mills sourcing through direct OEM relationships and forestry contractors purchasing via dealer networks for portable equipment.
Product Type:
Channel distribution splits between industrial biomass terminals procuring high-capacity units directly from manufacturers and landscaping contractors acquiring portable models through regional equipment dealers.
- Drum Chippers:Rotating cylindrical drums with parallel-mounted knives process logs at 1,000–2,200 RPM, achieving throughput rates above 100 tons per hour. Demand concentrates in Germany, Poland, and the Baltic states where EU Green Deal biomass targets are accelerating pellet plant capacity additions and fleet procurement for feedstock preparation. Drum configurations command premium pricing and extended order backlogs due to dimensional consistency requirements for utility-scale biomass combustion.
- Disc Chippers:High-speed rotating discs with radial-mounted knives excel in forestry contracting segments requiring rapid deployment on uneven terrain. California, Australia, and Mediterranean Europe are expanding mechanical vegetation management contracts for wildfire mitigation, favoring portable disc chipper acquisitions through dealer networks serving land clearing contractors operating on steep slopes.
- Knife Chippers:Specialized cutting heads with adjustable blade angles serve niche applications in urban tree maintenance and small-scale biomass processing.
- Flail Chippers:Hammer-mill style flails reduce brush and small-diameter material for mulch production and soil conditioning applications.
By volume, drum chippers lead industrial procurement. By growth pace, disc chippers are expanding most quickly in wildfire mitigation contracting.
End User:
Cost tier stratification separates capital-intensive biomass utilities from price-sensitive landscaping operators and mid-tier recycling processors.
- Forestry:Large-scale timber harvesting and forest management operations require high-throughput chippers integrated with forwarder and harvester fleets. Procurement specifications emphasize uptime guarantees and aftermarket parts availability through dense service networks.
- Landscaping:Municipal parks departments and commercial grounds maintenance contractors favor compact, towable units with rapid setup times. Equipment financing packages and seasonal rental options dominate this price-sensitive segment.
- Recycling:Wood waste processors serving construction demolition and pallet recovery operations prioritize versatility across feedstock types. Knife-wear algorithms and predictive maintenance sensors are creating recurring revenue streams distinct from traditional parts sales in this segment.
- Construction:Site clearing and land development contractors demand ruggedized chassis configurations for abrasive operating conditions.
Forestry commands the highest average transaction values. Landscaping shows the steepest expansion trajectory in unit shipments.
Technology:
Application context determines powertrain selection, with grid-connected pellet mills and remote forestry sites following divergent electrification timelines.
- Hydraulic:Proportional valve systems deliver precise feed control for variable-density material streams. Hydraulic configurations dominate mid-size mobile chippers where torque management and overload protection are critical.
- Electric:Grid-connected fixed-site installations at pellet mills in Germany and the Pacific Northwest are piloting modular powerpacks, compressing total cost gaps against diesel alternatives to under three years at current carbon credit valuations. EPA Tier 4 Final aftertreatment costs are accelerating interest in zero-direct-emission alternatives where infrastructure permits.
- Diesel:Stage V and EPA emission frameworks are elevating aftertreatment costs and compressing margins on mobile models, eroding manufacturer margins on mid-size units by fifteen to twenty percent.
- Gasoline:Compact single-operator units serve residential and light commercial landscaping with lower capital barriers.
Electric technology is gaining share fastest in fixed-site applications. Diesel retains dominance in remote mobile deployments.
Application:
Customer type segmentation separates utility-scale biomass producers with long-term throughput contracts from spot-market land clearing operators.
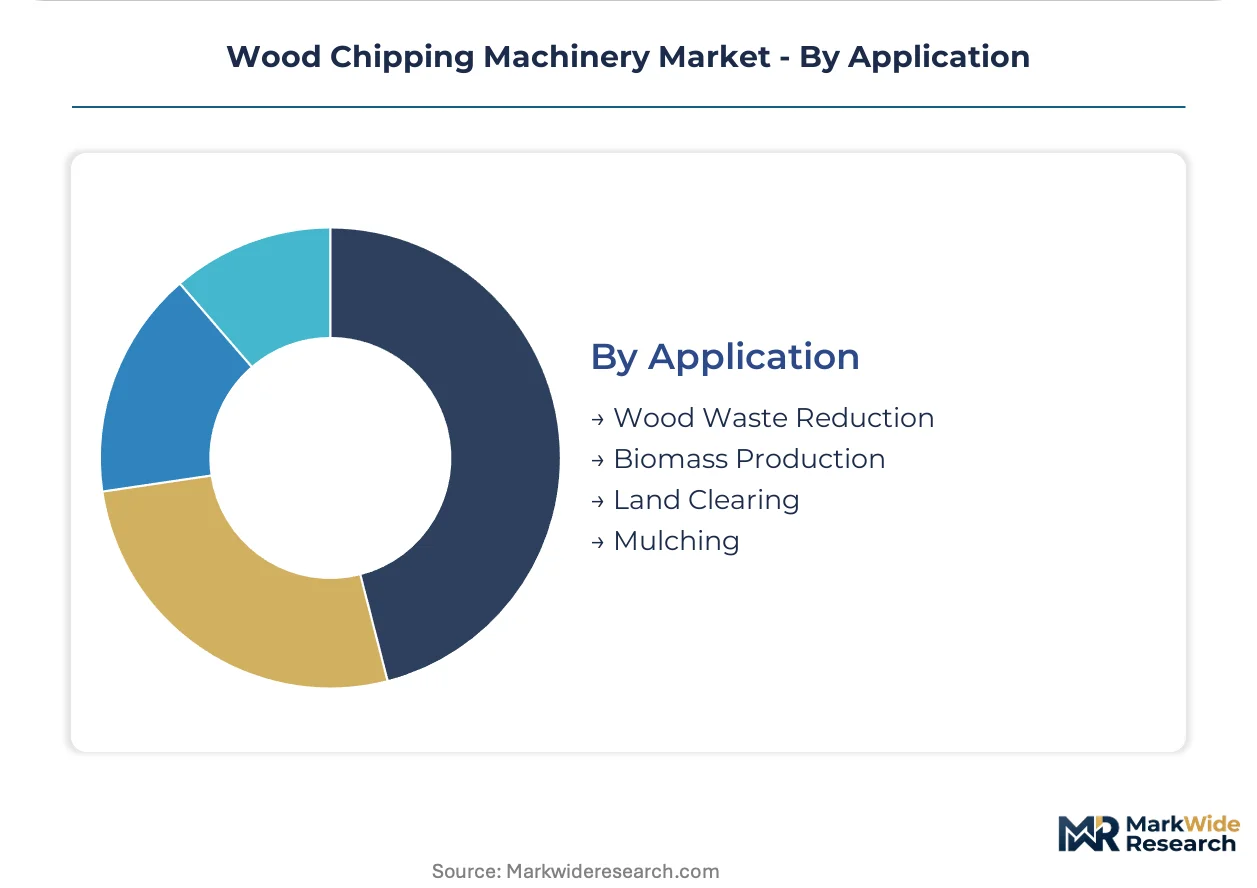
- Wood Waste Reduction:Construction and demolition debris processing, pallet recycling, and municipal green waste programs require contamination-tolerant feeding systems. REACH chemical restrictions on lubricants are forcing reformulation of biodegradable oils for machinery operating near watercourses.
- Biomass Production:Pellet mill operators in the US Southeast and British Columbia now specify guaranteed tons-per-hour minimums with penalty clauses, transferring operational risk to manufacturers while locking in multi-year service revenue streams.
- Land Clearing:Utility right-of-way maintenance and firebreak construction demand all-terrain mobility and rapid relocation capabilities.
- Mulching:Soil conditioning and erosion control applications favor fine particle output specifications for agricultural and revegetation projects.
Biomass production generates the highest equipment revenue per installation. Land clearing shows the fastest order growth in wildfire-prone jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal biomass targets and US Inflation Reduction Act clean fuel credits are redirecting capital toward pellet export infrastructure and utility-scale feedstock preparation. Procurement concentrates where decarbonization policies intersect with established forestry equipment ecosystems.
United States
Wildfire mitigation budgets across California and the Pacific Northwest are expanding mechanical vegetation management contracts for land clearing contractors. EPA Tier 4 Final emission standards are elevating aftertreatment costs on diesel-powered mobile chippers by fifteen to twenty percent. Pellet mill operators in the US Southeast now specify guaranteed tons-per-hour minimums with penalty clauses, transferring operational risk to manufacturers.
Germany
Member state renewable heat obligations are accelerating pellet plant capacity additions in Germany and neighboring Baltic states. EU F-Gas Regulation and Stage V emission frameworks from the European Commission are compressing margins on diesel-powered units. Industrial biomass terminals in Lower Saxony and Bavaria command premium pricing for drum chipper fleets achieving throughput rates above 100 tons per hour.
Brazil
Land clearing contracts for agricultural expansion and eucalyptus plantation management sustain demand for portable disc chipper deployments. Rural pellet mill sites lack grid capacity for fixed-site electric chippers, delaying technology transition timelines. São Paulo and Minas Gerais harbor the primary equipment dealer networks serving forestry contractors operating on uneven terrain.
Poland
EU Green Deal biomass targets are driving drum chipper fleet procurement for feedstock preparation at new pellet plant installations. REACH chemical restrictions on lubricants are forcing reformulation of biodegradable oils for machinery operating near watercourses. Industrial clusters in Silesia and Greater Poland are consolidating vendor relationships toward full-service throughput contracts with guaranteed minimums.
Australia
Mechanical vegetation management contracts for wildfire mitigation are expanding across New South Wales and Victoria. OSHA-aligned machine guarding standards shape design priorities for feed table dimensions and emergency stop placement. Biomass procurement teams in southeastern timber regions are piloting modular electric powerpacks where grid connectivity permits.
Wood Chipping Machinery Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and service network density. The vendor base splits between consolidated OEMs with integrated manufacturing and fragmented regional fabricators serving price-sensitive landscaping segments. Three archetypes dominate: throughput-maximizing biomass terminal specialists, portability-optimizing forestry contractors, and electrification-focused pellet mill suppliers. M&A activity targets aftermarket service capabilities, while geographic expansion concentrates on Southeast Asian palm oil waste valorization opportunities.
Among North American manufacturers, Terex, Bandit Industries, and Vermeer occupy distinct competitive positions. Terex represents the diversified industrial equipment archetype with cross-segment technology leverage. Bandit Industries exemplifies the in-house manufacturing specialist controlling lead times through captive production of critical components. Vermeer anchors the dealer-network-dependent tier, sustaining service revenue across equipment lifecycles through dense North American coverage. These three collectively illustrate the segmentation between scale-driven consolidation and specialization strategies.
| Leading Market Players |
|---|
| Terex |
| Bandit Industries |
| Vermeer |
| Morbark |
| Peterson |
| J.P. Carlton |
| MTD Products |
| ECHO Bear Cat |
| Bruks Siwertell Group |
| Others |
Value Network & Pricing Analysis
Twelve-to-eighteen-month lead times for precision-cast chipper drums from German and Japanese foundries concentrate pricing power with upstream suppliers, forcing OEMs to absorb margin compression or push cost increases toward biomass terminal operators with long-term throughput contracts. This inventory-to-pricing feedback loop intensifies as EPA Tier 4 Final and Stage V aftertreatment costs layer additional fifteen-to-twenty-percent bill-of-materials pressure onto diesel-powered mobile units.
Pricing Analysis
Certification level (ISO 9001 baseline versus CE-marked premium tiers) creates the primary spread across municipal and utility-scale procurement, with guaranteed uptime clauses and predictive maintenance sensor bundles commanding fifteen-to-twenty-five-percent premiums over equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service intensity, with forestry contractors in wildfire mitigation segments showing highest price sensitivity due to seasonal utilization patterns. Pricing pressure stems from electrification R&D splits compressing diesel fleet residual values, while pellet mill operators with guaranteed tons-per-hour minimums demonstrate lowest sensitivity to upfront capital cost.
Supply Chain Analysis
Rhine River barge congestion and Hamburg port capacity constraints expose just-in-time knife and hydraulic component deliveries to weather-related disruption, amplifying vulnerability for mid-size OEMs without captive foundry relationships. Precision castings for chipper drums and flywheels concentrate among German and Japanese suppliers, while hardened alloy knife metallurgy draws from Austrian and Swedish specialty steel mills. Single-source vulnerability in precision casting capacity creates structural risk as energy price shocks propagate through foundry energy surcharges. Distribution runs through dense North American dealer networks for portable forestry equipment and direct OEM relationships for fixed-site pellet mill installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance algorithms and guaranteed throughput contracts is expanding faster than hardware sales, repositioning competitive advantage toward manufacturers capable of operational risk transfer rather than equipment specification alone.
For Market Incumbents: Shield installed base relationships by backward integration into precision casting capacity in Lower Saxony or Bavaria, reducing exposure to German foundry lead time volatility. Deepen certification investment in Stage V and EPA Tier 4 Final compliance to maintain municipal contract eligibility as carbon intensity thresholds harden in EU biomass procurement tenders.
For New Entrants and Emerging Players: Lead with corrosion-resistant disc chipper designs targeting Indonesia palm oil waste valorization, where empty fruit bunch and trunk biomass remains underutilized for pellet export. Penetrate through equipment-as-a-service models bundling tropicalized hardware with local technician training partnerships, avoiding capital-intensive dealer network buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents with underoptimized aftermarket service divisions capable of standalone predictive maintenance platform development. Five-to-ten-year viability hinges on electrification roadmap credibility; monitor EU carbon border adjustment implementation as inflection indicator for stranded asset risk in legacy diesel fleet exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive drum and flywheel production insulates Bandit Industries from German foundry energy surcharge volatility. |
| Predictive Maintenance Platform Launch | Vibration monitoring and knife-wear algorithms bundled with finance packages create recurring revenue at biomass terminals. |
| Tropical Corrosion-Resistant Design Program | Specialized coatings and seal systems unlock Indonesia palm oil waste valorization opportunities ahead of pellet export infrastructure buildout. |
| CE Marking and Stage V Compliance Acceleration | Early certification completion secures municipal tender eligibility as EU Green Deal biomass targets tighten emission thresholds. |
| Equipment-as-a-Service Model Pilot | Guaranteed tons-per-hour contracts transfer operational risk to manufacturers while locking multi-year service revenue at US Southeast pellet mills. |
Research Methodology
Operator-level perspectives from maintenance directors at biomass terminals, pellet mill procurement leads, forestry contractor fleet managers, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from EPA enforcement actions, EU ETS transaction registries, customs trade data for chipper drum and knife imports, and SEC filings from listed industrial equipment manufacturers. Bottom-up equipment shipment tallies by powertrain technology and top-down pellet plant capacity expansion pipelines were triangulated to constrain volume estimates.
Sensitivity analysis across carbon credit valuation scenarios, foundry energy price bands, and electrification infrastructure buildout timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type (drum, disc, knife, flail), powertrain technology (diesel, electric, hydraulic, gasoline), end-use application (biomass production, land clearing, wood waste reduction, mulching), and regional regulatory cluster (EPA Tier 4 Final, Stage V, emerging economy baseline). CAGRs derived from equipment replacement cycles, pellet export infrastructure commissioning schedules, and wildfire mitigation budget appropriations trajectories.
Forecasts assume regulatory continuity in EPA emission standards and EU F-Gas Regulation enforcement; material policy shifts including accelerated carbon border adjustments or renewable fuel credit program modifications would require re-modeling. Practitioners should keep alternative scenarios live as grid capacity expansion timelines at rural Brazilian and Southeast Asian pellet mill sites evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Global Welding Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Rotomolding Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
North America: Heavy Construction Equipment Market
Construction Equipment
Pile Cage Welding Machine Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market