
 Electric and Hybrid Construction Equipment Market | 2026-2036
Electric and Hybrid Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric and Hybrid Construction Equipment Market Intelligence
ISO 19453 qualification for electric drivetrain sealing and thermal management is collapsing the supplier base to firms with certified testing infrastructure. Caterpillar leverages its captive battery module assembly to control cost position across the excavator range. Volvo Construction Equipment anchors European demand through its dedicated electric equipment plant in Sweden. Komatsu competes in Japan and Southeast Asia with integrated telematics platforms bundled into machine leases.
Electric and hybrid construction equipment encompasses earthmoving and material-handling machinery propelled by battery-electric, hybrid-electric, or fuel-cell powertrains, with nominal system voltages typically exceeding 600V DC and IP-rated enclosures per IEC 60529 for debris and moisture ingress protection. These machines serve urban construction, tunneling, and waste-management sites where emission restrictions, noise ordinances, or ventilation limits prohibit conventional diesel operation. Excavators and loaders currently lead unit shipments, reflecting concentrated demand from tunneling contractors and demolition specialists working in enclosed or regulated zones. Battery-powered configurations are expanding fastest among rental firms seeking to meet corporate Scope 3 targets without long-term capital commitment. Telematics integration across the power source segments is shifting from aftermarket add-on to factory-standard architecture, reshaping how fleet owners monitor charge cycles and predict maintenance intervals.
EPA Tier 4 Final and Stage V emission rules in North America and Europe are eliminating non-compliant diesel engine options for new equipment below 56kW, directly expanding the addressable market for electric substitutes. China's MIIT dual carbon goals and NMPA battery safety certifications are accelerating domestic OEM development while restricting import access for uncertified foreign brands. India's BIS charging infrastructure standards and PLI scheme for advanced chemistry cell manufacturing are conditioning when local contractors can operationalize electric fleets at scale. Stakeholders must monitor how regulator alignment on battery recycling mandates across these jurisdictions reshapes total cost of ownership calculations and residual value assumptions.
Market Dynamics
Stage V and EPA Tier 4 Final emission thresholds are compressing the viable product pipeline for diesel-dependent OEMs, forcing accelerated electrification roadmaps and supplier recertification investments across the construction equipment value chain.
Growth Catalysts
- Stage V emission thresholds:European regulators eliminated non-compliant diesel engines below 56kW, directly expanding addressable market for battery-electric excavators and hybrid loaders in urban construction zones.
- Tunneling contractors:Enclosed infrastructure projects in Germany, China, and the United States face ventilation limits and noise ordinances that prohibit conventional diesel operation, concentrating fleet electrification demand.
- ISO 19453 qualification:Standardized testing infrastructure for electric drivetrain sealing and thermal management is collapsing the supplier base to certified firms, accelerating quality convergence.
Market Restraints
- Battery cell supply concentration:Advanced chemistry cell manufacturing clusters in China create import dependency risks for European and North American OEMs assembling modules locally.
- Charging infrastructure gaps:India's BIS charging standards and uneven grid capacity at construction sites delay operationalization of electric fleets outside megacity transit corridors.
- Residual value uncertainty:Absence of standardized battery health certification protocols depresses secondary market liquidity for used electric equipment.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for domestic advanced chemistry cell manufacturing will localize supply chains and reduce landed cost for contractors in Mumbai and Delhi infrastructure corridors.
- Rental channel expansion:Battery-powered configurations are expanding fastest among rental firms seeking to meet corporate Scope 3 targets without long-term capital commitment.
- Telematics-platform bundling:Integrated machine lease offerings combining equipment, charging infrastructure, and predictive maintenance reshape customer lifetime value calculations.
Industry Challenges
- ISO 19453 certification timeline:Extended validation cycles for electric drivetrain sealing and thermal management delay product launches and compress revenue recognition windows.
- High-voltage technician scarcity:Nominal system voltages exceeding 600V DC require specialized training programs that construction equipment dealers have not yet scaled.
- Legacy fleet integration:Mixed diesel-electric job sites create operational complexity for charge scheduling, maintenance protocols, and operator certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric and Hybrid Construction Equipment Market |
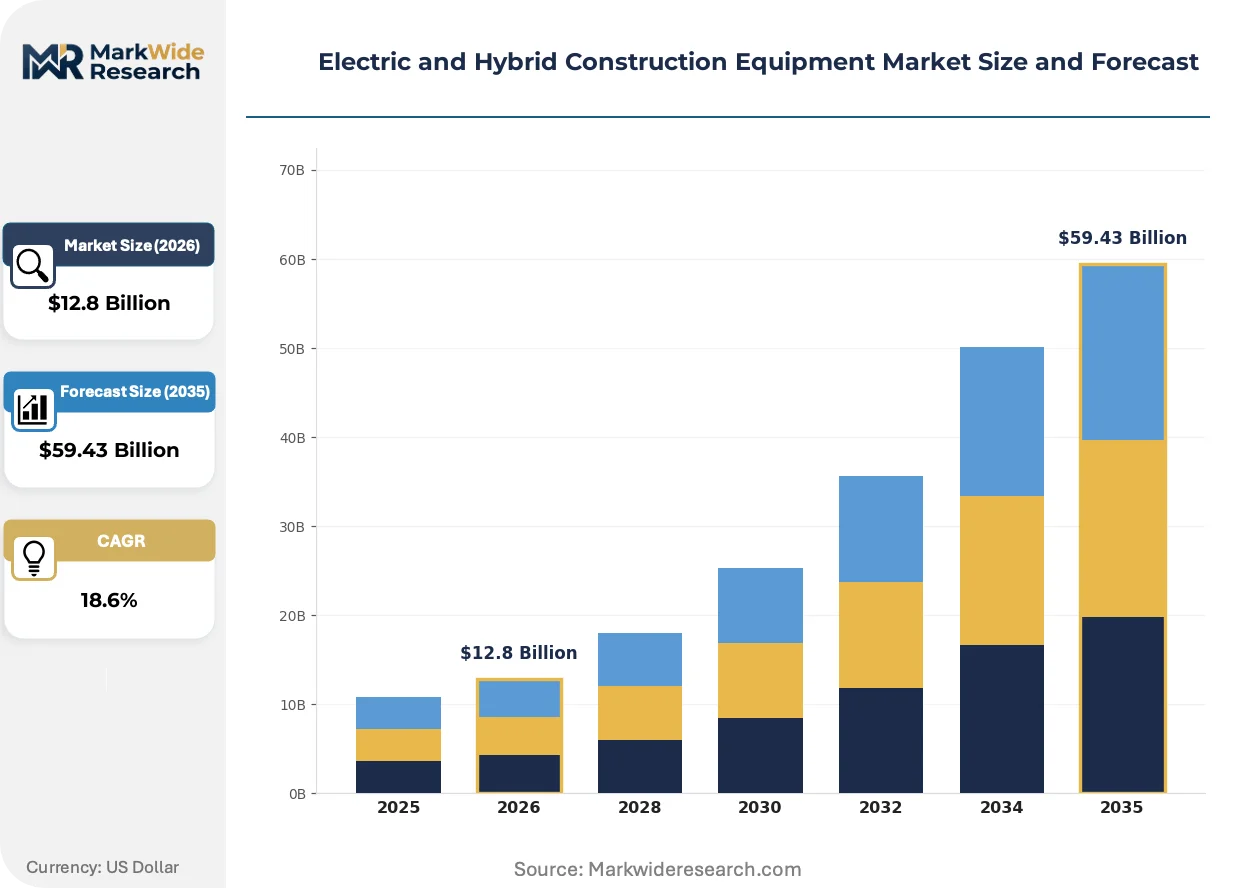
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $59.43 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Dump Trucks, Forklifts Power Source: Battery, Hybrid, Fuel Cell, Plug-in Hybrid End User: Contractors, Construction Companies, Rental Firms, Government Technology: Telematics, Automation, IoT, Advanced Propulsion |
| Companies Covered | Caterpillar, Volvo Construction Equipment, Komatsu, Hitachi Construction Machinery, Liebherr, John Deere, Doosan Infracore, JCB, Kubota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric and Hybrid Construction Equipment Market Strategic Shifts & Innovations
Telematics integration across power source segments is shifting from aftermarket add-on to factory-standard architecture, reshaping how fleet owners monitor charge cycles and predict maintenance intervals.
Solid-state battery prototyping is fragmenting the competitive landscape for high-duty-cycle applications. Underground mining contractors in Canada and Australia are piloting early configurations for continuous operation in ventilation-restricted shafts. This chemistry is fragmenting incumbent lithium-ion supply agreements and forcing cell suppliers to renegotiate volume commitments.
EPA Tier 4 Final enforcement in the United States eliminated grandfathering provisions for diesel engines below 56kW starting January 2024. Equipment dealers in California and Texas report accelerated trade-in activity for electric substitutes. Compact excavator segments show the fastest compliance-driven substitution rates.
Rental firms are consolidating procurement decisions at the corporate level rather than delegating to regional branches. National accounts teams at major lessors now specify electrification targets that override site-level preferences. This concentration is most visible in Germany and the United Kingdom where tunneling contractors face synchronized emission mandates across municipal jurisdictions.
Electric and Hybrid Construction Equipment Market Segmentation
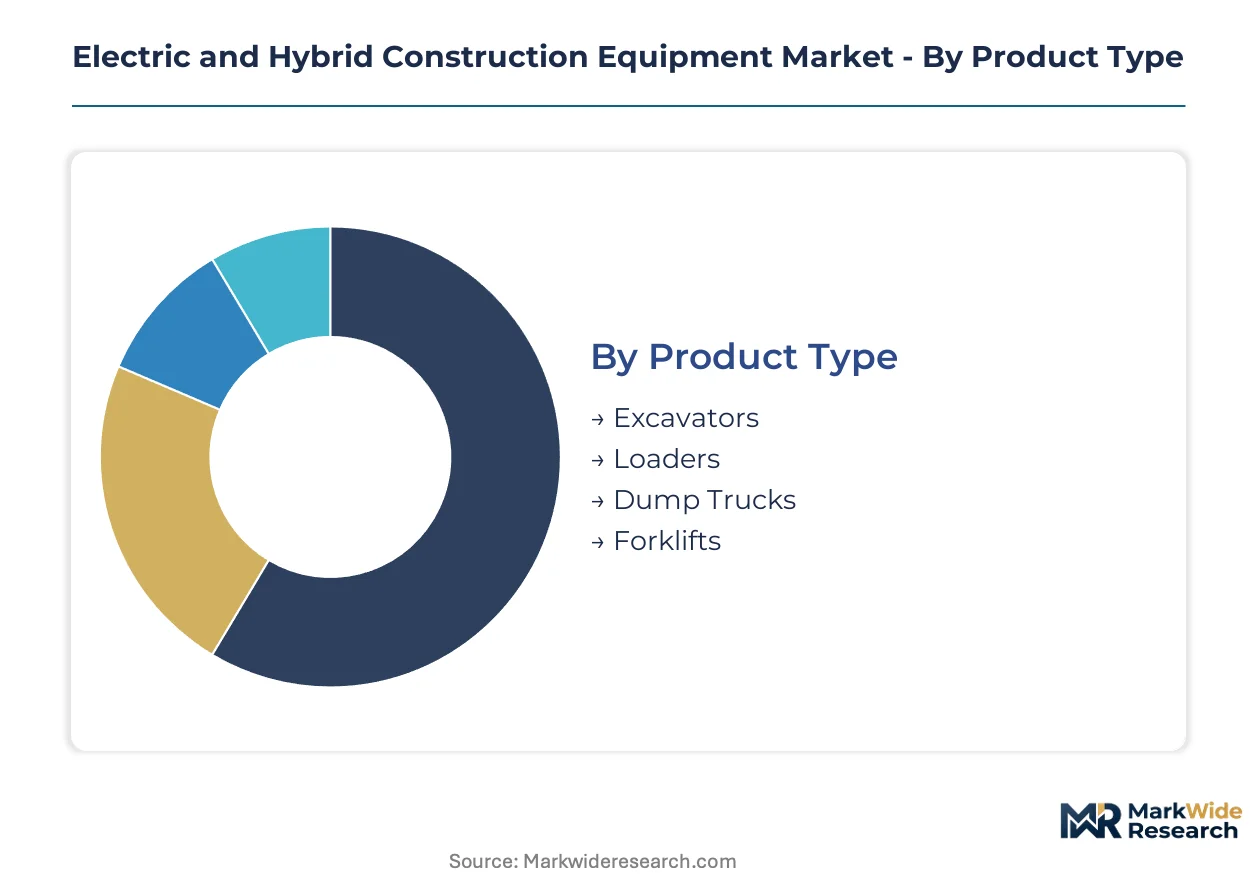
Segmentation in electric and hybrid construction equipment reveals how procurement authority, operational constraints, and powertrain specifications channel demand toward distinct product configurations. Understanding these divisions clarifies where rental firms concentrate fleet investments versus where owner-operators favor outright purchase.
Product Type:
Rental channels favor compact excavators and wheel loaders for urban job sites, while direct sales dominate heavy-duty dump trucks serving mining and tunneling contractors.
- Excavators:Battery-electric variants with nominal system voltages exceeding 600V DC and IP-rated enclosures per IEC 60529 serve tunneling contractors in Germany and China facing ventilation limits. EPA Tier 4 Final enforcement below 56kW has compressed the diesel alternative pipeline, accelerating substitution rates in compact segments.
- Loaders:Hybrid-electric wheel loaders integrate regenerative braking for material-handling cycles in enclosed waste-management sites. Demand concentrates with demolition specialists in the United States and United Kingdom where noise ordinances prohibit overnight diesel operation.
- Dump Trucks:Articulated haulers with fuel-cell prototyping serve continuous-duty mining applications in ventilation-restricted Canadian and Australian shafts.
- Forklifts:Battery-powered configurations dominate warehouse-adjacent construction logistics, with telematics integration shifting from aftermarket add-on to factory-standard architecture.
Excavators dominate installed base. Loaders represent where expansion concentrates most steeply.
Power Source:
Cost tiering separates premium battery systems from economy hybrid configurations, with fuel-cell prototypes occupying a nascent premium tier for specialized duty cycles.
- Battery:Advanced chemistry cells with NMPA safety certifications in China and BIS standards alignment in India serve rental firms seeking Scope 3 compliance without long-term capital commitment. Cell supply concentration in Chinese manufacturing clusters creates import dependency risks for European and North American OEMs assembling modules locally.
- Hybrid:Parallel hybrid architectures combining downsized diesel range extenders with electric traction motors serve contractors in India's Mumbai and Delhi infrastructure corridors where charging infrastructure gaps delay full electrification.
- Fuel Cell:Proton-exchange membrane systems with solid-state battery prototyping fragment supply agreements for underground mining contractors in Canada and Australia.
- Plug-in Hybrid:Grid-chargeable battery packs with onboard generation capability serve mixed diesel-electric job sites requiring operational flexibility during charge scheduling transitions.
Battery systems anchor current procurement volume. Fuel cell is climbing the fastest among power source alternatives.
End User:
Customer type determines whether telematics-platform bundling or standalone equipment procurement shapes lifetime value calculations.
- Contractors:Tunneling specialists in Germany, China, and the United States face synchronized emission mandates across municipal jurisdictions, concentrating fleet electrification demand in megacity transit corridors.
- Construction Companies:Urban infrastructure builders scale electrification faster than residential builders, with corporate sustainability targets overriding site-level equipment preferences.
- Rental Firms:National accounts teams at major lessors now specify electrification targets, consolidating procurement decisions at corporate level rather than delegating to regional branches.
- Government:Public procurement agencies in the United States and Europe embed emission thresholds into infrastructure tender requirements, expanding addressable market for certified electric substitutes.
Contractors dominate installed base. Rental firms are gaining share fastest as procurement centralizes.
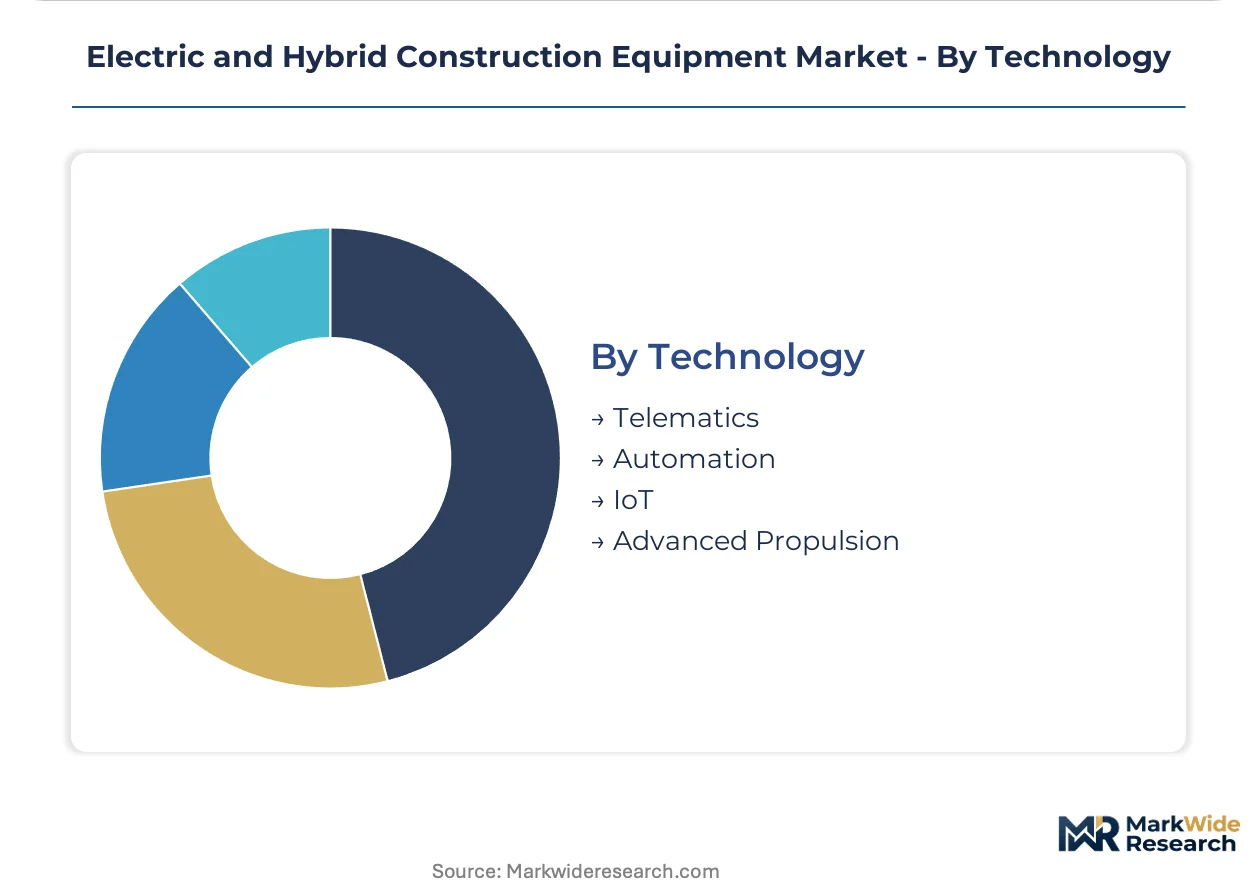
Technology:
Maturity differentiation separates proven telematics deployments from emerging automation systems requiring ISO 19453 validation cycles.
- Telematics:Factory-standard architectures monitoring charge cycles and predicting maintenance intervals reshape how fleet owners manage battery health certification and residual value assumptions.
- Automation:Semi-autonomous operation systems for repetitive excavation cycles face extended validation timelines under ISO 19453 qualification for electric drivetrain sealing and thermal management.
- IoT:Sensor networks for predictive maintenance integrate with high-voltage system diagnostics, though technician scarcity for systems exceeding 600V DC limits dealer scaling.
- Advanced Propulsion:Solid-state battery prototyping and integrated power electronics fragment incumbent lithium-ion supply agreements, forcing cell suppliers to renegotiate volume commitments.
Telematics dominates installed base. Advanced propulsion is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tunneling contractors and urban infrastructure builders concentrate procurement authority across four national markets where emission mandates and megacity transit investments align. Fleet electrification scales fastest where ventilation limits and noise ordinances intersect with synchronized regulatory enforcement.
United States
California and Texas equipment dealers report accelerated trade-in activity for electric substitutes following EPA Tier 4 Final enforcement below 56kW. The EPA eliminated grandfathering provisions starting January 2024, compressing the diesel alternative pipeline. Compact excavator segments in Los Angeles and Houston show the fastest compliance-driven substitution rates among urban contractors.
Germany
Stage V emission thresholds eliminated non-compliant diesel engines below 56kW, directly expanding the addressable market for battery-electric excavators. Tunneling contractors in Berlin and Munich face synchronized emission mandates across municipal jurisdictions. Volvo Construction Equipment anchors European demand through its dedicated electric equipment plant in Sweden, serving German infrastructure corridors.
China
MIIT dual carbon goals and NMPA battery safety certifications accelerate domestic OEM development while restricting import access for uncertified foreign brands. Urban infrastructure contractors in Beijing and Shanghai scale fleet electrification faster than residential builders. Zhengzhou and Xuzhou manufacturing clusters concentrate advanced chemistry cell production for domestic module assembly.
India
BIS charging infrastructure standards and the PLI scheme for advanced chemistry cell manufacturing condition when local contractors can operationalize electric fleets at scale. Contractors in Mumbai and Delhi infrastructure corridors deploy parallel hybrid architectures where charging infrastructure gaps delay full electrification. The Production-Linked Incentive scheme will localize supply chains and reduce landed cost for megacity transit projects.
Japan
Komatsu competes in domestic and Southeast Asian markets with integrated telematics platforms bundled into machine leases. METI industrial policy supports fuel-cell prototyping for continuous-duty applications. Tokyo and Osaka construction markets concentrate demand for hybrid loaders serving enclosed waste-management sites where noise ordinances prohibit overnight diesel operation.
Electric and Hybrid Construction Equipment Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive powertrain engineering capabilities, creating a tiered structure where scale advantages separate integrated OEMs from component-dependent assemblers. The competitive landscape exhibits consolidation around electrification roadmaps and supplier recertification investments. Two dominant strategic archetypes emerge: diversified machinery conglomerates with in-house battery module assembly, and specialized construction equipment manufacturers leveraging telematics-platform bundling. Competitive moves concentrate on strategic partnerships for charging infrastructure deployment and portfolio diversification into battery-electric variants.
Within the diversified machinery tier, Caterpillar and Volvo Construction Equipment exemplify integrated OEMs with captive battery engineering capabilities. Komatsu occupies a position representing the telematics-integrated lease model prevalent in Japanese and Southeast Asian markets. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without requiring equivalent scale or technology access.
| Leading Market Players |
|---|
| Caterpillar |
| Volvo Construction Equipment |
| Komatsu |
| Hitachi Construction Machinery |
| Liebherr |
| John Deere |
| Doosan Infracore |
| JCB |
| Kubota |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with lithium carbonate indexation lock in cell supply for European and North American OEMs while anchoring price visibility against raw material volatility. These arrangements concentrate procurement leverage among firms with balance-sheet capacity to commit volume, compressing margins for smaller assemblers forced into spot markets.
Pricing Analysis
Cost-plus contracts with quarterly lithium and nickel indexation dominate battery module procurement, transferring commodity risk to downstream buyers while insulating cell suppliers. Price differentiation rests on ISO 19453 certification tier and captive battery assembly capability, with integrated OEMs commanding premium positioning. Cost compression in standard hybrid configurations is intensifying because Chinese cell oversupply is eroding regional price floors. Rental firms exhibit highest price sensitivity due to Scope 3 compliance mandates without long-term capital commitment, while tunneling contractors absorb premiums for certified sealing and thermal management.
Supply Chain Analysis
Inventory cycles for high-voltage power electronics extend eighteen to twenty-four months, constraining OEM ability to respond to demand surges. Manufacturing gravity centers on China, South Korea, and Japan for advanced chemistry cells, with Germany and the United States hosting module assembly and pack integration. Raw material dependencies span lithium hydroxide, nickel sulfate, and rare-earth permanent magnets for traction motors. Single-source vulnerability concentrates in Chinese cathode active material production, where export licensing shifts create supply uncertainty. Distribution runs through OEM-direct channels for large fleet sales and national rental accounts, with regional dealers serving fragmented contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric and hybrid construction equipment represents a high-growth disruption as EPA Tier 4 Final and Stage V enforcement below 56kW eliminate diesel alternatives and force accelerated fleet turnover.
For Market Incumbents: Fortify captive battery module assembly to defend cost position against Chinese cell suppliers expanding downstream. Secure ISO 19453 certification early to collapse competitor access to certified testing infrastructure. Expand telematics-platform bundling into machine leases to lock in customer lifetime value against emerging entrants offering equipment-only procurement. For New Entrants and Emerging Players: Aftermarket battery health certification services represent a service-layer gap where incumbents under-serve secondary market liquidity needs. Target India's Mumbai and Delhi infrastructure corridors where PLI scheme localization will reduce landed costs for domestic assembly partnerships. Pursue charging infrastructure deployment as a bundled offering to contractors facing grid capacity constraints at construction sites. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated lease providers with national rental firm relationships. Long-term viability favors firms with backward integration into cell supply or exclusive partnerships with certified testing laboratories. Monitor BIS charging standard adoption rates across Indian states as the inflection signal for scalable fleet operationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Battery Module Assembly | Caterpillar's in-house production controls cost position across excavator ranges against import-dependent competitors. |
| ISO 19453 Certification Investment | Certified testing infrastructure collapses supplier base and accelerates quality convergence among qualified firms. |
| Telematics-Platform Bundling | Komatsu's integrated lease offerings reshape customer lifetime value calculations in Japanese and Southeast Asian markets. |
| PLI Scheme Localization | India's production-linked incentives will reduce landed costs for megacity transit corridor contractors in Mumbai and Delhi. |
| Charging Infrastructure Partnership | Deployment alliances address grid capacity gaps delaying electric fleet operationalization outside regulated urban zones. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and OEM technical documentation. Primary interviews engaged fleet procurement managers at rental firms, maintenance directors at tunneling contractors, OEM powertrain engineering leads, and aftermarket service heads at regional dealers. Secondary validation drew from EPA enforcement notices, Stage V type-approval databases, MIIT dual carbon policy releases, and BIS charging standard publications. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Segmentation dimensions modeled span product type, power source architecture, end-user category, and technology maturity tier across the projection horizon. CAGRs derive from elasticity-adjusted substitution curves responding to regulatory enforcement timelines and infrastructure buildout assumptions. Industry-specific forecast inputs incorporate battery cell cost trajectories and high-voltage technician training pipeline scaling.
Material uncertainties — battery chemistry transitions, tariff regime shifts, and grid capacity buildout delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory alignment and supply chain localization trajectories that may revise with policy changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Vertical Mill Market
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Utility Locator Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Soil Compaction Equipment Market