
 Induction Furnace Market | 2026-2036
Induction Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Induction Furnace Market Outlook
India is rewriting capacity deployment patterns across the induction furnace landscape. Inductotherm Group leverages its coreless furnace technology leadership to anchor demand from South Asian foundries. Electrotherm Limited competes through integrated in-house production of power electronics and melting systems. SMS Group sustains its position via large-scale project execution for steel manufacturing clients.
An induction furnace converts electrical energy into heat through electromagnetic induction, generating temperatures exceeding 1,600°C to melt ferrous and non-ferrous metals without direct fuel combustion. The equipment serves primary functions in metallurgy, foundry casting, and scrap metal recycling where precise temperature control and reduced emissions prove critical. Coreless furnaces dominate installed capacity due to operational flexibility across batch sizes and alloy types, while IGBT technology segments are gaining traction from power efficiency improvements in melting operations. Channel furnace categories retain stable positions in long-run holding applications where thermal consistency outweighs speed.
EPA emissions guidelines and OSHA workplace safety standards shape equipment specifications and installation protocols across US manufacturing facilities. India's BIS energy efficiency mandates and China's GB standards for industrial electrical equipment impose parallel compliance burdens on furnace suppliers seeking market access. Stakeholders must monitor how evolving carbon border mechanisms and national scrap utilization policies redirect investment toward hybrid melting systems and secondary metal processing infrastructure.
Market Dynamics
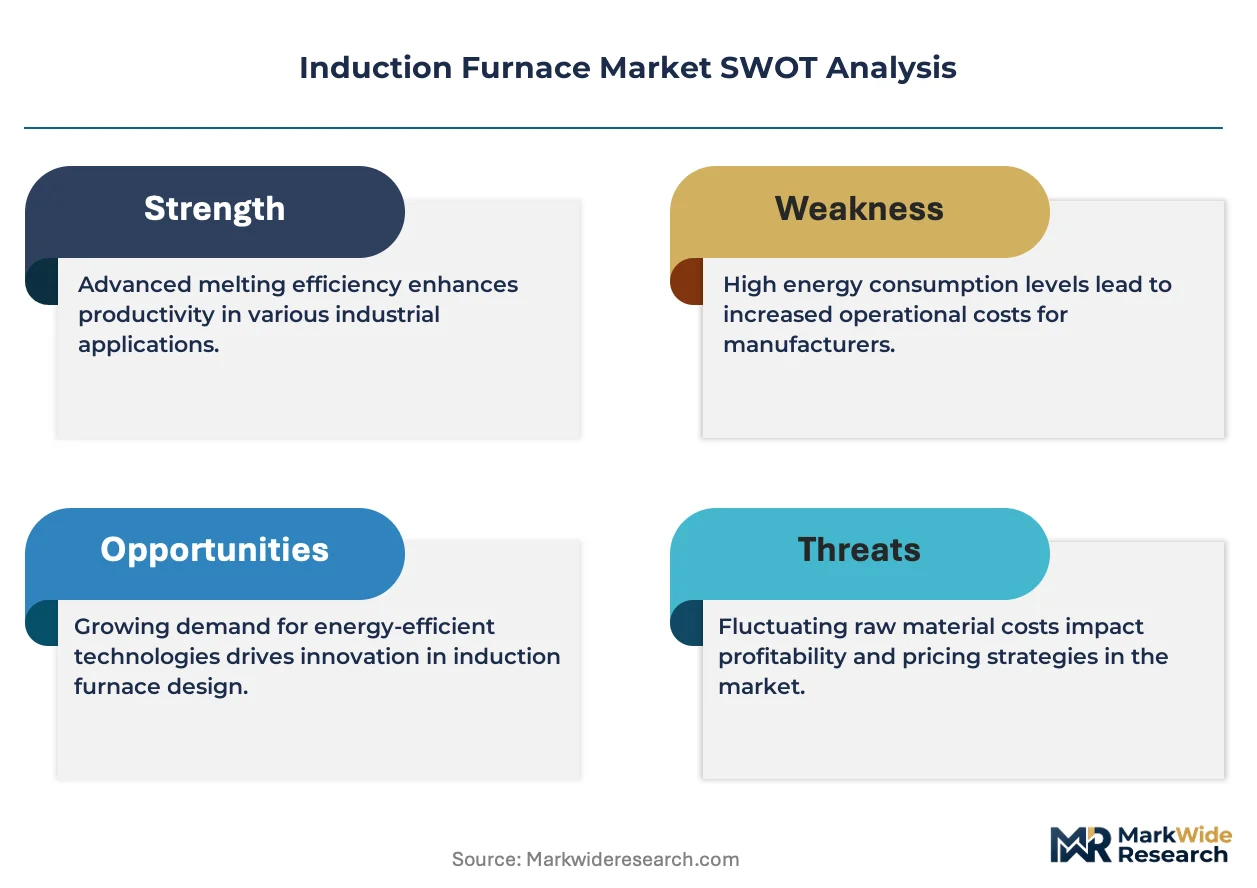
IGBT power electronics and active harmonic filtering are compressing energy consumption curves across melting operations, forcing incumbent furnace architectures toward modular retrofit pathways or full replacement cycles.
Growth Catalysts
- China's GB 18613 energy efficiency mandates:Tier-1 motor efficiency requirements are accelerating furnace rebuild schedules across Shandong and Hebei steel clusters.
- Automotive lightweighting programs:Aluminum-intensive electric vehicle platforms are expanding dedicated induction melting capacity at tier-1 casting suppliers.
- Scrap-fed steelmaking:Electric arc furnace route expansions in Turkey and Iran are pulling channel furnace demand for liquid metal holding applications.
Market Restraints
- Copper and silicon steel price volatility:Coil and magnetic core input costs swing 15-30% annually, compressing OEM margin stability.
- Graphite electrode supply concentration:Ultra-high power electrode manufacturing clusters in China create single-source vulnerability for large furnace operators.
- Refractory lining degradation rates:Silica and alumina crucible life limitations impose unplanned downtime costs exceeding preventive maintenance budgets.
Strategic Opportunities
- Vietnam's emerging foundry corridor:Greenfield investments in Hai Phong and Binh Duong provinces lack mature induction service infrastructure.
- Dual-frequency melting systems:Combined medium and high-frequency power supplies enable single-furnace flexibility across ferrous and non-ferrous alloys.
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade automotive and electrical steel are qualifying induction-based precision melting.
Industry Challenges
- Electromagnetic field compliance certification:Workplace exposure limit testing under IEEE C95.1 and ICNIRP guidelines extends commissioning timelines.
- Legacy thyristor system integration:Retrofitting active front-end drives into 1990s-era furnace controls requires custom firmware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induction Furnace Market |
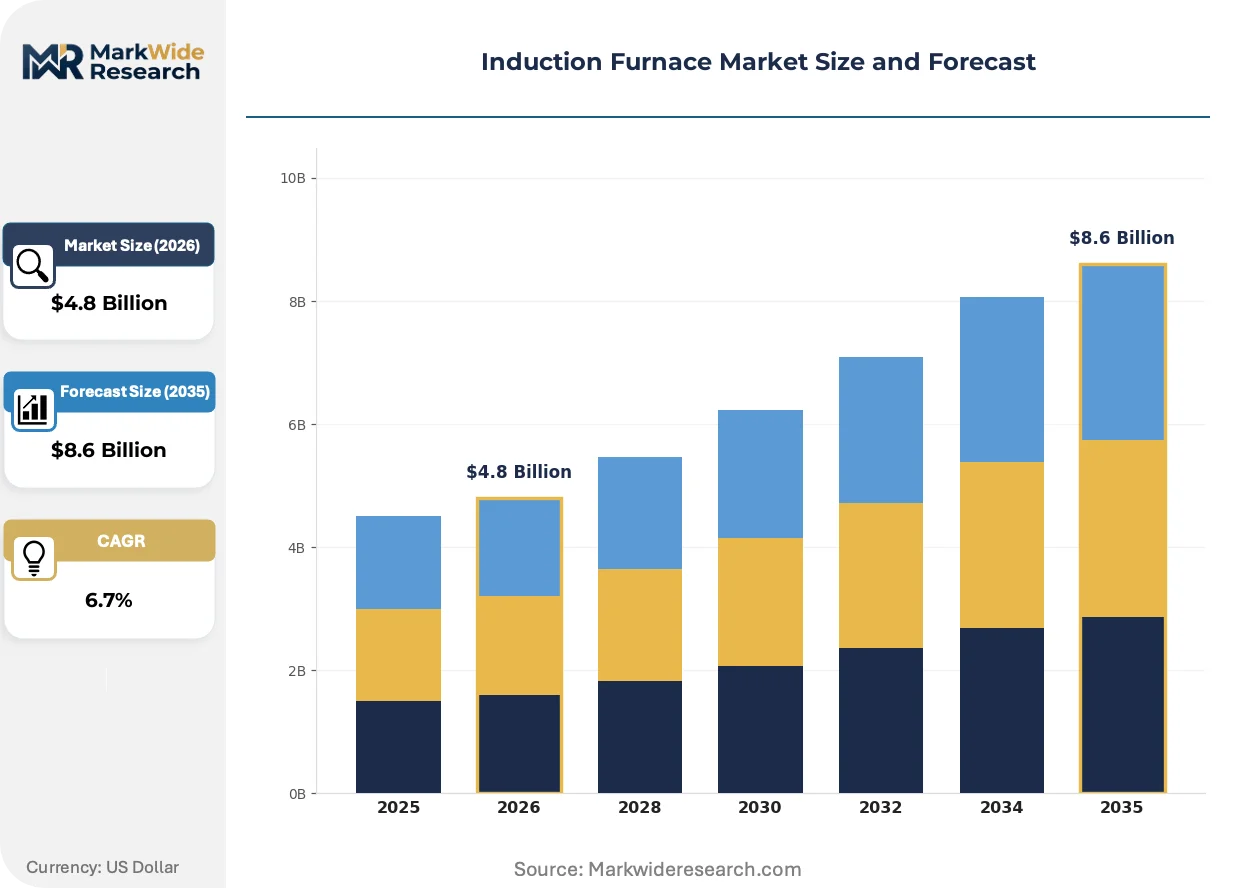
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coreless Furnace, Channel Furnace, Induction Melting Furnace, Induction Heating Furnace End User: Foundries, Steel Manufacturing, Non-Ferrous Metal Processing, Scrap Recycling Technology: Electromagnetic Induction, Resistance Heating, Hybrid Systems, IGBT Technology Application: Metallurgy, Aerospace Components, Automotive Parts, Electrical Equipment |
| Companies Covered | Inductotherm Group, Inductotherm Corporation, Ajax Tocco Magnethermic, ABP Induction Systems, Electrotherm Limited, OTTO JUNKER, Danieli, SMS Group, Tenova SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induction Furnace Market Strategic Shifts
Power semiconductor evolution and closed-loop thermal management are collapsing the performance gap between coreless and channel furnace architectures. Equipment differentiation now hinges on digital twin integration and predictive refractory monitoring rather than melting rate specifications alone.
IGBT-based resonant power supplies are hybridizing with traditional thyristor frequency converters across mid-capacity melting lines. Foundry operators in Germany and Italy are adopting these hybrid architectures to preserve existing transformer infrastructure while achieving 8-12% energy recovery through regenerative braking. The technology is hybridizing procurement criteria, forcing vendors to support mixed-vintage power electronics within single site deployments.
EPA's updated National Emission Standards for Hazardous Air Pollutants for ferrous foundries are tightening particulate and metal HAP limits effective 2026. Baghouse and wet scrubber retrofits are consuming 15-20% of furnace upgrade capital at US installations. Channel furnaces with integrated fume collection hoods are capturing specification share in gray iron applications where emissions compliance dominates total cost of ownership calculations.
Service contracting is unbundling from equipment sales across Southeast Asian markets. Thai and Indonesian foundries are purchasing melting capacity through tonnage-based agreements with vendors retaining asset ownership and maintenance liability. This model concentrates in aluminum die-casting supply chains serving Japanese automotive transplants, where balance sheet efficiency outweighs capital deployment preferences.
Induction Furnace Market Segmentation
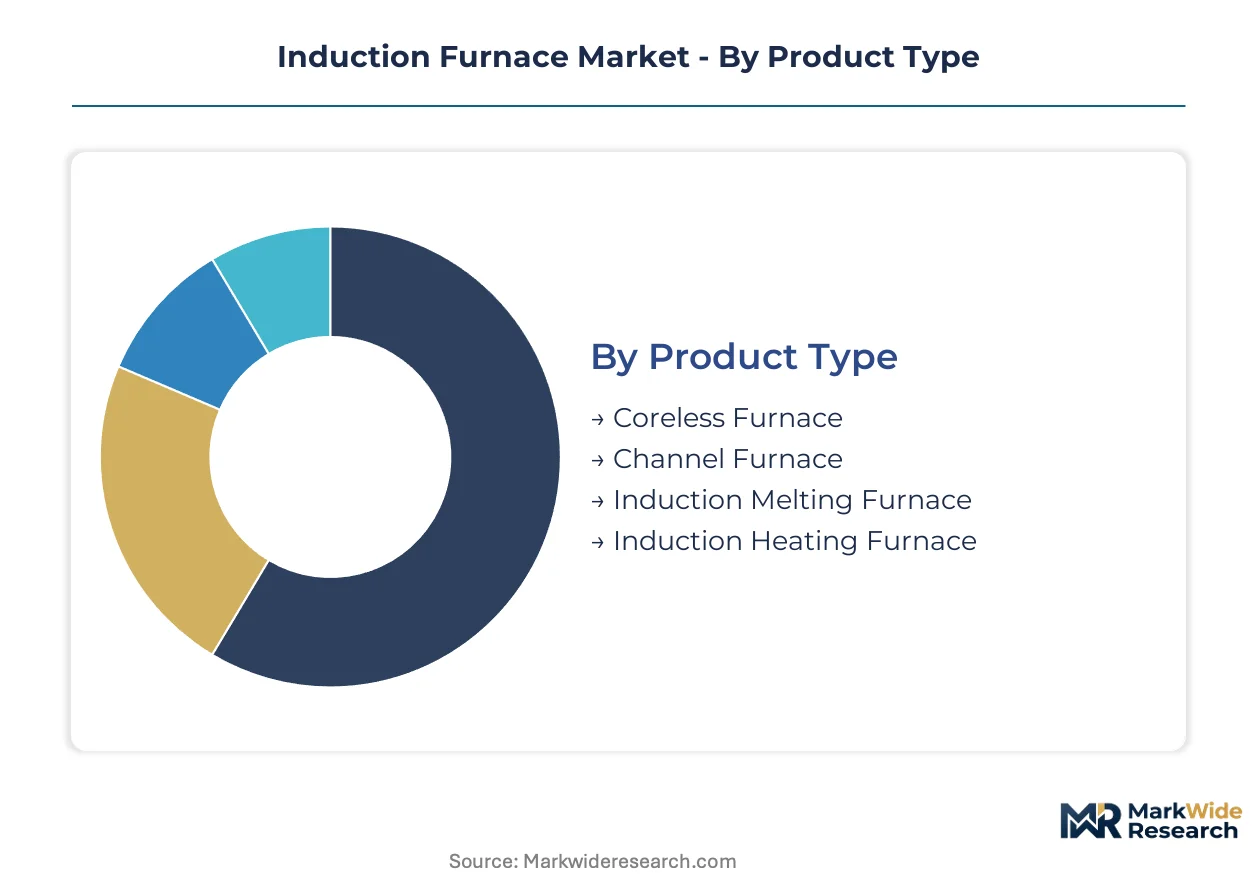
Segmentation reveals how furnace architectures, power electronics, and end-use requirements fragment procurement criteria across metallurgical operations. Understanding these divisions exposes where service intensity, energy efficiency mandates, and alloy flexibility reshape vendor-customer relationships.
Product Type:
After-sales service intensity varies dramatically across furnace architectures, with refractory-dependent designs demanding continuous technical support while solid-state systems shift service toward predictive electronics maintenance.
- Coreless Furnace:These units employ water-cooled copper coils surrounding a refractory crucible, enabling rapid alloy changes and batch flexibility. Demand concentrates in Indian foundries around Gujarat and Maharashtra where scrap-fed steelmaking requires frequent chemistry adjustments; refractory lining replacement cycles drive 40% of lifetime service revenue.
- Channel Furnace:A closed-loop inductor channel maintains molten metal pools for extended holding periods with minimal temperature drift. Long-run holding applications in Turkish and Iranian steel clusters favor this architecture; thermal consistency outweighs melting speed in liquid metal logistics for electric arc furnace feeding.
- Induction Melting Furnace:Purpose-built systems integrate power supply, coil assembly, and hydraulic tilt mechanisms for dedicated melting operations.
- Induction Heating Furnace:Surface-hardening and forging preheat applications utilize these units for localized heat treatment without bulk melting.
Coreless furnace holds the largest share; momentum sits with channel furnace configurations in integrated steelmaking corridors.
End User:
Cost tier stratification separates capital-intensive steel producers from foundry operators prioritizing batch flexibility over unit scale.
- Foundries:Batch-oriented melting for sand casting and die-casting operations dominates Southeast Asian demand, particularly in Vietnam's emerging Hai Phong and Binh Duong corridors where service infrastructure remains underdeveloped.
- Steel Manufacturing:Large-tonnage melting for billet and slab production requires continuous operation designs with redundant power supplies.
- Non-Ferrous Metal Processing:Aluminum, copper, and zinc melting demands precise temperature control to prevent oxidation losses.
- Scrap Recycling:Chemistry-variable feedstock necessitates rapid slagging and alloying capabilities; India's scrap recycling corridor expansion qualifies this segment for PLI-linked specialty steel incentives.
Steel manufacturing commands premium pricing; scrap recycling climbs fastest on circular economy policy tailwinds.
Technology:
Volume concentration in power electronics procurement favors integrated vendors with captive semiconductor sourcing.
- Electromagnetic Induction:Traditional coil-and-core designs utilizing variable frequency drives remain prevalent in legacy installations.
- Resistance Heating:Direct ohmic heating elements supplement induction in specialized alloy applications requiring controlled atmosphere.
- Hybrid Systems:Dual-frequency configurations combining medium and high-frequency power supplies enable single-furnace ferrous and non-ferrous flexibility; German and Italian foundries adopt these to preserve existing transformer infrastructure.
- IGBT Technology:Insulated-gate bipolar transistor power supplies achieve 8-12% energy recovery through regenerative braking, compressing consumption curves and forcing thyristor retrofits or replacement cycles.
Electromagnetic induction retains installed base dominance; IGBT technology gains specification share fastest on efficiency mandates.
Application:
Customer type differentiation separates aerospace qualification requirements from automotive volume procurement.
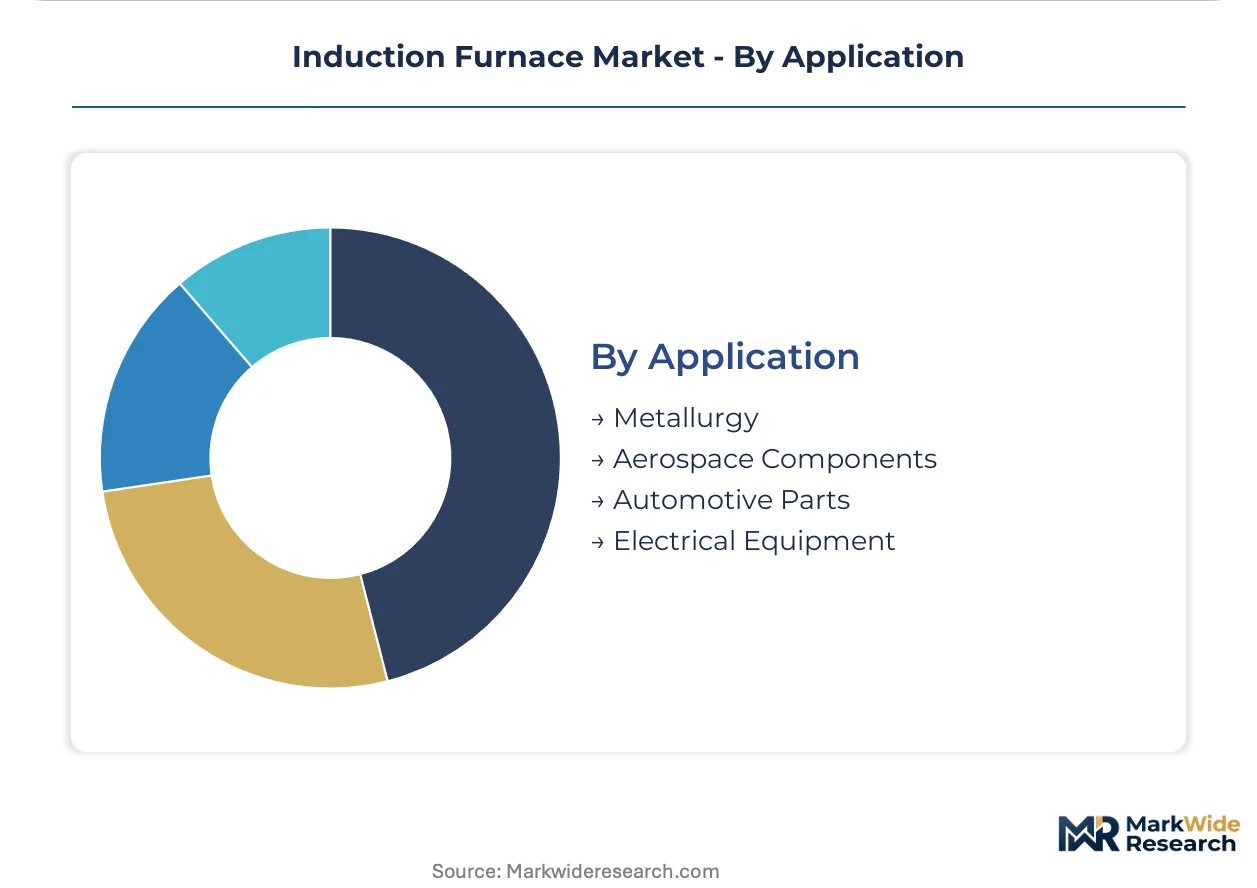
- Metallurgy:Primary and secondary metal production encompasses the broadest furnace specification range.
- Aerospace Components:Superalloy and titanium melting demands vacuum induction capabilities with trace element control.
- Automotive Parts:Aluminum-intensive electric vehicle platforms expand dedicated melting capacity at tier-1 casting suppliers; lightweighting programs specify channel furnaces with integrated fume collection for gray iron compliance.
- Electrical Equipment:Silicon steel and specialty magnetic alloy melting requires hydrogen atmosphere control.
Metallurgy anchors volume demand; automotive parts expands most quickly on electric vehicle platform rollouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coil and magnetic core manufacturing clusters concentrate in Germany, China, and India, concentrating furnace supply chains around these three fabrication hubs. Foundry demand disperses more widely, with Southeast Asian markets expanding fastest on automotive supplier relocations. Regulatory divergence across energy efficiency mandates and emissions protocols is fragmenting equipment specifications by geography.
China
GB 18613 Tier-1 motor efficiency requirements are accelerating furnace rebuild schedules across Shandong and Hebei steel clusters. MIIT's dual carbon goals impose parallel compliance burdens on industrial electrical equipment specifications. Channel furnace demand concentrates in Tangshan for liquid metal holding applications serving electric arc furnace expansions.
India
BIS energy efficiency mandates and PLI scheme incentives for specialty steel are qualifying induction-based precision melting capacity. Scrap-fed steelmaking expansion drives coreless furnace deployment across Gujarat and Maharashtra foundry corridors. Refractory lining replacement cycles generate 40% of lifetime service revenue for installed equipment around Rajkot and Pune.
Germany
Hybrid IGBT-thyristor architectures preserve existing transformer infrastructure while achieving regenerative braking energy recovery. REACH compliance and EU Green Deal carbon border mechanisms redirect investment toward secondary metal processing infrastructure. Foundry operators in Bavaria and North Rhine-Westphalia adopt dual-frequency systems for ferrous and non-ferrous flexibility.
United States
EPA National Emission Standards for Hazardous Air Pollutants updates tighten particulate and metal HAP limits effective 2026. Baghouse and wet scrubber retrofits consume 15-20% of furnace upgrade capital at Midwest foundry installations. Channel furnaces with integrated fume collection hoods capture specification share in gray iron applications across Ohio and Indiana.
Vietnam
Greenfield investments in Hai Phong and Binh Duong provinces lack mature induction service infrastructure, creating vendor opportunity. Japanese automotive transplants drive aluminum die-casting capacity expansion with tonnage-based service contracting preferences. Foundry corridor development concentrates melting demand without established power electronics maintenance networks.
Induction Furnace Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on coil fabrication and power semiconductor supply. The vendor base stratifies across three tiers: full-system providers with captive power electronics, furnace fabricators sourcing externally, and refractory service specialists. Two strategic archetypes dominate—vertically integrated melting technology platforms and regional foundry equipment assemblers. Competitive moves concentrate on modular retrofit pathways for legacy thyristor installations and service contracting unbundling in Southeast Asian markets.
Among European-based furnace specialists, OTTO JUNKER and SMS Group exemplify large-scale project execution capabilities for steel manufacturing clients. Inductotherm Corporation anchors the North American tier through coreless furnace technology leadership. These three names represent distinct geographic anchoring and customer scale positioning across the competitive map.
| Leading Market Players |
|---|
| Inductotherm Group |
| Inductotherm Corporation |
| Ajax Tocco Magnethermic |
| ABP Induction Systems |
| Electrotherm Limited |
| OTTO JUNKER |
| Danieli |
| SMS Group |
| Tenova SpA |
| Others |
Value Chain & Pricing Dynamics
Tangshan's channel furnace manufacturing cluster concentrates coil fabrication and magnetic core production, translating upstream capacity tightness into asymmetric pricing power for integrated vendors serving liquid metal holding applications in Hebei steel corridors.
Pricing Analysis
China's GB 18613 Tier-1 motor efficiency mandates dictate the pricing tier structure across furnace power electronics. Three-tier pricing structure across premium, standard, and economy levels separates IGBT-based regenerative systems from hybrid thyristor architectures and legacy frequency converters. Cost compression in standard-tier equipment is intensifying because copper and silicon steel input costs swing unpredictably. Scrap recycling operators in India's Gujarat corridor exhibit the highest price sensitivity, while aerospace component suppliers prioritize certification-grade vacuum induction capabilities over unit economics.
Supply Chain Analysis
Copper coil stock, silicon steel laminations, and graphite electrodes anchor the upstream feedstock profile for furnace fabrication. Manufacturing clusters in Germany, China, and India concentrate coil winding and magnetic core assembly. Supply chain risk centers on single-source vulnerability for ultra-high power graphite electrodes manufactured in China. Distribution runs through direct OEM relationships with steel manufacturers and foundry equipment distributors serving Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction furnace incumbents face substitution pressure from electric arc furnace route expansions and hybrid plasma melting technologies in secondary steelmaking. Defense requires technology-cycle positioning that preserves installed base relationships while absorbing efficiency mandates.
For Market Incumbents: Insulate coreless furnace service revenue through predictive refractory monitoring platforms that extend lining life and reduce unplanned downtime. Deepen backward integration into IGBT power semiconductor sourcing to offset copper and silicon steel cost volatility. Channel furnace specifications with integrated fume collection hoods defend position against emissions compliance retrofit competition in US gray iron applications.
For New Entrants and Emerging Players: Vietnam's Hai Phong and Binh Duong foundry corridors represent the most penetrable entry point, where greenfield aluminum die-casting capacity lacks mature induction service infrastructure. Tonnage-based service contracting models—retaining asset ownership while selling melting capacity—align with Japanese automotive transplant procurement preferences. Target refractory logistics and power electronics maintenance networks as the critical go-to-market wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors IGBT power supply specialists with captive semiconductor relationships and hybrid system integration capabilities. Long-term viability hinges on secondary metal processing infrastructure expansion under carbon border mechanisms. Watch India's PLI scheme disbursement velocity for specialty steel as the signal indicating induction-based precision melting capacity qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| IGBT Power Supply Retrofit | GB 18613 compliance accelerates thyristor replacement cycles across Shandong steel clusters. |
| Dual-Frequency System Development | German and Italian foundries adopt hybrid architectures preserving existing transformer infrastructure. |
| Tonnage-Based Service Contracting | Thai and Indonesian foundries purchase melting capacity without capital deployment burden. |
| Predictive Refractory Monitoring | Silica and alumina crucible life optimization reduces 40% lifetime service cost exposure. |
| Channel Furnace Fume Integration | EPA NESHAP compliance drives specification share in Ohio and Indiana gray iron applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS energy efficiency filings, SEC equipment supplier disclosures, and foundry association production surveys. Conversations with maintenance directors at steel manufacturing facilities, plant engineers at Southeast Asian foundries, OEM procurement teams specifying melting systems, and aftermarket service heads managing refractory logistics informed demand-side validation. Bottom-up furnace shipment analysis triangulates against top-down metallurgical capacity expansion tracking.
Forecast inputs include power electronics adoption curves, regulatory compliance deadlines, and scrap utilization policy trajectories across the analysis window. Segmentation dimensions span furnace architecture, power supply technology, end-use industry, and regional regulatory cluster. CAGRs derive from installed base turnover modeling and greenfield capacity addition pipelines. Industry-specific inputs incorporate GB 18613 implementation velocity and India's PLI scheme qualification thresholds.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, copper commodity cycles, or carbon border mechanism implementation schedules would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Quarterly review of furnace import data, refractory consumption indices, and power semiconductor lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Part Feeder Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Truck Mounted Concrete Mixer Market