
 Winch Market | 2026-2036
Winch Market Size, Share, and Industry Trends Forecast 2026-2036
Winch Market Outlook
Permanent magnet motor integration is reconfiguring electric winch architectures toward higher torque density and reduced maintenance intervals. WARN Industries leverages vertical integration to control drivetrain quality from motor winding to drum assembly. Huisman anchors its position through R&D intensity in offshore crane-winch combinations for deep-water vessel applications. Ingersoll Rand competes on manufacturing scale across pneumatic and hydraulic product lines for industrial material handling.
A winch is a mechanical device comprising a drum or spool, drive mechanism, and brake system, typically rated by line pull capacity from under one ton to over 500 tons, designed to wind in or let out rope or cable under tension for pulling, lifting, or securing loads. Electric winches now dominate the product type landscape due to precision control and lower operating costs in indoor and marine environments. The marine end user segment generates concentrated demand from offshore energy and commercial shipping fleets, while mining applications favor hydraulic systems for explosion-proof reliability in volatile atmospheres.
FCC equipment authorization governs radio-remote winch controls in the US, while CE marking under the EU Machinery Directive mandates emergency stop functions and load-limiting devices for European market access. ISO 4301-1 crane classification standards indirectly shape winch duty-cycle specifications through integrated lifting system requirements. Stakeholders must monitor how IEC 61508 functional safety standards propagate from offshore oil and gas into renewable energy vessel specifications.
Market Dynamics
Permanent magnet motor architectures are restructuring competitive advantage around torque density and thermal efficiency, compressing maintenance intervals while expanding duty-cycle ratings for offshore vessel operators.
Growth Catalysts
- Offshore Wind Installation Surge:Floating platform deployments in the North Sea and Baltic markets are mandating high-capacity electric winch systems for turbine component handling.
- IEC 60204-1 Certification Mandates:Tightened electrical safety standards across European marine applications are disqualifying legacy hydraulic systems from new vessel procurement specifications.
- Port Modernization in China:State-directed infrastructure investment at Shanghai, Ningbo-Zhoushan, and Shenzhen terminals sustains heavy-lifting equipment replacement cycles.
Market Restraints
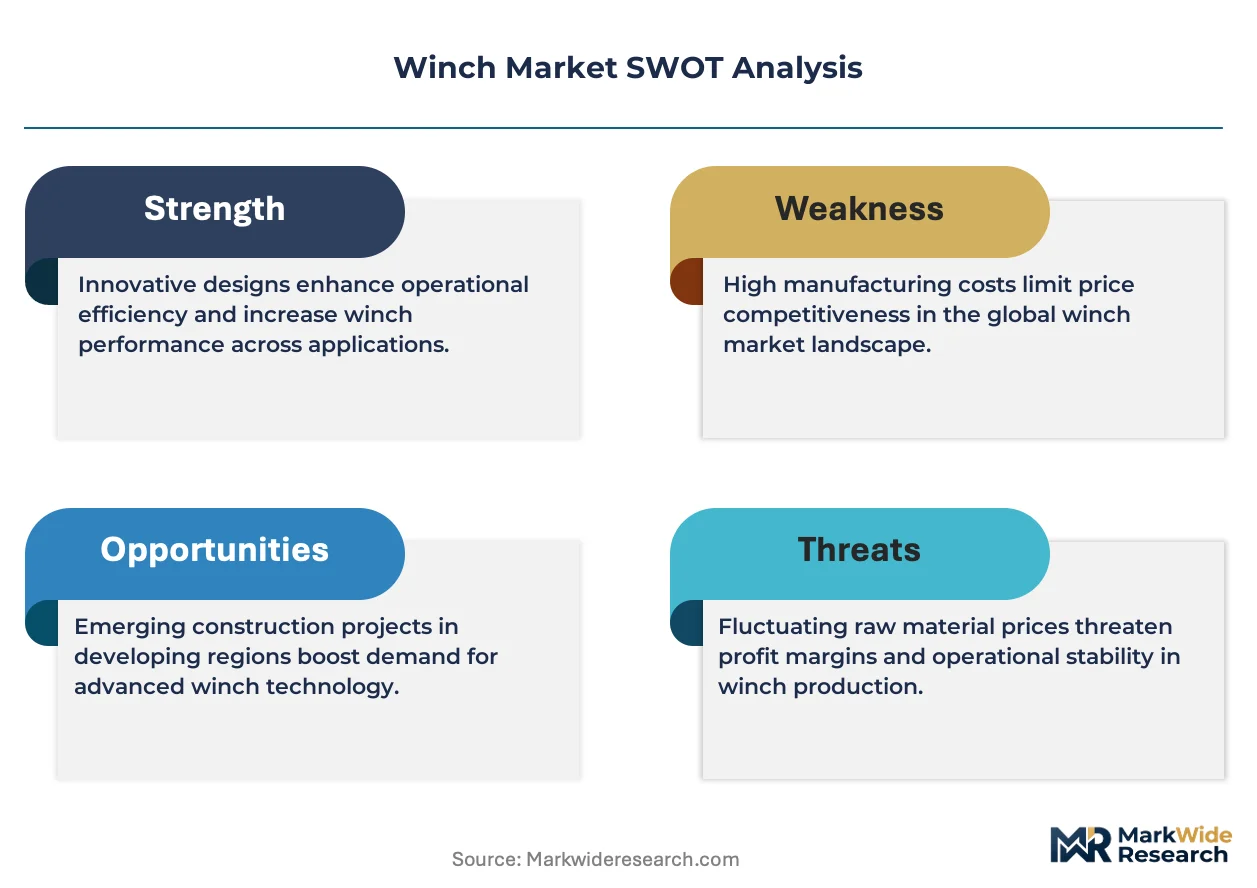
- Rare Earth Magnet Supply Concentration:Permanent magnet motor production depends on neodymium processing concentrated in Chinese refining facilities.
- Copper and Steel Price Volatility:Drum assemblies and motor windings face input cost pressure from commodity market fluctuations.
- Hydraulic System Entrenchment in Mining:Explosion-proof reliability requirements in coal and hard-rock operations resist electric system penetration.
Strategic Opportunities
- Decommissioning Vessel Equipment:North Sea oil platform removal contracts create demand for specialized deep-water winch configurations.
- Remote Monitoring Integration:IoT-enabled predictive maintenance contracts are displacing traditional break-fix service models in commercial shipping fleets.
- EU Green Deal Vessel Retrofit Subsidies:Electrification incentives for harbor craft and short-sea shipping accelerate electric winch replacement of pneumatic systems.
Industry Challenges
- IEC 61508 Functional Safety Certification:SIL-rated control system validation extends product development timelines for offshore oil and gas applications.
- Marine Electrical Technician Scarcity:Specialized skills for high-voltage winch commissioning and troubleshooting lag fleet electrification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winch Market |
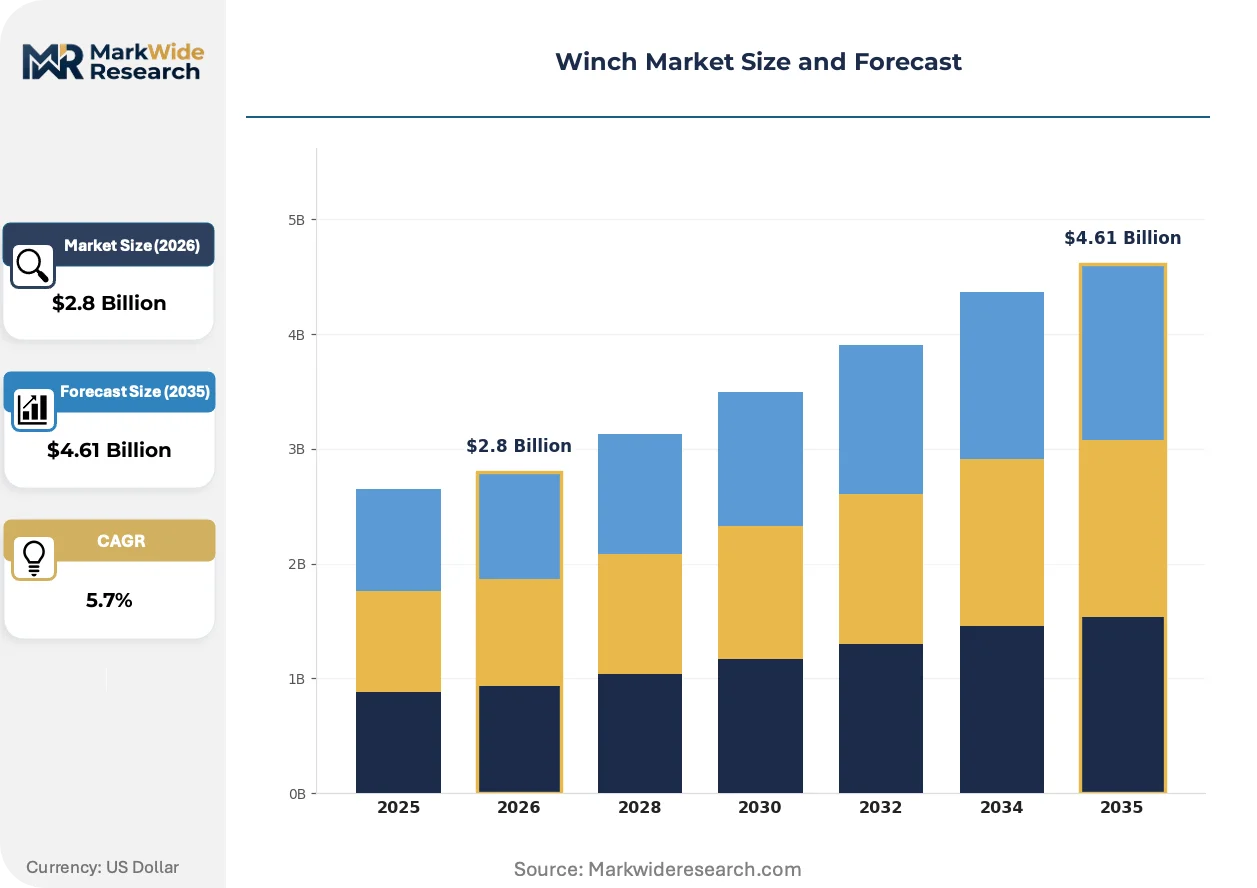
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Pneumatic Winches, Manual Winches End User: Construction, Marine, Automotive, Mining Technology: Gear Drive, Chain Drive, Belt Drive, Direct Drive Application: Material Handling, Lifting, Towing, Securing |
| Companies Covered | Paccar Winch, Huisman, Ingersoll Rand, Yale Materials Handling, Thern, WARN Industries, Ramsey Winch, Columbus McKinnon, TWG Dover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winch Market Strategic Shifts
Control system digitization and motor topology advances are compressing the performance gap between electric and hydraulic architectures while enabling predictive operational models.
Permanent magnet synchronous motors are migrating from auxiliary deck machinery to primary lifting winch applications. Offshore construction vessel operators are specifying these systems for dynamic positioning anchor handling. The technology is migrating from niche deep-water units toward standard platform supply vessels, eroding the installed base of wound-rotor induction motors.
CE marking under the EU Machinery Directive now mandates emergency stop functions and load-limiting devices for all marine winch systems entering European ports. This regulatory friction is forcing non-compliant Asian manufacturers to redesign control architectures for export market access. Norwegian and Danish classification societies are incorporating these requirements into their own vessel certification protocols ahead of formal IMO adoption.
After-sales service contracts are unbundling from original equipment sales as fleet operators seek specialized third-party maintenance providers. Independent service networks in Rotterdam, Singapore, and Houston are capturing overhaul work previously retained by manufacturers. This channel fragmentation is most visible in container shipping, where vessel operators prioritize port-state flexibility over single-source service agreements.
Winch Market Segmentation
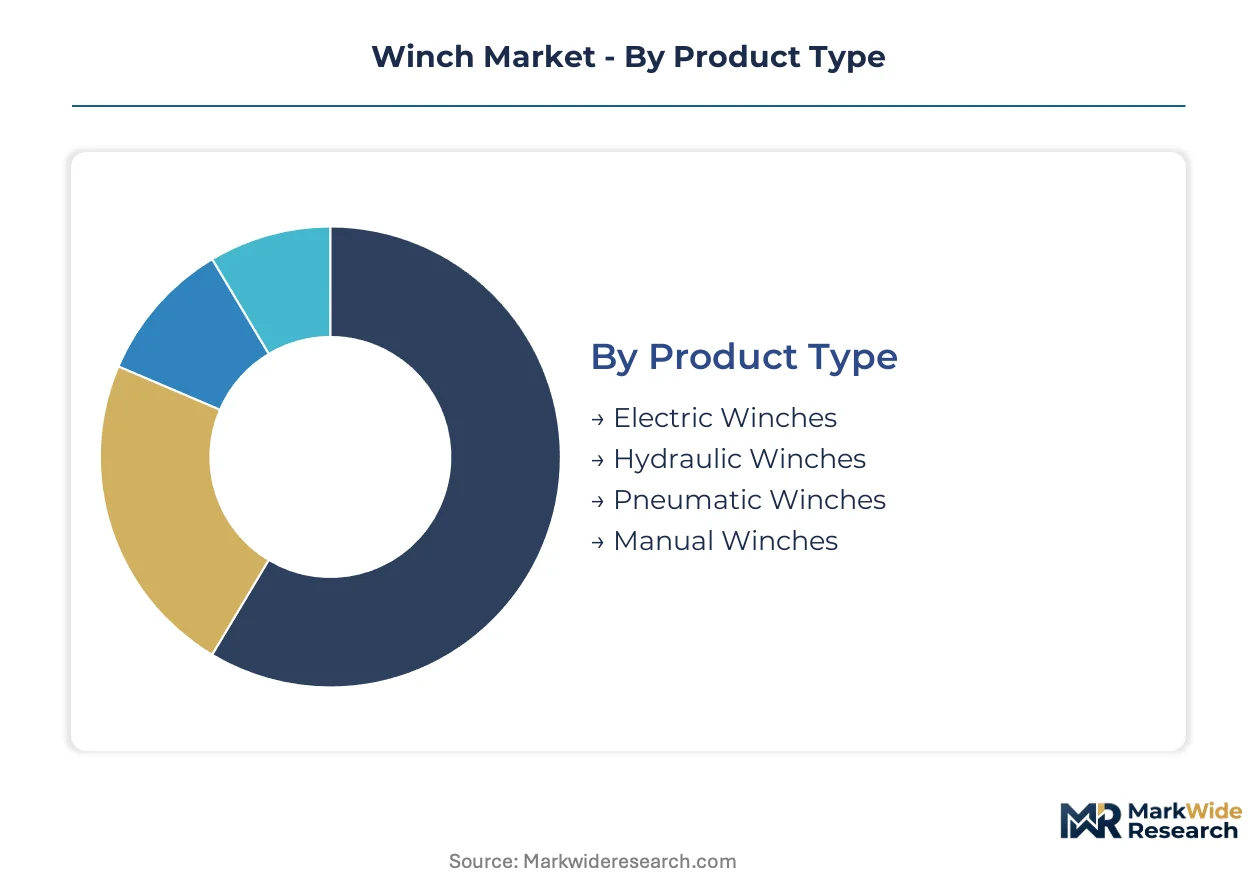
Winch procurement decisions hinge on load capacity, duty-cycle requirements, and environmental constraints. Segment boundaries blur as permanent magnet motors and digitized controls migrate across traditional product categories.
Product Type:
Electric systems anchor indoor and marine applications where precision control outweighs raw pulling power, while hydraulic architectures retain dominance in explosive atmospheres and extreme load cycling.
- Electric Winches:Permanent magnet synchronous motors deliver torque density advantages for offshore vessel anchor handling and port crane operations. North Sea wind installation fleets specify these systems for turbine component positioning, though IEC 60204-1 certification mandates are disqualifying legacy models from European procurement.
- Hydraulic Winches:Explosion-proof reliability sustains demand in underground coal and hard-rock mining where spark suppression is non-negotiable. Chinese port modernization programs still specify hydraulics for heavy-lift bollard pull applications exceeding 300 tons.
- Pneumatic Winches:Compressed-air drive suits hazardous chemical processing environments with strict ignition-source controls.
- Manual Winches:Hand-crank mechanisms persist in recreational marine and light utility vehicle applications where power supply is unreliable.
The dominant share belongs to Electric Winches, while Hydraulic Winches is closing the gap fastest in deep-water offshore specifications.
End User:
Capital intensity and regulatory exposure vary sharply across sectors, with marine and mining commanding premium pricing for certified systems.
- Construction:Tower crane integration and material hoists drive demand for variable-frequency electric winches with load-moment limiting. Urban high-rise projects in Shanghai and Shenzhen specify redundant brake systems per GB standards.
- Marine:Offshore energy vessels and commercial shipping fleets generate concentrated procurement for high-capacity electric systems. Norwegian classification society rules now incorporate EU Machinery Directive emergency-stop requirements ahead of formal IMO adoption.
- Automotive:Recovery winches for off-road vehicles and commercial towing favor compact electric architectures with wireless remote controls subject to FCC equipment authorization.
- Mining:Underground operations in coal belts and copper porphyry deposits specify flameproof hydraulic configurations meeting MSHA and analogous national mining safety codes.
Marine commands the highest average selling prices, yet Construction is expanding most quickly through state-directed infrastructure programs.
Technology:
Drive topology selection trades efficiency, maintenance access, and torque transmission precision against first cost and spatial constraints.
- Gear Drive:Helical and planetary gearboxes deliver stepped torque multiplication for heavy-lift applications. Offshore construction vessels specify these for dynamic positioning anchor handling where backlash control is critical.
- Direct Drive:Elimination of mechanical transmission reduces maintenance intervals and acoustic signature. Permanent magnet motors enable this architecture for precision lowering operations in port container handling.
- Chain Drive:Roller chain mechanisms suit high-shock intermittent duty in logging and rough-terrain recovery.
- Belt Drive:Synchronous belt systems serve light-duty material handling where noise suppression and clean operation are prioritized.
Gear Drive retains the largest installed base, though Direct Drive is gaining share fastest through marine electrification mandates.
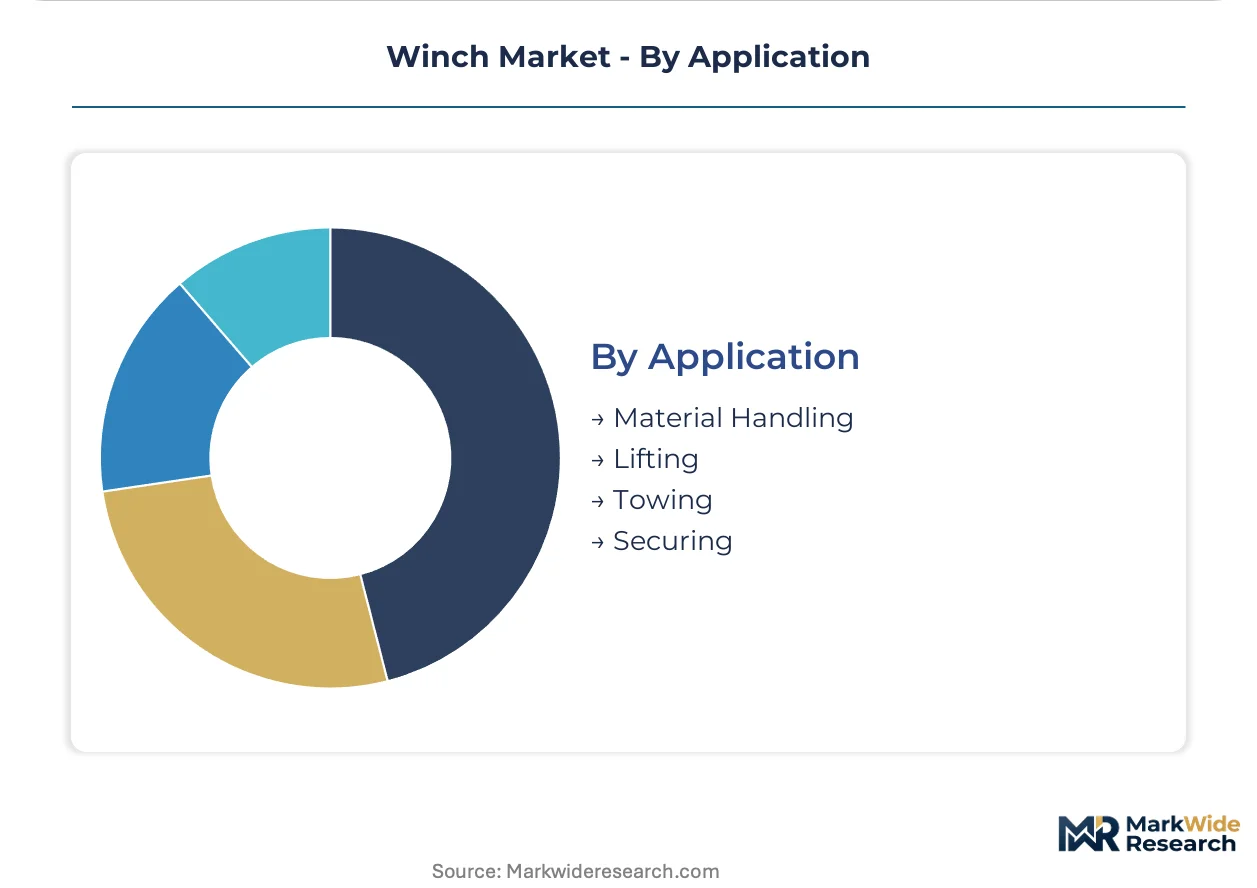
Application:
Functional requirements determine duty-cycle ratings, rope fleet angles, and control system sophistication across operating scenarios.
- Lifting:Vertical load handling demands certified brake systems and overload protection per ISO 4301-1 crane classification standards. Tower cranes and offshore platform supply vessels specify these for personnel and equipment transfer.
- Material Handling:Horizontal and inclined pulling operations in warehouses and distribution centers favor electric winches with variable speed control and position feedback.
- Towing:Bollard pull applications for salvage tugs and ship-assist vessels require sustained thermal ratings and drum capacity for wire rope storage.
- Securing:Mooring and cargo lashing operations utilize constant-tension winches with automatic payout to compensate for vessel motion and tide variation.
Lifting captures the premium pricing tier, while Material Handling is climbing the fastest through e-commerce fulfillment center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German winch manufacturers export high-capacity electric systems to North Sea offshore wind fleets, while Chinese shipyards supply standardized units to Southeast Asian port modernization programs.
China
State-directed infrastructure investment drives heavy-lifting equipment procurement at Shanghai, Ningbo-Zhoushan, and Shenzhen terminals. GB standards mandate redundant brake systems for tower crane integration in urban high-rise construction. Yangtze River Delta shipyards concentrate output of electric winch systems for domestic fleet replacement and export to Belt and Road port projects.
Germany
Offshore wind installation vessel operators specify precision electric winches for turbine component handling in North Sea and Baltic deployments. CE marking under the EU Machinery Directive mandates emergency stop functions and load-limiting devices for marine market access. Hamburg and Bremerhaven harbor craft electrification programs accelerate replacement of pneumatic systems with IEC 60204-1 certified equipment.
United States
Commercial shipping fleets in the Gulf of Mexico and Pacific Northwest generate demand for IoT-enabled predictive maintenance contracts. FCC equipment authorization governs radio-remote winch controls for automotive recovery and towing applications. Houston independent service networks capture overhaul work previously retained by original equipment manufacturers.
Norway
Deep-water vessel applications for offshore oil and gas decommissioning create demand for specialized winch configurations. Norwegian classification society rules incorporate EU Machinery Directive requirements ahead of formal IMO adoption. Stavanger and Bergen clusters anchor R&D intensity in offshore crane-winch combinations for floating platform deployments.
Japan
METI industrial efficiency programs promote permanent magnet motor adoption in port container handling equipment. JIS standards shape winch duty-cycle specifications through integrated lifting system requirements. Kobe and Yokohama maritime districts concentrate retrofit activity for short-sea shipping electrification under decarbonization targets.
Winch Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: integrated drivetrain specialists, diversified industrial conglomerates, and regional fabrication houses serving price-sensitive procurement. Premium positioning depends on IEC 61508 functional safety certification and SIL-rated control system validation. Mid-scale players compete through aftermarket service unbundling and third-party maintenance network density. Dominant competitive moves include backward integration into motor winding operations and strategic partnerships for rare earth magnet supply security.
Within the integrated specialist tier, WARN Industries and Huisman exemplify contrasting geographic anchoring and technical focus. WARN Industries occupies a position among North American vertically integrated fabricators controlling quality from motor production through drum assembly. Huisman represents European R&D-intensive positioning in offshore marine applications. Ingersoll Rand sits within the diversified industrial conglomerate archetype, competing across pneumatic and hydraulic product lines where manufacturing scale determines procurement outcomes.
| Leading Market Players |
|---|
| Paccar Winch |
| Huisman |
| Ingersoll Rand |
| Yale Materials Handling |
| Thern |
| WARN Industries |
| Ramsey Winch |
| Columbus McKinnon |
| TWG Dover |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta shipyards concentrate electric winch production capacity, and this geographic clustering grants established fabricators leverage over pricing for European offshore wind procurement. Neodymium refining concentration in Chinese facilities feeds upstream into permanent magnet motor costs, compressing margin flexibility for non-integrated assemblers.
Pricing Analysis
Permanent magnet synchronous motor systems command 15-25% premiums over wound-rotor induction alternatives, while legacy hydraulic architectures face price erosion from IEC 60204-1 disqualification in European marine tenders. Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified offshore systems from port-handling units and light-duty industrial models. Cost compression in the hydraulic tier is intensifying because electric substitution accelerates in North Sea vessel specifications. Mining operators show highest price sensitivity due to commodity cycle exposure, while offshore wind developers prioritize certification grade over unit cost.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese refining facilities, with secondary processing in Japan and Germany for high-grade motor applications. Drum assemblies rest on steel plate from Korean and Chinese mills, while copper winding supply concentrates in Chilean and Peruvian mining output feeding Chinese wire drawing. Single-source vulnerability in rare earth magnet supply creates exposure to export licensing shifts. Distribution runs through Rotterdam, Singapore, and Houston service hubs for aftermarket parts, with OEM-direct channels dominating new vessel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric winch incumbents face substitution pressure from integrated drivetrain specialists capturing offshore wind procurement through permanent magnet motor control. Hydraulic system defenders must navigate electrification mandates that disqualify legacy architectures from European marine specifications.
For Market Incumbents: Build certification moats around IEC 61508 SIL-rated control systems to lock out Asian competitors from North Sea offshore wind tenders. Secure captive supply of neodymium magnets through offtake agreements with Chinese refiners or Japanese magnet processors. Defend against emerging integrated specialists by controlling motor winding operations in-house rather than sourcing from third-party suppliers. For New Entrants and Emerging Players: Pursue decommissioning vessel specialization where deep-water winch configurations require engineering depth that commoditized suppliers cannot match. Target North Sea oil platform removal contracts as the most penetrable segment, as incumbent service networks lack presence in this emerging application. Lead with predictive maintenance contracts unbundled from equipment sales to capture fleet operator preference for third-party service flexibility. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent service networks in Rotterdam, Singapore, and Houston that capture overhaul work previously retained by manufacturers. Long-term viability favors acquisition targets with installed base density in container shipping fleets where electrification retrofit cycles extend replacement demand. Monitor IEC 60204-1 certification adoption rates among Asian manufacturers as the signal indicating when price competition from non-compliant suppliers will dissipate.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures torque density advantages for offshore vessel anchor handling specifications. |
| Backward Integration into Magnet Supply | Secures neodymium processing capacity against Chinese export licensing volatility. |
| IoT-Enabled Predictive Maintenance Contracts | Displaces break-fix service models in commercial shipping fleets seeking operational certainty. |
| IEC 61508 Functional Safety Certification | Unlocks North Sea offshore oil and gas procurement where SIL ratings are mandatory. |
| Independent Service Network Expansion | Captures overhaul revenue in Rotterdam, Singapore, and Houston port clusters. |
Study Parameters
Operator-level perspectives from vessel maintenance directors, offshore project engineers, port equipment procurement managers, and marine classification society surveyors anchored the qualitative base. These primary inputs combined with secondary validation from Lloyd's Register vessel databases, IEC certification registries, customs trade data for winch component flows, and SEC filings from diversified industrial conglomerates. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from equipment installation records.
Scenario-bracketing framed the analytical approach, with low-case assumptions incorporating extended hydraulic system entrenchment in mining and high-case assumptions accelerating EU Green Deal vessel retrofit subsidies. Segmentation dimensions modeled include product type, end-use sector, drive technology, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and fleet electrification penetration curves. Industry-specific forecast inputs incorporated offshore wind installation vessel order books and Chinese port modernization investment pipelines.
Macroeconomic conditions sit as an overlay; deviation in copper and steel commodity prices, rare earth export licensing regimes, or offshore energy capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory adoption timelines and technology substitution elasticities. Cross-checking against Lloyd's List vessel equipment databases and classification society installation records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Trommel Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Mobile Light Tower Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Boring Bar Market
Construction Equipment
Yard Crane Market
Construction Equipment
Extrusion Equipment Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Cutting and Bending Machine Market