
 Total Station Market | 2026-2036
Total Station Market Size, Share, and Industry Trends Forecast 2026-2036
Total Station Market Intelligence
The divergence between premium and commodity total station tiers is hardening around angular precision thresholds and software ecosystem lock-in. Hexagon AB leverages its captive CAD and BIM platforms to sustain premium positioning across European surveying firms. Trimble Inc. competes through GNSS fusion architectures that anchor its robotic systems in North American precision agriculture and construction workflows. Suzhou FOIF Co. Ltd. dominates domestic price-sensitive procurement in China's provincial land management agencies.
A total station integrates an electronic theodolite with an electronic distance meter to measure horizontal and vertical angles plus slope distances, achieving angular accuracy down to 0.5 arc-seconds in premium configurations. Its primary purpose is geospatial coordinate determination for engineering stakeout, boundary delineation, and volumetric analysis. Robotic total stations command the highest margin pools where single-operator productivity justifies premium outlays, while reflectorless variants expand fastest in hazardous mining measurement and utility corridor mapping where prism placement proves impractical. Manual total stations retain volume leadership in emerging-market surveying firms with constrained capital budgets and intermittent project pipelines.
ISO 17123 governs field test procedures for geodetic instruments and shapes manufacturer calibration protocols, while China's GB standards for surveying equipment and the EU's CE marking directives under the Radio Equipment Directive constrain market access for Bluetooth and wireless data transfer functionalities. India's BIS certification requirements for electronic surveying instruments create additional compliance layers for imported robotic and motorized units. Stakeholders must monitor whether national mapping agencies harmonize accuracy specifications with GNSS-RTK network densities, as this convergence determines replacement cycles for hybrid instrument fleets.
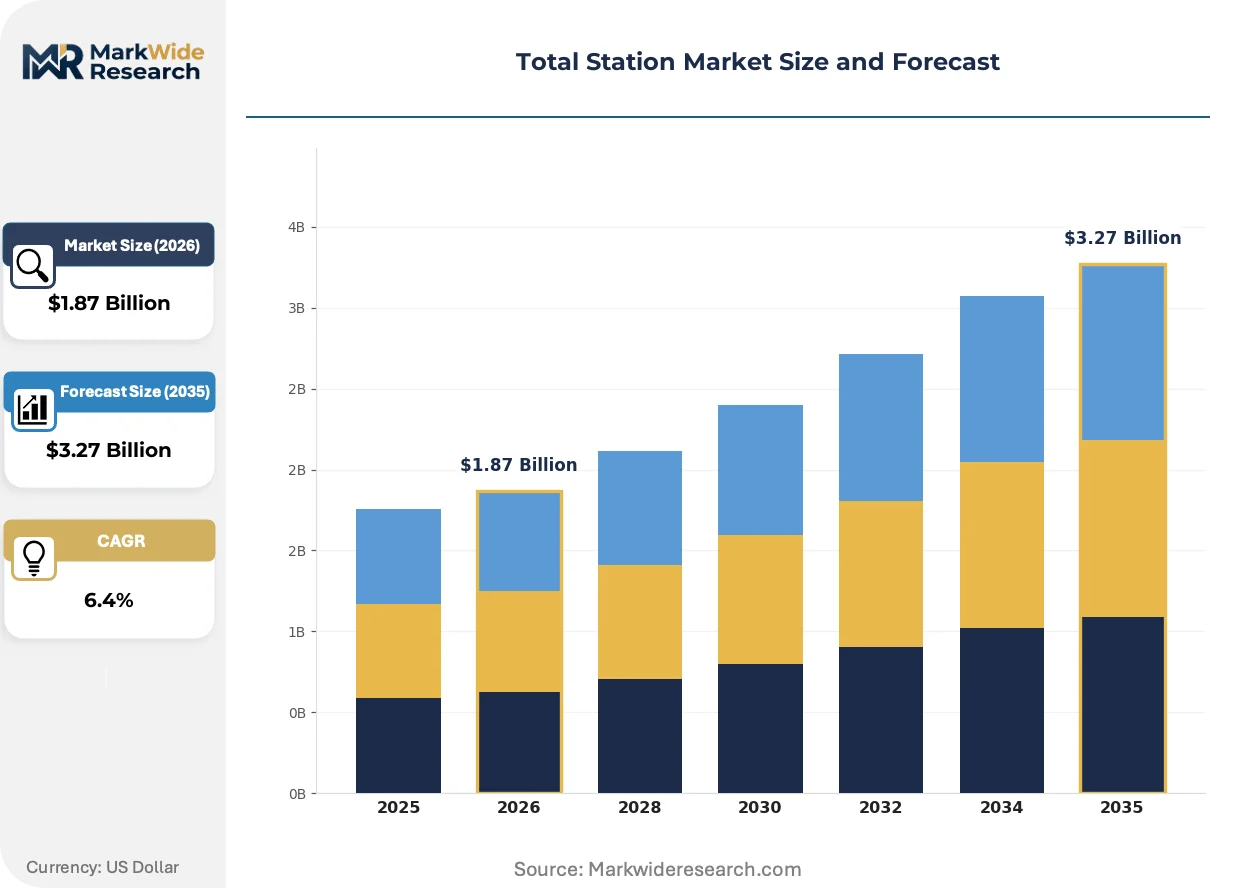
Market Dynamics
Robotic total station architectures are compressing crew sizes and recalibrating capital allocation across surveying firms, as single-operator productivity thresholds override legacy equipment depreciation schedules.
Growth Catalysts
- Indonesia's trans-island highway corridor:Civil engineering contractors face tightened geospatial accuracy mandates from national infrastructure agencies, accelerating motorized total station procurement for certification-compliant stakeout operations.
- ISO 17123 calibration protocols:Harmonized field test procedures reduce instrument verification friction across cross-border projects, lowering compliance overhead for equipment fleets serving multinational engineering contracts.
- Reflectorless measurement technology:Mining operators and utility corridor mappers deploy prism-free total stations in hazardous terrain where conventional reflector placement risks crew safety or proves physically impractical.
Market Restraints
- GNSS-RTK network density convergence:Hybrid instrument replacement cycles face compression as national mapping agencies synchronize accuracy specifications with satellite augmentation infrastructure, eroding total station-only deployment rationale.
- Semiconductor component concentration:Precision angle encoder and laser distance module supply chains cluster in East Asian manufacturing zones, exposing lead time volatility to geoeconomic friction.
- Manual total station residual demand:Emerging-market surveying firms with intermittent project pipelines and constrained capital budgets sustain price pressure on entry-tier equipment categories.
Strategic Opportunities
- Vietnam's Mekong Delta flood-control megaprojects:Robotic total station demand concentrates in large-scale hydraulic engineering where motorized instrument precision supports volumetric analysis for embankment and drainage system design.
- Software ecosystem lock-in:Captive CAD and BIM platform integration creates switching cost barriers that premium manufacturers leverage to sustain margin pools against commodity hardware competitors.
- India's BIS certification requirements:Regulatory layers for imported robotic and motorized units create compliance moats for domestic assemblers and authorized distributors with established certification workflows.
Industry Challenges
- Survey technician skill bifurcation:Robotic total station operation demands proficiency in instrument programming and data management software, widening the gap between trained operators and conventional theodolite-trained field crews.
- Bluetooth and wireless data transfer compliance:EU CE marking directives under the Radio Equipment Directive and China's GB standards impose divergent electromagnetic compatibility testing burdens on firmware development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Station Market |
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Total Stations, Manual Total Stations, Motorized Total Stations, Reflectorless Total Stations, Digital Theodolites Technology: GNSS Integration, Laser Scanning, Bluetooth Connectivity, Wireless Data Transfer, Advanced Angle Measurement Application: Construction Surveying, Mining Measurement, Agricultural Land Survey, Archaeological Mapping, Utility Management End User: Surveying Firms, Civil Engineering Companies, Land Management Agencies, Environmental Consultancies, Infrastructure Developers |
| Companies Covered | Hexagon AB, Trimble Inc., Topcon Corporation, Leica Geosystems AG, Suzhou FOIF Co. Ltd., STONEX Srl, Hi-Target Surveying Instrument Co. Ltd., Sokkia Co. Ltd., South Surveying & Mapping Instrument Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Station Market Strategic Shifts & Innovations
Sensor fusion architectures and autonomous pointing algorithms are redefining productivity benchmarks, while regulatory harmonization efforts reshape equipment certification pathways across national boundaries.
Multi-constellation GNSS integration with total station cores is electrifying robotic instrument positioning workflows. Mining survey departments in Australia's Pilbara region adopt these hybrid units for rapid resection in magnetically disturbed environments. The convergence is compressing standalone GNSS rover demand while elevating total station price bands.
China's GB standards for surveying equipment now mandate enhanced electromagnetic compatibility testing for wireless data transfer modules. Manufacturers serving provincial land management agencies must redesign Bluetooth stacks to satisfy both domestic type approval and export market CE marking. The compliance burden falls heaviest on mid-tier producers lacking dedicated regulatory affairs capacity.
Equipment-as-a-service contracting is displacing outright purchase in European surveying firms with variable project pipelines. Leasing providers bundle calibration, firmware updates, and replacement unit guarantees into per-project fees. The model concentrates in Germany's engineering services sector where seasonal infrastructure spending creates utilization volatility.
Total Station Market Segmentation
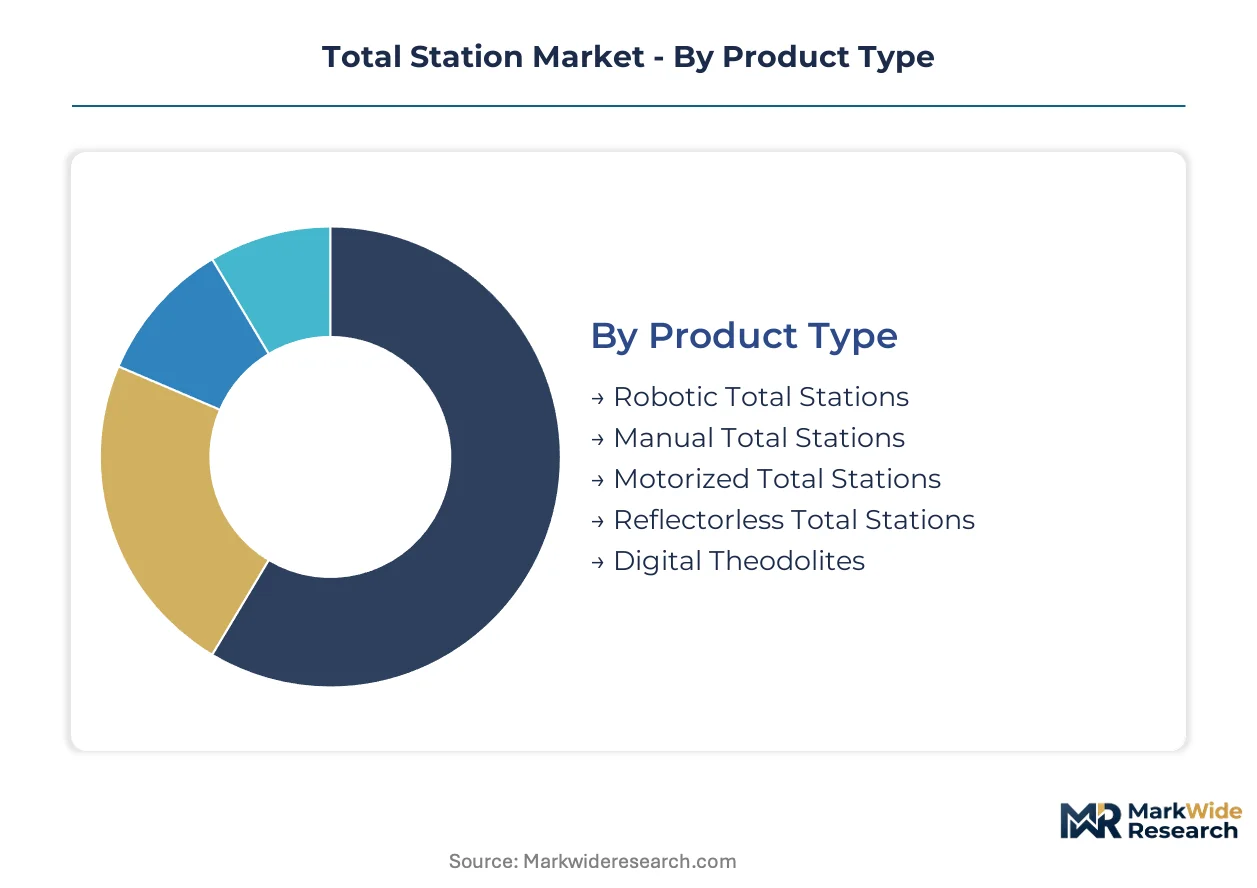
Total station procurement patterns diverge sharply across product architectures and operational contexts. Understanding these fault lines clarifies where premium positioning commands sustainable margins versus where price competition erodes returns.
Product Type:
Integration depth varies dramatically across this category, with autonomous robotic systems operating as standalone survey platforms while manual units function as embedded components within broader measurement workflows.
- Robotic Total Stations:Motorized instrument architectures enable single-operator remote control via tablet or field controller, eliminating traditional two-person survey crews. Demand concentrates in Vietnam's Mekong Delta flood-control megaprojects where motorized precision supports volumetric analysis for embankment design. ISO 17123 calibration protocols for angular accuracy verification elevate replacement thresholds for these premium units.
- Manual Total Stations:Conventional electronic theodolite-distance meter combinations require prism-toting rod operators and on-instrument keyboard entry. Indonesia's provincial surveying firms with intermittent project pipelines sustain residual demand despite crew inefficiency. Capital constraints and intermittent utilization patterns preserve this tier's volume leadership in emerging markets.
- Motorized Total Stations:Automated target tracking reduces operator fatigue on repetitive stakeout sequences without full robotic autonomy. Civil engineering contractors along Indonesia's trans-island highway corridor deploy these for certification-compliant geospatial verification.
- Reflectorless Total Stations:Time-of-flight laser distance measurement eliminates prism dependency for hazardous or inaccessible points. Mining operators in Australia's Pilbara region and utility corridor mappers adopt these where conventional reflector placement risks crew safety.
- Digital Theodolites:Angle-only measurement instruments serve educational institutions and legacy equipment replacement cycles. China's provincial technical colleges maintain procurement volumes for surveyor training programs.
Manual total stations lead volumes today; robotic configurations are gaining share fastest in infrastructure-heavy procurement corridors.
Technology:
Cost tier stratification separates foundational measurement engines from connectivity and fusion layers that command software ecosystem premiums.
- GNSS Integration:Multi-constellation satellite positioning cores hybridize with total station angle-distance engines for rapid resection in magnetically disturbed environments. Australian mining survey departments adopt these units where standalone GNSS rovers face signal degradation.
- Laser Scanning:High-speed point cloud acquisition modules extend total station functionality into as-built documentation and deformation monitoring. European engineering services firms bundle scanning capabilities for infrastructure condition assessment contracts.
- Bluetooth Connectivity:Short-range wireless data transfer to field controllers streamlines measurement logging and reduces cable inventory. China's GB standards mandate enhanced electromagnetic compatibility testing that burdens mid-tier producers.
- Wireless Data Transfer:Long-range radio or cellular modems enable real-time office synchronization for distributed project teams. EU CE marking directives under the Radio Equipment Directive impose divergent firmware testing protocols.
- Advanced Angle Measurement:Sub-arc-second encoder precision distinguishes premium instruments for geodetic network establishment and deformation analysis. National mapping agencies specify these thresholds for public works certification.
Advanced angle measurement anchors premium pricing; GNSS integration shows the steepest expansion trajectory as hybrid architectures displace standalone equipment.
Application:
Customer type fragmentation separates capital-intensive recurring survey operations from project-specific procurement with volatile utilization patterns.
- Construction Surveying:Stakeout, grade control, and as-built documentation for building and infrastructure projects. Southeast Asian civil engineering contractors face tightened geospatial accuracy mandates from national infrastructure agencies.
- Mining Measurement:Pit wall stability monitoring, stockpile volumetrics, and haul road alignment in extractive operations. Reflectorless total stations dominate where prism access proves hazardous or impractical.
- Agricultural Land Survey:Field boundary delineation, drainage design, and precision agriculture infrastructure layout. North American precision farming workflows favor GNSS-fusion robotic systems.
- Archaeological Mapping:Non-invasive site documentation and artifact positioning for cultural heritage preservation. Reflectorless measurement preserves delicate excavation surfaces from physical disturbance.
- Utility Management:Underground corridor mapping, pole line surveys, and easement verification for electricity and telecommunications networks. Single-operator robotic configurations reduce crew exposure in traffic-adjacent work zones.
Construction surveying commands the largest revenue pool; mining measurement offers the fastest volume climb as safety regulations tighten.
End User:
Volume concentration sits with fleet-owning entities while margin expansion follows specialized consultancies with premium service differentiation.
- Surveying Firms:Independent geospatial service providers with instrument fleets serving diverse client portfolios. Equipment-as-a-service contracting gains traction among German firms with seasonal utilization volatility.
- Civil Engineering Companies:Design-build contractors with in-house survey capabilities for project control. Indonesia's trans-island highway and Vietnam's hydraulic megaprojects drive motorized and robotic procurement.
- Land Management Agencies:Governmental bodies responsible for cadastral maintenance, boundary adjudication, and spatial data infrastructure. China's provincial agencies sustain price-sensitive procurement volumes.
- Environmental Consultancies:Specialized firms conducting impact assessments, remediation monitoring, and conservation planning. Robotic single-operator configurations reduce field deployment costs for remote site access.
- Infrastructure Developers:Public-private partnership entities financing and operating transport, energy, and water assets. Long-term concession agreements justify premium instrument lifecycle investments.
Land management agencies anchor volume procurement; environmental consultancies are climbing fastest on specialized service premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surveying instrument technicians concentrate in Germany's precision engineering corridor and China's Yangtze River Delta manufacturing belt. These workforce clusters anchor regional specialization in calibration-intensive geodetic equipment and cost-optimized electronic distance measurement modules respectively.
United States
Precision agriculture contractors in the Midwest deploy GNSS-fusion robotic systems for field boundary staking and drainage design. The Federal Communications Commission regulates radio spectrum allocation for wireless data transfer modules under Part 90 rules. Equipment leasing networks cluster in Illinois and Iowa where seasonal planting cycles create utilization volatility for surveying firms.
Germany
Engineering services firms in Bavaria and Baden-Württemberg adopt equipment-as-a-service contracting to manage seasonal infrastructure spending fluctuations. The Kraftfahrt-Bundesamt enforces electromagnetic compatibility testing for Bluetooth-enabled field controllers under EU Radio Equipment Directive transpositions. Stuttgart's metrology institutes host ISO 17123 calibration laboratories serving cross-border Central European projects.
China
Provincial land management agencies in Jiangsu and Zhejiang sustain price-sensitive procurement volumes for manual total station fleets. The Ministry of Industry and Information Technology administers GB standards compliance for surveying equipment wireless modules. Suzhou's precision electronics corridor manufactures angle encoders and laser distance modules for domestic and export markets.
Indonesia
Civil engineering contractors along the trans-island highway corridor face tightened geospatial accuracy mandates from the national infrastructure agency. BIS-equivalent type approval requirements for imported electronic surveying instruments create compliance layers for robotic and motorized units. Survey technician training programs concentrate in Jakarta and Surabaya to support certification-compliant stakeout operations.
Vietnam
Hydraulic engineering consortia in the Mekong Delta deploy robotic total stations for volumetric analysis of embankment and drainage system designs. The Ministry of Science and Technology coordinates national measurement standards alignment with ASEAN metrology frameworks. Ho Chi Minh City-based surveying firms upgrade motorized instrument fleets to satisfy public works certification requirements.
Total Station Market Key Industry Players
Top-tier vendors anchor premium robotic and GNSS-fusion architectures, while mid-tier specialists compete on manual and motorized configurations for price-sensitive procurement. The vendor base stratifies across three functional tiers: integrated geospatial conglomerates with captive software ecosystems, regional fabrication specialists with domestic certification advantages, and component-focused assemblers serving educational and replacement markets. Competitive positioning hardens around calibration service networks and firmware update continuity rather than hardware specifications alone. M&A activity concentrates on software platform acquisitions, while geographic expansion follows national mapping agency certification harmonization.
Within the integrated geospatial tier, Hexagon AB and Trimble Inc. exemplify contrasting ecosystem strategies. Hexagon leverages its captive CAD and BIM platforms to sustain premium positioning across European surveying firms with high switching costs. Trimble anchors its competitive position in North American precision agriculture and construction workflows through GNSS fusion architectures. Suzhou FOIF Co. Ltd. occupies a distinct tier as a Chinese limited company representing domestic price-sensitive procurement specialization in provincial land management agencies.
| Leading Market Players |
|---|
| Hexagon AB |
| Trimble Inc. |
| Topcon Corporation |
| Leica Geosystems AG |
| Suzhou FOIF Co. Ltd. |
| STONEX Srl |
| Hi-Target Surveying Instrument Co. Ltd. |
| Sokkia Co. Ltd. |
| South Surveying & Mapping Instrument Co. Ltd. |
| Others |
Cost & Logistics Intelligence
EU electromagnetic compatibility mandates under the Radio Equipment Directive gate qualified supply for wireless-enabled total stations and anchor premium-tier pricing access for manufacturers with dedicated regulatory affairs capacity. China's parallel GB standards for surveying equipment create divergent compliance burdens that fragment supplier qualification pools and sustain price premiums for dual-certified producers serving multinational engineering contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment-as-a-service contracting from outright purchase transactions across European and North American surveying firms. Three-tier pricing structure across premium, standard, and economy levels stratifies by angular precision thresholds and software ecosystem integration depth. Cost compression in manual total station tiers is intensifying because emerging-market procurement concentrates in price-sensitive provincial land management agencies. Civil engineering contractors with certification mandates show least price sensitivity, while intermittent-project surveying firms in Indonesia and Vietnam exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from national infrastructure agencies, while authorized distributor networks serve fragmented surveying firm procurement across Southeast Asian markets. Precision angle encoder and laser distance module production clusters in China, Japan, and Germany, with final assembly drawing from Taiwan and South Korea for electronic subcomponents. Single-source vulnerability concentrates in East Asian semiconductor fabrication for wireless data transfer chipsets. Distribution runs through regional calibration service centers that anchor aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ISO 17123 calibration protocol harmonization across national mapping agencies drives replacement demand for certified-compliant instrument fleets.
For Market Incumbents: Deepen captive software ecosystem integration to elevate switching costs against commodity hardware competitors entering through price-sensitive procurement channels. Expand calibration service network density in Vietnam and Indonesia to defend installed base revenue against emerging domestic assemblers with BIS-equivalent certification advantages. Prioritize firmware update continuity programs that extend instrument lifecycle value. For New Entrants and Emerging Players: Begin with reflectorless total station specialization for mining measurement applications where safety regulations tighten and prism access constraints limit incumbent solution flexibility. Target Australia's Pilbara region and Indonesian coal corridor where hazardous terrain measurement demands outstrip qualified supply. Pursue equipment-as-a-service contracting models to bypass capital-constrained buyer segments. For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service providers because certification harmonization across ASEAN metrology frameworks concentrates compliance expertise in fragmented local operators. Long-term viability hinges on software platform acquisitions that capture recurring firmware revenue streams. Monitor GNSS-RTK network density expansion as the signal indicating total station-only deployment rationale erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | ISO 17123-compliant laboratories in Jakarta and Ho Chi Minh City capture certification-driven replacement cycles. |
| GNSS Fusion Architecture Development | Multi-constellation integration with total station cores commands premium positioning in Australian mining survey departments. |
| Software Platform Acquisition | Captive CAD and BIM ecosystems create switching cost barriers that sustain margin pools against commodity competitors. |
| Equipment-as-a-Service Launch | Per-project contracting with bundled calibration reduces utilization volatility for German engineering services firms. |
| Dual Certification Investment | Simultaneous CE marking and GB standards compliance unlocks access to both European and Chinese infrastructure procurement. |
Research Approach
Multiple input streams — primary interviews with surveying firm operators, civil engineering procurement directors, and national mapping agency calibration specialists; secondary validation through customs trade records, ISO 17123 laboratory accreditation databases, and equipment manufacturer SEC filings; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates.
Historical shipment data was cross-referenced against panel input from regional distributor networks to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product architecture tier, technology integration depth, application context, and end-user procurement pattern. CAGRs were derived from instrument replacement cycle analysis and infrastructure spending elasticity coefficients, with specific weighting for GNSS-RTK network density convergence effects and regulatory harmonization milestones.
Several conditions sit outside the modeled scope, including geoeconomic friction impacts on semiconductor lead times and unannounced national mapping agency accuracy specification revisions. Forecasts reflect assumptions about certification compliance continuity and infrastructure mandate enforcement consistency. Periodic stress-testing of base assumptions against actual procurement tender awards and replacement cycle timing is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Asia Pacific Power Tools Market
Tools
Trim Press Market
Tools
Digital Levels Market
Tools
Stationary Wood Planer Market
Tools
Oxy-Fuel Torches Market
Tools
DIY Ball Mill Market
Tools
Vertical Milling Machine Market
Tools
Belt File Sander Market
Tools
Sanding Machine Market
Tools
Global Tools Storage Products Market
Tools
Machining Centers Market
Tools
United States Machine Tools Market
Tools
Pneumatic Tools Market
Tools
Chainsaw Market
Tools
Concrete Saw Market
Tools
Surface Planer Market