
 China Metal Fabrication Equipment Market | 2026-2036
China Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Metal Fabrication Equipment Market Outlook
The China metal fabrication equipment sector is recalibrating around a widening gap between premium electric-hybrid systems and conventional hydraulic units serving price-sensitive buyers. SINOMACH HEAVY EQUIPMENT GROUP CO.,LTD leverages its state-backed scale to dominate heavy structural fabrication lines. Anhui Yingliu Electromechanical Co. Ltd anchors the mid-market through specialized CNC press brake production for automotive tier-one suppliers. China First Heavy Industries controls the premium tier with integrated casting-to-fabrication capabilities for nuclear and aerospace end users.
Metal fabrication equipment encompasses machinery that cuts, bends, welds, and forms metal stock into finished components, typically operating at tolerances of 0.1 mm for laser systems and forming pressures exceeding 1,000 tons on large press brakes. These systems serve as the production backbone for industries requiring precise metal transformation from raw sheet and plate. Laser cutting machines command the largest installed base but face margin compression as domestic suppliers proliferate; electric-hybrid technology is capturing the fastest expansion as MIIT efficiency mandates raise operating costs for pure hydraulic systems. Sheet metal fabrication generates the steadiest replacement demand, while structural fabrication tied to infrastructure stimulus absorbs the heaviest unit volumes.
MIIT efficiency standards and GB certification requirements for industrial machinery are compelling manufacturers to redesign power trains and thermal management systems. The national standardization administration is aligning equipment safety protocols with international IEC frameworks to facilitate export qualification for Belt and Road projects. Stakeholders must track provincial subsidy shifts and raw material alloy pricing volatility to time capacity commitments.
Market Dynamics
China's metal fabrication equipment sector is bifurcating around MIIT energy-efficiency mandates that penalize pure hydraulic systems while rewarding electric-hybrid retrofits. This regulatory compression is accelerating capital rotation toward certified platforms and squeezing uncertified domestic suppliers from mid-tier procurement lists.
Growth Catalysts
- MIIT Efficiency Directives:Mandatory power-consumption benchmarks for industrial machinery are forcing replacement cycles in Jiangsu and Guangdong manufacturing clusters. Tier-one automotive suppliers now specify electric-hybrid systems as procurement preconditions.
- Automotive Electrification:Battery enclosure fabrication requires laser-tolerant, high-tonnage press brakes with thermal management integration. New energy vehicle OEMs are expanding dedicated fabrication lines at 3-4x the density of conventional powertrain facilities.
- Belt and Road Export Alignment:GB standards harmonization with IEC frameworks qualifies Chinese equipment for infrastructure projects across Central Asia and Southeast Asia. SAMR certification reciprocity agreements reduce re-certification costs for qualified manufacturers.
Market Restraints
- Alloy Price Volatility:Structural steel and rare-earth servo motor materials experience 15-25% quarterly swings that compress fabrication line margins. Equipment manufacturers lack pass-through pricing power with state-owned construction conglomerates.
- Servo Drive Supply Concentration:High-precision motion control components concentrate among Japanese and German suppliers, exposing Chinese OEMs to 90-day lead times and currency hedging costs.
- Hydraulic System Stranded Assets:Existing installed base of pure hydraulic press brakes faces accelerated depreciation as MIIT efficiency grades tighten annually, chilling secondary market liquidity.
Strategic Opportunities
- Western Province Industrialization:Sichuan and Shaanxi manufacturing bases remain underpenetrated for premium electric-hybrid systems. Provincial subsidy programs offset 20-30% of equipment costs for qualifying greenfield investments.
- Nuclear Fabrication Certification:MEE environmental clearance and nuclear-grade welding specifications create captive demand for integrated casting-to-fabrication platforms with full traceability documentation.
- AI-Assisted Quality Control:Machine vision integration with legacy CNC systems enables real-time defect detection without full line replacement. Aerospace tier-one suppliers are piloting retrofit kits for existing press brake installations.
Industry Challenges
- Servo-Electric Technician Scarcity:Maintenance and calibration of hybrid electromechanical systems requires skills distinct from hydraulic troubleshooting. Vocational training pipelines lag equipment deployment by 18-24 months in secondary manufacturing cities.
- GB Certification Timeline Compression:New efficiency categories introduced by the national standardization administration require 8-12 month re-certification cycles that delay product launches and freeze R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Metal Fabrication Equipment Market |
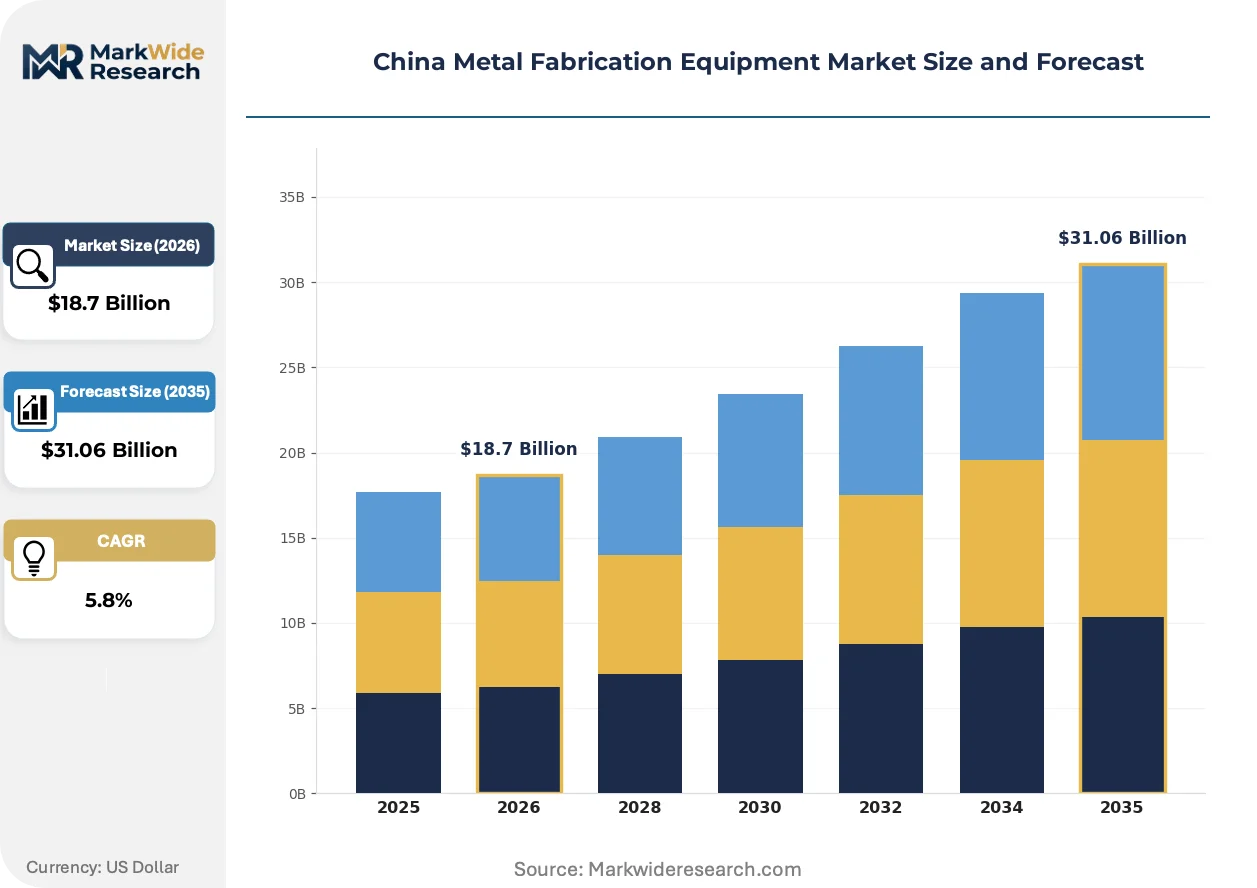
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutting Machines, CNC Press Brakes, Welding Equipment, Bending Machines Technology: Hydraulic, Pneumatic, Electric, Hybrid End User: Aerospace, Automotive Manufacturers, Construction, Electronics Application: Sheet Metal Fabrication, Structural Fabrication, Prototype Production, Custom Fabrication |
| Companies Covered | SINOMACH HEAVY EQUIPMENT GROUP CO.,LTD, Anhui Yingliu Electromechanical Co. Ltd, Western Superconducting Technologies Co. Ltd, Luoyang Xinqianglian Slewing Bearing Co. Ltd, China First Heavy Industries, JL Mag Rare-Earth Co. Ltd, Ningbo Zhenyu Technology Co. Ltd, Wuxi Paike New Materials Technology Co.,Ltd., China International Marine Containers (Group) Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Metal Fabrication Equipment Market Strategic Shifts
Equipment architecture is fragmenting into configurable subsystems that accommodate rapid re-tooling between automotive, aerospace, and energy sector specifications. This modularization is compressing product development cycles and enabling aftermarket revenue streams previously captured by specialized integrators.
Laser cutting workcells are modularizing around swappable resonator configurations and automated material handling towers. Automotive stampers in Guangdong are deploying these platforms to switch between mild steel and aluminum processing within single shift cycles. The technology is modularizing supplier relationships as well, allowing end-users to mix Chinese frame structures with German or Japanese photonics packages.
MIIT's 2024 efficiency grading system for industrial machinery imposes tiered operating cost penalties on equipment below Class I certification. Fabrication shops in Jiangsu are accelerating depreciation schedules for pre-2022 hydraulic assets to avoid energy surcharge exposure. The policy is compressing residual values for uncertified used equipment and redirecting capital toward electric-hybrid platforms with verified Class I ratings.
Service contract unbundling is separating equipment sales from maintenance, training, and software update obligations. State-owned construction equipment lessors in northern China now demand itemized service pricing rather than bundled lifecycle agreements. This shift is fragmenting vendor revenue recognition and forcing equipment manufacturers to build captive service networks or cede margin to third-party technical providers.
China Metal Fabrication Equipment Market Segmentation
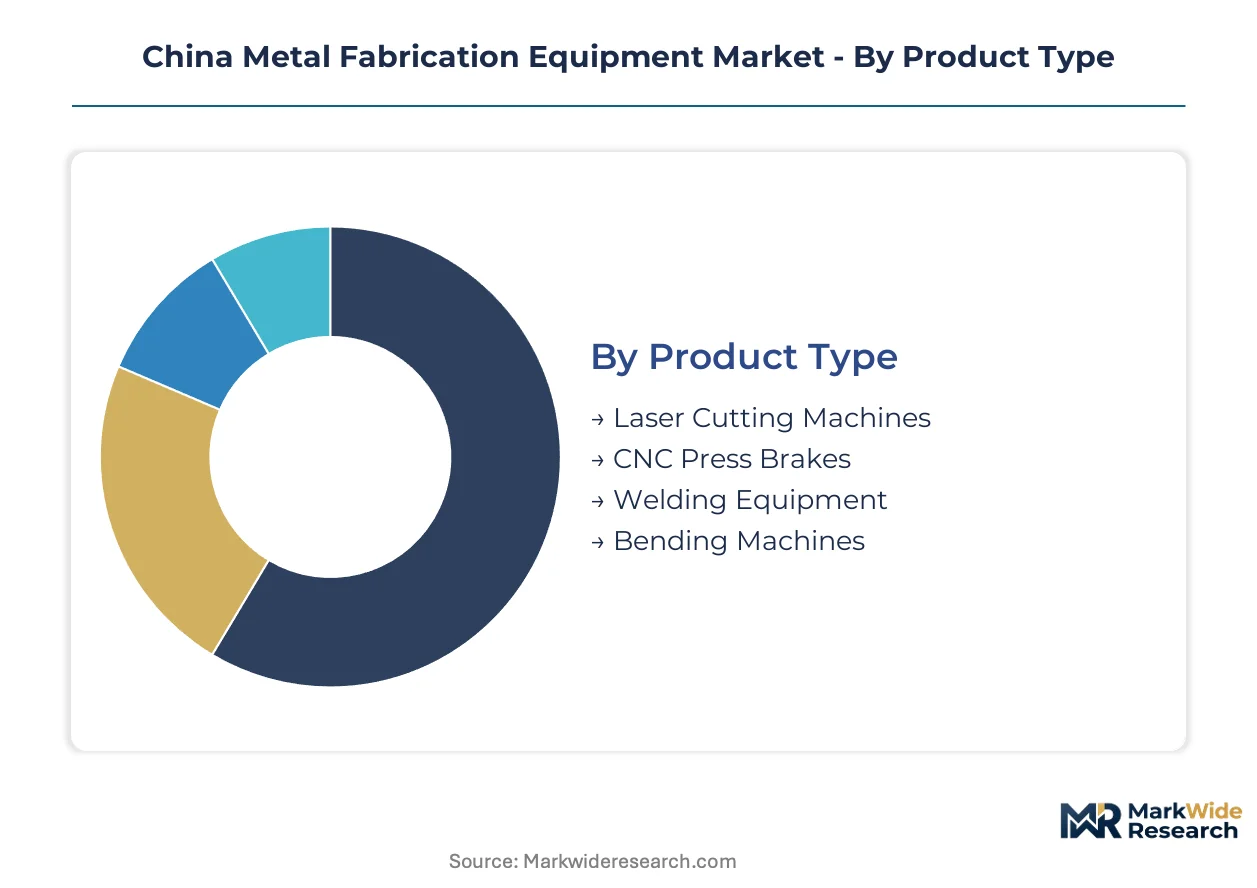
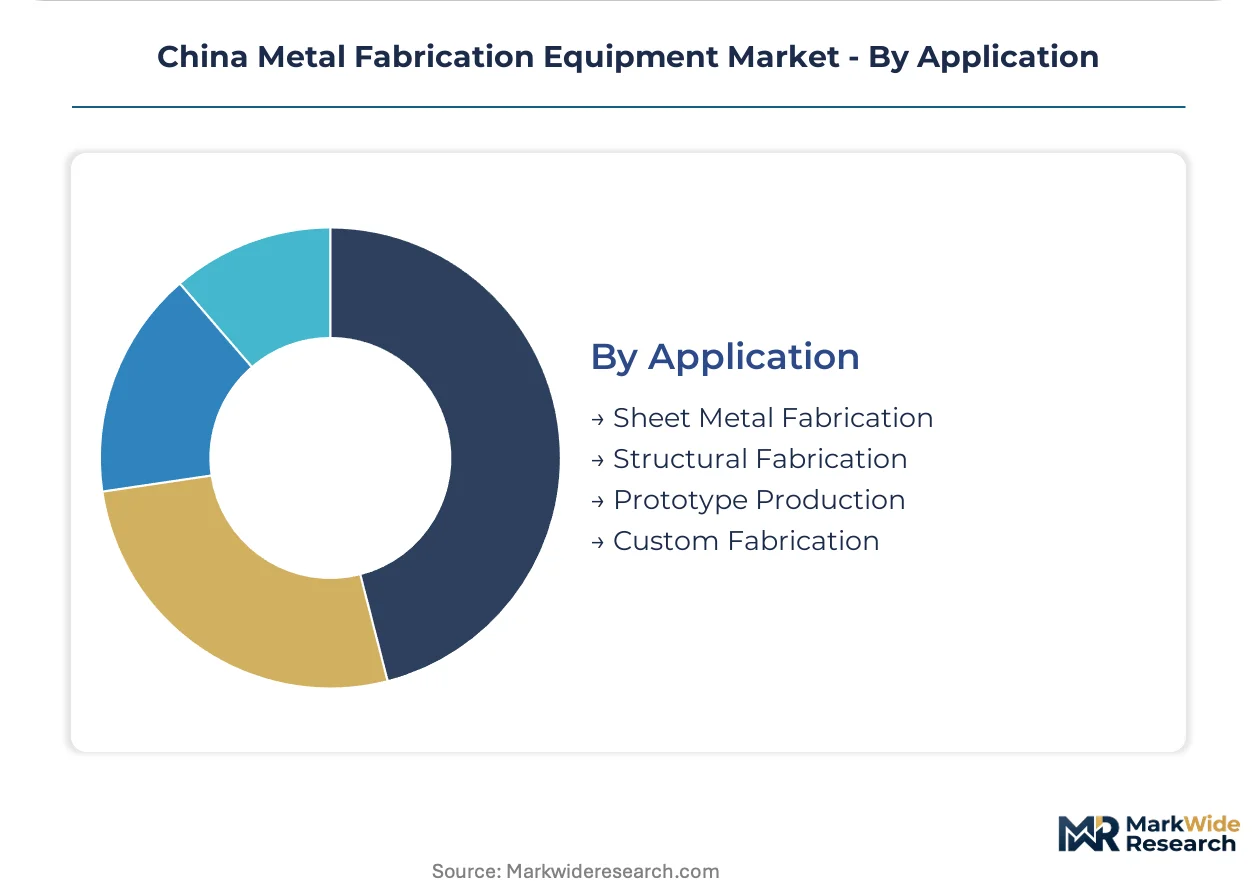
Metal fabrication equipment procurement in China follows distinct technical and application logics that determine replacement timing and vendor selection. Understanding how these segments intersect with MIIT efficiency mandates reveals where capital deployment concentrates.
Product Type:
Upgrade cycles vary dramatically across equipment categories, with energy-intensive platforms facing accelerated obsolescence under tightening efficiency grades.
- Laser Cutting Machines:Fiber and CO2 resonator systems operating at 0.1 mm tolerances dominate Guangdong automotive stampers. Jiangsu sheet metal shops are retrofitting 6kW+ fiber units to process aluminum battery enclosures for new energy vehicle suppliers. MIIT Class I certification now gates procurement at tier-one facilities.
- CNC Press Brakes:Electric-hybrid servo-electric systems with 1,000+ ton forming pressures are displacing hydraulic units in automotive tier-one supply chains. Anhui Yingliu and domestic rivals compete on synchronization accuracy for multi-axis backgauge control.
- Welding Equipment:Automated MIG/TIG cells with integrated seam tracking serve structural steel fabricators tied to state infrastructure contracts.
- Bending Machines:Entry-level mechanical and hydraulic units persist in secondary cities where price sensitivity overrides efficiency metrics.
Laser cutting machines sit at the top of the volume ranking, with CNC press brakes climbing the fastest as automotive electrification reshapes forming requirements.
Technology:
Cost tiers now align cleanly with regulatory compliance grades, creating procurement bifurcation between certified and uncertified platforms.
- Hydraulic:Conventional fluid-power systems face stranded asset risk as MIIT annual efficiency tightening accelerates depreciation. Residual values are collapsing in secondary markets across northern China.
- Electric:Pure servo-electric architectures deliver precision positioning for aerospace fabrication but carry 40-60% capital premiums that limit penetration beyond nuclear and aviation certified shops.
- Hybrid:Combines hydraulic force density with servo-electric efficiency management, capturing fastest expansion as the compliance-cost sweet spot for mid-market automotive suppliers.
- Pneumatic:Compressed-air systems retain niche positioning in light-gauge electronics fabrication where cycle speed trumps energy metrics.
Hybrid technology commands the steepest expansion trajectory, while hydraulic platforms hemorrhage share to regulatory compression.
End User:
Customer type determines specification stringency, with state-linked sectors imposing traceability requirements that filter supplier pools.
- Automotive Manufacturers:New energy vehicle OEMs in Guangdong and Jiangsu are deploying dedicated battery enclosure lines at 3-4x conventional powertrain density. Electric-hybrid press brakes with thermal management integration are specified as procurement preconditions.
- Construction:State-owned conglomerates absorb heavy unit volumes for structural steel processing, but lack pass-through pricing power exposes equipment vendors to alloy cost volatility.
- Aerospace:Tier-one suppliers pilot AI-assisted quality control retrofits on existing CNC installations, prioritizing defect detection over full line replacement.
- Electronics:Precision sheet metal for server racks and enclosures demands laser-tolerant thin-gauge processing in Shenzhen and Dongguan clusters.
Automotive manufacturers anchor volume demand, with aerospace applications gaining share fastest through certification-captive procurement.
Application:
Volume concentration versus margin opportunity splits across fabrication modes, with custom work commanding pricing power but scale residing in repetitive production.
- Sheet Metal Fabrication:Steadiest replacement demand source as Guangdong and Jiangsu job shops cycle aging hydraulic assets to avoid MIIT energy surcharges. Mild steel and aluminum switching capability is becoming standard.
- Structural Fabrication:Infrastructure stimulus absorbs heaviest unit volumes through bridge and building steel processing. SINOMACH and state-backed equipment lessors dominate this capital-intensive segment.
- Prototype Production:Low-volume, high-mix environments in Shenzhen electronics corridors favor quick-changeover modular laser cells.
- Custom Fabrication:Specialty alloy and thick-plate work for energy sector clients commands premium pricing but fragmented order flows.
Structural fabrication leads absolute volume, with sheet metal fabrication expanding most quickly through regulatory-forced replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier fabrication equipment exports, whereas China absorbs the heaviest domestic deployment volume for mid-market electric-hybrid systems. Japan maintains precision-component supply dominance. South Korea and India represent contrasting expansion vectors—Korea through automotive electrification, India through infrastructure stimulus absorption.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg source high-tonnage press brakes for aluminum battery enclosure forming. The KBA enforces machinery safety protocols aligned with EU machinery directives. Stuttgart manufacturing clusters deploy laser-tolerant fabrication cells for Mercedes-Benz and Porsche electrification programs.
Japan
Precision servo drives and motion control components anchor supply relationships with Chinese OEMs facing 90-day lead times. METI industrial efficiency standards shape export equipment specifications. Nagoya fabrication technology corridors concentrate suppliers of high-precision backgauge systems for multi-axis press brake integration.
South Korea
Hyundai and Kia electrification roadmaps demand dedicated battery enclosure fabrication lines at 3-4x conventional density. MFDS certification reciprocity with Chinese SAMR streamlines equipment qualification. Gyeonggi-do manufacturing belts absorb Korean-made laser cutting workcells for new energy vehicle supplier parks.
India
Infrastructure stimulus through the PLI scheme for specialty steel absorbs heavy structural fabrication unit volumes. BIS machinery safety standards tighten import certification requirements. Gujarat and Maharashtra industrial corridors deploy Chinese-origin hydraulic press brakes for bridge and building steel processing.
United States
Reshoring incentives through the IRA drive capital expenditure in domestic fabrication capacity for EV supply chains. OSHA machinery safety enforcement shapes equipment specification requirements. Michigan and Tennessee automotive corridors source electric-hybrid press brakes for battery enclosure production lines.
China Metal Fabrication Equipment Market Competitive Environment
Top-tier vendors anchor state-backed heavy equipment fabrication, while mid-market specialists compete on CNC synchronization accuracy. The vendor base stratifies across three functional tiers: integrated casting-to-fabrication platforms, electric-hybrid press brake specialists, and modular laser system integrators. Consolidation pressure concentrates among hydraulic equipment manufacturers facing MIIT efficiency grade obsolescence. Strategic moves center on backward integration into servo drive supply chains and geographic expansion into western Chinese provinces.
Within the state-backed heavy equipment tier, SINOMACH HEAVY EQUIPMENT GROUP CO.,LTD and China First Heavy Industries occupy positions reflecting scale advantages in structural fabrication lines. Among mid-market CNC specialists, Anhui Yingliu Electromechanical Co. Ltd exemplifies the electric-hybrid press brake archetype serving automotive tier-one procurement mandates. These three entities represent distinct competitive positioning vectors—state conglomerate scale, mid-market technology specialization, and integrated premium-tier capability—without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| SINOMACH HEAVY EQUIPMENT GROUP CO.,LTD |
| Anhui Yingliu Electromechanical Co. Ltd |
| Western Superconducting Technologies Co. Ltd |
| Luoyang Xinqianglian Slewing Bearing Co. Ltd |
| China First Heavy Industries |
| JL Mag Rare-Earth Co. Ltd |
| Ningbo Zhenyu Technology Co. Ltd |
| Wuxi Paike New Materials Technology Co.,Ltd. |
| China International Marine Containers (Group) Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Structural steel futures volatility cascades through fabrication equipment pricing tiers, compressing margins for hydraulic press brake manufacturers while amplifying premiums for MIIT-certified electric-hybrid systems. Equipment vendors face pass-through constraints with state-owned construction conglomerates, forcing cost absorption in mid-market segments.
Pricing Analysis
Capacity additions in Jiangsu and Guangdong are reshaping price floors for CNC press brakes as domestic electric-hybrid production scales. Three-tier pricing structure across premium, standard, and economy levels aligns with MIIT efficiency certification grades, with Class I-rated systems commanding substantial premiums over uncertified hydraulic alternatives. Price differentiation hinges on servo drive sourcing origin and thermal management integration depth. Cost compression in entry-level mechanical bending units is intensifying because alloy price swings erode already-thin margins. State infrastructure contractors exhibit lowest price sensitivity due to subsidy offset mechanisms, while secondary city job shops demonstrate acute responsiveness to equipment financing terms.
Supply Chain Analysis
Refurbishment flows for pre-2022 hydraulic assets are accelerating as MIIT efficiency grades strand installed bases, creating secondary market liquidity challenges and parts harvesting opportunities. Servo drive production concentrates in Japan and Germany, with Chinese OEMs drawing from Nagoya precision corridors and Bavarian motion control specialists. Rare-earth magnet materials and high-grade structural steel constitute critical input dependencies. Single-source vulnerability in photonics packages for fiber laser resonators exposes integrators to extended lead time fluctuations. Distribution runs through provincial equipment lessors in northern China and direct OEM relationships with automotive tier-one suppliers in Guangdong clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's metal fabrication equipment sector operates as a regulatory compounder where MIIT efficiency mandates accelerate capital rotation and compress replacement cycles across installed bases.
For Market Incumbents: Lock in captive supply relationships for servo drive components to mitigate Japanese and German supplier concentration risk. Deepen backward integration into rare-earth magnet processing to offset quarterly alloy price volatility exposure. Defensive consolidation around nuclear-grade welding certification capabilities protects margin pools from emerging casting-to-fabrication integrators. For New Entrants and Emerging Players: MIIT efficiency directives in western provinces open a window for electric-hybrid system penetration where incumbent service networks remain thin. Sichuan and Shaanxi manufacturing bases offer lowest competitive density for premium equipment deployment. Target automotive battery enclosure fabrication lines through thermal management integration specialization as the most penetrable application segment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-market CNC press brake specialists possessing electric-hybrid retrofit expertise and established automotive tier-one relationships. Long-term viability centers on regulatory compliance trajectory rather than cyclical capacity expansion. Monitor MIIT annual efficiency grade tightening announcements and provincial subsidy program renewals as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Supply | Mitigates 90-day lead time exposure from Nagoya and Bavarian component suppliers. |
| Nuclear Fabrication Certification Investment | Captures MEE-cleared demand from integrated casting-to-fabrication platform buyers. |
| AI-Assisted Quality Control Retrofit Kits | Enables aftermarket revenue capture from aerospace tier-one supplier installed bases. |
| Western Province Service Network Buildout | Secures first-mover positioning in Sichuan and Shaanxi greenfield manufacturing investments. |
| GB Standards Harmonization with IEC Frameworks | Qualifies equipment for Belt and Road infrastructure procurement across Central Asia. |
Study Parameters
Multiple input streams — plant engineer interviews, OEM procurement team discussions, aftermarket service head consultations, and provincial equipment lessor dialogues — were reconciled against customs trade records, MIIT efficiency directive filings, SAMR certification databases, and SEC disclosures from multinational component suppliers. Bottom-up equipment deployment tracking across Jiangsu and Guangdong manufacturing clusters was triangulated with top-down market sizing from structural steel consumption correlations.
Historical capacity installation patterns were cross-referenced against panel input from maintenance directors and technical R&D directors to inform trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type, technology architecture, end-user industry, and application mode dimensions. CAGRs were derived from replacement cycle acceleration factors tied to MIIT regulatory tightening schedules and automotive electrification capex intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt alloy price spikes or sudden provincial subsidy program suspensions. Practitioners should monitor MIIT annual efficiency grade publication schedules and rare-earth export quota adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Collating Machinery Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
North America Mobile Light Tower Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Vertical Machining Centers Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Canada Construction Equipment Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Stamping Machines Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Global Portable Light Towers Market