
 Global Laundry Folding Machine Market | 2026-2036
Global Laundry Folding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laundry Folding Machine Market Outlook
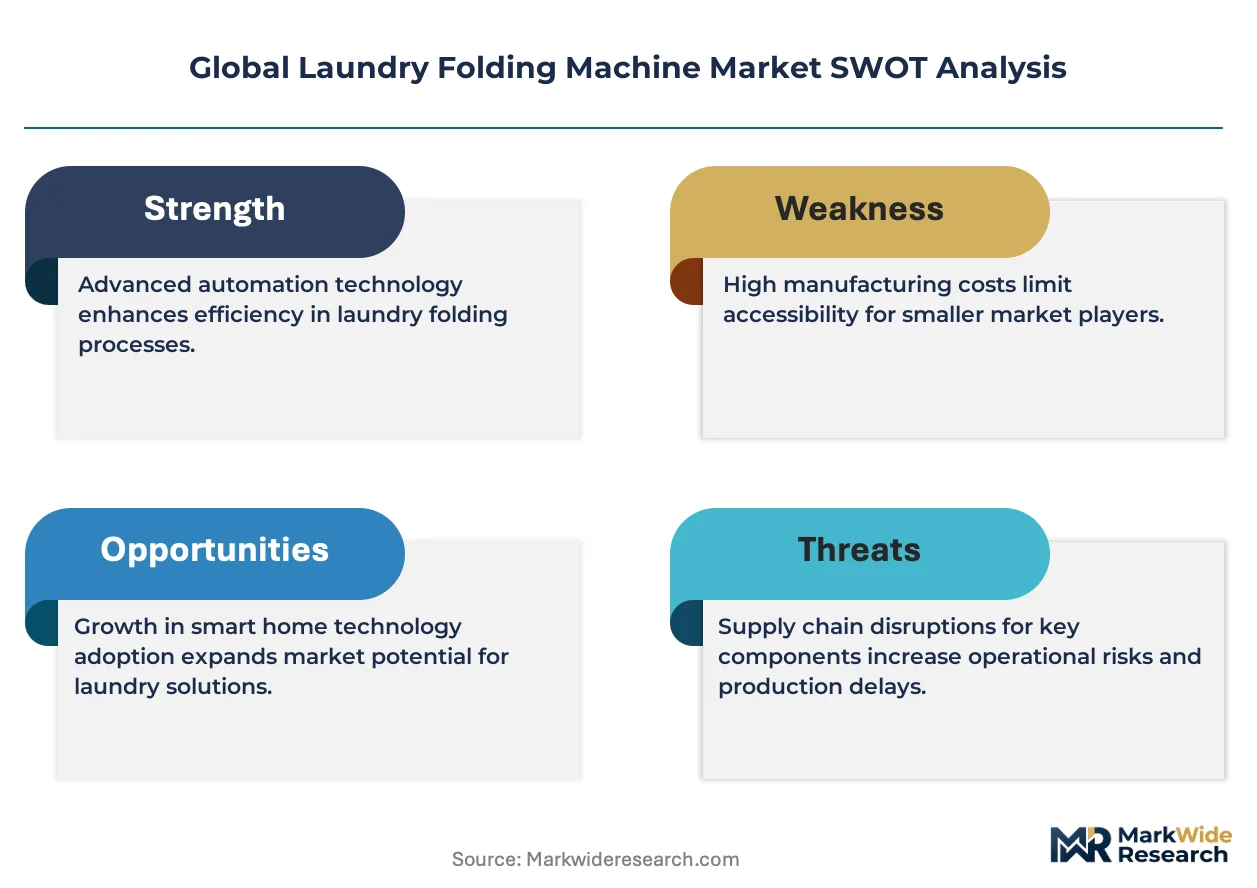
The EU Ecodesign Directive is hardening efficiency benchmarks for textile finishing equipment sold across member states. Herbert Kannegiesser GmbH leverages its engineering heritage to dominate high-throughput commercial installations. Panasonic Corporation anchors its position through sensor-based robotics developed for precision household applications. Sara Equipments competes on cost-optimized mechanical systems tailored to South Asian industrial laundries.
A laundry folding machine automates the post-wash process of flattening, aligning, and stacking textiles using mechanical arms, conveyor belts, or robotic manipulators with throughput rates exceeding 600 items per hour in commercial configurations. The equipment serves hotels, hospitals, and centralized linen facilities seeking labor reduction and output consistency. Automatic systems lead the product type dimension by installed base, though robotic technology is expanding fastest as vision-guided folding improves accuracy for irregular garments. The hospitality end-user segment captures the dominant share of current revenue, while industrial laundries represent the emerging margin pool as contract operators scale automation.
The EU F-Gas Regulation shapes refrigerant choices in steam-assisted folding systems, while CE marking governs electrical safety compliance for machines deployed across Europe. The US OSHA maintains ergonomic standards that push commercial operators toward automated handling to reduce repetitive strain liabilities. Japan's METI promotes next-generation manufacturing subsidies that accelerate sensor-based folding R&D. Stakeholders must monitor how tightening energy standards in multiple jurisdictions reshape total cost of ownership calculations for fleet replacement decisions.
Market Dynamics
Energy efficiency mandates under the EU Ecodesign Directive are forcing commercial laundries to accelerate fleet replacement cycles, compressing capital deployment timelines and reshaping vendor selection criteria toward lifecycle cost optimization.
Growth Catalysts
- Labor Cost Arbitrage:Hospitality operators in Germany and France are automating linen handling to offset minimum wage escalations and reduce repetitive strain injury claims under OSHA-equivalent workplace safety frameworks.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in steam-assisted folding systems is creating replacement demand for heat-pump-based equipment with lower global warming potential ratings.
- Vision-Guided Robotics:Sensor arrays and machine learning algorithms are expanding folding accuracy for irregular garments, enabling automation penetration into healthcare linen services previously resistant to mechanical handling.
Market Restraints
- Stainless Steel Input Volatility:Conveyor frame fabrication depends on nickel-alloy steel grades subject to London Metal Exchange price swings, compressing margin predictability for equipment assemblers.
- Control System Concentration:Programmable logic controller supply concentrates among German and Japanese automation specialists, exposing machine builders to semiconductor allocation bottlenecks.
- Technical Limitation:Current robotic manipulators struggle with mixed-fiber textiles exhibiting variable friction coefficients, limiting throughput consistency for industrial laundries processing diverse hotel linen streams.
Strategic Opportunities
- India Contract Laundry Expansion:Hospital outsourcing of linen services in Maharashtra and Karnataka is creating first-time automation demand among mid-scale operators previously dependent on manual folding.
- Japan METI Subsidies:Next-generation manufacturing grants are accelerating sensor-based folding R&D, positioning domestic vendors to export precision household systems to Southeast Asian markets.
- Leasing Channel Innovation:Equipment-as-a-service models are penetrating the US hospitality sector, converting capex-averse boutique hotel chains to automated systems through per-piece pricing structures.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of pneumatic actuators with vision systems requires specialized technicians, with training pipelines lagging installation growth in emerging automation markets.
- CE Marking Timeline Compression:Evolving electrical safety standards for textile machinery are extending certification cycles, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laundry Folding Machine Market |
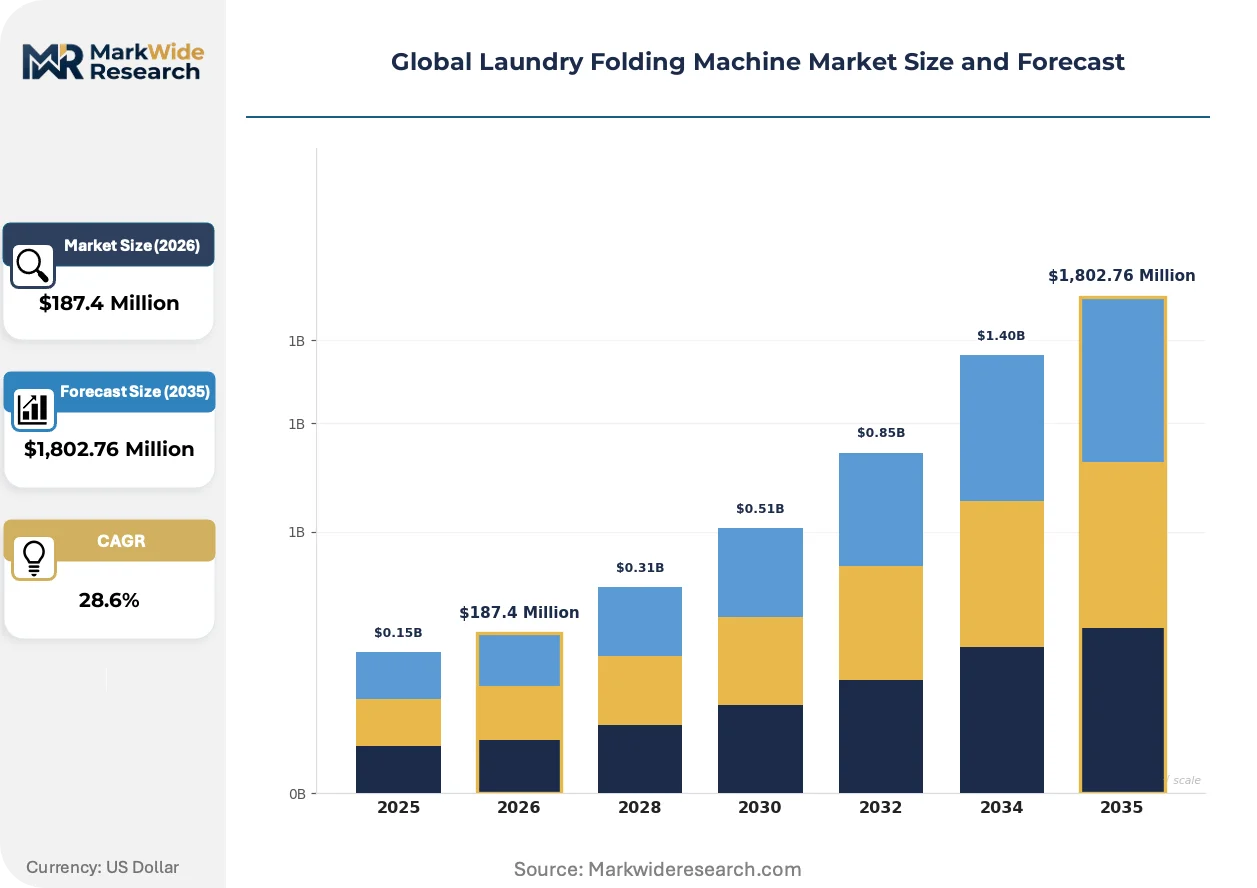
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Commercial Technology: Robotic, Mechanical, Sensor-based, Steam-assisted End User: Household, Hospitality, Retail, Industrial Installation: Standalone, Integrated, Portable, Fixed |
| Companies Covered | Shanghai Jinyi Washing Equipment Manufacturing, Herbert Kannegiesser GmbH, FoldiMate, Sara Equipments, Consolidated Laundry Machinery, Electrolux Professional, Ramsons Garment Finishing Equipment Pvt. Ltd., Sunrise Garment Machinery Pvt. Ltd., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laundry Folding Machine Market Strategic Shifts
Robotic manipulation capabilities are advancing faster than procurement organizations can absorb them, creating a deployment gap where technical possibility outpaces operational readiness across commercial laundry verticals.
Computer vision systems paired with adaptive grippers are expanding into hospitality linen services that previously rejected automation due to garment variability. Major hotel chains in Germany and Austria are piloting these installations to handle mixed-size bedding without manual pre-sorting. The technology is expanding into mid-scale operators by compressing the minimum viable throughput threshold below 400 items per hour.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules for steam-assisted equipment, compelling manufacturers to redesign thermal systems around CO2 heat pumps. Industrial laundries in Belgium and the Netherlands face the most acute compliance deadlines, accelerating retrofit decisions ahead of the 2030 benchmark. CE marking requirements for modified electrical architectures are extending engineering validation cycles by four to six months.
Buying committees at hospital systems are consolidating vendor relationships around full-lifecycle service agreements rather than transactional equipment purchases. Distributors in the US Southwest are responding by bundling preventive maintenance with hardware sales, displacing pure-resale margins with recurring revenue streams. This pattern is most visible in Texas and Florida, where health system consolidation has concentrated procurement authority among fewer administrative entities.
Global Laundry Folding Machine Market Segmentation
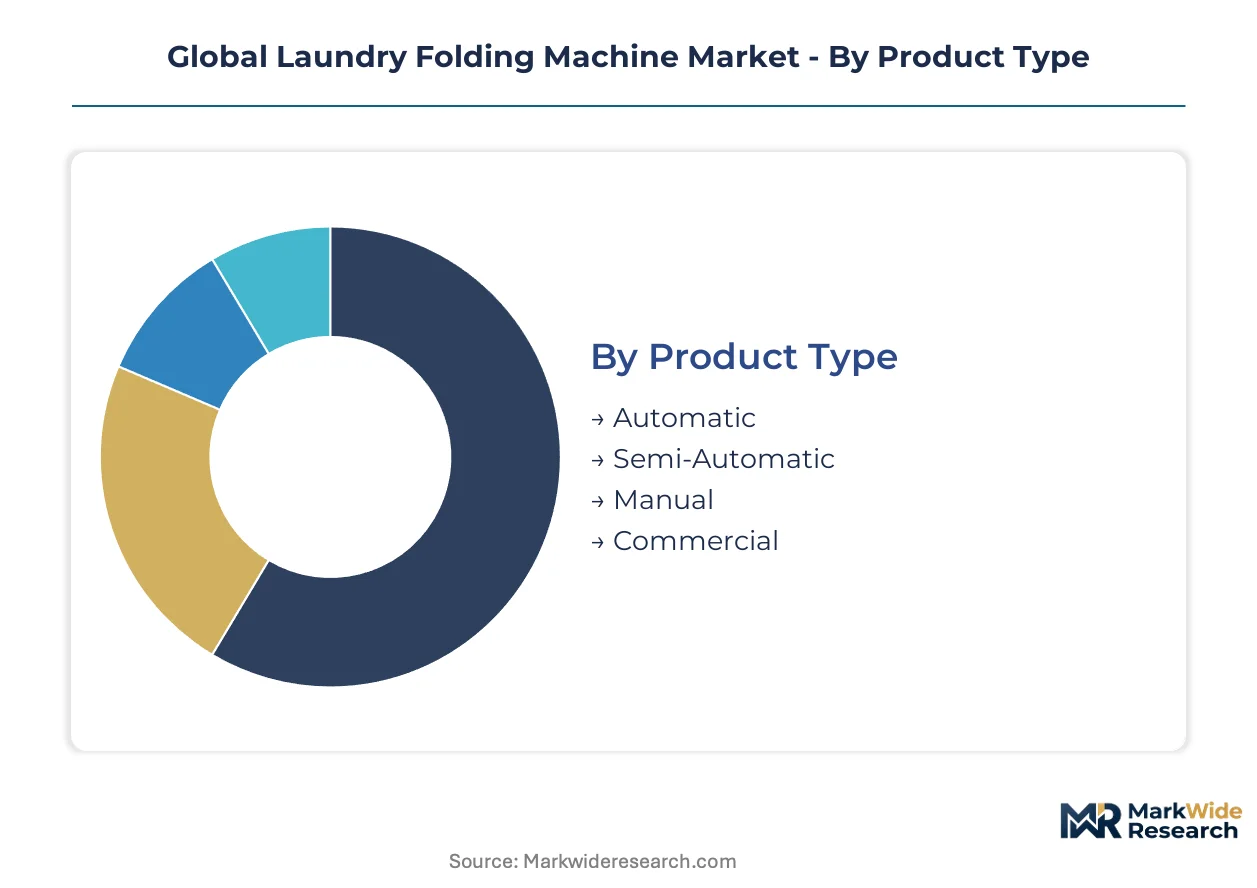
Equipment segmentation in the laundry folding machine market determines regulatory pathways, capital intensity, and service model design. Distinct product configurations face divergent certification burdens across CE marking, OSHA compliance, and energy efficiency mandates.
Product Type:
CE marking governs electrical safety for automatic and semi-automatic systems sold across Europe, while manual units face lighter conformity assessment. OSHA ergonomic standards in the US push commercial operators toward powered configurations to reduce workplace injury exposure.
- Automatic:Fully motorized systems with programmable logic controllers handle throughput exceeding 600 items per hour. Demand concentrates in German industrial laundries serving hospital consortiums and hotel chains, driven by EU Ecodesign Directive efficiency deadlines.
- Semi-Automatic:Hybrid designs requiring operator intervention for loading and final stacking. French hospitality operators favor these units for mid-scale properties balancing labor costs against full automation capex.
- Manual:Human-powered folding aids with minimal mechanical assistance. South Asian contract laundries in Maharashtra deploy these for cost-sensitive hospital outsourcing contracts.
- Commercial:Heavy-duty configurations engineered for continuous operation in centralized linen facilities. Belgian operators retrofit these to meet F-Gas Regulation refrigerant phase-down requirements.
Automatic systems sit at the top of the volume ranking, with Commercial configurations climbing the fastest as fleet replacement accelerates under tightening energy mandates.
Technology:
Technology selection drives thermal system design and refrigerant choices under the EU F-Gas Regulation, with steam-assisted and robotic platforms facing the steepest compliance redesign requirements.
- Robotic:Vision-guided manipulators with adaptive grippers process irregular garments without pre-sorting. Austrian hotel chains pilot these installations for mixed-size bedding streams.
- Mechanical:Pneumatic and cam-driven folding arms deliver consistent output for standardized linen formats. German engineering heritage dominates this segment through precision component supply chains.
- Sensor-based:Arrays of photoelectric and capacitive detectors enable real-time fabric detection and fold calibration. Japan's METI subsidies accelerate R&D export to Southeast Asian markets.
- Steam-assisted:Thermal finishing systems using heat pumps or refrigerant-based steam generation. Dutch industrial laundries face acute retrofit deadlines ahead of 2030 benchmarks.
Mechanical technology retains the largest installed base, though Robotic platforms are gaining share fastest as vision systems compress minimum viable throughput thresholds.
End User:
End-user segmentation shapes procurement authority concentration and service contract structures, with hospital systems consolidating vendor relationships around lifecycle agreements.
- Hospitality:Hotels and resorts seeking labor reduction and output consistency. Texas and Florida health system consolidation has concentrated procurement authority among fewer administrative entities.
- Industrial:Centralized linen facilities and contract operators scaling automation. Karnataka hospital outsourcing creates first-time automation demand among mid-scale operators.
- Household:Residential consumers with space-constrained installation requirements. Japanese vendors target precision household systems for export growth.
- Retail:Dry cleaning chains and garment service providers with mixed-textile processing needs. Variable friction coefficients in mixed-fiber textiles limit throughput consistency for robotic handling.
Hospitality captures the dominant revenue position, with Industrial laundries expanding most quickly as contract operators scale automation across emerging markets.
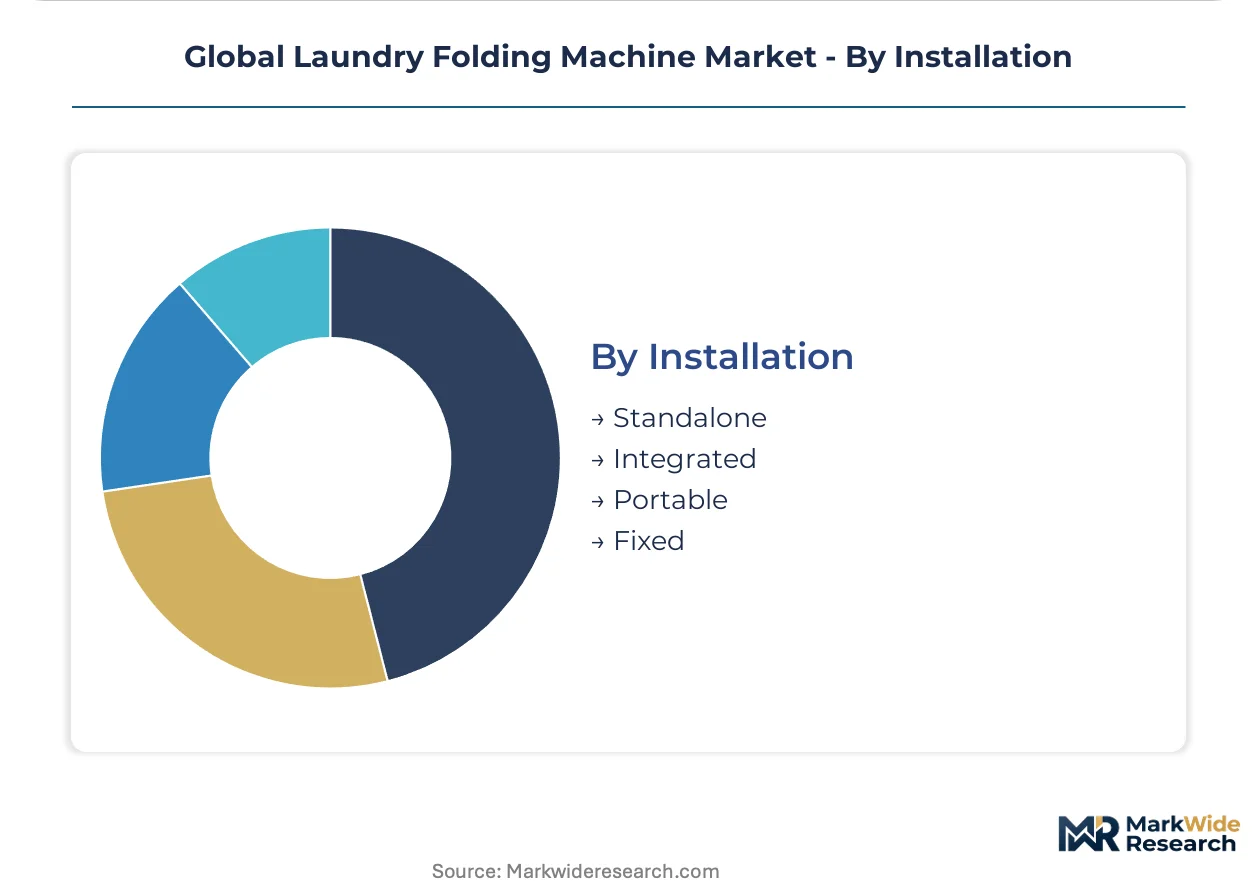
Installation:
Installation configuration determines facility retrofit complexity and capital deployment flexibility, with integrated systems requiring longest engineering validation cycles under evolving CE marking standards.
- Standalone:Self-contained units requiring minimal facility modification. US boutique hotel chains adopt these through equipment-as-a-service per-piece pricing structures.
- Integrated:Conveyor-linked systems embedded within continuous processing lines. Extended certification cycles delay revenue recognition for new product introductions.
- Portable:Mobile configurations for temporary or seasonal capacity needs. Seasonal resort operators in Alpine regions deploy these for summer/winter demand peaks.
- Fixed:Permanent infrastructure with dedicated utility connections. German industrial laundries favor these for high-throughput hospital and hotel contracts.
Fixed installations lead by cumulative deployment value, with Standalone units expanding most quickly as leasing channels penetrate capex-averse customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial laundry automation originated in post-war Germany, where engineering-intensive textile processing clusters scaled mechanized finishing systems for centralized hospital and hotel linen services. This heritage established technical benchmarks that shaped equipment design across European and Asian manufacturing centers.
Germany
Industrial laundries in North Rhine-Westphalia serve major hotel chains and healthcare consortiums with high-throughput automated systems. EU Ecodesign Directive efficiency mandates accelerate fleet replacement timelines among operators in the Ruhr industrial corridor. Herbert Kannegiesser GmbH anchors engineering supply chains from its Vlotho headquarters, exporting precision mechanical systems to Benelux markets.
United States
OSHA ergonomic standards push commercial operators toward automated handling to reduce repetitive strain liabilities in high-volume linen facilities. Hospital system consolidation in Texas and Florida concentrates procurement authority among fewer administrative entities. Boutique hotel chains in the Southwest adopt equipment-as-a-service models through distributors bundling preventive maintenance with hardware sales.
Japan
METI next-generation manufacturing subsidies accelerate sensor-based folding R&D for precision household applications. Domestic vendors target Southeast Asian export markets with compact systems designed for space-constrained residential installations. Osaka-based engineering clusters develop adaptive gripper technologies for irregular garment handling.
India
Hospital outsourcing of linen services in Maharashtra and Karnataka creates first-time automation demand among mid-scale contract operators. CDSCO medical device frameworks influence equipment certification for healthcare-adjacent textile processing. Sara Equipments competes from Coimbatore with cost-optimized mechanical systems tailored to South Asian industrial laundries.
Belgium
Industrial laundries face acute EU F-Gas Regulation compliance deadlines ahead of 2030 refrigerant phase-down benchmarks. Steam-assisted folding systems in the Flanders region undergo retrofit cycles toward CO2 heat pump thermal architectures. CE marking requirements for modified electrical architectures extend engineering validation cycles by four to six months.
Global Laundry Folding Machine Market Competitive Environment
The competitive structure tilts toward engineering-intensive specialists with multi-decade mechanical heritage. Vendor concentration remains moderate, with tiered differentiation between precision German fabricators, Japanese sensor-technology developers, and cost-optimized South Asian assemblers. Strategic archetypes separate into high-throughput commercial system builders, precision household robotics developers, and contract-manufacturing exporters. Dominant competitive moves include geographic expansion through distributor partnerships and technology licensing agreements to access emerging automation markets.
Among German engineering specialists, Herbert Kannegiesser GmbH occupies a position exemplifying high-throughput commercial installation dominance. Panasonic Corporation anchors the precision household tier through its sensor-based robotics heritage. Sara Equipments represents the cost-optimized archetype serving South Asian industrial laundries. Shanghai Jinyi Washing Equipment Manufacturing and Electrolux Professional sit within the diversified commercial equipment tier, while FoldiMate exemplifies venture-backed robotics development targeting consumer segments.
| Leading Market Players |
|---|
| Shanghai Jinyi Washing Equipment Manufacturing |
| Herbert Kannegiesser GmbH |
| FoldiMate |
| Sara Equipments |
| Consolidated Laundry Machinery |
| Electrolux Professional |
| Ramsons Garment Finishing Equipment Pvt. Ltd. |
| Sunrise Garment Machinery Pvt. Ltd. |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
The EU Ecodesign Directive gates qualified supply and premium-tier pricing access for laundry folding machine vendors, forcing CE-marked efficiency compliance as a prerequisite to German and Benelux hospital procurement committees while excluding uncertified assemblers from high-margin fleet replacement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated robotic systems from mechanical conveyor configurations and manual folding aids. CE marking tier and after-sales service bundling drive price differentiation, with German engineering heritage commanding brand premiums. Cost compression in economy-tier mechanical units is intensifying because South Asian contract manufacturers scale export capacity. Hospital consortiums in North Rhine-Westphalia exhibit lowest price sensitivity, while Maharashtra mid-scale operators remain most cost-constrained.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns serving Benelux and Central European industrial laundries. Manufacturing concentrates in Germany, Japan, and India, with precision mechanical components drawing from Ruhr Valley engineering clusters. Nickel-alloy stainless steel and programmable logic controllers from Japanese automation specialists constitute critical input dependencies. Single-source vulnerability in semiconductor allocation for control systems poses structural risk. Distribution runs through authorized dealer networks bundling preventive maintenance with hardware placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital procurement committees prioritize full-lifecycle service agreements over transactional equipment purchases, elevating vendors with certified efficiency ratings and captive service infrastructure.
For Market Incumbents: Deepen backward integration into precision mechanical component fabrication to offset London Metal Exchange nickel volatility and secure margin predictability. Prioritize CE marking pre-certification for CO2 heat pump thermal architectures ahead of EU F-Gas Regulation deadlines. Consolidate distributor relationships in Texas and Florida where health system concentration concentrates procurement authority among fewer administrative entities. For New Entrants and Emerging Players: Begin with Karnataka and Maharashtra hospital outsourcing contracts where first-time automation demand among mid-scale operators creates white-space opportunity. Target standalone equipment-as-a-service models for US boutique hotel chains seeking capex avoidance through per-piece pricing structures. Lead with sensor-based compact systems for Southeast Asian residential export markets accelerated by Japan METI subsidy spillover. For Investors and Strategic Acquirers: Roll-up economics work for precision mechanical specialists with multi-decade German engineering heritage because fragmented vendor relationships among hospital systems favor consolidated full-lifecycle service providers. Target mid-scale commercial equipment assemblers with established CE marking pathways and captive aftermarket service revenue. Watch F-Gas Regulation compliance retrofit acceleration in Belgium and the Netherlands as inflection signal for heat-pump thermal system demand.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Accelerates revenue recognition for CO2 heat pump architectures ahead of EU F-Gas deadlines. |
| Equipment-as-a-Service Model Launch | Converts capex-averse US boutique hotel chains through per-piece pricing structures. |
| Backward Integration into Component Fabrication | Captures margin from nickel-alloy conveyor frame production in Ruhr engineering clusters. |
| Sensor-Based Robotics R&D Expansion | Leverages Japan METI subsidies for Southeast Asian precision household system exports. |
| Full-Lifecycle Service Agreement Bundling | Aligns with Texas and Florida hospital system procurement consolidation patterns. |
Study Parameters
Bottom-up hospitality and healthcare end-use modeling reconciled against top-down German and Japanese manufacturing capacity tracking forms the analytical core. Primary interviews with maintenance directors at industrial laundries, OEM procurement teams, aftermarket service heads, and hospital purchasing committees combined with secondary validation against CE marking databases, EU Ecodesign Directive compliance filings, and METI subsidy disclosure records. Triangulation across these sources anchors volume and value estimates.
The input-output matrix maps equipment type, technology platform, end-user segment, and installation configuration against throughput capacity and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation across the projection horizon. Forecast inputs include EU F-Gas Regulation phase-down schedules and hospital outsourcing penetration rates in Maharashtra and Karnataka.
Caveats apply where refrigerant technology transitions or semiconductor allocation bottlenecks could materially shift the outlook for steam-assisted system retrofits and control system availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Global Conveyor Maintenance Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market