
 Vertical Machining Centers Market | 2026-2036
Vertical Machining Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Machining Centers Market Analytics
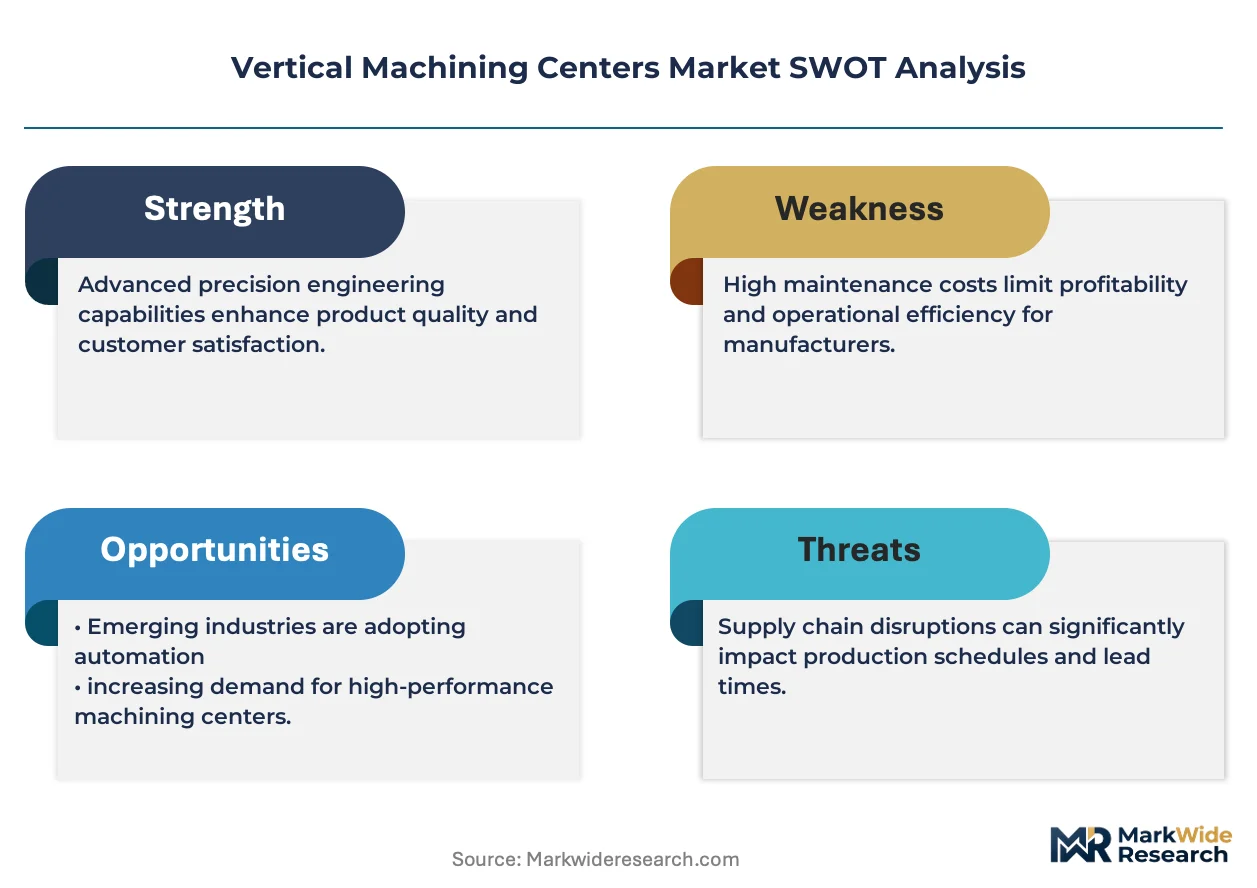
Modular spindle and tooling packages is pivoting how buyers configure vertical machining centers, letting automotive and medical device producers swap precision heads without full machine replacement. DMG MORI Co. Ltd. leverages its integrated control software to lock in long-term service contracts across German and Japanese customer bases. Haas Automation Inc. anchors its position through a factory-direct distribution model that compresses lead times for North American job shops. Yamazaki Mazak Corp. specializes in multi-tasking configurations that blur the line between vertical and horizontal processing.
A vertical machining center is a metal-cutting machine tool where the spindle axis runs perpendicular to the worktable, typically achieving positioning accuracies within 0.005 mm and spindle speeds exceeding 12,000 RPM for finishing operations. Its primary commercial purpose is precision milling, drilling, and tapping of complex components across batch production environments. Five-axis configurations command the premium margin pool because simultaneous contouring capability eliminates multiple setups for aerospace turbine housings and orthopedic implants. CNC controls dominate unit volume by integrating real-time tool path compensation and predictive maintenance diagnostics. Small and medium frame sizes see the fastest replacement cycles among electronics subcontractors in Asia.
ISO 230-2 test codes for machine tool accuracy and the EU Machinery Directive together shape baseline certification requirements for equipment sold into European aerospace and medical supply chains. The U.S. FDA's quality system regulation for medical device manufacturing indirectly drives demand for verified spindle thermal stability and traceable calibration protocols. China's GB standards for machine tool safety and precision classes, administered by SAMR, create tiered market access conditions for domestic versus imported equipment. Stakeholders must monitor how dual carbon goals in Beijing and the EU Green Deal's embodied carbon tracking reshape energy efficiency specifications for spindle motors and coolant systems.
Market Dynamics
The European Union's Machinery Directive revision is compressing certification timelines while aerospace manufacturers in the United States and China simultaneously expand five-axis capacity for titanium and composite machining.
Growth Catalysts
- EU Machinery Directive:Tightened safety and precision standards for automated metal-cutting equipment are forcing equipment upgrades across German and Italian aerospace supply chains.
- Titanium airframe components:US aerospace manufacturers are expanding machining capacity for lightweight structural parts, driving demand for high-torque spindle configurations.
- Five-axis simultaneous contouring:This capability eliminates multiple setups for complex geometries, reducing per-part processing time in medical device and turbine housing production.
Market Restraints
- Ball screw and linear guide supply:Japanese and Taiwanese suppliers control critical precision motion component manufacturing, creating input cost volatility and extended lead times.
- ISO 230-2 thermal drift testing:Compliance with machine tool accuracy verification protocols adds 8-12 weeks to European market entry for non-certified builders.
- Hybrid manufacturing systems:Additive-subtractive combined platforms threaten standalone vertical machining center demand in prototype and low-volume production environments.
Strategic Opportunities
- India's PLI scheme for precision engineering:Production-linked incentives for advanced manufacturing equipment create first-mover advantages for five-axis suppliers establishing local assembly.
- Real-time tool path compensation:Convergence of edge computing and CNC controls enables predictive chatter suppression, opening premium pricing for intelligent spindle systems.
- EU Green Deal embodied carbon tracking:Energy efficiency specifications for spindle motors and coolant systems favor regenerative drive technology adoption.
Industry Challenges
- Five-axis programming proficiency:CAM software complexity and simultaneous contouring simulation skills lag behind installed base expansion, constraining utilization rates.
- Legacy FANUC and Siemens control retrofit:Integration of predictive maintenance diagnostics with existing shop floor data architectures requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Machining Centers Market |
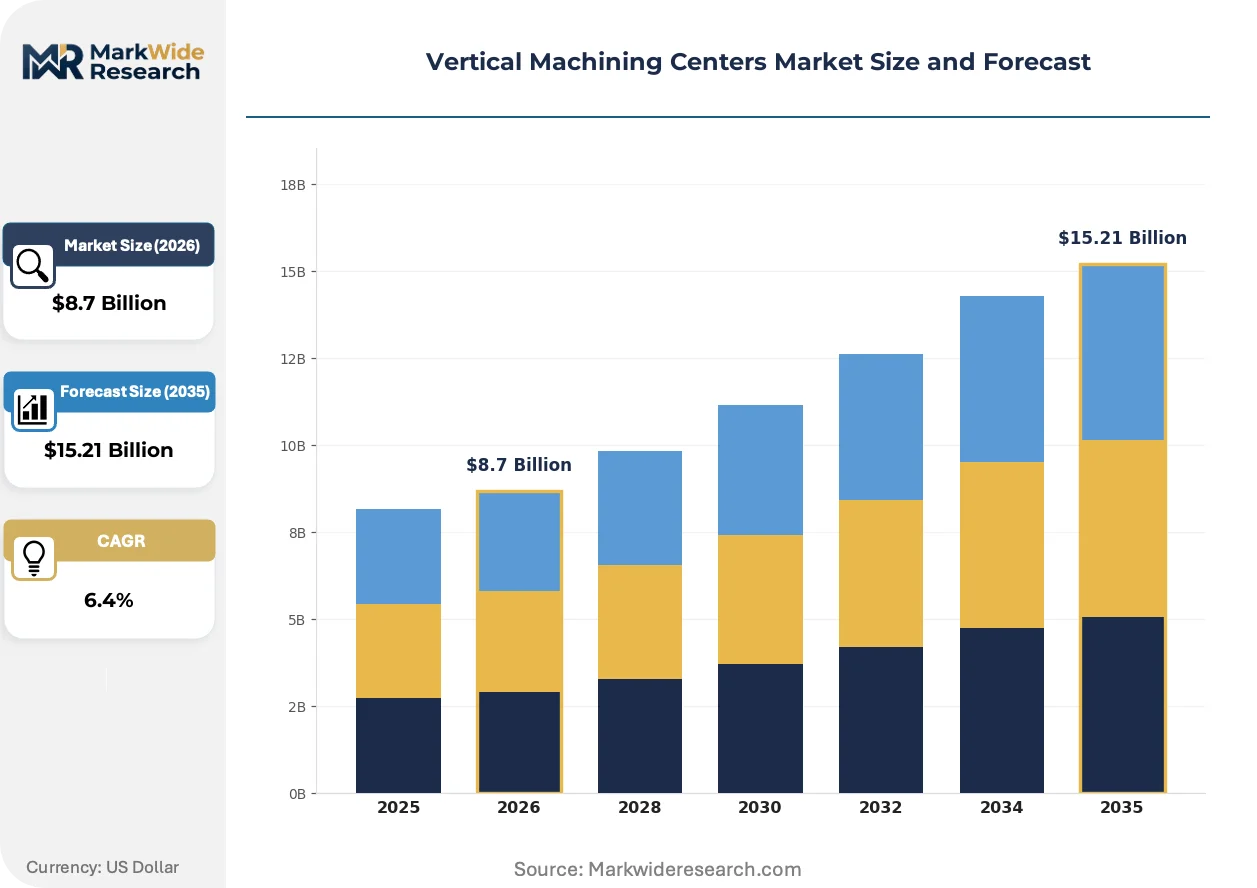
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-Axis, 3-Axis, CNC, Manual Technology: Vertical, Horizontal, Hybrid, Multi-Tasking End User: Aerospace, Automotive OEMs, Medical Device Manufacturers, Electronics Size: Small, Medium, Large, Extra Large |
| Companies Covered | DMG MORI Co. Ltd., Yamazaki Mazak Corp., Haas Automation Inc., Okuma Corp., DN Solutions Co. Ltd., CHIRON Group SE, Hurco Companies Inc., GF Machining Solutions AG, Makino Milling Machine Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Machining Centers Market Evolving Landscape
Modular spindle architectures are fragmenting traditional machine-tool procurement patterns while regulatory pressure on energy intensity accelerates regenerative drive adoption across European and Chinese manufacturing corridors.
Digital twin integration is unifying virtual commissioning with physical production workflows. Automotive powertrain suppliers in Stuttgart and medical device manufacturers in Minneapolis are deploying physics-based simulation to compress first-article qualification from weeks to days. This convergence of software and hardware is unifying the specification process, letting buyers validate cutting strategies before capital commitment.
REACH restrictions on metalworking fluid biocides are forcing aqueous coolant reformulation across European precision machining operations. German automotive suppliers report 15-20% fluid consumption reduction through minimum quantity lubrication systems. Aerospace subcontractors in Toulouse and Hamburg are responding with sealed cabin designs that capture mist and extend tool life.
Service contract unbundling is separating hardware procurement from predictive maintenance subscriptions. Japanese automotive tier-one suppliers now specify uptime guarantees rather than spare parts availability. This preference shift is most visible in the Shanghai-Suzhou manufacturing corridor, where domestic tool builders compete on total cost-per-part rather than capital expenditure alone.
Vertical Machining Centers Market Segmentation
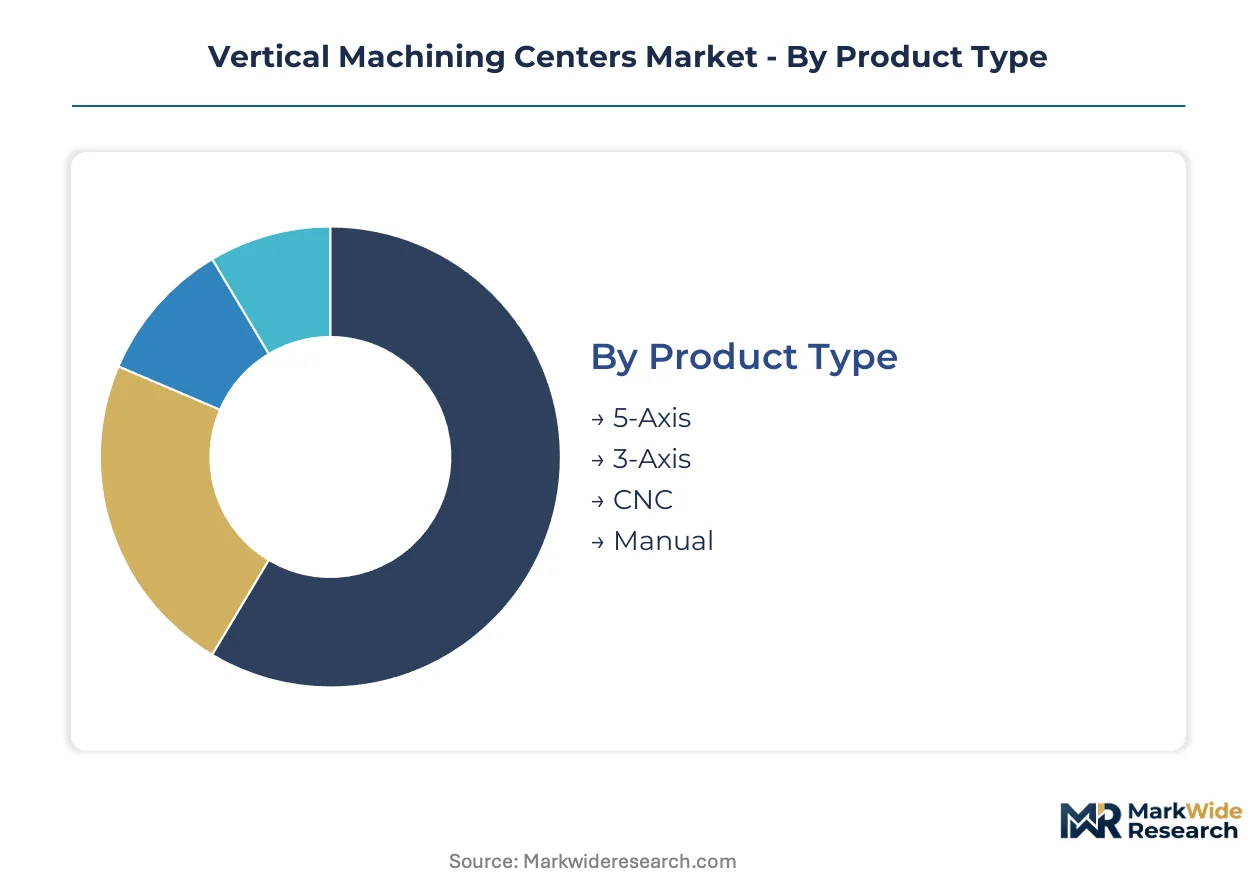
Vertical machining center procurement patterns diverge sharply across precision requirements, with aerospace and medical buyers prioritizing five-axis simultaneous contouring while job shops optimize for spindle speed per dollar. Segmentation reveals how tooling modularity and control architecture reshape replacement cycles across discrete manufacturing verticals.
Product Type:
Upgrade cycles accelerate where spindle interchangeability reduces capital commitment for precision manufacturers reconfiguring for titanium or composite work.
- 5-Axis:Simultaneous contouring capability eliminates multiple setups for complex geometries. Demand concentrates among US aerospace manufacturers expanding capacity for turbine housings and structural titanium components, driven by FAA airworthiness certification timelines for next-generation narrowbody programs.
- CNC:Computer numerical control systems integrate real-time tool path compensation and predictive maintenance diagnostics. Chinese electronics subcontractors in the Shanghai-Suzhou corridor favor compact CNC units with fastest replacement cycles among small-batch precision machining operations.
- 3-Axis:Fixed spindle orientation suits high-volume automotive bracket and housing production where setup complexity remains minimal.
- Manual:Hand-cranked positioning persists in prototype shops and vocational training facilities with limited automation requirements.
CNC sits at the top of the volume ranking, with 5-Axis climbing the fastest.
Technology:
Cost tier separation widens between entry-level vertical platforms and integrated multi-function systems that compress floor space and labor hours.
- Multi-Tasking:Configurations merge milling, turning, and grinding operations within single fixturing sequences. German automotive powertrain suppliers in Stuttgart specify these systems to consolidate five-operation part flows into two-machine cells, reducing work-in-process inventory and first-article qualification overhead.
- Hybrid:Additive-subtractive platforms combine directed energy deposition with precision machining for near-net-shape aerospace components. US Department of Defense prototyping contracts drive adoption among tier-three suppliers seeking to bypass forging lead times for low-volume titanium brackets.
- Vertical:Perpendicular spindle orientation dominates general-purpose job shops for accessibility and chip evacuation simplicity.
- Horizontal:Pallet-based tombstone fixturing optimizes unattended production of prismatic automotive and hydraulic components.
Vertical maintains installed base dominance, though Hybrid platforms are gaining share fastest in defense-aerospace prototyping.
End User:
Application-specific precision thresholds determine whether buyers prioritize thermal stability, spindle torque, or rapid traverse speeds.
- Aerospace:Titanium airframe machining demands high-torque spindle configurations with thermal drift compensation verified to ISO 230-2 protocols. US manufacturers expanding capacity in Wichita and Everett drive specification of 40-taper through-spindle coolant systems for deep-hole drilling of wing attachment fittings.
- Medical Device Manufacturers:Orthopedic implant production requires sub-micron positioning repeatability and traceable calibration documentation under FDA quality system regulation. Minneapolis and Warsaw, Indiana clusters specify machines with sealed cabin designs and minimum quantity lubrication to satisfy biocompatibility protocols.
- Automotive OEMs:Powertrain housing production favors high-speed machining centers with 50-taper spindles for cast iron and aluminum roughing operations.
- Electronics:Miniaturized component machining drives demand for compact footprint machines with 30,000+ RPM spindles and ceramic bearing technology.
Automotive OEMs anchor volume demand, while Medical Device Manufacturers expand most quickly on orthopedic and dental implant production growth.
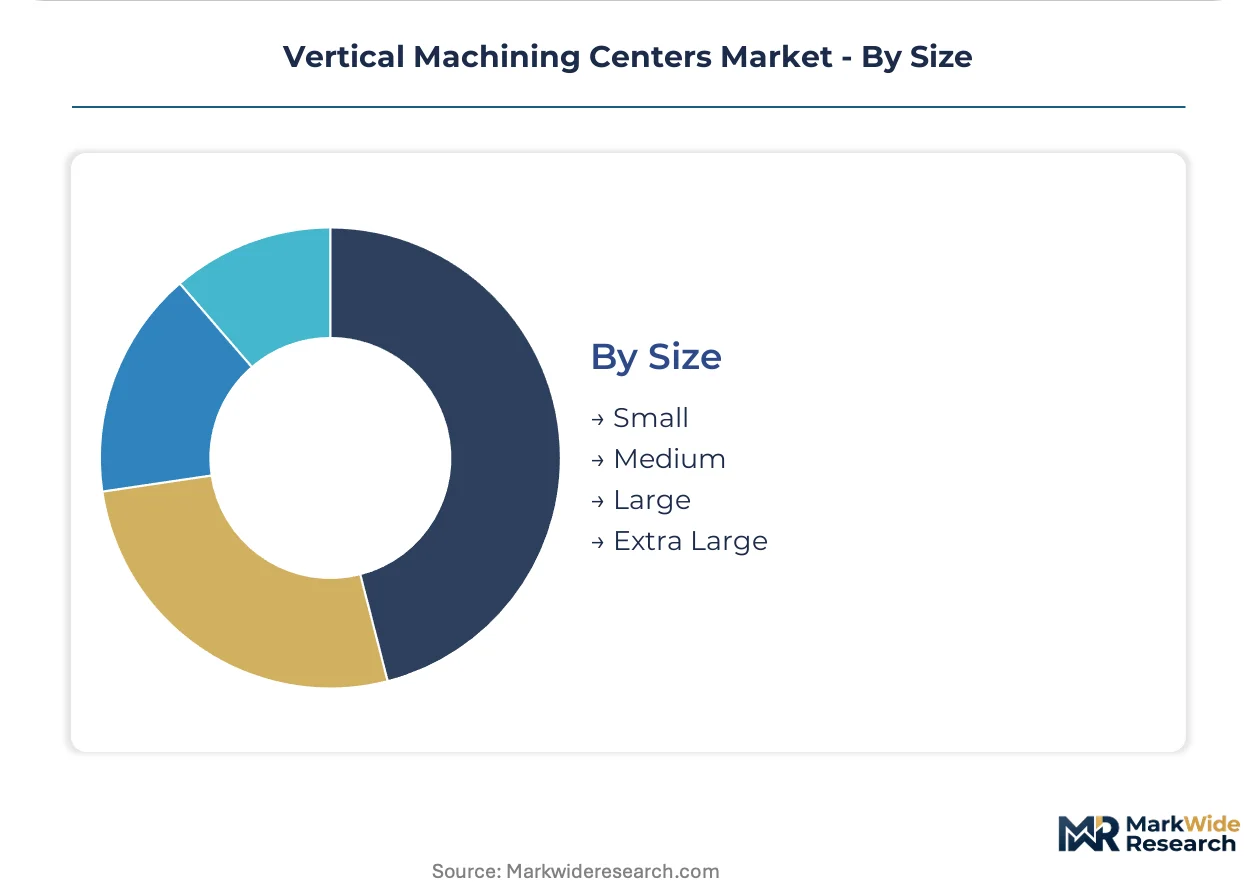
Size:
Customer type segmentation separates job shops seeking rapid payback periods from captive manufacturers optimizing for part-family throughput.
- Small:Benchtop and compact floor-standing units serve electronics subcontractors and medical device startups with limited capital budgets. Asian contract manufacturers in Shenzhen and Penang favor these machines for smartphone fixture and connector machining where floor space commands premium lease rates.
- Medium:Work envelopes accommodating 500-800 mm X-axis travel balance versatility with accessibility for mid-tier job shops. German and Italian aerospace supply chains specify medium-frame five-axis units for turbine blade and structural component batch production.
- Large:Extended Y and Z travels accommodate mold bases and aerospace structural assemblies requiring single-setup processing.
- Extra Large:Gantry-style configurations machine wind turbine hubs and aerospace wing spars beyond conventional vertical center capacities.
Medium frames lead unit volume, with Small sizes climbing fastest on electronics subcontractor expansion in Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertical machining centers trace their commercial origins to post-war American job shops and German tool rooms, where perpendicular spindle configurations first displaced manual milling for batch production. The industry's geographic footprint now stretches across precision manufacturing corridors on three continents.
United States
Aerospace manufacturers in Wichita and Everett expand five-axis capacity for titanium wing attachment fittings and turbine housings. FAA airworthiness certification timelines for next-generation narrowbody programs compress procurement decisions. Seattle-Tacoma and Dallas-Fort Worth clusters anchor demand for high-torque through-spindle coolant systems.
Germany
Automotive powertrain suppliers in Stuttgart specify multi-tasking configurations to consolidate five-operation part flows into two-machine cells. The EU Machinery Directive revision tightens safety and precision standards for automated metal-cutting equipment across German aerospace supply chains. Bavaria's machine tool builders face compressed certification timelines for thermal drift compliance.
China
Domestic tool builders scale five-axis production in the Shanghai-Suzhou manufacturing corridor to serve electronics subcontractors. SAMR-administered GB standards for machine tool safety and precision classes create tiered market access conditions. Beijing's dual carbon goals reshape energy efficiency specifications for spindle motors and coolant systems.
Japan
Ball screw and linear guide suppliers in Nagoya and Osaka control critical precision motion component manufacturing, creating input cost volatility for downstream builders. METI industrial policy supports predictive maintenance diagnostics integration with legacy FANUC control architectures. Chubu region automotive tier-one suppliers now specify uptime guarantees rather than spare parts availability.
India
Production-linked incentives for advanced manufacturing equipment create first-mover advantages for five-axis suppliers establishing local assembly. The PLI scheme for precision engineering accelerates capital equipment procurement in Pune and Chennai industrial belts. Domestic medical device manufacturers in Gujarat and Karnataka seek verified spindle thermal stability for orthopedic implant production.
Vertical Machining Centers Market Competitive Landscape
The competitive structure tilts toward integrated control software and factory-direct distribution models. Japanese and German builders anchor the premium tier through long-term service contract lock-in, while American manufacturers compress lead times through captive distribution networks. Three archetypes dominate: full-lifecycle solution providers, modular spindle specialists, and volume-focused job shop suppliers. M&A activity concentrates on predictive maintenance software assets, and geographic expansion targets India's PLI-eligible manufacturing zones.
Among Japanese builders, Yamazaki Mazak Corp. and Makino Milling Machine Co. Ltd. occupy positions emphasizing multi-tasking configurations that blur traditional vertical-horizontal boundaries. DMG MORI Co. Ltd. represents the German-Japanese hybrid archetype, integrating control software with machine tool hardware. Haas Automation Inc. anchors the American factory-direct model, exemplifying how compressed lead times defend share in North American job shop segments. These three names illustrate how geographic origin and organizational structure shape competitive positioning without requiring uniform strategic moves.
| Leading Market Players |
|---|
| DMG MORI Co. Ltd. |
| Yamazaki Mazak Corp. |
| Haas Automation Inc. |
| Okuma Corp. |
| DN Solutions Co. Ltd. |
| CHIRON Group SE |
| Hurco Companies Inc. |
| GF Machining Solutions AG |
| Makino Milling Machine Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Regenerative drive technology adoption simultaneously compresses energy operating costs for end-users and concentrates procurement leverage among builders with captive motor-controller integration capabilities in Germany and Japan.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vertical machining center transactions, with ISO 230-2 thermal drift certification and five-axis simultaneous contouring capability separating price bands. Aerospace and medical device manufacturers in Wichita and Stuttgart show lowest price sensitivity due to FAA and FDA compliance requirements, while Asian electronics subcontractors in Shenzhen drive cost compression in compact CNC units. Price differentiation rests on spindle modularity and control software integration depth.
Supply Chain Analysis
ISO 230-2 and EU Machinery Directive compliance gates create tiered supplier qualification, with ball screw and linear guide manufacturing anchored in Nagoya and Osaka, precision casting concentrated in Bavaria, and control electronics assembly scaling in Shanghai-Suzhou. Critical inputs draw from Japanese motion components, German cast iron, and Taiwanese servo motors. Single-source vulnerability runs through Nagoya-based ball screw suppliers. Distribution runs through factory-direct networks in North America and authorized dealer channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical machining centers market reads as a late-cycle quality story, with US aerospace manufacturers and European medical device producers prioritizing thermal stability certification and traceable calibration over capital expenditure minimization.
For Market Incumbents: To counter hybrid additive-subtractive platforms threatening prototype demand, DMG MORI and Yamazaki Mazak should deepen predictive maintenance software integration with legacy FANUC architectures while expanding local assembly capacity in Pune and Chennai to capture India's PLI scheme benefits. For New Entrants and Emerging Players: Domestic tool builders in China's eastern manufacturing corridor offer the most penetrable white-space, particularly for compact five-axis units serving electronics subcontractors with compressed lead time requirements and total cost-per-part pricing models. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Japanese builders with underutilized multi-tasking IP and stagnant European aftermarket service penetration, with long-term viability hinging on edge computing integration for real-time chatter suppression; watch for inflection when automotive tier-one suppliers in Chubu begin specifying uptime guarantees as standard contract terms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Motion Components | Captive ball screw production insulates Japanese builders from Nagoya supply volatility and extends margin capture. |
| Predictive Maintenance Software Platform Launch | Service contract unbundling in Stuttgart and Minneapolis shifts buyer preference toward uptime guarantees. |
| Local Assembly Footprint in India | PLI scheme eligibility in Pune and Chennai accelerates capital equipment procurement for precision engineering. |
| Regenerative Drive Technology Adoption | EU Green Deal embodied carbon tracking favors energy-efficient spindle motors in German automotive supply chains. |
| Digital Twin Integration Partnership | Physics-based simulation compresses first-article qualification timelines for automotive powertrain suppliers. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with maintenance directors at aerospace subcontractors, plant engineers at automotive powertrain facilities, OEM procurement teams, and aftermarket service heads with secondary validation through customs trade data, SEC machinery filings, SAMR GB standard registrations, and EU Machinery Directive certification databases.
Input-output matrices map spindle configuration demand against ball screw supply capacity, control architecture adoption, and regional regulatory compliance costs across the projection horizon, with CAGRs derived from segment-level replacement cycle analysis and installed base expansion rates in titanium machining and orthopedic implant production.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Japanese precision component export restrictions and REACH biocide reformulation timelines for metalworking fluids. Deviation in FAA narrowbody certification schedules or EU Machinery Directive enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crawler Dozers Market
Construction Equipment
Fogging Machine Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Piles Turner Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Solar Pile Driving Equipment Market