
 Book Binding Machines Market | 2026-2036
Book Binding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Book Binding Machines Market Outlook
Buyer concentration among large commercial print shops is consolidating as regional chains acquire independent operators and centralize capital expenditure decisions. GBC leverages its established distribution network to sustain aftermarket service revenue across North American print service providers. James Burn anchors European demand through specialized wire-binding equipment engineered for high-speed continuous operation.
Book binding machines mechanically secure printed sheets into finished volumes using thermal adhesive, mechanical stitching, or wire-and-spine insertion processes operating at speeds from hundreds to thousands of cycles per hour. Perfect binding equipment dominates volume sales to publishing houses running long print runs, while spiral binding systems capture expanding demand from educational institutions producing customized course materials and short-run manuals. Fully automated lines concentrate margin pools in high-capacity installations serving bulk production environments, whereas manual and semi-automatic units occupy price-sensitive entry segments.
CE marking under EU machinery directives and ISO 9001 quality frameworks govern product safety and manufacturing consistency for equipment sold across Europe, while OSHA machine guarding standards shape electrical and mechanical safety specifications in the United States. The EU F-Gas Regulation increasingly influences thermal binding equipment designs as manufacturers phase refrigerant-dependent heating elements from adhesive melting subsystems. Stakeholders must monitor evolving energy efficiency standards and regional certification reciprocity agreements when allocating production capacity across manufacturing footprints.
Market Dynamics
Educational institutions are modernizing campus print centers at an accelerating pace, replacing legacy thermal binding systems with automated wire-and-spine equipment that reduces manual handling and supports short-run customization workflows.
Growth Catalysts
- ISO 9001 Certification Mandates:European publishers now require supplier equipment to carry quality management certification, pulling automated binding lines into replacement cycles ahead of schedule.
- Campus Print Center Modernization:Universities across Germany, France, and Italy are consolidating departmental binding operations into centralized facilities equipped for on-demand course material production.
- Thermal Adhesive Formulation Advances:Low-temperature EVA and PUR adhesives are expanding perfect binding applications to coated and digitally printed stocks previously limited to mechanical stitching.
Market Restraints
- Precision Component Supply Concentration:High-tolerance drive systems and servo motors for automated lines concentrate among German and Japanese suppliers, creating lead time vulnerability.
- Steel Wire Price Volatility:Spiral binding equipment margins compress when galvanized steel feedstock costs fluctuate, particularly affecting mid-cap manufacturers without long-term supply agreements.
- CE Marking Compliance Burden:Small equipment builders face disproportionate testing costs under EU machinery directives, slowing entry into automated system segments.
Strategic Opportunities
- India Educational Infrastructure:State-level textbook procurement reforms are creating demand for semi-automatic binding systems capable of handling regional language imposition variations.
- EU F-Gas Regulation Tailwind:Thermal binding equipment redesigns to eliminate refrigerant-dependent heating elements open retrofit and replacement revenue streams.
- Print-on-Demand Integration:Binding systems with JDF-compliant digital front ends are capturing workflow integration contracts from commercial print shops serving self-publishing platforms.
Industry Challenges
- Mechatronics Talent Scarcity:Automated line manufacturers struggle to hire controls engineers capable of integrating servo-driven gathering and trimming modules.
- Legacy System Interoperability:Campus print centers face integration friction when connecting new binding equipment to existing prepress and finishing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Book Binding Machines Market |
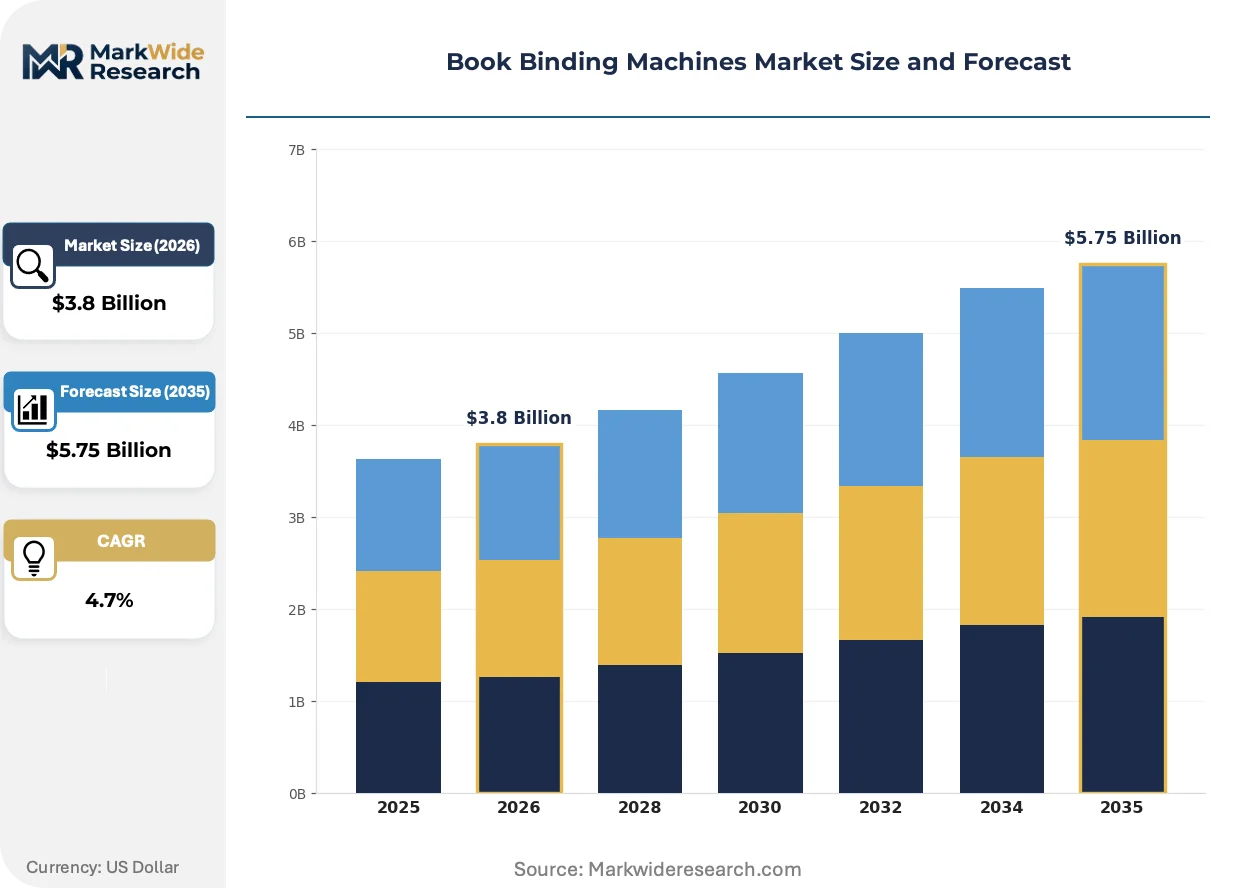
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automated, Electric End User: Publishing Houses, Educational Institutions, Print Shops, Libraries Binding Method: Saddle Stitching, Perfect Binding, Spiral Binding, Wire Binding Capacity: Low Volume, Medium Volume, High Volume, Bulk |
| Companies Covered | GBC, Akiles, Tamerica, Rhin-O-Tuff, James Burn, Coverbind, Fastback, Unibind, Rayson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Book Binding Machines Market Strategic Shifts
Binding equipment architecture is shifting from mechanical transmission to distributed motor control, enabling real-time adjustment of nip pressure and adhesive application rates without manual intervention.
Induction heating technology is electrifying thermal binding subsystems by replacing resistive coil elements with electromagnetic energy transfer, cutting warm-up intervals from fifteen minutes to under ninety seconds. University print centers in the Netherlands and Scandinavia are specifying induction-equipped perfect binders for high-mix, low-volume operations. This electrification is compressing the competitive gap between entry-level and mid-tier equipment performance tiers.
The EU F-Gas Regulation is forcing thermal binding equipment redesigns as manufacturers phase hydrofluorocarbon-dependent heating elements from adhesive melting subsystems. Equipment builders are pivoting to infrared and induction alternatives, with certification timelines extending six to nine months for redesigned product lines. German and Italian manufacturers with in-house thermal engineering capabilities are capturing specification share from competitors dependent on outsourced heating module suppliers.
Short-run customization requirements are fragmenting buyer procurement patterns as campus print centers and commercial shops unbundle binding services from traditional print contracts. Equipment vendors now face direct specification decisions from facilities managers rather than through consolidated print supplier relationships. This disintermediation is most pronounced in France and Spain, where university autonomy reforms have decentralized equipment purchasing authority to individual campuses.
Book Binding Machines Market Segmentation
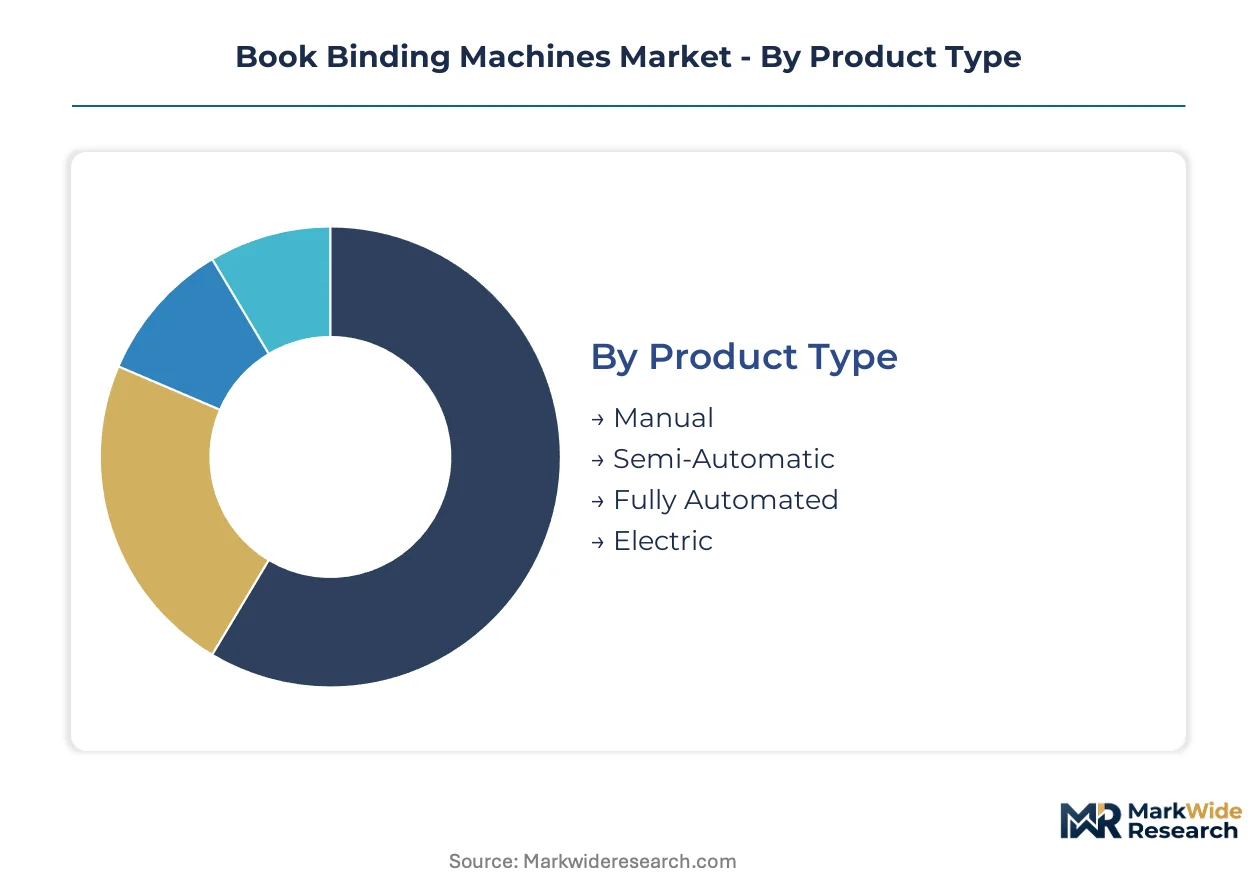
Binding equipment procurement patterns diverge sharply between standalone installations for dedicated finishing departments and embedded modules integrated into end-to-end digital print lines. Segment boundaries increasingly blur as hybrid configurations—semi-automatic gathering with automated trimming—capture workflow flexibility demands from mid-volume operations.
Product Type:
Standalone manual units serve occasional binding needs in small facilities, while embedded electric and fully automated systems dominate continuous production environments requiring upstream integration with digital front ends.
- Fully Automated:Servo-driven gathering, trimming, and adhesive application modules operate at thousands of cycles per hour with minimal operator intervention. German precision engineering clusters supply the high-tolerance drive systems that concentrate margin pools in this segment, though mechatronics talent scarcity constrains manufacturer expansion capacity.
- Semi-Automatic:Operator-fed gathering stations transition to motorized trimming and binding heads, bridging price-sensitive entry points with throughput demands from campus print centers. Universities across France and Italy specify these systems for on-demand course material production where run lengths vary daily.
- Manual:Hand-cranked or foot-operated pressing mechanisms serve occasional binding needs in libraries and small offices with volumes below fifty units daily.
- Electric:Motorized single-station units eliminate manual cranking while retaining operator control over cycle timing, occupying the transition zone between manual and automated workflows.
Volume placements concentrate in Fully Automated; the faster expansion belongs to Semi-Automatic as campus modernization programs prioritize workflow flexibility over maximum throughput.
End User:
Cost tier stratification separates capital-intensive centralized installations from distributed departmental equipment, with procurement authority increasingly fragmenting toward facilities managers rather than consolidated print suppliers.
- Educational Institutions:Campus print centers modernize legacy thermal binding operations with automated wire-and-spine equipment that reduces manual handling. State-level textbook procurement reforms in India are creating demand for semi-automatic systems capable of handling regional language imposition variations.
- Publishing Houses:Long-run perfect binding dominates volume production of trade books and catalogs, with ISO 9001 certification mandates pulling automated lines into replacement cycles ahead of schedule across European operations.
- Print Shops:Commercial service providers face buyer consolidation as regional chains acquire independent operators, centralizing capital expenditure decisions toward multi-station automated lines.
- Libraries:Archival binding and repair operations sustain demand for manual and electric single-station equipment with preservation-grade adhesive compatibility.
Revenue concentration sits with Publishing Houses; Educational Institutions are climbing the fastest as university autonomy reforms decentralize purchasing authority to individual campuses.
Binding Method:
Application requirements dictate method selection—lay-flat functionality for manuals versus spine printing compatibility for retail display—with thermal adhesive formulation advances expanding perfect binding into digitally printed stocks previously limited to mechanical stitching.
- Perfect Binding:Thermal adhesive systems secure squared spines compatible with retail display and spine printing, now operating with low-temperature EVA and PUR formulations that handle coated stocks. The EU F-Gas Regulation is forcing equipment redesigns as manufacturers phase hydrofluorocarbon-dependent heating elements in favor of infrared and induction alternatives.
- Spiral Binding:Continuous plastic or metal coil insertion enables 360-degree lay-flat functionality essential for manuals and workbooks. Steel wire price volatility compresses margins when galvanized feedstock costs fluctuate, particularly affecting mid-cap manufacturers without long-term supply agreements.
- Saddle Stitching:Wire staples through the center fold serve short-run brochures and catalogs with sub-64-page signatures, maintaining relevance in high-speed web-fed environments.
- Wire Binding:Twin-loop wire spines provide professional finish for presentations and reports, with James Burn anchoring European demand through specialized equipment engineered for high-speed continuous operation.
Perfect Binding retains the largest installed base; Spiral Binding is expanding most quickly as customized course material production proliferates across decentralized campus operations.
Capacity:
Customer type and volume scale align tightly—bulk installations serve dedicated publishing facilities while low and medium volume units match the intermittent rhythms of educational and library environments.
- High Volume:Continuous-feed systems with automated gathering towers and inline trimming serve bulk production environments with daily outputs exceeding ten thousand units, concentrating in publishing house central facilities.
- Medium Volume:Batch-fed automated lines with manual loading stations accommodate variable run lengths from commercial print shops serving multiple client verticals.
- Low Volume:Single-station equipment with operator-controlled cycle timing matches the sporadic demands of library repair operations and small departmental print rooms.
- Bulk:Integrated binding towers within web offset or digital print lines operate at newspaper-scale speeds, requiring specialized mechatronics integration capabilities concentrated among German and Japanese suppliers.
Equipment shipments concentrate in High Volume; Medium Volume is gaining share fastest as print-on-demand integration requirements fragment procurement toward flexible batch configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany's precision engineering clusters, with secondary demand nodes emerging across North American commercial print networks and Asia-Pacific educational infrastructure programs.
Germany
Campus print center modernization across Bavaria and Baden-Württemberg drives automated wire-binding equipment demand. CE marking under EU machinery directives shapes product certification timelines for equipment builders in Stuttgart and Munich industrial zones. Precision drive system manufacturers in the Black Forest region supply high-tolerance servo motors for fully automated binding lines.
United States
Regional print shop chains consolidate independent operators and centralize capital expenditure toward multi-station automated systems. OSHA machine guarding standards govern electrical and mechanical safety specifications for binding equipment deployed across commercial facilities. Chicago and Los Angeles metropolitan areas host the densest concentrations of commercial print service providers upgrading legacy thermal binding operations.
India
State-level textbook procurement reforms generate demand for semi-automatic systems handling regional language imposition variations. BIS certification requirements influence equipment specifications for government educational infrastructure tenders. Manufacturing clusters in Gujarat and Maharashtra assemble mid-capacity binding systems for domestic distribution and neighboring export markets.
France
University autonomy reforms decentralize equipment purchasing authority to individual campuses, fragmenting procurement patterns toward flexible semi-automatic configurations. EU F-Gas Regulation compliance timelines extend six to nine months for thermal binding equipment redesigns. Lyon and Toulouse university print centers specify induction-heated perfect binders for high-mix, low-volume course material production.
Japan
High-tolerance drive system suppliers concentrate manufacturing capacity for automated binding line exports. METI industrial standards influence equipment efficiency specifications for domestic publishing house installations. Nagoya and Osaka precision engineering clusters produce servo motors and gathering module components for German and North American equipment integrators.
Book Binding Machines Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular retrofit solutions and digital workflow integration partnerships. The vendor base stratifies across three capability tiers: precision-engineered fully automated lines, flexible semi-automatic configurations, and price-sensitive manual equipment. Three strategic archetypes dominate: German precision engineering specialists, North American distribution-network players, and Asian cost-optimized fabricators. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing for digital front-end integration.
Among North American distribution-network players, GBC leverages established aftermarket service infrastructure across print service providers. James Burn anchors European demand through specialized wire-binding equipment engineered for high-speed continuous operation. James Burn International GmbH and GBC represent contrasting archetypes—European precision specialization versus North American service-network scale—each occupying distinct positions within the competitive matrix.
| Leading Market Players |
|---|
| GBC |
| Akiles |
| Tamerica |
| Rhin-O-Tuff |
| James Burn |
| Coverbind |
| Fastback |
| Unibind |
| Rayson |
| Others |
Value Chain & Pricing Dynamics
Campus print center modernization across Germany, France, and Italy is pulling automated binding lines into replacement cycles ahead of normal depreciation schedules, forcing equipment builders to absorb CE marking compliance costs while competing for specification share against regional distributors with lower overhead structures.
Pricing Analysis
Volume placements concentrate in fully automated lines where German precision engineering commands premium positioning, while semi-automatic configurations compete on workflow flexibility rather than throughput metrics. Pricing stratifies across ISO 9001-certified premium tiers, standard CE-marked mid-range systems, and economy manual units serving occasional binding needs. Cost compression in the semi-automatic tier is intensifying because mid-cap manufacturers lack long-term steel wire supply agreements. Educational institutions exhibit the highest price sensitivity as decentralized procurement authority fragments volume discounts, whereas publishing houses running continuous production tolerate premium positioning for reliability guarantees.
Supply Chain Analysis
Mechatronics talent scarcity in Germany and Japan is constraining expansion capacity for automated line manufacturers despite concentrated precision drive system production in Stuttgart, Munich, and Nagoya industrial zones. Component sourcing draws from German servo motor suppliers, Japanese gathering module specialists, and Chinese steel wire feedstock providers. Single-source vulnerability concentrates in high-tolerance drive systems where replacement qualification timelines extend equipment procurement cycles. Distribution runs through established aftermarket service networks for commercial print shops and direct campus sales channels where university autonomy reforms have disintermediated traditional print supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a cost-of-compliance moat, forcing six-to-nine-month redesign timelines that advantage German and Italian manufacturers with in-house thermal engineering capabilities over competitors dependent on outsourced heating module suppliers.
For Market Incumbents: Extend certification lead times into sustained specification advantage by accelerating infrared and induction heating module development before competitors complete outsourced redesigns. Consolidate aftermarket service contracts across North American print service provider networks to lock out emerging modular retrofit entrants. Vertical integration into precision drive system supply buffers lead time vulnerability from Japanese component concentration. For New Entrants and Emerging Players: Enter via India's state-level textbook procurement reforms where BIS certification requirements favor domestic assembly partnerships over fully imported systems. Target semi-automatic configurations for regional language imposition flexibility that established players have underinvested in. Pursue JDF-compliant digital front-end integration partnerships with print-on-demand platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors precision-engineered mid-cap specialists with captive thermal engineering capabilities and existing CE marking infrastructure. Long-term viability hinges on consolidation plays that aggregate campus procurement relationships before university autonomy reforms fully fragment addressable demand. Watch induction heating adoption curves in Netherlands and Scandinavian university print centers as the signal for technology inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Compresses competitor redesign timelines and consolidates specification share among pre-certified German and Italian builders. |
| Induction Heating Module Development | Replaces refrigerant-dependent thermal subsystems ahead of EU F-Gas Regulation enforcement deadlines. |
| Campus Direct Sales Channel Buildout | Captures procurement authority fragmentation as French and Spanish university autonomy reforms disintermediate traditional suppliers. |
| JDF Workflow Integration Partnership | Secures specification contracts from commercial print shops serving self-publishing platform volume growth. |
| Aftermarket Service Network Expansion | Locks recurring revenue streams across North American regional print chain consolidation. |
Study Parameters
Document review covered equipment certification databases, EU machinery directive filings, and customs trade records for binding system components, complemented by interviews with campus facilities managers, commercial print shop procurement directors, OEM equipment engineers, and aftermarket service heads. Secondary validation drew from ISO 9001 registrar filings, BIS certification bulletins, METI efficiency standard disclosures, and OSHA machine guarding compliance reports. Bottom-up demand modeling across educational, publishing, and commercial print verticals was triangulated against top-down capacity estimates from German and Japanese precision engineering clusters.
Installed base projections and replacement cycle timing across the analysis window reflect segmentation by automation tier, binding method, and end-user concentration. The analytical framework modeled capacity utilization rates, adhesive formulation substitution elasticities, and regional procurement authority decentralization patterns. CAGRs were derived from equipment shipment trajectories and campus modernization program announcements rather than extrapolated trend fitting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel wire price volatility spikes or extended mechatronics talent scarcity in German manufacturing regions. Forecasts reflect documented assumptions regarding EU F-Gas Regulation enforcement consistency and Indian state-level procurement reform implementation pacing. Material deviation in induction heating adoption rates or campus procurement centralization reversals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Power Drill Market
Tools
Machine Vise Market
Tools
Cutting Equipment, Accessories and Consumables Market
Tools
Mortiser Market
Tools
Handheld Blower Market
Tools
Power Tool Gears Market
Tools
Telescopic Tool Boxes Market
Tools
Global Construction Camera Market
Tools
Log Splitters Market
Tools
Power Press Machines Market
Tools
Metal Cutting Machine Market
Tools
Sander Market
Tools
Wood Floor Grinding Machine Market
Tools
Handheld Pipe Cutter Market
Tools
Woodworking Sanders Market