
 Dozer Tire Market | 2026-2036
Dozer Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Dozer Tire Market Foresight
Subscription-based tire monitoring and predictive maintenance programs is broadening how dozer tire value gets captured beyond the initial sale. Michelin leverages its MEMS sensor integration to sustain premium positioning in autonomous mining fleets. Bridgestone anchors large contracts across South American copper operations through integrated service agreements. Continental competes on embedded RFID tracking that extends lifecycle visibility for contractor fleets.
Dozer tires are engineered for extreme load-bearing capacity across abrasive terrain, typically incorporating reinforced steel-belted carcasses and cut-resistant tread compounds to withstand puncture hazards in rock and demolition environments. Radial construction dominates high-horsepower mining applications where heat dissipation and footprint uniformity reduce soil compaction and fuel burn. Bias ply retains cost-sensitive share in emerging market construction fleets where capital constraints limit upfront radial investment. Foam-filled variants are gaining fastest in demolition and scrap-handling niches where flat elimination justifies weight penalties.
EPA Tier 4 Final and EU Stage V emissions frameworks are reshaping dozer powertrain design, which in turn loads tires with higher torque and weight profiles that demand revised load index certifications. MSHA surface equipment standards in the United States and Australia's state-based mine safety regimes enforce tread-depth minimums and inspection intervals that accelerate replacement cycles. China's GB standards for off-highway tires are tightening import compliance gates for non-domestic suppliers. Stakeholders must monitor how electrified dozer torque curves and battery ballast redistribute wear patterns across tread designs.
Market Dynamics
Electrification of dozer powertrains is redistributing load stresses across tire contact patches, forcing manufacturers to recertify carcass designs for torque spikes and battery ballast weight that radial constructions were not originally engineered to absorb.
Growth Catalysts
- Deepening open-pit extraction:Mining operators in Western Australia's Pilbara district and Chile's Atacama are accelerating fleet renewals as haul distances lengthen and terrain abrasiveness intensifies.
- EU Stage V emissions protocols:Heavier electric dozer platforms entering European quarries require tires with revised load index certifications that OEMs must secure to maintain equipment homologation.
- MEMS sensor integration:Embedded pressure and temperature monitoring is extending tire lifecycle visibility for autonomous mining fleets, converting capital goods into recurring service revenue streams.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and synthetic rubber feedstock cost swings compress margin predictability for tire compounders serving price-sensitive construction segments.
- Steel cord supply concentration:Arc furnaces and tire-grade bead wire production cluster in select East Asian manufacturing zones, exposing procurement to logistics bottlenecks and tariff friction.
- Bias ply technical ceiling:Heat buildup and footprint distortion limit bias construction to lower horsepower applications, structurally excluding the segment from electrified mining equipment adoption curves.
Strategic Opportunities
- Scrap-handling foam-filled variants:Demolition contractors in North American urban cores are accepting weight penalties for flat elimination in debris-strewn environments where puncture downtime costs exceed fuel efficiency losses.
- RFID-enabled lifecycle tracking:Contractor fleets operating mixed equipment pools across dispersed job sites are adopting embedded identification to automate inspection logging and replacement scheduling.
- India's infrastructure buildout:Road construction and dam projects in states like Madhya Pradesh and Rajasthan are generating demand for cost-optimized radial tires as domestic mining output expands.
Industry Challenges
- Compound formulation for dual-chemistry powertrains:Tire engineers must simultaneously validate tread compounds for diesel-electric hybrid heat profiles and pure battery-electric torque delivery without separate SKU proliferation.
- MSHA surface equipment inspection intervals:US mine safety mandates accelerate replacement cycles beyond wear-based economics, forcing inventory carrying cost increases for site-level procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dozer Tire Market |
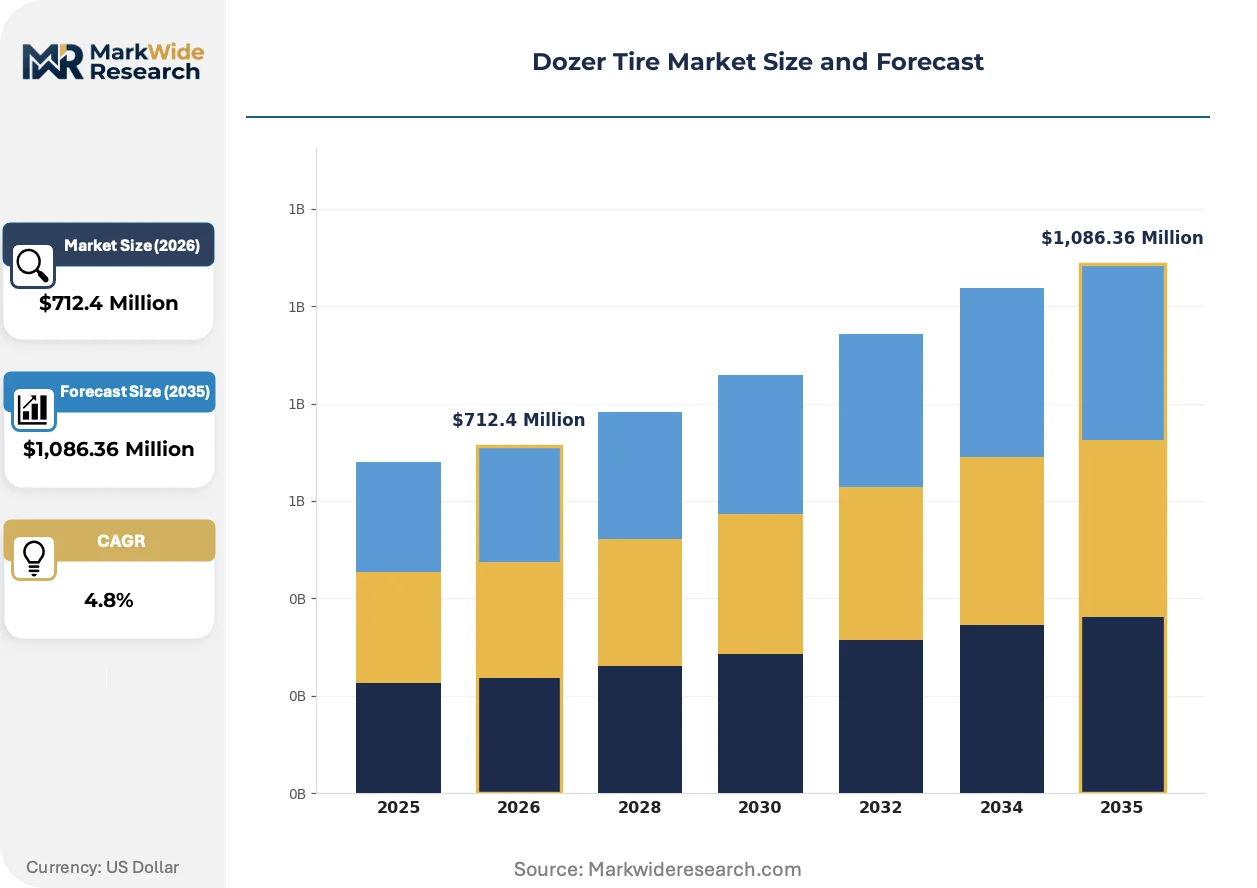
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,086.36 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bias Ply, Radial, Solid, Foam-Filled Tread Pattern: Flat, Multi-V, Ribbed, Chevron Construction Material: Rubber, Synthetic, Steel, Composite End User: Construction, Mining, Agriculture, Forestry |
| Companies Covered | Michelin, Bridgestone, Goodyear, Continental, Yokohama Rubber, Balkrishna Industries, Titan International, BKT, Trelleborg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dozer Tire Market Shifts & Advancements
Sensor-embedded tire architectures are converging with predictive maintenance platforms to restructure how value gets captured across the equipment lifecycle. Three developments are compressing traditional sales models and redefining competitive differentiation.
RFID and MEMS sensor integration is converging with cloud-based fleet management platforms to enable real-time tread wear monitoring and automated replacement triggering. Autonomous mining operators in Western Australia are deploying these systems at scale to eliminate manual inspection labor and unplanned downtime. The structural consequence is a shift from unit sales toward subscription-based availability contracts that lock in multi-year supplier relationships.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing dozer OEMs to add battery ballast and electric drive components that increase curb weight by fifteen to twenty percent. Tire manufacturers must secure new load index certifications from homologation bodies to maintain equipment compliance. Mining segments in Chile and Scandinavia are absorbing these certification costs fastest, while emerging market construction fleets delay adoption pending price convergence.
Buyers in copper extraction and iron ore hauling are consolidating procurement authority into centralized fleet management offices that negotiate integrated service agreements spanning tires, monitoring hardware, and site-level maintenance labor. Traditional distribution through independent dealers is compressing as direct OEM-tiremaker partnerships capture volume commitments. This pattern is most visible across South American mining corridors where integrated operators like those in Chile's Antofagasta region are standardizing on single-source tire programs.
Dozer Tire Market Segmentation
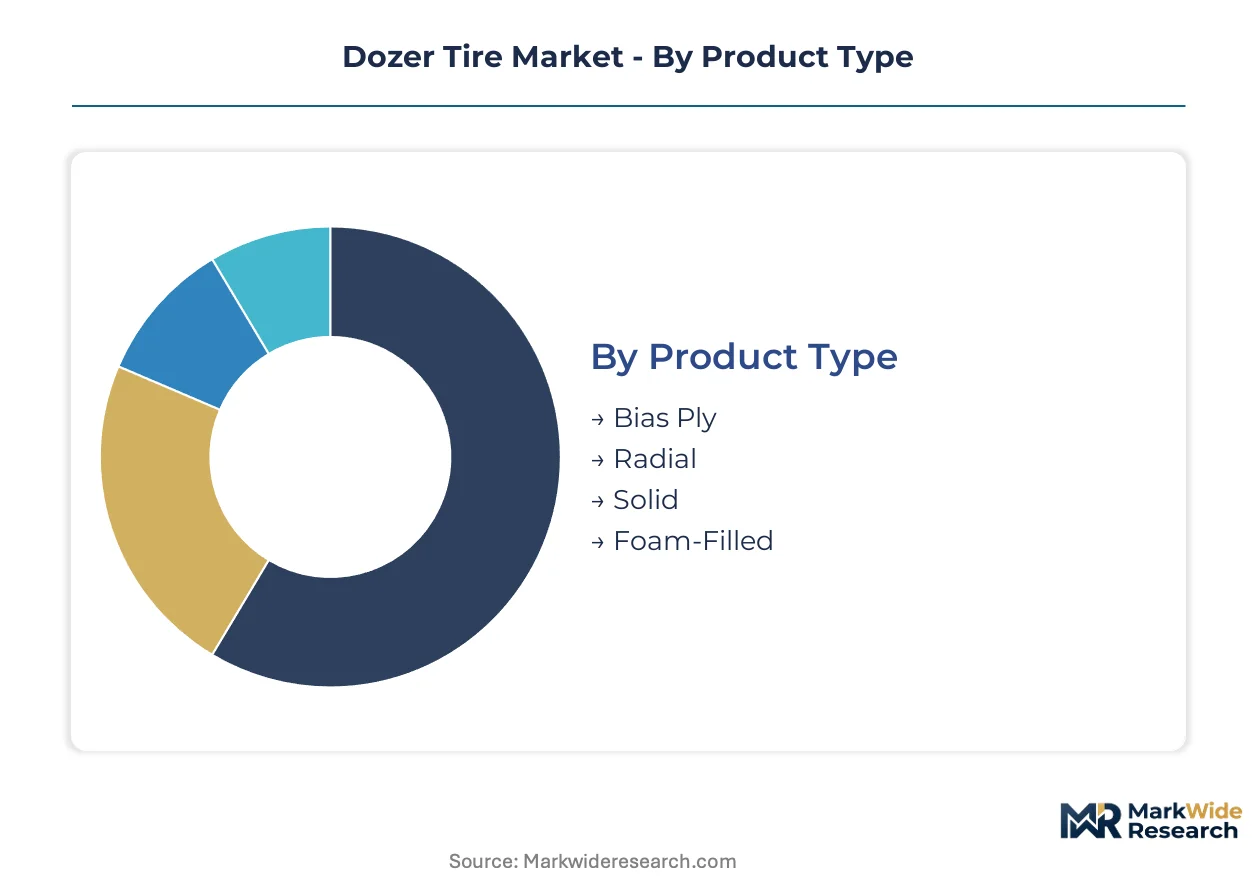
Dozer tire selection hinges on matching carcass construction to duty cycle intensity, tread geometry to traction requirements, and compound formulation to terrain abrasiveness. Procurement teams segment specifications by equipment horsepower, site conditions, and total cost of ownership horizons rather than upfront unit price alone.
Product Type:
Construction technology determines load-bearing capacity, heat dissipation, and repairability across mining and earthmoving applications.
- Radial:Steel-belted carcasses distribute loads evenly across wider footprints, reducing soil compaction and fuel consumption in high-horsepower mining fleets. Western Australia's Pilbara iron ore operators specify radial construction exclusively for autonomous haulage corridors where heat buildup limits bias alternatives.
- Bias Ply:Cross-ply nylon or polyester cords create rigid sidewalls resistant to impact damage in rocky terrain, though heat accumulation restricts deployment to lower-speed construction tasks. Capital-constrained contractors in India's Madhya Pradesh road projects favor bias construction for initial fleet builds despite higher lifecycle costs.
- Solid:Molded rubber eliminates puncture risk entirely, trading ride comfort for absolute reliability in scrap metal handling and demolition debris. Urban demolition contractors in North American metropolitan cores absorb vibration penalties to eliminate flat-related downtime.
- Foam-Filled:Polyurethane injection into standard tire cavities provides flat-proofing at reduced weight penalty versus solid designs, gaining traction in mixed debris environments where puncture frequency justifies fill costs.
Radial construction leads on scale across mining procurement; foam-filled variants lead on momentum in urban demolition niches.
Tread Pattern:
Contact patch geometry governs traction, self-cleaning, and wear distribution across soil, rock, and paved surfaces.
- Multi-V:Angled lug arrays bite into loose aggregate while ejecting packed material, dominating copper extraction in Chile's Atacama where haul roads alternate between compacted earth and fractured rock. Mine operators in the Antofagasta region specify Multi-V patterns for drive-wheel positions on electric dozers where torque spikes accelerate lug wear.
- Chevron:V-shaped bars center the tread for directional stability on slopes, preferred in forestry skidding and hillside quarrying. Scandinavian aggregate producers deploy chevron patterns for winter operations on frozen inclines where lateral slip risks equipment positioning.
- Flat:Continuous rib designs maximize ground contact for grading precision and paved surface protection, standard on finish dozers in roadbuilding fleets.
- Ribbed:Circumferential grooves channel water and reduce rolling resistance on improved haul roads, specified for transport dozers in bauxite operations.
Multi-V patterns dominate mining volume; chevron configurations gain share fastest in forestry and hillside extraction.
Construction Material:
Compound and reinforcement selection balances cut resistance, thermal stability, and procurement cost against specific abrasion profiles.
- Rubber:Natural and synthetic polymer blends form the base matrix for all pneumatic variants, with styrene-butadiene ratios tuned to heat tolerance requirements. Southeast Asian supply disruptions for natural rubber feedstock have compressed compounder margins serving price-sensitive construction segments.
- Steel:Bead wire and belt plies provide structural integrity under extreme loads, with tire-grade cord production concentrated in East Asian manufacturing zones exposed to logistics bottlenecks.
- Synthetic:Aramid and nylon reinforcements reduce weight in specialty applications where unsprung mass affects fuel efficiency.
- Composite:Hybrid reinforcement schemes combining steel belts with synthetic overlays optimize specific strength-to-weight ratios for electric dozer battery ballast accommodation.
Rubber-steel combinations anchor procurement volume; composite reinforcements climb fastest under electrified powertrain loads.
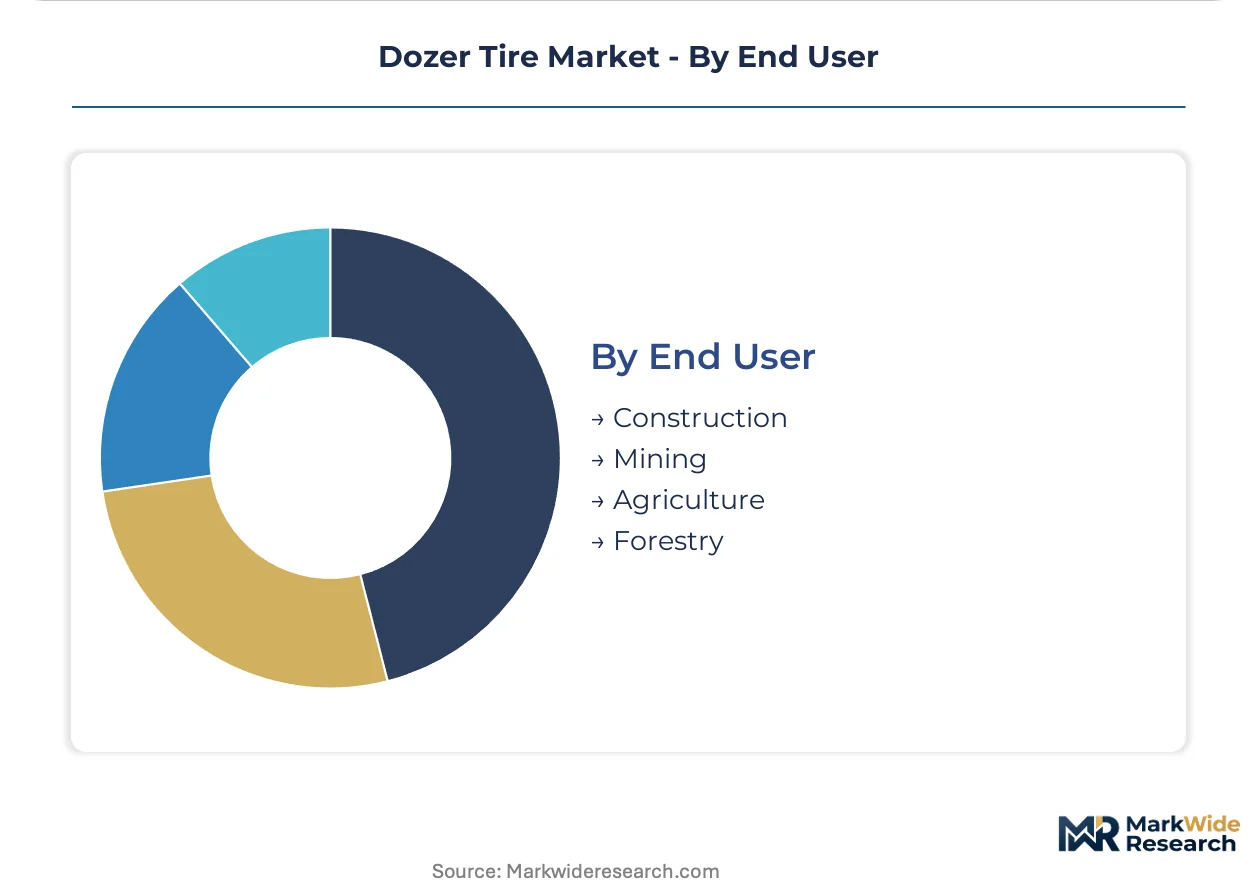
End User:
Application intensity and downtime cost structure dictate specification tier and service contract integration.
- Mining:Continuous operation regimes and autonomous fleet deployment demand sensor-integrated radials with predictive maintenance contracts. Australia's state-based mine safety regimes enforce tread-depth minimums that accelerate replacement cycles beyond wear-based economics.
- Construction:Intermittent utilization and mixed equipment pools favor cost-optimized bias or entry-level radial procurement with standard warranty terms. Road and dam projects in Rajasthan generate demand for mid-tier specifications as domestic infrastructure output expands.
- Agriculture:Lower duty cycles and soil compaction sensitivity drive bias ply retention in land preparation and drainage applications.
- Forestry:Stump damage and slash debris prioritize cut-resistant compounds and reinforced sidewalls in remote access conditions.
Mining commands specification leadership and service integration intensity; construction provides volume breadth across dispersed geographic markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands mining fleet renewal intensity while Chile concentrates copper extraction expansion, yet India's infrastructure buildout is generating parallel construction equipment demand across divergent terrain profiles.
Australia
Western Australia's Pilbara iron ore district drives autonomous haulage corridor specifications where state-based mine safety regimes enforce tread-depth minimums. The country's national mining regulator mandates inspection intervals that accelerate replacement cycles beyond wear-based economics. Perth-based procurement offices for Rio Tinto and BHP standardize on sensor-integrated radial programs with predictive maintenance contracts.
Chile
Antofagasta region copper operators are consolidating fleet authority into centralized offices negotiating integrated tire-service agreements. Chile's national mining safety authority enforces surface equipment standards that compress replacement timelines for high-torque electric dozer deployments. Calama and Antofagasta city clusters host contractor pools standardizing on single-source tire programs for open-pit extraction.
United States
EPA Tier 4 Final frameworks are reshaping dozer powertrain design, loading tires with higher torque profiles that demand revised load index certifications. MSHA surface equipment standards enforce inspection intervals that accelerate replacement cycles and elevate inventory carrying costs. Arizona copper corridors and Appalachian coal regions concentrate fleet procurement for mining applications.
India
Madhya Pradesh and Rajasthan road construction and dam projects are generating demand for cost-optimized radial tires as domestic mining output expands. The Bureau of Indian Standards tightens off-highway tire import compliance gates for non-domestic suppliers. Mumbai and Delhi-NCR procurement hubs coordinate infrastructure fleet specifications across dispersed state-level projects.
Germany
EU Stage V emissions protocols are pressuring OEMs to certify tires for heavier electric dozer platforms entering European quarries. The country's national automotive regulator KBA oversees equipment homologation requirements that tire manufacturers must satisfy. Bavarian and North Rhine-Westphalia quarry operators are absorbing certification costs fastest for electrified fleet transitions.
Dozer Tire Market Competitive Landscape
Top-tier vendors anchor premium sensor-integrated segments, while mid-tier compounders compete on cost-optimized radial specifications for price-sensitive construction fleets. The vendor base stratifies across integrated mining service providers, regional construction specialists, and emerging market fabricators. Three strategic archetypes dominate: predictive maintenance platform operators, certification-heavy homologation leaders, and volume-driven bias ply suppliers. Competitive intensity concentrates on securing multi-year availability contracts and achieving backward integration into steel cord supply.
Within the integrated service tier, Michelin and Bridgestone exemplify platform-based positioning through embedded monitoring hardware and site-level maintenance bundling. Continental occupies a position emphasizing RFID-enabled lifecycle tracking for contractor fleet automation. These three anchors represent the shift from unit sales toward subscription-based revenue capture across autonomous mining deployments.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone |
| Goodyear |
| Continental |
| Yokohama Rubber |
| Balkrishna Industries |
| Titan International |
| BKT |
| Trelleborg |
| Others |
Supply & Pricing Matrix
EU Stage V emissions protocols mandating heavier electric dozer platforms are forcing tire manufacturers to absorb recertification costs while procurement offices in Western Australia's Pilbara district consolidate into multi-year availability contracts that compress spot-market pricing power.
Pricing Analysis
Capacity additions in India and Thailand are reshaping price floors for cost-optimized radial tires serving infrastructure construction fleets. Three-tier pricing structure across premium sensor-integrated, standard certified-radial, and economy bias-ply levels anchors procurement segmentation. Cost compression in the bias-ply tier is intensifying because natural rubber feedstock volatility from Southeast Asian supply disruptions compresses compounder margins. Construction contractors in India's Madhya Pradesh road projects exhibit highest price sensitivity; autonomous mining operators in Chile's Antofagasta region show least sensitivity due to downtime cost structures.
Supply Chain Analysis
Steel cord supply rests on concentrated tire-grade bead wire production in China, Japan, and South Korea. Natural rubber draws from Thai and Indonesian plantation networks; synthetic rubber feedstock sources from South Korean petrochemical complexes. Single-source vulnerability in steel cord procurement exposes tire manufacturers to logistics bottlenecks and tariff friction in East Asian manufacturing zones. Distribution runs through OEM-direct partnerships for mining fleets and independent dealer networks for dispersed construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Stage V certification costs for electric dozer tires create margin premiums unavailable in price-sensitive Indian infrastructure procurement.
For Market Incumbents: Acquire sensor-embedded tire monitoring platforms to defend against predictive maintenance specialists capturing recurring revenue streams from autonomous mining fleets. Secure backward integration into steel cord supply to mitigate East Asian logistics concentration risk. Anchor multi-year availability contracts with Australian iron ore operators before electrified fleet renewals accelerate replacement cycles. For New Entrants and Emerging Players: Independent dealer networks in India's Rajasthan and Madhya Pradesh infrastructure corridors represent the most penetrable channel for cost-optimized radial introductions. Target foam-filled variant demand from North American urban demolition contractors accepting weight penalties for flat elimination. Pursue white-label manufacturing partnerships with established compounders to bypass capital-intensive certification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier radial specialists possessing India domestic manufacturing footprints and Bureau of Indian Standards compliance capabilities. Long-term viability favors compounders achieving captive supply of natural rubber feedstock or synthetic rubber alternatives. Watch electric dozer torque curve standardization across OEM platforms as inflection indicator for composite reinforcement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Integration | MEMS-enabled predictive maintenance contracts lock in multi-year mining fleet relationships across Western Australia's Pilbara autonomous haulage corridors. |
| Backward Integration into Steel Cord | In-house bead wire production mitigates East Asian supply concentration risk affecting radial carcass certification timelines. |
| EU Stage V Certification Investment | Load index recertification for battery-ballasted electric dozers preserves equipment homologation access in German and Scandinavian quarry markets. |
| Foam-Filled Variant Capacity Expansion | Polyurethane injection capabilities capture urban demolition contractor demand in North American metropolitan debris-handling applications. |
| India Domestic Manufacturing Footprint | Bureau of Indian Standards compliance gates position compounders for Madhya Pradesh and Rajasthan infrastructure project procurement. |
Research Methodology
Multiple input streams — procurement director interviews at Australian iron ore operators, compounder R&D lead discussions, and distributor channel assessments — were reconciled against trade customs data, mining safety regulator filings, and OEM equipment specification databases. Primary fieldwork engaged maintenance directors at Chilean copper extraction sites, aftermarket service heads in North American demolition contracting, and tire procurement managers across Indian state infrastructure projects. Secondary validation drew from MSHA surface equipment standards documentation, Australia's state-based mine safety regime filings, and EU Stage V homologation records. Bottom-up volume builds across product type and tread pattern segments were triangulated against top-down mining fleet renewal projections.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass carcass construction technology, tread geometry configuration, reinforcement material scheme, and end-use application intensity. CAGRs were derived from equipment fleet renewal schedules, electrification adoption curves, and replacement cycle compression factors. Industry-specific forecast inputs incorporated autonomous mining deployment rates and electric dozer battery ballast weight specifications affecting load index demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric dozer platform standardization, natural rubber supply disruption recurrence, and East Asian steel cord logistics friction. Forecasts reflect documented assumptions regarding mining safety inspection interval enforcement and emissions protocol implementation timelines. A small set of triggers — OEM electrification roadmap acceleration, Southeast Asian plantation climate events, and India import compliance gate tightening — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Backhoes Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Snow Removal Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Global Hot Runner Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Rotary Trommel Market