
 Resistance Welding Products Market | 2026-2036
Resistance Welding Products Market Size, Share, and Industry Trends Forecast 2026-2036
Resistance Welding Products Market Analytics
Automotive-grade weld quality certification is redrawing competitive boundaries in resistance welding equipment. The Lincoln Electric Company leverages in-house electrode manufacturing to control alloy consistency across its spot welding systems. Illinois Tool Works Inc. anchors its position through intensive R&D in microprocessor-controlled current modulation for thin-gauge aluminum. OBARA CORP dominates robotic welding gun supply to Japanese OEM transplant factories across North America and Europe.
Resistance welding products encompass electrodes, welding guns, transformers, controllers, and auxiliary fixtures that generate localized heat through electrical resistance at the joint interface, typically operating at 1,000–20,000 amperes with cycle times under 30 milliseconds to fuse overlapping metal sheets without filler material. Spot welders occupy the largest installed base due to body-in-white assembly requirements, while laser welders represent the fastest-expanding category as OEMs adopt remote welding for roof and door applications. Microprocessor-controlled technology captures the dominant margin pool by enabling real-time adaptive current adjustment, whereas mechanical systems face gradual displacement in new capital expenditure.
The EPA enforces workplace exposure limits for welding fumes under OSHA-aligned standards, compelling fabricators to specify low-spatter equipment that reduces ventilation burden. Japan's METI promotes JIS-compliant precision welding through its manufacturing technology roadmap, while the EU F-Gas Regulation indirectly advantages resistance processes over gas-dependent alternatives. Stakeholders must monitor how battery pack welding specifications evolve as cell-to-pack architectures demand higher joint density with thinner tab materials.
Market Dynamics
The EU F-Gas Regulation is compressing demand for gas-dependent welding processes while battery pack architectures demand higher joint density with thinner tab materials. This dual pressure is restructuring capital allocation across electrode suppliers and welding gun manufacturers.
Growth Catalysts
- Automotive aluminum adoption:OEMs are expanding aluminum-intensive body-in-white assembly lines to meet lightweighting mandates for electric vehicle range extension.
- F-Gas Regulation:The EU framework is accelerating shifts toward solid-state resistance welding technologies that eliminate consumable shielding gases entirely.
- Battery pack production:Cell-to-pack architectures require precision tab welding at higher joint densities, concentrating demand in German, Japanese, and US manufacturing clusters.
Market Restraints
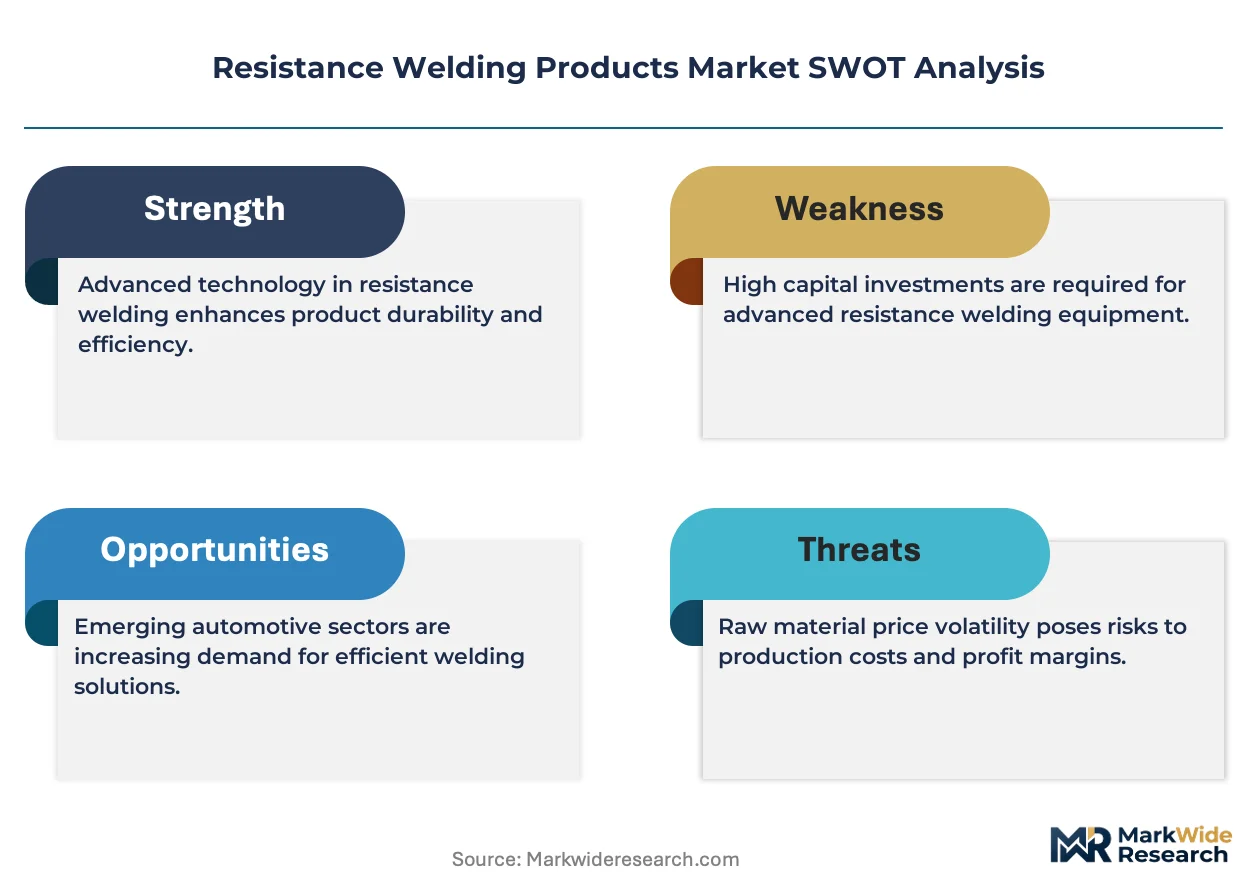
- Copper alloy volatility:Electrode manufacturing depends on copper-chromium-zirconium alloys with price swings tied to mining supply from Chile and Zambia.
- Transformer supply concentration:High-frequency welding transformer production clusters in Japanese and German mid-cap specialists, creating single-source risk for OEMs.
- Laser substitution:Remote laser welding for roof and door applications is capturing share in premium vehicle segments where cosmetic finish requirements exceed resistance weld capabilities.
Strategic Opportunities
- Indian EV manufacturing:The country's PLI scheme for automotive and battery production is creating first-mover advantage for welding equipment suppliers establishing local electrode production.
- Microprocessor convergence:Adaptive current modulation combined with machine vision feedback enables real-time quality prediction, opening premium pricing for integrated system suppliers.
- Service unbundling:Predictive maintenance contracts based on electrode wear algorithms represent recurring revenue streams separate from capital equipment sales.
Industry Challenges
- Weld technician scarcity:The shift from mechanical to microprocessor-controlled systems demands programming skills that vocational pipelines in Germany and Japan have not scaled to match.
- Dual certification burden:Suppliers must simultaneously maintain ISO 18278 automotive weld standards and site-specific OEM process approvals, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistance Welding Products Market |
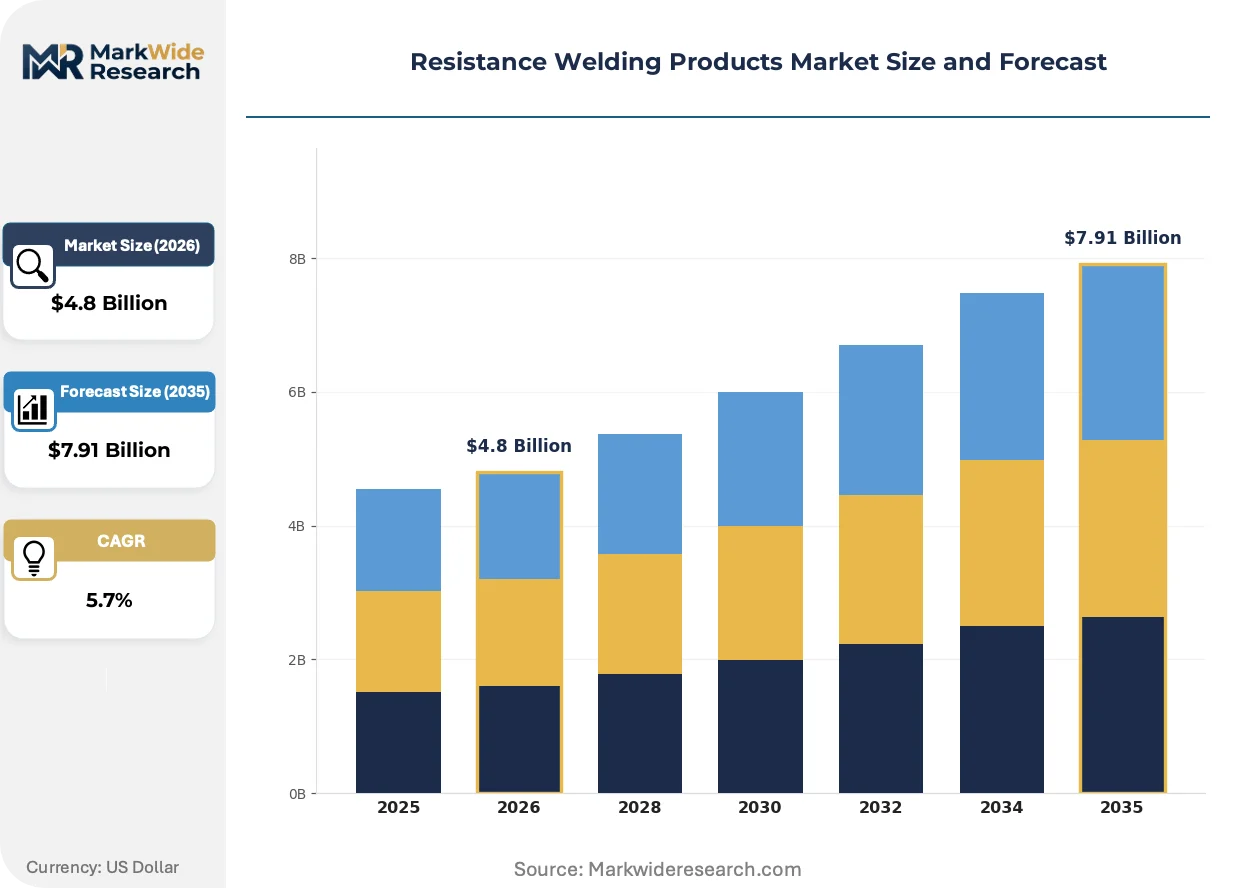
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spot Welders, Seam Welders, Projection Welders, Laser Welders Technology: Microprocessor-Controlled, Mechanical, Pneumatic, Hydraulic Application: Automotive Manufacturing, Aerospace Assembly, Electrical Equipment, Metal Fabrication End User: OEMs, Tier-1 Suppliers, Fabricators, Manufacturers |
| Companies Covered | The Lincoln Electric Company, Illinois Tool Works Inc., OBARA CORP, Panasonic Welding Systems Co., Ltd., AMADA WELD TECH, voestalpine AG, Air Liquide, Fronius International GmbH, DAIHEN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistance Welding Products Market Evolving Landscape
Adaptive process control is replacing fixed-parameter welding across automotive assembly lines. Real-time feedback systems now modulate current amplitude within individual cycles based on dynamic resistance measurements.
Medium-frequency direct current welding technology is displacing traditional alternating current transformer systems in aluminum spot welding applications. European and Japanese OEMs are adopting MFDC equipment for new battery tray and closure panel lines at accelerating rates. This displacement is compressing margins for legacy transformer suppliers while concentrating value capture in power electronics specialists with silicon carbide inverter expertise.
The EU F-Gas Regulation is mandating phase-down of hydrofluorocarbon consumption across industrial processes. Welding equipment purchasers in Germany, France, and Italy now face total cost of ownership calculations that favor resistance processes over MIG and TIG alternatives requiring shielding gas. Automotive OEMs are responding by specifying solid-state welding for new platform launches.
Battery manufacturers are consolidating supplier relationships around full-system integrators rather than component vendors. Tier 1 battery pack producers in the United States and South Korea now procure electrode-gun-transformer-controller packages from single sources with guaranteed joint quality outcomes. This consolidation is visible most acutely in the Michigan and Stuttgart corridors where cell-to-pack capacity is expanding fastest.
Resistance Welding Products Market Segmentation
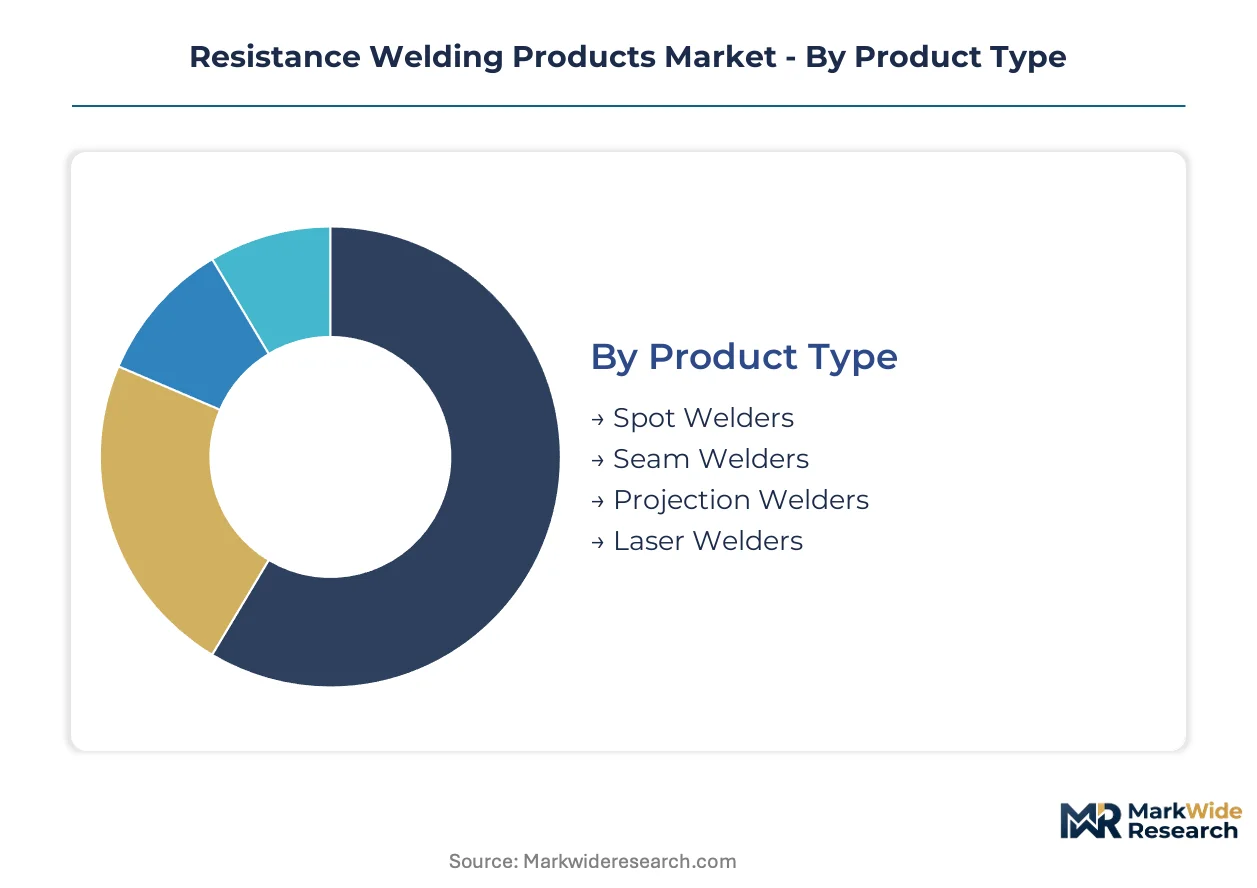
Resistance welding products serve divergent performance requirements across automotive body assembly, battery tab joining, and precision aerospace fabrication. Segmentation reveals where technology premiums concentrate and which equipment categories face displacement pressure from solid-state alternatives.
Product Type:
Margin pools concentrate in laser welding systems for cosmetic-critical applications and spot welding equipment for high-volume automotive lines.
- Spot Welders:These systems generate localized heat through electrode contact at 1,000–20,000 amperes with cycle times under 30 milliseconds, dominating body-in-white assembly for steel and aluminum sheet stacks. Demand concentrates in Germany, Japan, and Michigan where electric vehicle battery pack production requires precision tab welding at high joint densities.
- Laser Welders:Remote beam delivery enables non-contact joining of roof and door panels where cosmetic finish requirements exceed resistance weld capabilities. European and Japanese OEMs specify these systems for premium vehicle segments, though equipment costs limit penetration to high-margin product lines.
- Seam Welders:Continuous roller electrode systems create leak-tight joints for fuel tanks and exhaust components.
- Projection Welders:These machines localize current through embossed projections for nut and fastener attachment.
Spot welders hold installed capacity. Laser welders are rotating up the share rankings.
Technology:
Microprocessor-controlled systems command pricing premiums through real-time adaptive current modulation, while mechanical and pneumatic equipment faces gradual displacement.
- Microprocessor-Controlled:Digital current modulation enables cycle-by-cycle parameter adjustment based on dynamic resistance feedback, essential for thin-gauge aluminum welding in battery pack architectures. German and Japanese OEMs now specify these controllers as baseline for new platform launches.
- Mechanical:Fixed-parameter cam-driven systems retain relevance in low-mix, high-volume steel fabrication where changeover frequency remains minimal.
- Pneumatic:Compressed air actuation delivers cost-effective force control for general metal fabrication applications.
- Hydraulic:High-force systems serve heavy-gauge applications in construction equipment and railcar manufacturing.
Microprocessor-controlled equipment captures dominant margins. Mechanical systems are losing position in new capital expenditure decisions.
Application:
Automotive manufacturing absorbs the majority of resistance welding equipment shipments, though aerospace and electrical equipment applications sustain specialized demand.
- Automotive Manufacturing:Body-in-white assembly, battery tray fabrication, and closure panel joining drive equipment specifications. The EU F-Gas Regulation accelerates solid-state welding adoption as OEMs eliminate gas-dependent processes from new platform designs.
- Electrical Equipment:Busbar joining and switchgear fabrication require precision resistance welding for copper and aluminum conductors.
- Aerospace Assembly:Titanium and nickel alloy joining for engine components and structural brackets demands specialized equipment with NADCAP-compliant process control.
- Metal Fabrication:General job shop applications span furniture, appliances, and industrial equipment production.
Automotive manufacturing anchors volume demand. Aerospace assembly is gaining strategic importance for margin expansion.
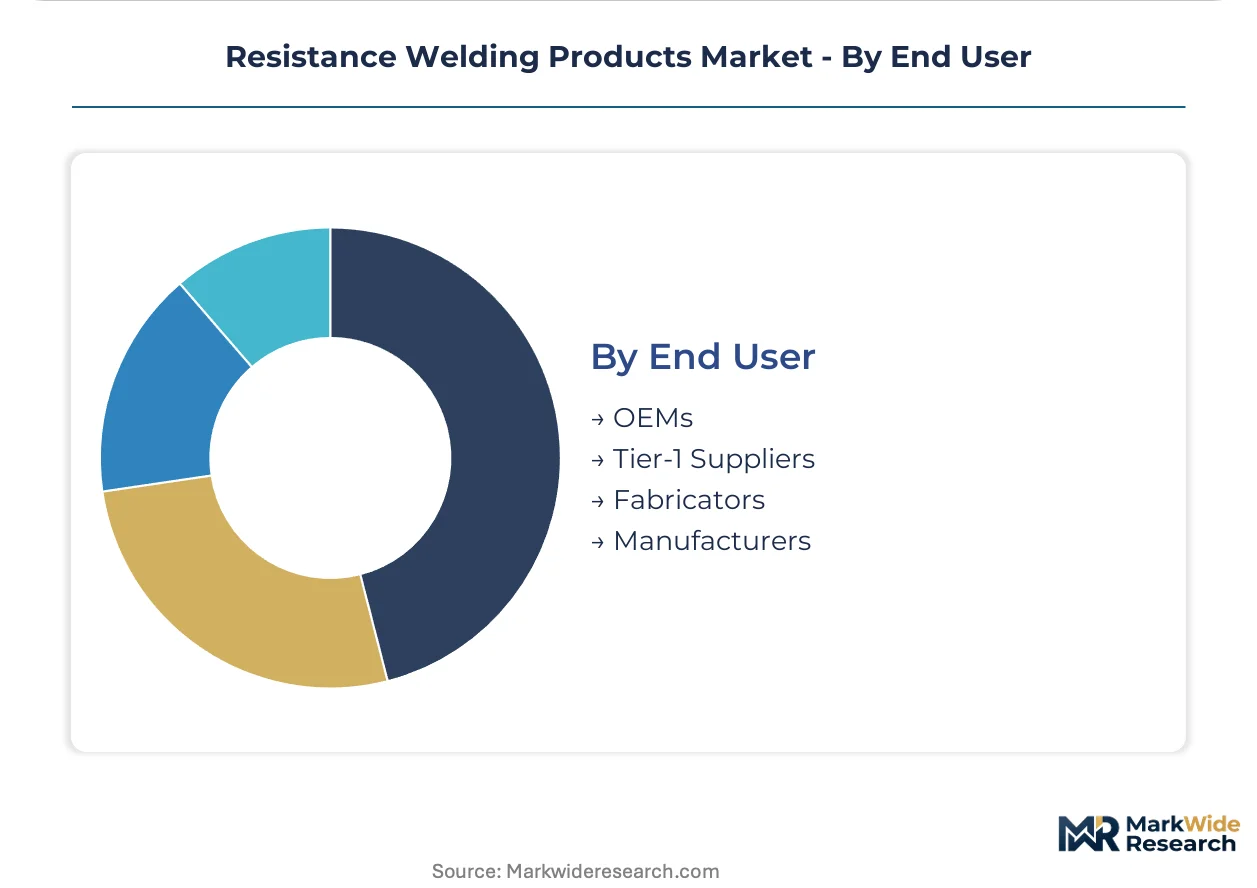
End User:
OEMs and Tier-1 suppliers concentrate procurement of integrated welding systems, while fabricators and independent manufacturers drive aftermarket electrode and component demand.
- OEMs:Vehicle manufacturers specify electrode-gun-transformer-controller packages with guaranteed joint quality outcomes, consolidating supplier relationships around full-system integrators in Michigan and Stuttgart corridors.
- Tier-1 Suppliers:Battery pack producers and body component suppliers procure medium-frequency direct current equipment for aluminum-intensive assembly lines.
- Fabricators:Job shops purchase standalone spot welding machines and consumable electrodes for contract manufacturing.
- Manufacturers:Industrial equipment and appliance producers maintain captive welding capacity for component production.
OEMs dictate technology roadmaps. Tier-1 suppliers are expanding procurement autonomy as cell-to-pack architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in resistance welding equipment reveal concentrated manufacturing in Germany and Japan against rising import dependence in the United States and India. Trade flows trace automotive investment cycles, with equipment shipments tracking EV battery factory announcements across three continents.
Germany
Battery tray and body-in-white assembly lines at Stuttgart and Munich-area OEM plants drive precision welding equipment imports from Japanese suppliers. The EU F-Gas Regulation accelerates platform redesigns eliminating gas-dependent processes, favoring solid-state resistance systems for new vehicle architectures. Industrial clusters around Wolfsburg and Ingolstadt concentrate electrode-gun-transformer procurement decisions.
United States
Michigan and Tennessee battery pack factories source medium-frequency direct current welding systems for aluminum-intensive cell-to-pack production. EPA workplace exposure standards under OSHA-aligned enforcement compel low-spatter equipment specifications that reduce ventilation infrastructure costs. The Detroit-Windsor corridor anchors North American demand concentration for robotic welding gun integration.
Japan
METI manufacturing technology roadmaps promote JIS-compliant precision welding for domestic EV battery and aerospace applications. Nagoya-area automotive suppliers export robotic welding systems to North American transplant factories, maintaining technology leadership in adaptive current modulation. Kansai-region power electronics specialists control high-frequency transformer production for global OEM supply chains.
China
Domestic electrode and welding gun production scales to serve BYD and CATL battery factory expansions across Fujian and Sichuan provinces. GB standards for automotive welding quality tighten certification requirements for equipment imports from European and Japanese suppliers. Yangtze River Delta manufacturing clusters develop captive electrode alloy production to reduce copper-chromium-zirconium import exposure.
India
PLI scheme incentives for automotive and battery production attract first-mover welding equipment suppliers establishing local electrode manufacturing in Tamil Nadu and Gujarat. Central Electricity Authority grid stability requirements influence power supply specifications for industrial welding installations. Chennai and Pune industrial corridors concentrate demand from emerging EV supply chain investments.
Resistance Welding Products Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. Market structure tiers between full-system integrators capturing OEM procurement consolidation and component specialists defending electrode and transformer niches. Strategic archetypes include captive alloy producers controlling upstream material consistency, power electronics houses with silicon carbide inverter expertise, and robotic integration firms bundling vision systems with welding guns. Competitive moves center on backward integration into electrode manufacturing and geographic co-location with battery factory investments.
Within the Japanese industrial equipment tier, OBARA CORP and DAIHEN Corporation exemplify robotic welding gun specialists serving automotive OEM transplant networks across North America and Europe. Among diversified manufacturing conglomerates, Illinois Tool Works Inc. occupies a position representing microprocessor-controlled technology integration for thin-gauge aluminum applications. Lincoln Electric anchors the electrode manufacturing archetype through in-house alloy production capabilities.
| Leading Market Players |
|---|
| The Lincoln Electric Company |
| Illinois Tool Works Inc. |
| OBARA CORP |
| Panasonic Welding Systems Co., Ltd. |
| AMADA WELD TECH |
| voestalpine AG |
| Air Liquide |
| Fronius International GmbH |
| DAIHEN Corporation |
| Others |
Value Network & Pricing Analysis
Medium-frequency direct current inverter adoption replacing traditional alternating current transformer systems simultaneously shifts procurement geography toward Japanese and German power electronics clusters while compressing margins for legacy equipment tiers. This substitution dynamic concentrates pricing power with silicon carbide inverter specialists and fragments negotiation leverage across mechanical transformer incumbents.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates microprocessor-controlled adaptive systems with real-time quality prediction from fixed-parameter mechanical units and pneumatic legacy equipment. Cost compression in economy tiers is intensifying because Chinese domestic manufacturers scale electrode production for BYD and CATL supply chains. Tier-1 battery pack producers exhibit least price sensitivity due to joint quality guarantees, while independent fabricators drive volume in price-sensitive spot welder categories.
Supply Chain Analysis
Just-in-time electrode replenishment dominates automotive body-in-white lines, whereas strategic stockpiling of copper-chromium-zirconium alloy feedstock persists among Japanese and German transformer specialists. Geographic supply concentration centers on Japan for robotic welding gun production, Germany for precision controller manufacturing, and China for electrode alloy processing. Raw material dependencies draw from Chilean and Zambian copper mining, Japanese silicon carbide substrate fabrication, and German power semiconductor packaging. Single-source vulnerability in high-frequency transformer production creates procurement risk for OEMs. Distribution runs through direct OEM integration contracts for full-system packages and aftermarket channel partners for consumable electrodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The resistance welding products market is recovering from cyclical capital expenditure compression as electric vehicle platform launches reactivate equipment procurement. Automotive aluminum adoption and battery pack capacity expansion constitute the primary cyclical drivers.
For Market Incumbents: Consolidate backward integration into electrode alloy production to defend against copper price volatility and Chinese domestic supply growth. Capture silicon carbide inverter expertise through targeted R&D allocation or specialist acquisition to maintain technology leadership as MFDC displacement accelerates. Prioritize geographic co-location with Michigan and Stuttgart battery factory corridors to secure OEM procurement consolidation.
For New Entrants and Emerging Players: Anchor in Indian PLI scheme jurisdictions to establish electrode manufacturing ahead of Tamil Nadu and Gujarat EV supply chain maturation. Target service unbundling opportunities through predictive maintenance algorithms and electrode wear monitoring systems. Pursue white-label controller integration for Tier-2 battery producers seeking cost-adaptive alternatives to full-system OEM packages.
For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by accelerating platform redesign cycles that favor solid-state welding specialists. Long-term viability favors power electronics houses with silicon carbide expertise and robotic integration firms bundling vision feedback systems. Acquisition targets should demonstrate NADCAP or ISO 18278 certification infrastructure and established OEM process approval relationships. The signal to watch is cell-to-pack architecture penetration rates in premium EV segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Alloy Production | In-house copper-chromium-zirconium manufacturing insulates Lincoln Electric from Chilean mining supply shocks. |
| Silicon Carbide Inverter Technology Acquisition | Power electronics expertise captures MFDC displacement value as European OEMs specify aluminum welding systems. |
| Predictive Maintenance Service Unbundling | Electrode wear algorithms generate recurring revenue streams independent of capital equipment sales cycles. |
| Geographic Co-location with Battery Corridors | Michigan and Stuttgart proximity secures OEM procurement consolidation for full-system integrators. |
| Machine Vision Feedback Integration | Real-time quality prediction commands premium pricing for adaptive current modulation systems. |
Research Methodology
Desk research of trade customs data, automotive production databases, and regulatory filings preceded structured interviews with OEM welding engineers, Tier-1 battery procurement managers, electrode manufacturing plant directors, and aftermarket service heads. Primary fieldwork with equipment distributors and power electronics specialists validated secondary findings from SEC filings, METI technology roadmaps, and EU F-Gas implementation guidance. Bottom-up equipment shipment analysis triangulated against top-down automotive capital expenditure projections.
Variance decomposition across product type, technology tier, application segment, and regional manufacturing cluster informed analytical framework construction over the projection horizon. Segmentation modeling incorporated electrode material grade, controller architecture, end-user procurement scale, and OEM platform lifecycle timing. CAGRs derived from regression analysis of historical capital expenditure patterns against battery capacity announcement pipelines and aluminum body-in-white adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EV production growth and F-Gas regulatory enforcement continuity; material deviation would warrant model refresh. Forecasts reflect base-case automotive investment cycles and copper alloy price stability assumptions. Revision becomes warranted when laser welding substitution rates in premium vehicle segments cross critical penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Vibrating Feed Conveyors Market