
 Plasma Welding Machine Market | 2026-2036
Plasma Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
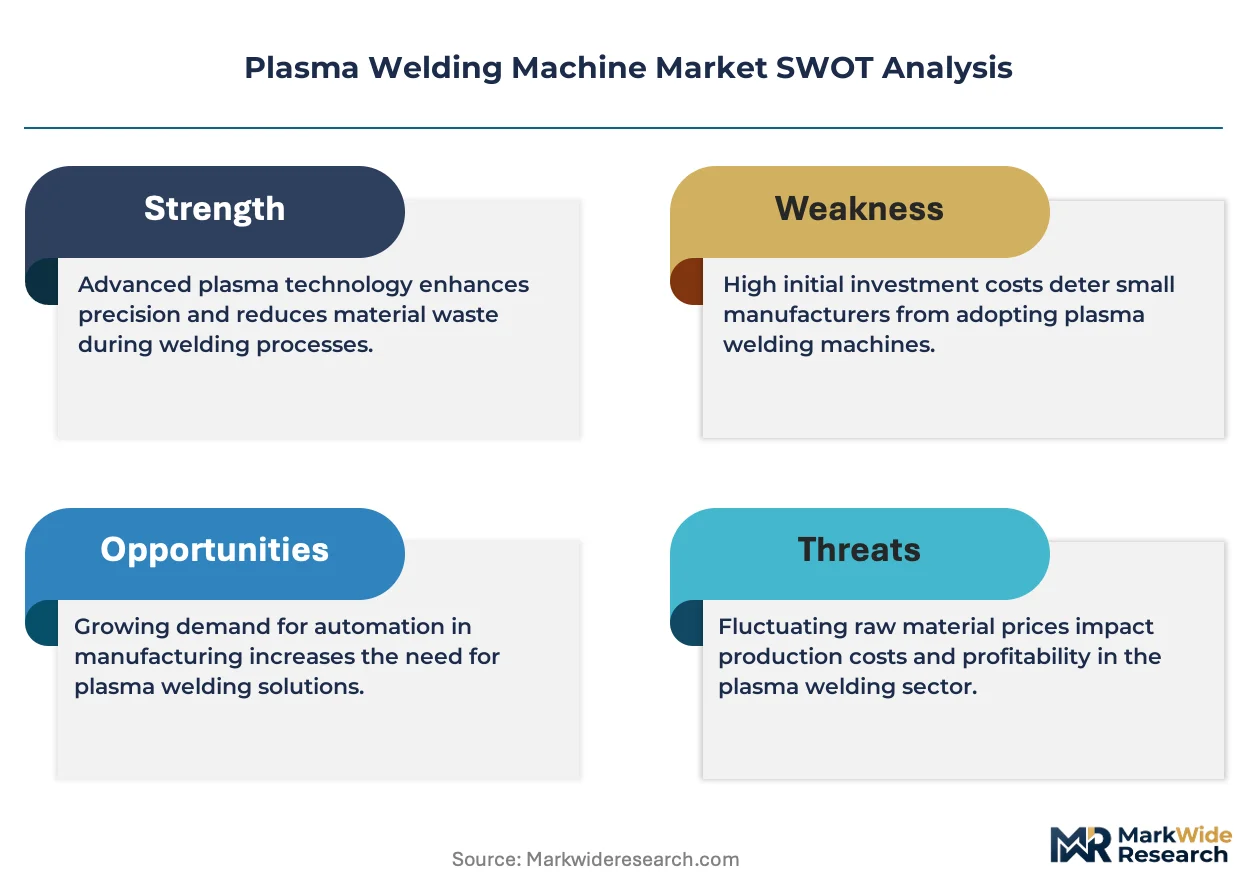
Plasma Welding Machine Market Analysis
The direct sales channel for industrial welding systems is narrowing as manufacturers consolidate distributor networks and push toward factory-direct engagement with large end users. Lincoln Electric Holdings Inc. leverages its captive distribution infrastructure to control pricing and service attach rates across North American fabrication shops. Fronius International GmbH anchors its position in European automotive supply chains through localized technical centers in Austria and Germany. DAIHEN Corporation dominates robotic plasma integration in Japan's precision manufacturing sector, sustaining long-term contracts with tier-one suppliers.
Plasma welding machines generate concentrated arc temperatures exceeding 20,000°C using ionized gas streams to fuse metals with minimal distortion, serving applications where conventional TIG or MIG processes lack precision. Automated systems lead the product type hierarchy as labor costs and repeatability requirements reshape factory floors, while handheld units retain share in field repair and maintenance environments. DC plasma technology occupies the largest technology segment due to its stability in stainless steel and nickel alloy joining, though hybrid plasma configurations are gaining traction where multi-material fabrication demands process flexibility.
The EPA enforces emission thresholds on welding fume capture systems that directly affect plasma equipment specification in US metalworking facilities, while REACH compliance in Europe restricts consumable alloy compositions and drives substitution toward certified filler materials. ISO 15614 welding procedure standards govern cross-border qualification protocols, creating certification barriers for equipment vendors entering regulated supply chains. Stakeholders must monitor evolving carbon border adjustments and machinery efficiency mandates that will reshape capital equipment procurement criteria across key manufacturing jurisdictions.
Market Dynamics
Automotive OEMs in Germany, Japan, and the United States are consolidating supplier bases for battery enclosure welding, forcing equipment vendors to certify simultaneously under ISO 15614, EASA airframe standards, and METI precision manufacturing guidelines.
Growth Catalysts
- EASA Airframe Certification:Tighter weld qualification protocols for commercial aviation are expanding automated plasma line investments at Airbus suppliers in Toulouse and Hamburg.
- EV Battery Enclosure Demand:Lithium-ion pack manufacturers require distortion-free sealing joints that DC plasma systems deliver on aluminum-copper dissimilar metal stacks.
- Stainless Steel Medical Device Fabrication:ISO 13485-certified shops in Minneapolis and Osaka are replacing TIG benches with micro-plasma cells for catheter and stent production.
Market Restraints
- Tungsten Electrode Supply Concentration:Over 70% of high-purity thoriated and lanthanated electrode feedstock originates from Chinese rare earth processing clusters, exposing buyers to export quota volatility.
- REACH Alloy Restrictions:ECHA's expanding candidate list of restricted substances limits consumable filler compositions, forcing European fabricators toward certified but higher-cost alternatives.
- Helium Ionization Gas Dependency:Plasma keyholing processes rely on helium blends where price spikes and US Bureau of Land Management reserve auctions create input cost instability.
Strategic Opportunities
- India PLI Scheme for Specialty Steel:Domestic stainless and nickel alloy production incentives are creating first-mover openings for plasma system vendors in Pune and Vadodara precision metalworking clusters.
- Additive Manufacturing Repair:Directed energy deposition cells using plasma arc wire feed are penetrating aerospace MRO facilities for blade and vane restoration.
- Carbon Border Adjustment Mechanism:EU CBAM phase-in is pushing Turkish and South Korean exporters toward certified low-distortion welding to avoid embodied carbon tariffs on fabricated components.
Industry Challenges
- Welding Procedure Qualification Bottlenecks:ISO 15614-1 testing protocols require 6-12 month validation cycles that delay equipment deployment at tier-two automotive suppliers.
- Multi-Axis Programming Skill Scarcity:Robotic plasma integration demands simultaneous proficiency in arc physics, PLC logic, and offline robot simulation software that training pipelines have failed to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Welding Machine Market |
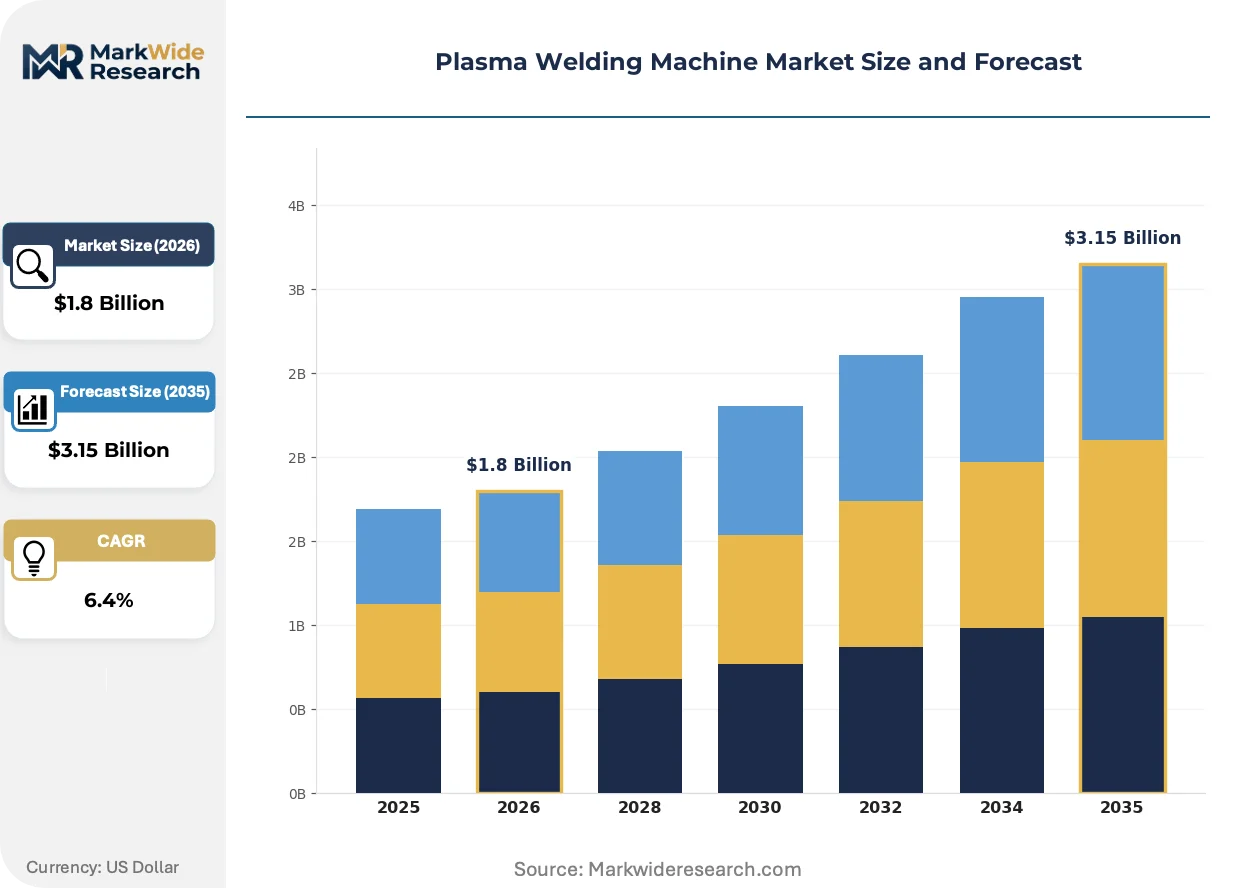
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Automated, Portable, Stationary Technology: DC Plasma, High-Frequency Plasma, Hybrid Plasma, Alternating Current Plasma End User: Manufacturing, Automotive, Aerospace, Construction Application: Metal Fabrication, Repair, Maintenance, Joining |
| Companies Covered | Lincoln Electric Holdings Inc., Hypertherm Inc., The ESAB Group Inc., Fronius International GmbH, EWM GmbH, DAIHEN Corporation, Miller Electric Manufacturing LLC, Air Liquide S.A., voestalpine Böhler Welding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Welding Machine Market Emerging Trajectories
Real-time arc monitoring and adaptive power modulation are compressing the gap between manual welder judgment and automated repeatability, with implications for both factory-floor layouts and service revenue models.
Vision-guided seam tracking combined with machine learning-based penetration prediction is digitizing quality assurance in high-mix, low-volume fabrication environments. Medical device contract manufacturers in Switzerland and Massachusetts are deploying these systems to eliminate post-weld radiographic inspection for Class III implantable components. The technology is digitizing the economics of short-run production by collapsing setup-to-first-part cycles from hours to minutes.
EPA enforcement of NESHAP Subpart XXXXXX fume capture efficiency is mandating integrated extraction hoods on all new plasma installations above 300A in US metalworking facilities. Fabricators in Ohio and Texas are selecting equipment bundles with factory-certified ventilation packages to preempt OSHA regional emphasis program inspections. The regulation is accelerating vendor consolidation toward suppliers with captive environmental compliance engineering capabilities.
After-sales service unbundling is fragmenting the traditional bundled maintenance contract model that dominated industrial welding equipment. Large automotive stampers in Stuttgart and Detroit are negotiating à la carte spare parts and remote diagnostics subscriptions, displacing comprehensive annual service agreements. South Korean shipyards have pioneered this shift, using internal maintenance teams trained at DAIHEN technical centers to reduce total cost of ownership.
Plasma Welding Machine Market Segmentation
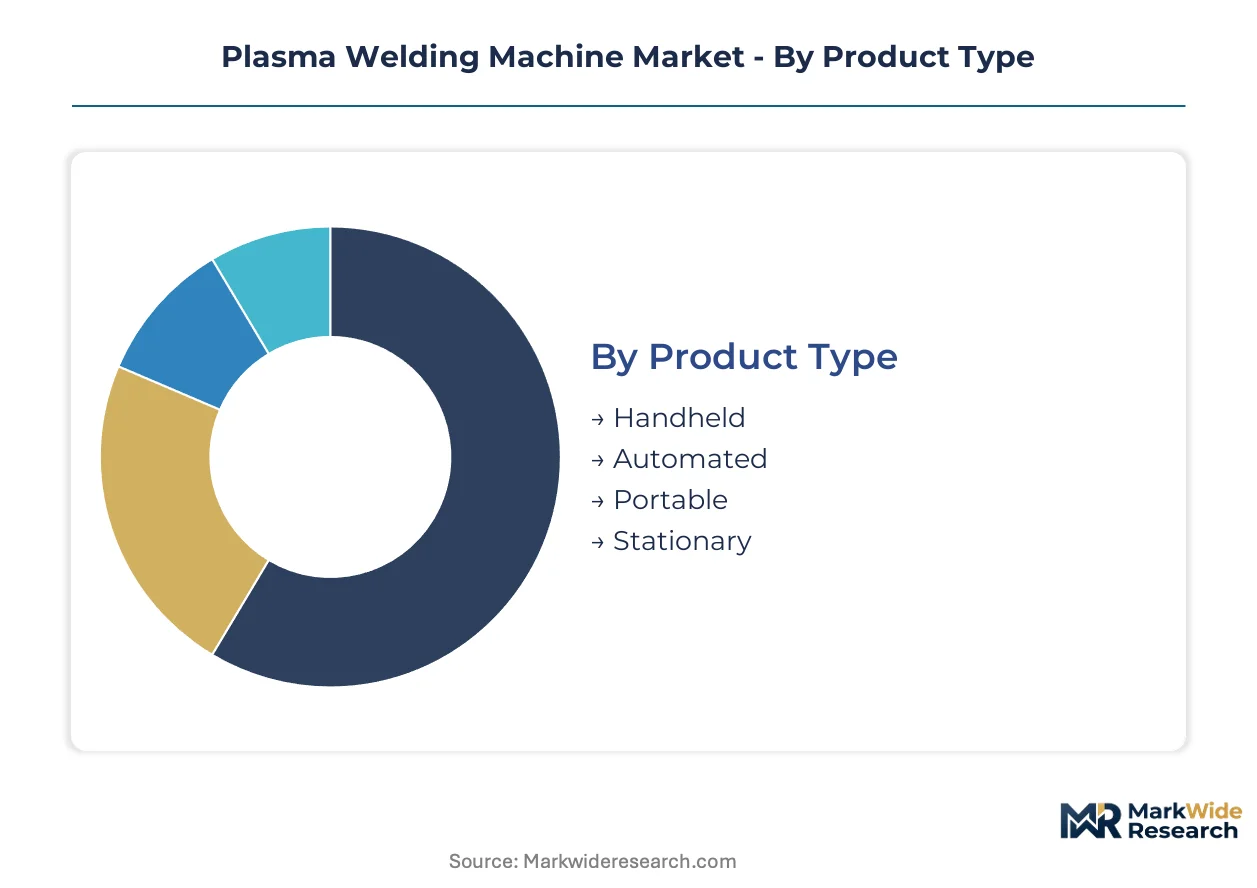
Plasma welding machine segmentation reflects divergent capital deployment strategies across precision manufacturing environments. Equipment specifications vary dramatically between high-volume automated lines and field-service portability requirements.
Product Type:
Handheld units serve repair technicians in confined spaces; automated systems dominate aerospace and automotive production floors where repeatability thresholds exceed manual capability.
- Automated:Multi-axis robotic cells integrate vision-guided seam tracking and adaptive power modulation for distortion-critical joints. Airbus suppliers in Toulouse and Hamburg deploy these systems under EASA airframe certification protocols that mandate weld procedure qualification.
- Handheld:Compact torch assemblies with micro-plasma capability enable field maintenance of stainless steel process piping. Technicians at South Korean shipyards favor these units for hull repair where dockside crane access is limited.
- Portable:Trailer-mounted power supplies with integrated gas blending support construction site mobilization across German industrial zones.
- Stationary:Fixed-position heavy-duty systems anchor dedicated fabrication cells in Minneapolis medical device shops certified to ISO 13485.
Established volume favors Automated; emerging adoption favors Portable.
Technology:
Power source architecture determines arc stability and material compatibility across alloy portfolios.
- DC Plasma:Direct current configurations deliver consistent arc characteristics for stainless steel and nickel alloy joining. Battery enclosure manufacturers in Stuttgart rely on DC systems for aluminum-copper dissimilar metal stacks where heat input control prevents intermetallic formation.
- Hybrid Plasma:Combined DC-pulsed waveform architectures enable multi-material fabrication without equipment changeover. Japanese precision metalworking clusters in Osaka are adopting these systems for high-mix, low-volume medical device production.
- High-Frequency Plasma:Ignition circuits using high-voltage oscillation support non-contact arc initiation on reflective surfaces.
- Alternating Current Plasma:Polarity reversal cycles reduce tungsten electrode erosion during magnesium alloy welding.
DC Plasma retains the largest installed base; Hybrid Plasma is climbing the fastest as flexibility premiums offset capital cost differentials.
End User:
Industry-specific quality mandates reshape equipment specification priorities.
- Aerospace:EASA and FAA certification protocols require automated plasma lines with full parameter traceability. Hamburg airframe suppliers invest in integrated quality data systems that archive every weld for airworthiness documentation.
- Automotive:EV battery enclosure welding demands distortion-free sealing joints that DC plasma systems deliver on thin-gauge aluminum. OEM consolidation of supplier bases in Detroit and Stuttgart forces simultaneous multi-standard certification.
- Manufacturing:General metal fabrication shops in China's precision clusters prioritize throughput over certification depth.
- Construction:Infrastructure contractors select portable systems with simplified operator interfaces for field deployment.
Aerospace commands the steepest expansion trajectory; Manufacturing holds the deepest installed base.
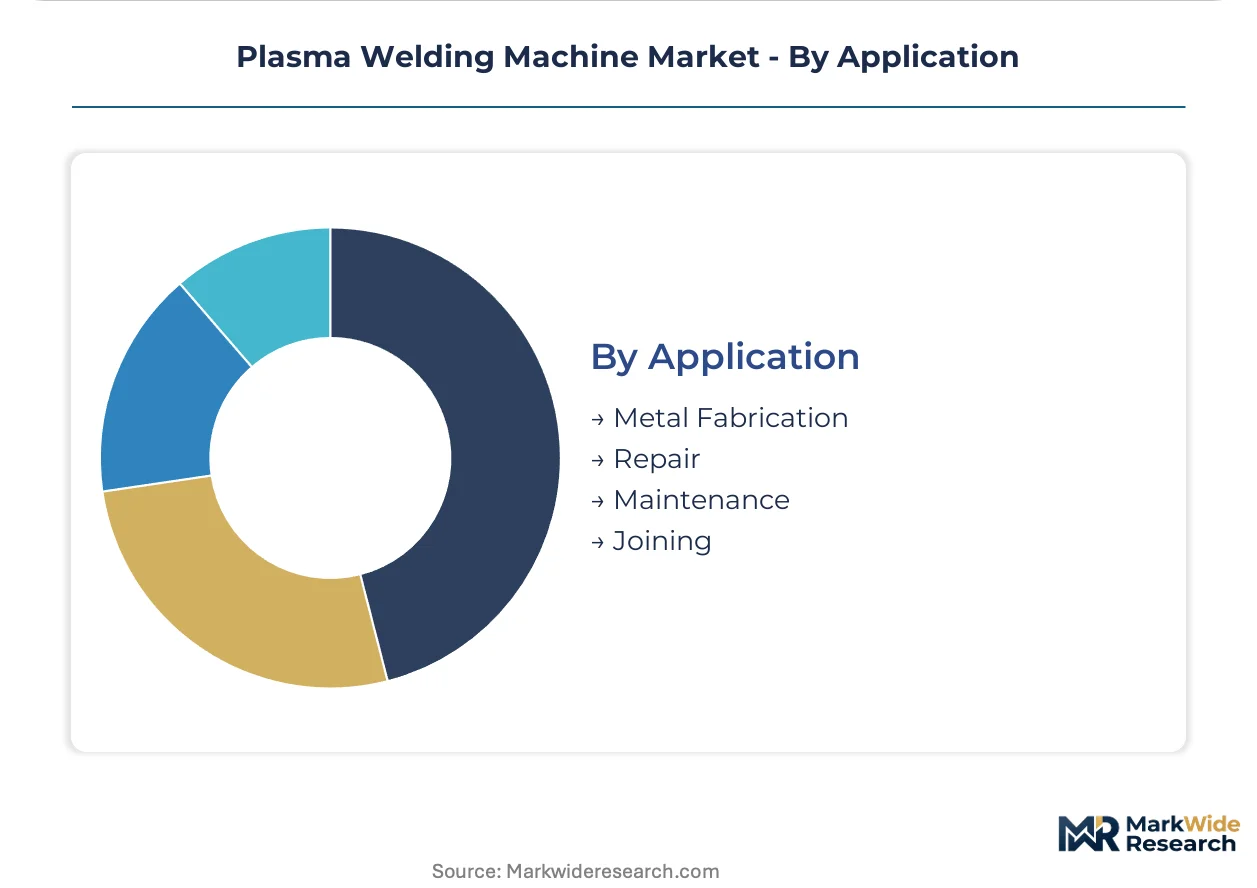
Application:
Process requirements dictate equipment configuration from precision micro-joining to structural restoration.
- Metal Fabrication:Original equipment production of pressure vessels, heat exchangers, and process piping relies on automated plasma for root pass consistency. Vadodara specialty steel shops under India's PLI scheme are commissioning these systems for domestic stainless production.
- Repair:Directed energy deposition using plasma arc wire feed penetrates aerospace MRO facilities for turbine blade restoration. Massachusetts and Switzerland host the densest concentrations of these additive repair cells.
- Joining:Permanent assembly operations in automotive body-in-white applications favor robotic integration with real-time penetration monitoring.
- Maintenance:Scheduled turnaround work at Texas petrochemical facilities deploys handheld units with EPA-compliant fume extraction hoods.
Metal Fabrication anchors procurement volume; Repair is gaining share fastest as aerospace MRO expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors in Germany command 15-20% price premiums over comparable systems from South Korean manufacturers, reflecting certification depth and captive service infrastructure rather than hardware differentiation alone. This pricing-power asymmetry reshapes procurement patterns across precision metalworking clusters worldwide.
United States
EV battery enclosure manufacturers in Michigan and Ohio require distortion-free aluminum-copper joining that DC plasma systems deliver. EPA enforcement of NESHAP Subpart XXXXXX fume capture rules mandates integrated extraction hoods above 300A installations. Minneapolis medical device shops certified to ISO 13485 anchor domestic demand for micro-plasma cells in catheter production.
Germany
Airbus suppliers in Hamburg and Toulouse expand automated plasma lines under EASA airframe certification protocols. REACH compliance through ECHA restricts consumable alloy compositions, forcing substitution toward certified filler materials. Stuttgart automotive stampers consolidate supplier bases for battery enclosure welding, demanding simultaneous multi-standard qualification.
Japan
Precision metalworking clusters in Osaka replace TIG benches with micro-plasma cells for stent and catheter fabrication. METI precision manufacturing guidelines govern robotic plasma integration at tier-one suppliers. DAIHEN Corporation sustains long-term contracts with domestic automotive and aerospace manufacturers through localized technical centers.
China
Stainless steel pressure vessel fabricators in Jiangsu and Zhejiang provinces drive volume demand for automated root-pass systems. The country's rare earth processing clusters supply over 70% of global thoriated and lanthanated tungsten electrode feedstock. Domestic precision metalworking clusters prioritize throughput over deep certification stacks.
India
The PLI scheme for specialty steel creates first-mover openings for plasma system vendors in Pune and Vadodara. BIS standards govern equipment safety certification for domestic metalworking facilities. Domestic stainless and nickel alloy production incentives attract capital equipment deployment in western India precision clusters.
Plasma Welding Machine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying power sources, torches, and gas delivery modules. The vendor base organizes around three archetypes: diversified industrial conglomerates with captive distribution, pure-play welding equipment specialists with regional technical centers, and robotic automation firms bundling plasma sources into multi-axis cells. Consolidation pressure concentrates among mid-tier European fabricators seeking scale to offset REACH compliance costs. Strategic moves center on backward integration into consumable electrode supply and geographic expansion through distributor acquisition in Asian precision manufacturing clusters.
Within the diversified industrial tier, Lincoln Electric Holdings Inc. and Fronius International GmbH occupy positions defined by captive distribution infrastructure and localized service networks. Lincoln Electric leverages its North American fabrication shop relationships to control pricing and service attach rates. Fronius anchors European automotive supply chains through technical centers in Austria and Germany. DAIHEN Corporation exemplifies the robotic integration archetype, sitting within Japan's precision manufacturing sector with long-term tier-one supplier relationships. These three represent distinct competitive postures: scale-driven distribution control, regional technical anchoring, and robotic system bundling respectively.
| Leading Market Players |
|---|
| Lincoln Electric Holdings Inc. |
| Hypertherm Inc. |
| The ESAB Group Inc. |
| Fronius International GmbH |
| EWM GmbH |
| DAIHEN Corporation |
| Miller Electric Manufacturing LLC |
| Air Liquide S.A. |
| voestalpine Böhler Welding GmbH |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European tungsten electrode refining is compressing margins across automated system tiers while amplifying pricing leverage for Chinese rare earth processors. German equipment vendors exploit captive technical center networks to sustain configured-to-order premiums against South Korean volume manufacturers.
Pricing Analysis
Configured-to-order pricing commands spreads of 40-60% above standard catalog configurations for EASA-certified automated lines with integrated quality data archiving. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and after-sales bundling. Pricing pressure stems from automotive OEM supplier base consolidation forcing simultaneous multi-standard qualification costs onto equipment vendors. Tier-two automotive stampers exhibit highest price sensitivity; aerospace MRO facilities show lowest due to airworthiness liability exposure.
Supply Chain Analysis
Export control regimes limiting plasma power source technology flows constrain vendor expansion into precision manufacturing clusters. Supply concentrates in China for thoriated tungsten electrodes, Germany for high-frequency inverter assemblies, and Japan for robotic integration modules. Raw material dependencies encompass helium blends for keyholing processes, lanthanated electrode feedstock, and nickel alloy filler compositions. Single-source vulnerability in Chinese rare earth processing exposes buyers to export quota volatility. Distribution runs through factory-direct engagement with large end users and captive distributor networks for mid-market fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs consolidate supplier bases for battery enclosure welding, forcing equipment vendors to absorb certification costs and extend payment terms.
For Market Incumbents: Pre-empt margin erosion in standard automated tiers by backward integration into consumable electrode supply and captive helium blending infrastructure. Defend positioning in EASA-certified aerospace lines through expanded Hamburg and Toulouse technical centers. Counter emerging robotic automation firms bundling plasma sources into multi-axis cells by unbundling after-sales service into à la carte remote diagnostics subscriptions.
For New Entrants and Emerging Players: India's western precision metalworking clusters around Pune and Vadodara offer underpenetrated white space under PLI scheme incentives for specialty steel production. Target medical device contract manufacturers in Switzerland and Massachusetts deploying vision-guided seam tracking for Class III implantable components. Enter through additive manufacturing repair partnerships with aerospace MRO facilities seeking directed energy deposition capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with captive consumable supply and long-term technical service contracts. Five-to-ten year viability favors robotic integration specialists with tier-one automotive relationships over pure-play power source manufacturers facing commodity pressure. Monitor helium auction outcomes from US Bureau of Land Management reserves as inflection indicator for input cost stability in keyholing process tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Supply | Captive thoriated tungsten feedstock insulates margins from Chinese export quota volatility. |
| Localized Technical Center Expansion | Hamburg and Toulouse facilities accelerate EASA airframe certification cycles for Airbus suppliers. |
| Service Unbundling and Remote Diagnostics | À la carte subscriptions displace comprehensive annual agreements at Stuttgart automotive stampers. |
| Additive Manufacturing Repair Partnerships | Directed energy deposition cells penetrate Massachusetts aerospace MRO facilities for blade restoration. |
| Helium Blending Infrastructure Investment | Integrated gas delivery modules reduce dependency on Bureau of Land Management reserve auctions. |
Methodological Framework
Operator-level perspectives from maintenance directors at automotive stampers, plant engineers in medical device fabrication, OEM procurement teams for battery enclosures, and aftermarket service heads in aerospace MRO anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings of diversified industrial conglomerates, EASA airworthiness directives, EPA NESHAP enforcement records, and customs data on tungsten electrode trade flows. Bottom-up equipment deployment tracking across precision metalworking clusters triangulated against top-down vendor revenue segmentation.
Scenario-bracketing framed low, base, and high cases across the projection horizon using elasticity assumptions for helium price spikes and REACH compliance cost pass-through. Segmentation dimensions encompassed product type hierarchy, power source architecture, end-user industry mandates, and application process requirements. CAGRs derived from installed base turnover rates and replacement demand modeling. Industry-specific inputs included EASA certification pipeline backlogs and PLI scheme disbursement schedules for Indian specialty steel production.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed equipment manufacturers or sudden helium reserve policy shifts would shift outcomes. Material shifts in rare earth export licensing or carbon border adjustment mechanism enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Road Roller Market
Construction Equipment
Global Welding Market
Construction Equipment
Shield Machines Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Stud Welding Guns Market