
 Epoxy Glue Market | 2026-2036
Epoxy Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Glue Market Analytics
Asian petrochemical feedstock corridors is hardening the cost position of regional epoxy resin producers. Henkel AG & Co. KGaA leverages its automotive OEM certification network to anchor premium structural bonding contracts. Dow Inc. sustains technology leadership through proprietary curing agent portfolios. Sika AG dominates construction-grade formulations with deep contractor channel relationships.
Epoxy glue comprises a thermosetting polymer system formed by reacting epichlorohydrin with bisphenol-A or bisphenol-F, yielding cured bonds with tensile strengths exceeding 2,000 psi and chemical resistance across pH extremes. The primary industrial purpose centers on permanent load-bearing adhesion in metal, composite, and concrete assemblies where mechanical fasteners fail or add unacceptable weight. Structural grades command the deepest margin pools due to aerospace and wind energy certification burdens. Fast cure variants are gaining fastest in automotive assembly lines where cycle time compression dictates tooling economics. Rigid formulations remain mature in conventional construction, while flexible epoxies are displacing polyurethane alternatives in vibration-dampening electronics applications.
EPA VOC regulations restrict solvent content in commercial adhesive formulations, pushing manufacturers toward 100% solids and waterborne epoxy systems. REACH compliance in Europe mandates disclosure of Substances of Very High Concern across imported resin precursors, elevating documentation costs for non-EU suppliers. OSHA workplace exposure limits for amine hardeners further constrain small-batch blending operations. Stakeholders must monitor evolving biobased feedstock certifications and regional carbon border adjustments that will redefine cost-competitive sourcing geography.
Market Dynamics
Automotive OEMs are compressing assembly cycle times to under 90 seconds per bonded joint, forcing adhesive suppliers to reformulate cure kinetics without sacrificing structural certification. This pressure is reshaping R&D allocation across the entire epoxy value chain.
Growth Catalysts
- Lightweighting mandates:NHTSA fuel economy standards push Detroit and Stuttgart automakers to replace mechanical fasteners with structural epoxy bonds in aluminum-intensive vehicle platforms.
- REACH SVHC disclosure:ECHA's expanded candidate list forces downstream transparency, creating competitive advantage for European formulators with pre-certified supply chains.
- Wind blade scaling:15-meter root diameters in offshore turbines demand toughened epoxy systems that pass DNV-ST-0126 fatigue testing for 25-year service life.
Market Restraints
- Epichlorohydrin volatility:Propylene feedstock costs swing with Asian naphtha spreads, compressing margin predictability for non-integrated resin producers.
- Amine hardener oligopoly:Three German and Japanese chemical houses control 70% of cycloaliphatic amine supply, creating single-source vulnerability for small-batch blenders.
- Polyurethane substitution:Sika and Huntsman are advancing moisture-cure PUR systems that match epoxy shear strength at lower cure temperatures for construction applications.
Strategic Opportunities
- India infrastructure build-out:National Highways Authority of India is specifying epoxy-coated rebar for coastal bridges, opening specification battles among international suppliers.
- Biobased feedstock certification:USDA BioPreferred and TÜV OK Compost labels command 12-18% price premiums in consumer-facing electronics packaging adhesives.
- Digital dispensing integration:Collaborative robots with vision-guided dispensing heads are creating aftermarket service contracts that bundle adhesive with application equipment.
Industry Challenges
- Formulation chemist scarcity:Retiring baby-boomer polymer scientists are leaving knowledge gaps in amine-epoxy stoichiometry optimization for ultra-fast cure applications.
- Aerospace qualification timelines:OEM lock of new adhesive grades through Boeing BAC 5514 or Airbus AIMS standards extends 18-36 months, freezing competitive rotation.
- Legacy ERP integration:Batch record systems from the 1990s resist connectivity with modern IoT curing monitors, complicating Industry 4.0 transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Glue Market |
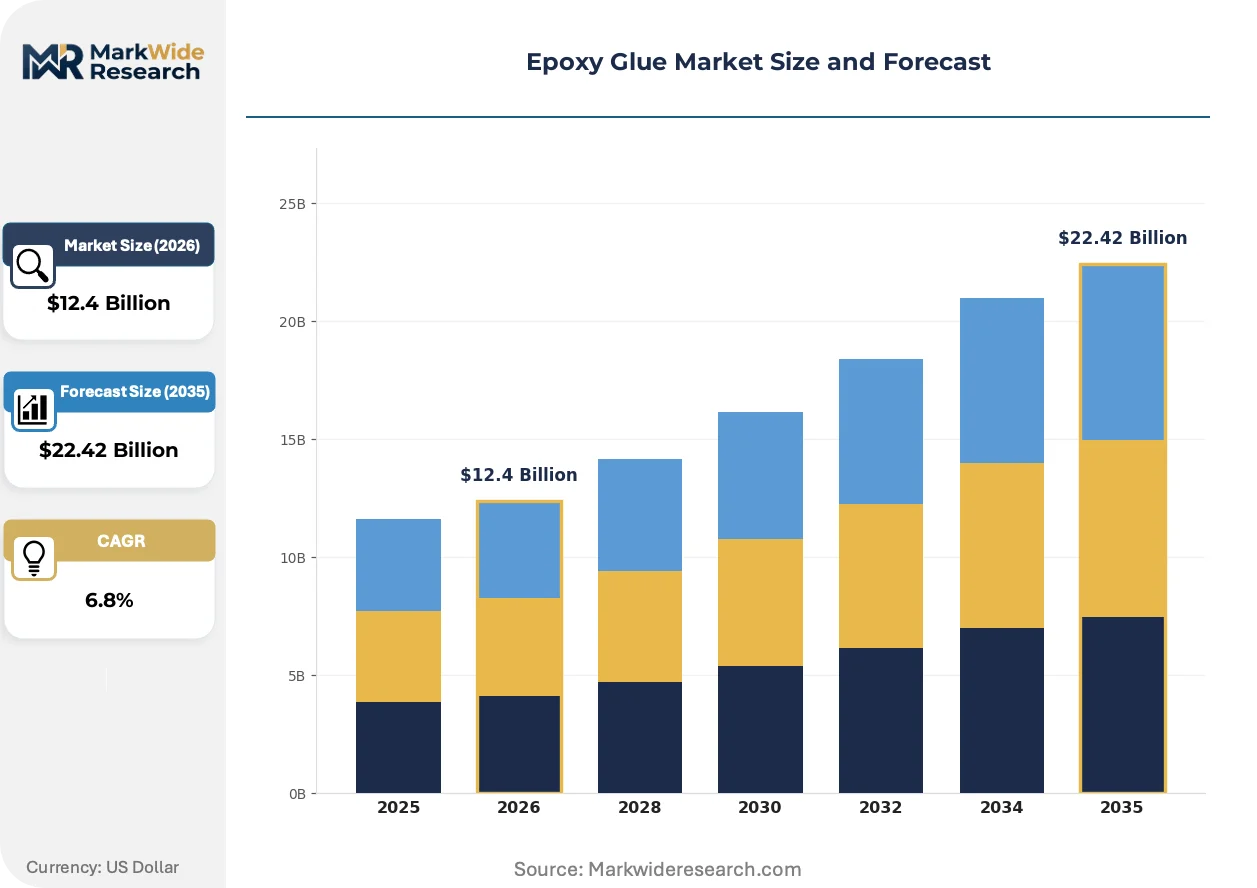
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Fast Cure, Structural Application: Automotive, Construction, Electronics, Aerospace End User: Manufacturers, DIY Enthusiasts, Contractors, Engineers Distribution Channel: Online Retailers, Wholesale Distributors, Specialty Stores, Direct Sales |
| Companies Covered | 3M, Henkel AG & Co. KGaA, H.B. Fuller Company, Sika AG, Dow Inc., Arkema Group, Ashland, Bostik, Permabond LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Glue Market Evolving Landscape
Formulation chemistry is converging with process automation and regulatory disclosure requirements, compressing the traditional three-year product development cycle into 18-month sprints for qualified suppliers.
Dual-cure epoxy systems combining UV snap-set with thermal post-cure are automating throughput in electronics assembly lines where shadow areas previously required batch oven processing. Foxconn and Pegatron are deploying these systems across Shenzhen and Zhengzhou facilities to eliminate WIP buffers. The technology is automating line balancing decisions that previously required manual takt time adjustments.
EPA Method 24 VOC testing protocols are tightening solvent content thresholds for commercial adhesive categories, pushing formulators toward 100% solids and waterborne epoxy platforms. Small Midwestern blenders without captive resin production face capital barriers to compliance. Construction-grade product lines serving California South Coast Air Quality Management District jurisdictions are reformulating fastest.
Direct procurement from adhesive manufacturers is displacing traditional distribution in wind energy and aerospace sectors where technical service integration outweighs inventory convenience. Vestas and Siemens Gamesa are negotiating multi-year supply agreements that embed field engineering support. Germany and Denmark host the most concentrated buyer consolidation, with three OEMs controlling 80% of European blade epoxy demand.
Epoxy Glue Market Segmentation
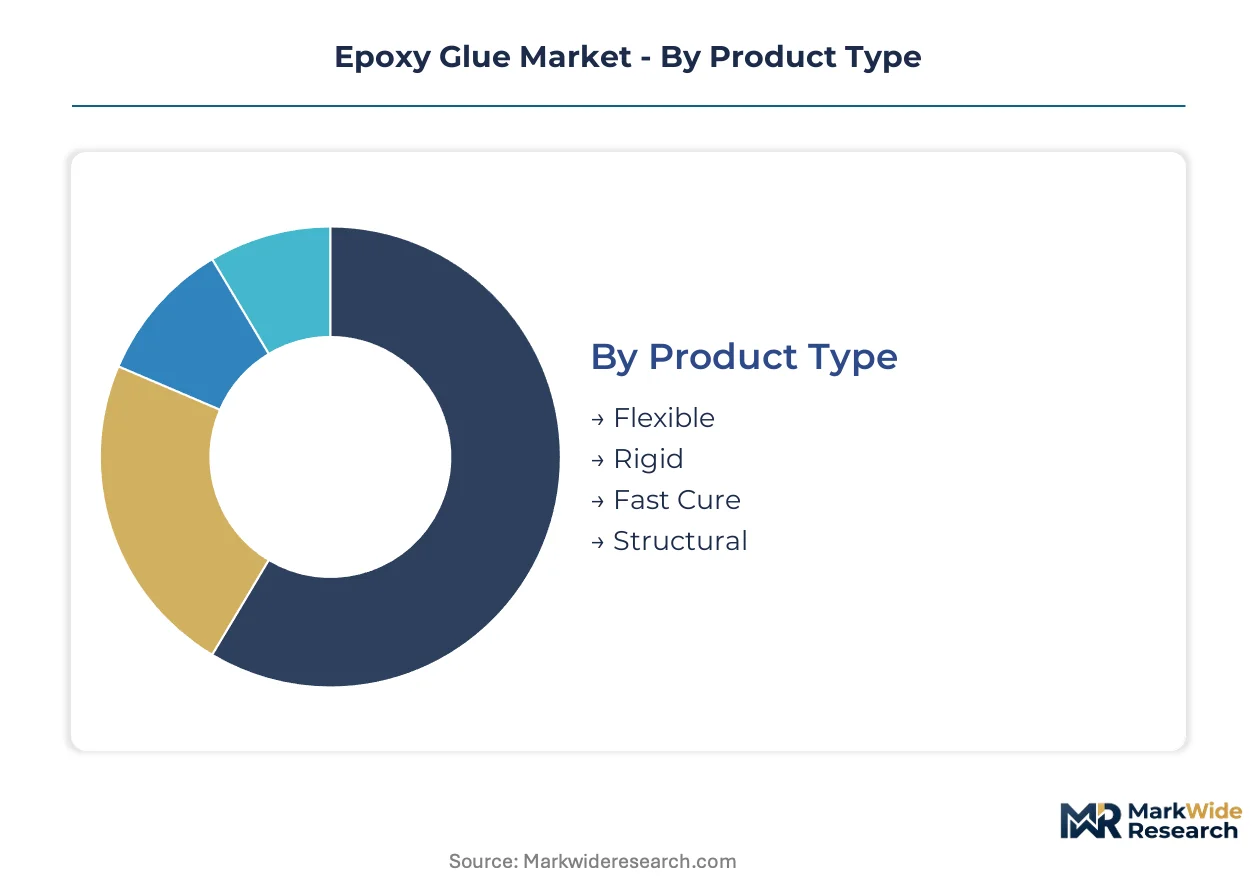
Epoxy glue segmentation reveals how formulation chemistry, cure kinetics, and certification burdens fragment margin pools across industrial supply chains. Understanding these divides exposes where technical service integration commands premium pricing versus where commodity blending competes on logistics.
Product Type:
Supply concentration in amine hardeners and specialty resins concentrates margin capture among integrated producers with captive feedstock access.
- Flexible:Modified with reactive diluents and rubber tougheners to achieve elongation at break above 15%. Electronics manufacturers in Shenzhen and Zhengzhou specify these grades for PCB vibration damping where thermal cycling exceeds 1,000 cycles. Supply chains favor Japanese and German resin houses with proprietary flexibilizer portfolios.
- Rigid:Unmodified bisphenol-A systems delivering compressive strength above 10,000 psi. Construction contractors across Germany and the US Midwest specify these for concrete crack injection where load transfer efficiency matters. Price pressure is severe from Asian commodity producers with naphtha-integrated epichlorohydrin positions.
- Fast Cure:Accelerated aliphatic amine formulations achieving handling strength in under 15 minutes. Automotive OEMs in Stuttgart and Detroit drive specification.
- Structural:Toughened systems meeting aerospace and wind energy fatigue certifications. DNV-ST-0126 qualification creates single-source dependence for blade root bonding.
Today's leader: Structural. Tomorrow's challenger: Fast Cure.
Application:
Cost tier stratification separates specification-driven sectors with embedded technical service from price-sensitive volume markets.
- Automotive:Structural bonding of aluminum-intensive platforms where rivet elimination saves 2-4 kg per vehicle. NHTSA fuel economy mandates push Detroit and Stuttgart OEMs toward certified epoxy systems with documented crash performance. Cycle time compression below 90 seconds per joint forces reformulation of cure kinetics.
- Construction:Concrete repair, rebar coating, and composite strengthening dominate volume. India's National Highways Authority specifies epoxy-coated rebar for coastal bridges, opening specification battles among European and Japanese suppliers with pre-certified supply chains.
- Electronics:Underfill, potting, and thermal interface applications. Miniaturization drives demand for low-viscosity, high-purity grades.
- Aerospace:Primary and secondary structural bonding with 25-year service life requirements. Boeing BAC 5514 and Airbus AIMS qualification timelines extend 18-36 months.
Construction commands current volume. Automotive offers the steepest expansion trajectory.
End User:
Customer type determines whether procurement optimizes for technical integration, inventory availability, or unit economics.
- Manufacturers:Integrated production lines with automated dispensing and in-process cure monitoring. Direct procurement from adhesive producers dominates, displacing distribution layers.
- DIY Enthusiasts:Small-package retail through home improvement channels. Price sensitivity limits penetration of premium formulations.
- Contractors:Project-based demand with irregular volume patterns. Wholesale distributors and specialty stores compete on availability and credit terms.
- Engineers:Specification authority without purchase execution. Technical documentation and certification packages drive supplier selection.
Manufacturers currently concentrate value capture. Contractors represent the most fragmented, least penetrated tier.
Distribution Channel:
Channel choice reflects the trade-off between technical service embedding and logistics efficiency across end-use segments.
- Online Retailers:Growing share in DIY and small-batch industrial procurement. Amazon Business and Alibaba challenge traditional distributors on price transparency.
- Wholesale Distributors:Construction and contractor segments depend on regional inventory positioning and credit facilities. W.W. Grainger and Fastenal compete on same-day availability.
- Specialty Stores:Technical advice and product demonstration for professional users. Surviving chains emphasize application equipment bundling.
- Direct Sales:Wind energy and aerospace OEMs negotiate multi-year agreements embedding field engineering support. Vestas and Siemens Gamesa procurement teams favor this channel.
Direct sales currently deepen account control. Online retailers gain fastest in small-batch segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping epoxy glue production geography as formulators migrate toward jurisdictions with lower compliance documentation burdens and integrated petrochemical feedstock access.
China
Domestic infrastructure build-out and electronics manufacturing clusters drive volume consumption of high-performance adhesive systems. MEE enforcement of GB standards for VOC emissions pushes coastal formulators toward waterborne platforms. Shenzhen and Zhengzhou host Foxconn and Pegatron facilities deploying dual-cure epoxy systems for electronics assembly automation.
United States
Automotive OEMs in Detroit compress assembly cycle times below 90 seconds per bonded joint, demanding reformulated fast-cure epoxies. EPA Method 24 VOC testing protocols tighten solvent content thresholds for commercial adhesive categories. California South Coast Air Quality Management District jurisdictions force fastest reformulation of construction-grade product lines.
Germany
Stuttgart automakers specify structural bonding systems for aluminum-intensive vehicle platforms under NHTSA-equivalent EU fuel economy mandates. ECHA REACH SVHC disclosure requirements create competitive advantage for domestic formulators with pre-certified supply chains. Hamburg and Cologne anchor wind energy blade manufacturing clusters demanding DNV-ST-0126 qualified toughened epoxy systems.
India
National Highways Authority specifications for epoxy-coated rebar in coastal bridges open specification battles among international suppliers. BIS certification requirements for construction adhesives elevate entry barriers for non-domestic producers. Maharashtra and Gujarat infrastructure corridors concentrate demand for concrete repair and composite strengthening formulations.
Japan
METI industrial standards for electronics-grade adhesives mandate purity thresholds that filter small-batch blenders from high-reliability supply chains. Osaka and Nagoya manufacturing belts specify low-viscosity underfill epoxies for PCB miniaturization. Domestic resin houses maintain proprietary flexibilizer portfolios for vibration-dampening applications.
Epoxy Glue Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biobased certification and digital dispensing integration as differentiation vectors. The vendor base stratifies across integrated petrochemical houses with captive epichlorohydrin supply, regional formulators with deep contractor channel relationships, and specialty blenders serving aerospace qualification timelines. Three strategic archetypes dominate: feedstock-integrated resin producers, application-integrated dispensing system bundlers, and certification-anchored aerospace specialists. M&A activity concentrates on hardener technology acquisitions and regional distribution network consolidation.
Within the integrated chemical house tier, Dow Inc. and Arkema Group exemplify feedstock-backed positions that compress margin volatility for downstream formulators. Henkel AG & Co. KGaA and Sika AG occupy distinct archetypes—Henkel leverages automotive OEM certification networks while Sika dominates construction-grade channels through contractor relationships. These four anchors illustrate how competitive positioning fragments across end-use specialization rather than converging on undifferentiated volume.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Sika AG |
| Dow Inc. |
| Arkema Group |
| Ashland |
| Bostik |
| Permabond LLC |
| Others |
Value Network & Pricing Analysis
Captive epichlorohydrin production anchors margin control for integrated resin houses, compressing cost volatility exposure while enabling aggressive pricing in construction-grade segments where Asian commodity producers compete. This upstream integration choice separates pricing power between feedstock-backed formulators and small-batch blenders vulnerable to propylene cost swings.
Pricing Analysis
Distributor margin layers in construction channels absorb 15-25 points before contractor pricing, while direct-to-OEM aerospace and wind energy contracts embed technical service premiums. Three-tier pricing structure across structural certification grades, standard industrial formulations, and commodity construction blends captures value from DNV-ST-0126 qualification burdens down to price-driven rebar coating specifications. Cost compression in rigid bisphenol-A construction grades intensifies because Asian naphtha-integrated producers flood export markets. DIY enthusiasts and small contractors exhibit highest price sensitivity, whereas automotive and aerospace OEMs prioritize certification documentation over unit cost.
Supply Chain Analysis
Epichlorohydrin supply rests on naphtha-integrated petrochemical corridors in China, South Korea, and Saudi Arabia, with European and North American producers dependent on imported propylene feedstocks. Specialty amine hardener production concentrates among German and Japanese chemical houses, while bisphenol-A and bisphenol-F resins source from integrated phenol chains. Single-source vulnerability in cycloaliphatic amine supply creates procurement risk for non-integrated formulators lacking long-term offtake agreements. Distribution runs through wholesale distributors for construction and contractor segments, with direct sales dominating wind energy and aerospace where field engineering integration outweighs inventory convenience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epoxy glue market compounds steadily as automotive lightweighting mandates and wind blade scaling create durable specification demand across industrial supply chains.
For Market Incumbents: Hedge margin exposure in commodity construction grades by securing captive epichlorohydrin supply or long-term feedstock offtakes, while accelerating certification investment in structural grades where DNV-ST-0126 and Boeing BAC 5514 create defendable positions against polyurethane substitution threats from Sika and Huntsman. For New Entrants and Emerging Players: Digital dispensing integration with collaborative robot systems offers a technology-first wedge into automotive assembly line retrofits, targeting mid-tier suppliers in Stuttgart and Detroit lacking in-house automation expertise. Biobased feedstock certification for electronics packaging adhesives opens specification battles where USDA BioPreferred labels command measurable premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity intersects with retiring baby-boomer technical knowledge, creating acquisition opportunity in specialty blenders with aerospace qualification pipelines. Hardener technology portfolios and regional distribution networks represent priority target archetypes. Amine hardener supply disruption or REACH SVHC list expansion signal inflection points warranting portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive feedstock supply insulates margin volatility from Asian naphtha price swings. |
| Dual-Cure System Platform Launch | UV-thermal hybrid chemistry eliminates WIP buffers in Foxconn and Pegatron electronics lines. |
| Long-Term Supply Agreement with Wind OEM | Multi-year Vestas or Siemens Gamesa contracts embed field engineering and deepen account control. |
| Biobased Feedstock Certification Program | USDA BioPreferred and TÜV OK Compost labels unlock 12-18% price premiums in consumer electronics. |
| Joint Venture for Regional Production Hub | Local formulation in Maharashtra or Gujarat satisfies BIS certification requirements for NHAI infrastructure projects. |
Research Methodology
Bottom-up automotive and wind energy demand modeling reconciled against top-down epoxy resin production tracking forms the analytical core of this study. Primary interviews with adhesive formulators, automotive Tier 1 procurement leads, wind blade manufacturing engineers, and construction contractor purchasing managers combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, customs trade data, and EPA Method 24 regulatory filings. This triangulation ensures volume estimates align with actual production capacity and disclosed offtake patterns.
Input-output matrices map epichlorohydrin and amine hardener flows through formulation tiers to end-use consumption across the projection horizon. Segmentation dimensions include product type chemistry, application industry, cure kinetics requirements, and regional regulatory cluster. CAGRs derive from fitted growth curves against disclosed OEM platform ramp schedules and infrastructure investment pipelines, with sensitivity testing around NHTSA fuel economy compliance timelines and REACH SVHC disclosure expansion scenarios.
The model holds under stable petrochemical feedstock pricing and current regulatory enforcement intensity; deviation in propylene cost volatility or accelerated biobased mandate adoption would shift volume trajectories. Forecasts reflect documented assumptions about OEM lightweighting program commitments and wind energy installation rates. A small set of named triggers—amine hardener supply disruption, carbon border adjustment implementation, and aerospace qualification timeline compression—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Cycloaliphatic Epoxy Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market