
 North America Human Fibrin Glue Market | 2026-2036
North America Human Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
North America Human Fibrin Glue Market Analytics
United States plasma fractionation capacity is reshaping supply security across the North America Human Fibrin Glue Market. Baxter International leverages its vertically integrated plasma collection network to sustain fill-finish output for surgical sealants. Grifols anchors European-sourced fibrinogen supply into U.S. compounding operations through specialized cold-chain logistics. Johnson & Johnson (Ethicon) competes on suture-integrated delivery platforms that bundle mechanical closure with biologic hemostasis.
Human fibrin glue comprises a two-component biologic adhesive combining human fibrinogen and thrombin, typically stabilized with aprotinin or tranexamic acid to prevent premature polymerization; manufacturers precipitate fibrinogen from pooled human plasma via cryoprecipitation followed by viral inactivation steps, producing a viscous sealant that mimics the final stage of physiologic coagulation for surgical hemostasis and tissue adhesion. Pre-filled syringe delivery mode dominates hospital purchasing due to reduced preparation time and lower contamination risk in operating rooms. Orthopedic surgery applications generate expanding volume as arthroplasty procedures rise and surgeons seek alternatives to mechanical fixation in partial-thickness repairs.
FDA Center for Biologics Evaluation and Research enforces stringent viral safety protocols for plasma-derived sealants, while Health Canada Biologics and Genetic Therapies Directorate mandates comparable donor screening and manufacturing controls that elevate compliance costs for cross-border suppliers. CSL Behring navigates these dual frameworks through dedicated North American plasma collection and fractionation infrastructure. Stakeholders must monitor evolving biosimilar guidance from both regulators as recombinant fibrinogen alternatives advance through clinical pipelines.
Market Dynamics
Plasma fractionation capacity constraints are redistributing competitive advantage across the North America Human Fibrin Glue Market, forcing manufacturers to secure captive fibrinogen supplies through backward integration or exclusive collection contracts rather than spot-market sourcing.
Growth Catalysts
- Pre-filled syringe delivery systems:Operating room workflow standardization in U.S. academic medical centers accelerates adoption of ready-to-use sealant formats that eliminate reconstitution steps and reduce contamination risk during cardiovascular procedures.
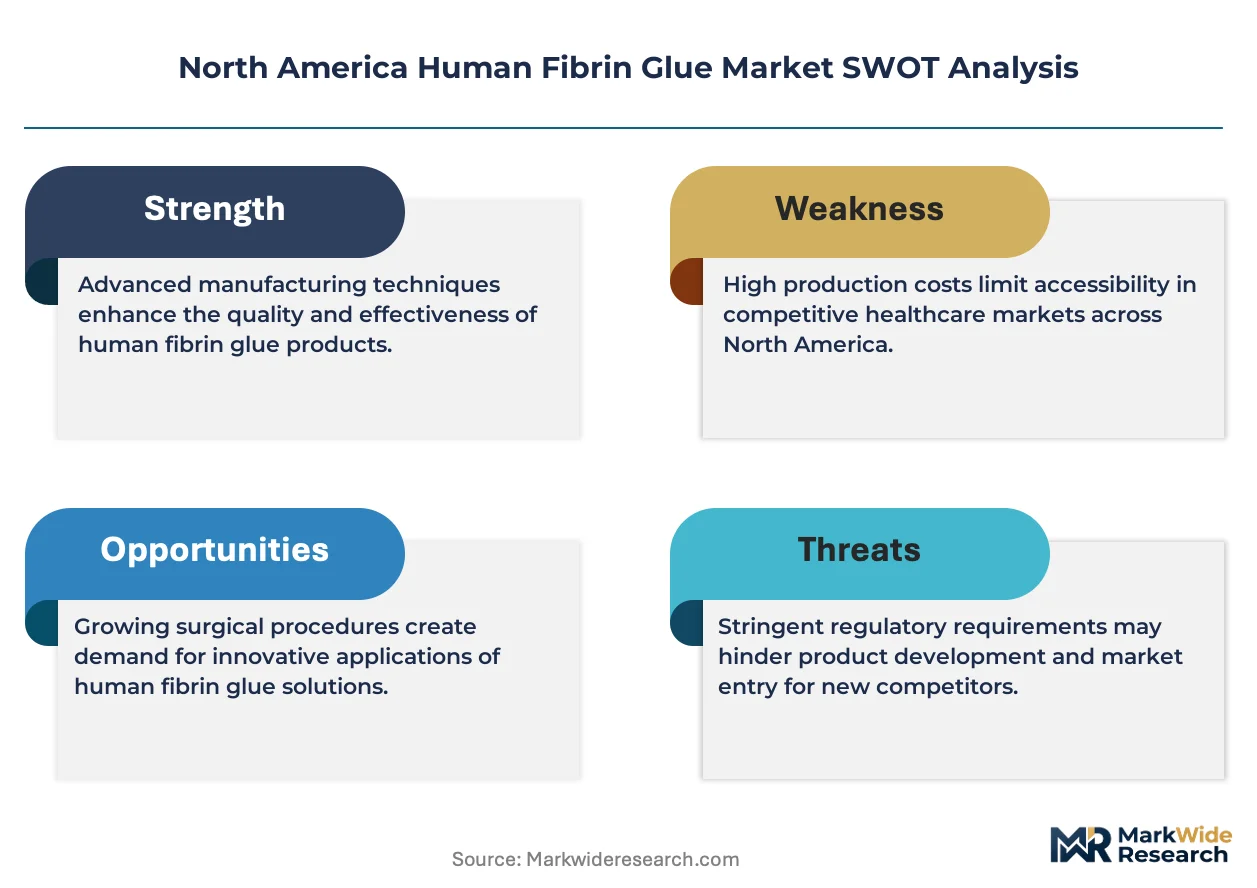
- FDA viral safety protocols:Stringent biologics licensing requirements for plasma-derived hemostats elevate barriers to entry, consolidating volume among established fractionators with validated pathogen inactivation infrastructure.
- Arthroplasty volume expansion:Rising joint replacement procedures in the northeastern United States corridor generate demand for biologic fixation alternatives to mechanical sutures in partial-thickness soft tissue repairs.
Market Restraints
- Plasma supply concentration:Dependence on U.S.-based donor collection networks exposes manufacturers to seasonal donation variability and regional collection center capacity limits.
- Recombinant fibrinogen substitutes:Biosimilar alternatives advancing through clinical pipelines threaten to displace plasma-derived sealants in price-sensitive hospital purchasing categories.
- Health Canada cross-border compliance:Dual-track regulatory submissions for Biologics and Genetic Therapies Directorate approval inflate timeline and documentation costs for U.S.-origin products entering Canadian provinces.
Strategic Opportunities
- Canadian cardiovascular expansion:Academic medical centers in Ontario and Quebec are upgrading surgical suites with integrated hemostasis platforms, creating first-mover advantage for suppliers establishing direct hospital contracts.
- Suture-integrated delivery convergence:Mechanical closure devices combined with biologic sealant reservoirs address unmet need in trauma and transplant centers seeking single-application solutions.
- Cold-chain logistics innovation:Specialized temperature-controlled distribution networks enable just-in-time inventory models that reduce hospital carrying costs for temperature-sensitive fibrinogen concentrates.
Industry Challenges
- Fractionation technologist scarcity:Specialized expertise in cryoprecipitation and viral inactivation processes concentrates among legacy plasma processors, constraining new entrant manufacturing scale-up.
- Legacy ERP integration:Hospital procurement systems require custom interface development to accommodate lot-level traceability mandates for plasma-derived biologics under FDA track-and-trace regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Human Fibrin Glue Market |
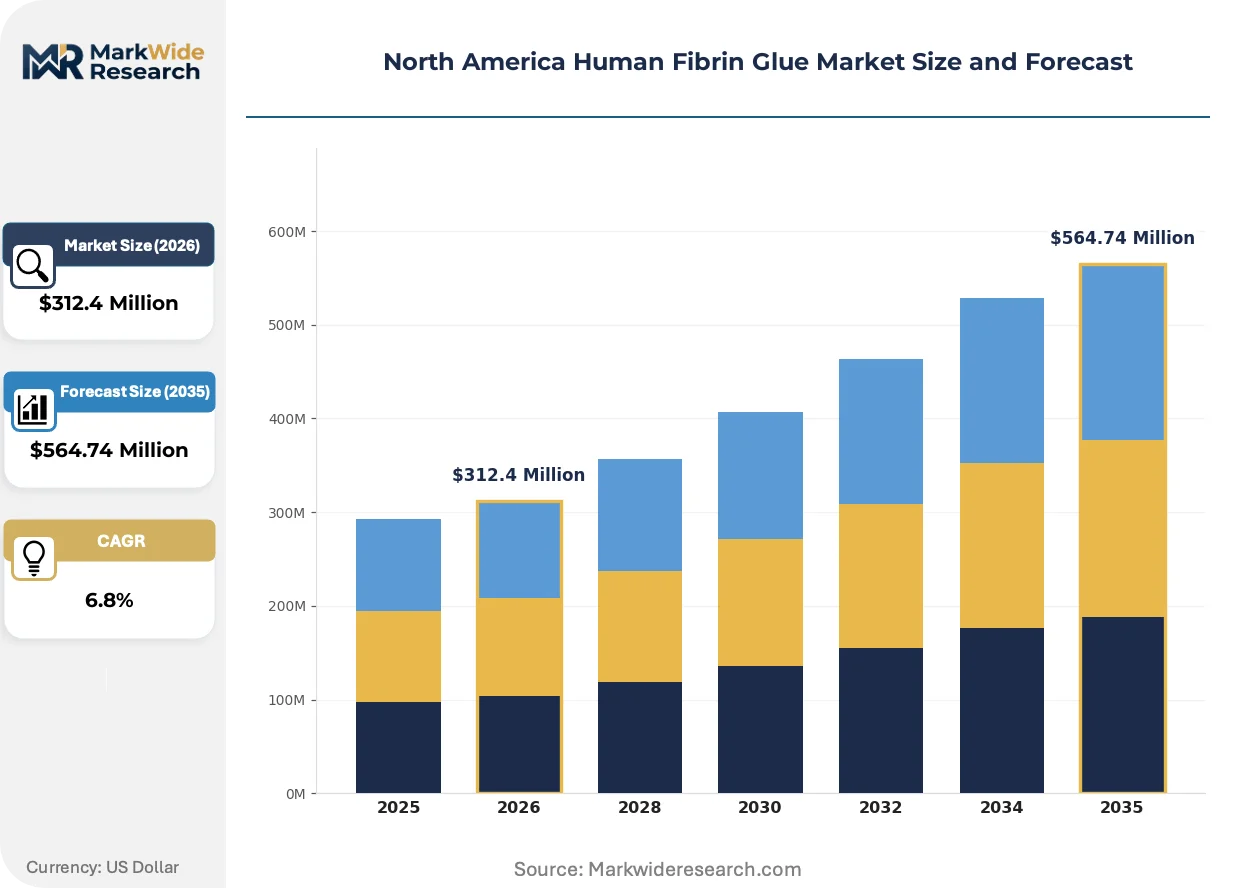
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Fibrin Sealant, Biological Adhesive, Surgical Glue, Tissue Adhesive End User: Hospitals, Surgical Centers, Clinics, Laboratories Application: Orthopedic Surgery, Cardiovascular Surgery, Dermatology, Veterinary Medicine Delivery Mode: Pre-filled Syringe, Ampoule, Spray Application, Gel Application |
| Companies Covered | Integra LifeSciences Corporation, Pfizer Inc., Baxter International Inc., Vivostat A/S, Grifols S.A., Johnson & Johnson (Ethicon), Becton, Dickinson and Company, Stryker Corporation, CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Human Fibrin Glue Market Evolving Landscape
Delivery platform engineering is compressing the gap between mechanical and biologic closure modalities, while regulatory harmonization pressures and procurement centralization reshape how surgical sealants reach operating rooms.
Dual-chamber syringe systems is hybridizing fibrinogen and thrombin storage within single-use applicators, eliminating manual mixing steps. Ambulatory surgery centers in Texas and Florida are piloting these platforms for outpatient arthroscopy. The technology is compressing training curves for circulating nurses and reducing product waste from failed reconstitution.
FDA Center for Biologics Evaluation and Research tightened donor deferral criteria for variant Creutzfeldt-Jakob disease risk in 2023, shrinking eligible plasma pools for fractionation. Manufacturers with vertically integrated collection networks absorb compliance costs more efficiently than contract-dependent competitors. The policy shift most acutely affects mid-scale sealant producers lacking captive donor bases.
Hospital value analysis committees now mandate head-to-head hemostasis efficacy data prior to formulary inclusion, displacing traditional surgeon preference-driven purchasing. Integrated delivery networks in California and Illinois consolidate buying power across multiple facilities. This behavioral shift concentrates contract awards among suppliers with robust clinical trial portfolios and health economic evidence packages.
North America Human Fibrin Glue Market Segmentation
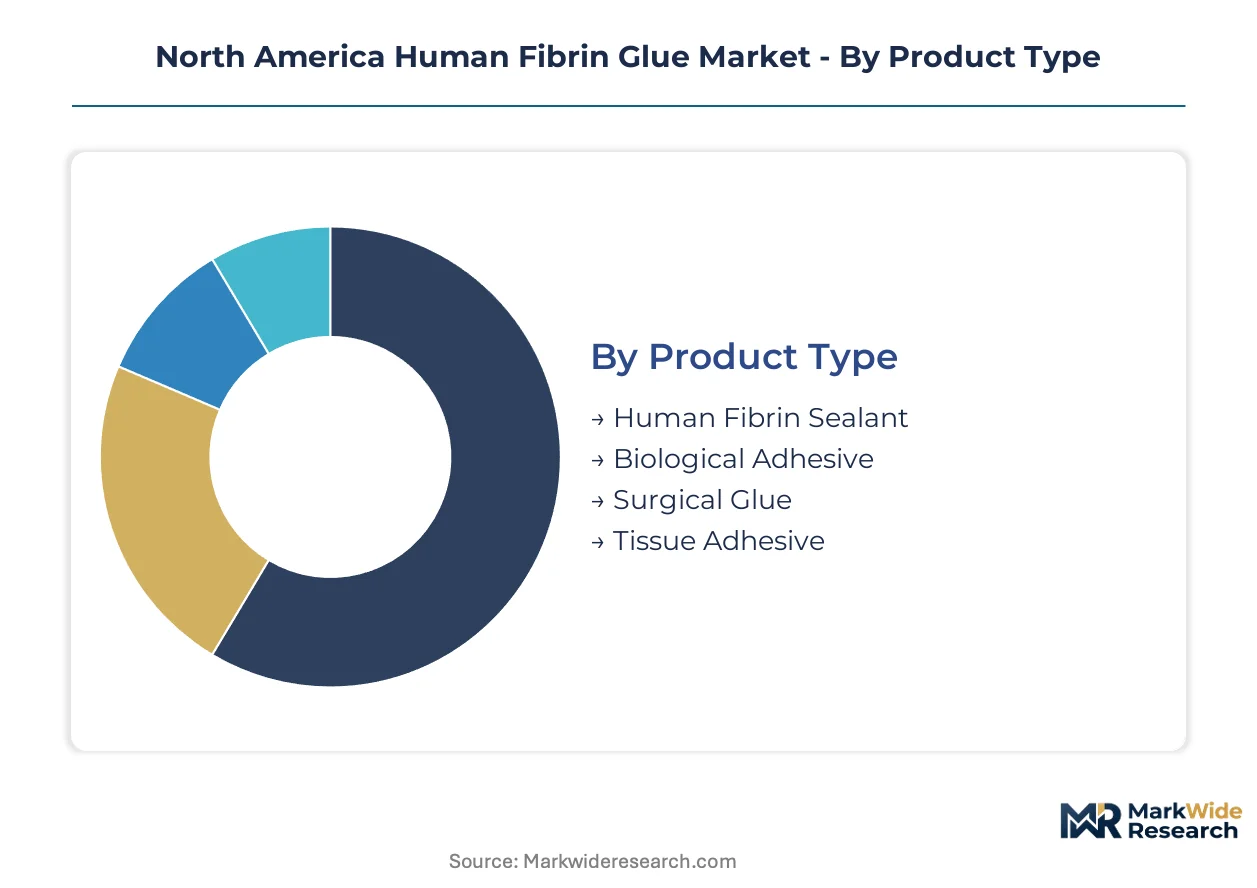
Surgical sealant procurement in North America fragments across technical specifications, clinical settings, and administration protocols. Understanding these divides reveals where manufacturers must align product development with institutional purchasing criteria and regulatory compliance pathways.
Product Type:
After-sales service intensity varies sharply across product categories, with plasma-derived sealants demanding cold-chain technical support and lot-traceability systems that recombinant alternatives currently bypass.
- Human Fibrin Sealant:Two-component biologic combining fibrinogen and thrombin precipitated from pooled human plasma via cryoprecipitation, stabilized with aprotinin or tranexamic acid to prevent premature polymerization. Demand concentrates in transplant centers across the northeastern United States corridor, where surgeons require validated viral inactivation documentation for every lot.
- Biological Adhesive:Broader category encompassing collagen-based, albumin-crosslinked, and fibrinogen-thrombin combinations with modified clotting kinetics. Academic medical centers in Ontario and Quebec are expanding formulary inclusion as cardiovascular surgery suites upgrade hemostasis platforms.
- Surgical Glue:Cyanoacrylate and other synthetic polymer alternatives offering rapid polymerization without biologic sourcing constraints.
- Tissue Adhesive:Specialized formulations for superficial wound closure and dermatologic applications with lower tensile strength requirements.
Human Fibrin Sealant holds the largest share; momentum sits with Biological Adhesive as Canadian cardiovascular expansion accelerates.
End User:
Procurement sophistication and volume scale diverge dramatically across institutional types, with integrated delivery networks consolidating purchasing power while ambulatory sites prioritize workflow simplicity.
- Hospitals:Academic medical centers and tertiary care facilities with transplant, trauma, and cardiovascular surgery programs. Value analysis committees in California and Illinois now mandate head-to-head hemostasis efficacy data prior to formulary inclusion.
- Surgical Centers:Ambulatory surgery centers in Texas and Florida are piloting dual-chamber syringe systems for outpatient arthroscopy, compressing training curves for circulating nurses.
- Clinics:Dermatology and minor procedure sites with lower throughput and reduced cold-chain infrastructure investment.
- Laboratories:Research and reference facilities utilizing sealants for tissue engineering and experimental surgical models.
Hospitals dominate volume; surgical centers are climbing the fastest as outpatient arthroplasty migration continues.
Application:
Clinical indication shapes regulatory submission pathways and reimbursement coding, with cardiovascular and orthopedic procedures commanding distinct evidence requirements for FDA biologics licensing.
- Orthopedic Surgery:Arthroplasty and soft tissue repair applications where biologic fixation alternatives reduce mechanical suture burden. Rising joint replacement procedures in the northeastern United States corridor generate expanding volume as surgeons seek partial-thickness repair solutions.
- Cardiovascular Surgery:Aortic reconstruction, valve repair, and coronary bypass anastomosis requiring hemostatic control in anticoagulated patients. Canadian academic medical centers are upgrading surgical suites with integrated hemostasis platforms.
- Dermatology:Mohs surgery and cosmetic procedure applications with emphasis on cosmetic outcome and minimal tissue trauma.
- Veterinary Medicine:Equine and companion animal surgical applications with reduced regulatory burden but limited reimbursement infrastructure.
Cardiovascular Surgery commands premium pricing; Orthopedic Surgery shows steepest expansion trajectory as arthroplasty volume rises.
Delivery Mode:
Packaging configuration determines preparation time, contamination risk, and waste generation—factors that hospital value analysis committees now weight heavily in contract awards.
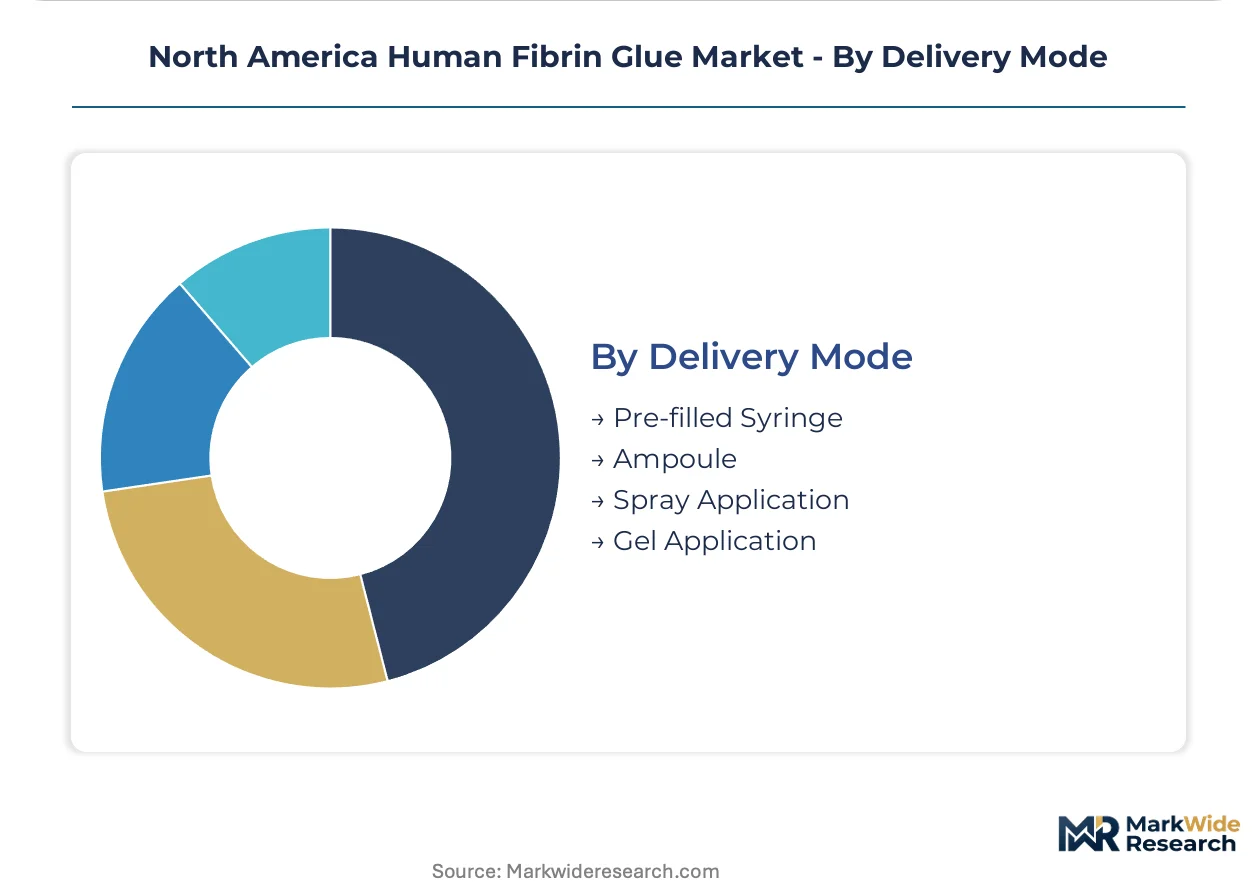
- Pre-filled Syringe:Ready-to-use format eliminating reconstitution steps, dominating hospital purchasing due to reduced preparation time and lower contamination risk in operating rooms. Operating room workflow standardization in U.S. academic medical centers accelerates adoption.
- Spray Application:Aerosolized delivery for broad surface coverage in hepatic resection and trauma applications.
- Ampoule:Traditional vial format requiring manual mixing, now relegated to cost-sensitive purchasing categories and research settings.
- Gel Application:Viscous formulation for precise placement in neurosurgical and ophthalmic procedures.
Pre-filled Syringe captures the largest share; spray application is gaining share fastest as trauma centers seek rapid surface coverage solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation infrastructure concentrates in the United States and Canada, with Mexican demand met largely through cross-border distribution channels. The northeastern corridor from Boston to Philadelphia anchors surgical sealant consumption density.
United States
FDA viral safety protocols and biologics licensing requirements tighten purity standards for plasma-derived hemostats. Baxter International leverages vertically integrated collection networks to sustain fill-finish output. California and Illinois integrated delivery networks consolidate purchasing power across multiple facilities.
Canada
Health Canada Biologics and Genetic Therapies Directorate mandates donor screening and manufacturing controls that elevate compliance costs for cross-border suppliers. CSL Behring navigates dual regulatory frameworks through dedicated North American infrastructure. Ontario and Quebec academic medical centers upgrade cardiovascular surgery suites with integrated hemostasis platforms.
Mexico
Hospital purchasing committees in Mexico City and Monterrey prioritize cost-effective sealant formats for expanding surgical programs. The national pharmaceutical regulator enforces import documentation requirements for temperature-sensitive biologics. Northern border states rely on U.S.-based cold-chain logistics networks for just-in-time fibrinogen concentrate delivery.
North America Human Fibrin Glue Market Competitive Landscape
Vertically integrated plasma fractionators and diversified surgical device manufacturers split the market between captive supply security and bundled delivery innovation. Baxter International and Grifols S.A. anchor the fractionator tier with backward integration into plasma collection networks. Johnson & Johnson (Ethicon) and Stryker Corporation occupy the device-bundling tier, competing on suture-integrated platforms. Dominant competitive moves include exclusive collection contracts and dual-chamber syringe delivery system development.
Among established fractionators, Baxter International and Grifols S.A. exemplify supply-chain control archetypes, while CSL Behring occupies a position bridging North American and European regulatory compliance. Within the surgical device tier, Johnson & Johnson (Ethicon) represents bundled delivery platform specialists, and Stryker Corporation anchors the orthopedic-focused segment. These players collectively illustrate how competitive positioning in this market depends on securing captive fibrinogen supplies or engineering workflow-integrated administration systems.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Pfizer Inc. |
| Baxter International Inc. |
| Vivostat A/S |
| Grifols S.A. |
| Johnson & Johnson (Ethicon) |
| Becton, Dickinson and Company |
| Stryker Corporation |
| CSL Behring |
| Others |
Value Network & Pricing Analysis
Plasma fractionation infrastructure in the United States concentrates fibrinogen supply among three legacy processors, anchoring margin pools in viral inactivation certification and cold-chain logistics rather than raw material sourcing. Hospital value analysis committees in California and Illinois now weight total cost of ownership—including lot traceability systems and waste reduction—above unit price in contract awards.
Pricing Analysis
FDA biologics licensing requirements dictate the pricing tier structure across the North America Human Fibrin Glue Market, separating premium-grade sealants with validated pathogen inactivation documentation from standard tiers lacking comprehensive viral safety dossiers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification depth, after-sales technical support intensity, and delivery mode sophistication. Cost compression in economy tiers is intensifying because recombinant fibrinogen alternatives threaten displacement in price-sensitive hospital purchasing categories. Ambulatory surgery centers in Texas and Florida exhibit highest price sensitivity, while transplant centers in the northeastern United States corridor prioritize premium tiers regardless of unit cost.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk calculus for cross-border fibrinogen concentrate movements. Manufacturing concentration rests on the United States, Canada, and European source plasma networks, with Mexican demand fed through U.S.-based cold-chain logistics. Raw material dependencies center on cryoprecipitated fibrinogen, aprotinin stabilizers, and thrombin concentrates. Single-source vulnerability characterizes viral inactivation expertise, which concentrates among legacy plasma processors with decades of validated manufacturing history. Distribution runs through specialized temperature-controlled networks enabling just-in-time inventory models for hospital customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Human Fibrin Glue Market sits at a platform-economics inflection where dual-chamber syringe delivery systems are redefining interoperability standards between mechanical closure and biologic hemostasis, consolidating purchasing decisions around workflow-integrated ecosystems rather than standalone product performance.
For Market Incumbents: Build captive plasma collection moats through exclusive donor center contracts in the upper Midwest and Texas corridor, insulating fill-finish output from seasonal donation variability. Deepen backward integration into cryoprecipitation capacity to absorb FDA viral safety compliance costs more efficiently than contract-dependent competitors. Counter recombinant fibrinogen substitution threats by bundling sealant reservoirs with suture-integrated delivery platforms that lock in hospital formulary position through mechanical-biologic convergence. For New Entrants and Emerging Players: Build out ambulatory surgery center penetration in Florida and Texas, where outpatient arthroscopy migration creates white-space demand for simplified dual-chamber syringe formats that compress nurse training curves. Target Canadian cardiovascular expansion in Ontario and Quebec academic medical centers upgrading integrated hemostasis platforms, where Health Canada compliance requirements deter U.S. incumbents from rapid market entry. Pursue direct hospital contracting models that bypass consolidated GPO purchasing channels dominating U.S. integrated delivery networks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fractionators with validated viral inactivation infrastructure and underutilized cryoprecipitation capacity, positioned for acquisition by device-bundling strategics seeking captive fibrinogen supply. Long-term viability hinges on regulatory moat sustainability against recombinant biosimilar erosion over the medium-term horizon. Monitor Health Canada Biologics and Genetic Therapies Directorate guidance evolution as the signal for cross-border competitive dynamics shift.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Chamber Syringe Development | Compresses operating room preparation time and reduces contamination risk for circulating nurses. |
| Exclusive Plasma Collection Contracts | Secures captive fibrinogen supply against seasonal donation variability in upper Midwest donor centers. |
| FDA Biologics Licensing Pathway Investment | Validates viral inactivation protocols that hospital value analysis committees mandate for formulary inclusion. |
| Canadian Cardiovascular Suite Partnerships | Captures first-mover advantage in Ontario and Quebec academic medical center upgrade cycles. |
| Suture-Integrated Delivery Platform Convergence | Addresses unmet need in trauma and transplant centers seeking single-application mechanical-biologic solutions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plasma fractionation executives, hospital purchasing committee chairs, cardiovascular surgeons, cold-chain logistics operators, and regulatory affairs specialists; and secondary validation against FDA biologics licensing databases, Health Canada submission records, hospital procurement contracts, GPO pricing disclosures, and plasma industry trade data. Bottom-up triangulation across product-level volume estimates and top-down cross-checks against fractionator reported outputs ensured analytical coherence.
Forecast inputs considered procedure volume trajectories across cardiovascular, orthopedic, and trauma surgical categories, plasma collection center capacity expansion plans, regulatory pathway timelines for recombinant alternatives, and hospital consolidation patterns among integrated delivery networks. Segmentation dimensions modeled included product type, end user institution class, clinical application, and delivery mode configuration. CAGRs were derived from slope analysis across the projection horizon, calibrated to historical fill-finish output trends and surgical procedure growth rates.
Stress conditions across plasma donation variability, FDA donor deferral criteria tightening, Health Canada cross-border compliance cost inflation, and recombinant fibrinogen biosimilar approval timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding surgical procedure migration to outpatient settings and cold-chain infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
North America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Italy Adhesives Market