
 Global Lithium Ion Battery Binders Market | 2026-2036
Global Lithium Ion Battery Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithium Ion Battery Binders Market Intelligence
Project finance for new battery gigafactories is reconfiguring which suppliers can compete for high-volume contracts. Zeon Corporation leverages its leadership in aqueous binders like Styrene-Butadiene Rubber for graphite and silicon-based anodes. Solvay sustains its market position through its extensive portfolio of Polyvinylidene Fluoride (PVDF) cathode binders. Arkema differentiates with its specialty PVDF grades, focusing on adhesion and high-voltage stability for advanced cell chemistries.
Lithium-ion battery binders are polymers that ensure electrode integrity by binding active materials to each other and the current collector. These materials are processed in a slurry, using solvents like N-Methyl-2-pyrrolidone (NMP) or water for aqueous systems, which impacts manufacturing cost and environmental footprint. Polyvinylidene Fluoride (PVDF) is the leading product type for cathodes in Electric Vehicles, valued for its electrochemical stability. Styrene-Butadiene Rubber (SBR) dominates the anode binder segment, offering flexibility for high-capacity graphite and silicon materials.
The EU's REACH regulation and Battery Regulation impose strict chemical safety and lifecycle management requirements on binder materials. In parallel, China's GB standards and the US EPA's oversight of solvents influence formulation choices and factory emissions controls. Consequently, binder selection involves a critical tradeoff between electrochemical performance, manufacturing scalability, and evolving environmental compliance mandates.
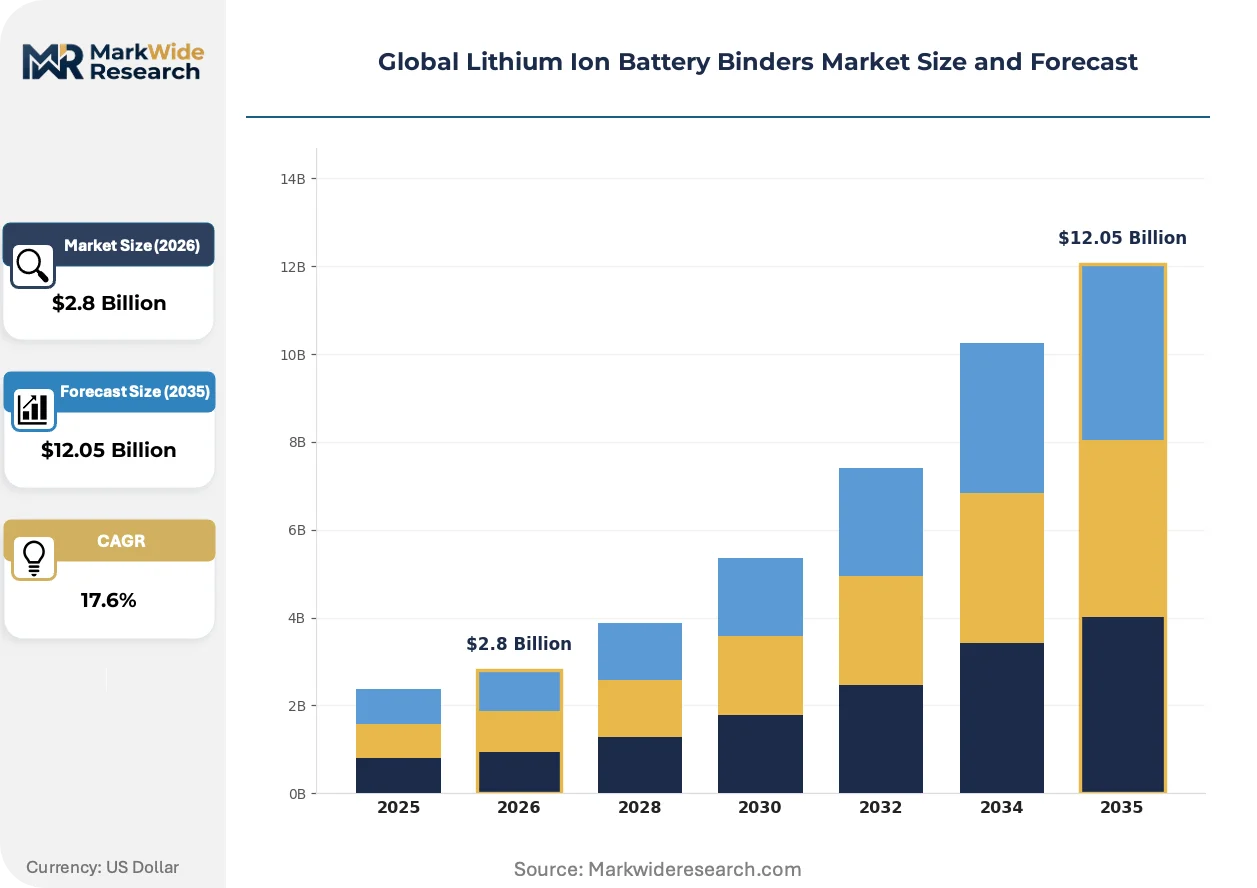
Market Dynamics
The technical imperative to increase the energy density of lithium-ion cells, primarily through the adoption of high-capacity silicon anodes, is the central force reconfiguring the binder market. This shift creates new performance demands that legacy materials cannot meet, driving intense innovation in polymer chemistry.
Growth Catalysts
- EV Policy Mandates:Government regulations like the EU's Battery Regulation and its associated carbon footprint declarations incentivize the adoption of advanced, efficient battery chemistries, which in turn require higher-performance binder systems to maintain stability and longevity.
- Grid-Scale Energy Storage:The rapid expansion of large-scale Energy Storage Systems (ESS) to support renewable energy integration creates a massive new volume market for batteries, demanding cost-effective and durable binders optimized for long-duration cycling rather than automotive power density.
- Silicon Anode Commercialization:The transition from graphite to silicon-blended anodes necessitates binders with superior elasticity and adhesion to manage the significant volume expansion of silicon during charging, creating a premium market for advanced SBR and new polymer families.
Market Restraints
- Raw Material Volatility:The market is subject to price fluctuations in key feedstocks for PVDF and SBR polymers, as well as the processing solvent N-Methyl-2-pyrrolidone (NMP), which can compress margins for binder manufacturers and their customers.
- PVDF Supply Concentration:A high concentration of Polyvinylidene Fluoride (PVDF) production capacity within a few key suppliers and geographies creates a persistent risk of supply chain bottlenecks, price instability, and geopolitical vulnerability for battery manufacturers. *Aqueous Processing Hurdles: While environmentally preferred, water-based binders like SBR present manufacturing challenges, including slurry viscosity control, longer drying times, and potential hydrogen gas evolution, which can slow down production lines compared to established NMP-based systems.
Strategic Opportunities
- Emerging Production Hubs:National industrial policies, such as India's Production Linked Incentive (PLI) scheme for battery manufacturing, create greenfield opportunities for binder suppliers to establish local production and capture demand in nascent gigafactory ecosystems.
- Solid-State Battery Binders:The long-term development of solid-state batteries will require an entirely new class of binder materials, or ion-conducting polymer electrolytes, that can ensure mechanical integrity and facilitate ion transport at the solid-solid interface.
- Multifunctional Material Systems:There is a significant opportunity in developing integrated binder systems that combine adhesion properties with other functions, such as ionic conductivity or thermal management, reducing component count and improving overall cell performance.
Industry Challenges
- Capital-Intensive Expansion:Building new world-scale polymer production facilities for battery-grade PVDF or SBR requires substantial capital investment and long lead times, making it difficult for new entrants to compete on scale with established chemical giants.
- Automotive Qualification Cycles:The extensive and time-consuming validation process for any new material in automotive battery cells, often lasting several years, acts as a significant barrier to the rapid adoption of innovative binder technologies.
- Performance Metrology Gaps:A lack of industry-wide standardized testing protocols for evaluating next-generation binder performance, particularly for adhesion and flexibility in silicon anodes over thousands of cycles, complicates direct comparison and material selection for cell engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium Ion Battery Binders Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.05 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinylidene Fluoride, Styrene-Butadiene Rubber, Cellulose, Polyethylene Oxide Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Applications End User: Aerospace, Automotive Manufacturers, Electronics Companies, Power Grid Operators Technology: Synthesis Process, Formulation Technology, Coating Technology, Processing Techniques |
| Companies Covered | Arkema, Solvay, LG Chem, ENEOS Corporation, Zeon Corporation, BASF SE, DuPont, DAIKIN Industries, Ltd., Kureha Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium Ion Battery Binders Market Strategic Shifts & Innovations
Innovation in the binder market is driven by a fundamental tension between achieving higher electrochemical performance and meeting stricter environmental and manufacturing cost targets. This dynamic pushes material science toward novel polymers and water-based processing solutions.
Computational chemistry and materials informatics are being used to accelerate the discovery of novel binder polymers with tailored properties. Battery R&D labs and specialty chemical firms are adopting this approach to screen thousands of potential candidates virtually before committing to expensive lab synthesis. This methodology is digitizing the traditionally empirical, trial-and-error process of polymer formulation, compressing development timelines for next-generation materials.
The US EPA's regulatory actions on solvents like N-Methyl-2-pyrrolidone (NMP) under toxic substance frameworks are accelerating the industry's shift away from solvent-based processing. This pressure compels a move toward aqueous (water-based) binder systems for both cathodes and anodes to reduce environmental impact and worker exposure risks. Cathode manufacturers are most affected, as they must validate new aqueous PVDF formulations that maintain adhesion and electrochemical stability.
A significant shift in sourcing strategy has battery manufacturers demanding regionalized binder production to de-risk supply chains and qualify for local content incentives. This trend disrupts the established model of sourcing from large, centralized plants in Asia, compelling suppliers to plan for smaller, more agile facilities in North America and Europe. This pattern is most pronounced in the electric vehicle sector, where policies like the US Inflation Reduction Act directly link consumer tax credits to domestic material sourcing.
Global Lithium Ion Battery Binders Market Segmentation
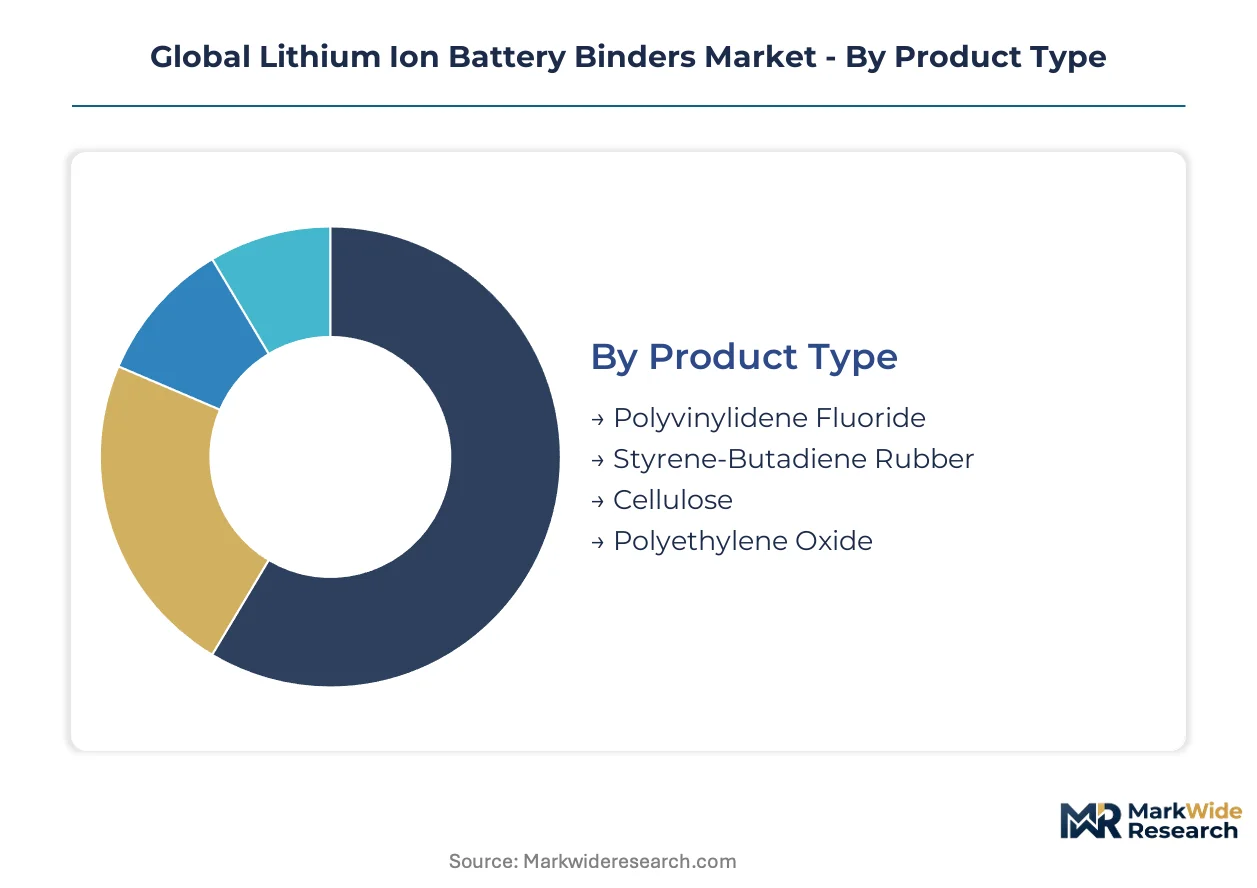
Understanding the segmentation of the global lithium ion battery binders market provides crucial insights into the diverse performance requirements and strategic priorities across various applications. Each segment demands specific material characteristics, influencing research and development efforts and market positioning for suppliers.
Product Type:
The after-sales-service intensity for lithium ion battery binders varies significantly by product type, influencing material selection and long-term performance guarantees.
- Polyvinylidene Fluoride:Polyvinylidene Fluoride (PVDF) serves as a critical cathode binder, valued for its high electrochemical stability and strong adhesion properties within high-voltage battery cells. Demand concentrates in Electric Vehicle battery manufacturing hubs across China and South Korea, driven by stringent performance requirements for power density and cycle life.
- Styrene-Butadiene Rubber:Styrene-Butadiene Rubber (SBR) is the predominant anode binder, particularly for graphite and silicon-based electrodes, offering essential elasticity to accommodate volume changes. Its adoption is accelerating in Germany and the US as gigafactories scale production of next-generation cells requiring enhanced mechanical flexibility.
- Cellulose:Cellulose-based binders offer an environmentally friendly alternative, often used in niche applications or as an additive to improve mechanical properties in aqueous systems.
- Polyethylene Oxide:Polyethylene Oxide (PEO) is explored for its potential in solid-state electrolytes and as a binder for certain electrode materials, leveraging its ionic conductivity.
Polyvinylidene Fluoride holds the largest share; momentum sits with Styrene-Butadiene Rubber.
Application:
Application categories for lithium ion battery binders differentiate based on specific performance requirements and operational cycles.
- Electric Vehicles:Electric Vehicles demand binders with exceptional electrochemical stability and high adhesion to withstand rapid charge-discharge cycles and extreme temperatures. Production in Poland and the US drives significant volume, where automotive manufacturers prioritize long-term durability and safety.
- Energy Storage Systems:Energy Storage Systems require binders optimized for extended cycle life and cost-effectiveness in large-scale installations supporting renewable energy integration. China's national grid modernization initiatives and Australia's utility-scale projects are expanding demand for these robust binder solutions.
- Consumer Electronics:Consumer Electronics utilize binders that enable compact designs and high energy density for devices like smartphones, laptops, and wearables.
- Industrial Applications:Industrial Applications, including power tools and robotics, require binders that offer durability and consistent performance under demanding operational conditions.
Electric Vehicles currently dominate the market; Energy Storage Systems are expanding most quickly.
End User:
End-user segments for lithium ion battery binders are characterized by distinct procurement patterns and regulatory compliance needs.
- Automotive Manufacturers:Automotive Manufacturers require binders that meet rigorous safety standards and extensive qualification processes, often spanning several years. Their procurement strategies prioritize suppliers capable of delivering high-volume, consistent quality materials for global production lines in Germany and Japan.
- Power Grid Operators:Power Grid Operators seek durable and reliable binders for large-scale energy storage, emphasizing longevity and minimal maintenance over decades of operation. National energy policies in India and the US incentivize the deployment of grid-scale batteries, increasing demand for robust binder solutions.
- Aerospace:The Aerospace sector demands binders with extreme reliability and lightweight properties for critical applications in aircraft and space vehicles.
- Electronics Companies:Electronics Companies procure binders for mass-produced consumer devices, focusing on cost-effectiveness, consistent quality, and compatibility with high-volume manufacturing processes.
Automotive Manufacturers exert the most significant market influence; Power Grid Operators are rapidly increasing their purchasing volumes.
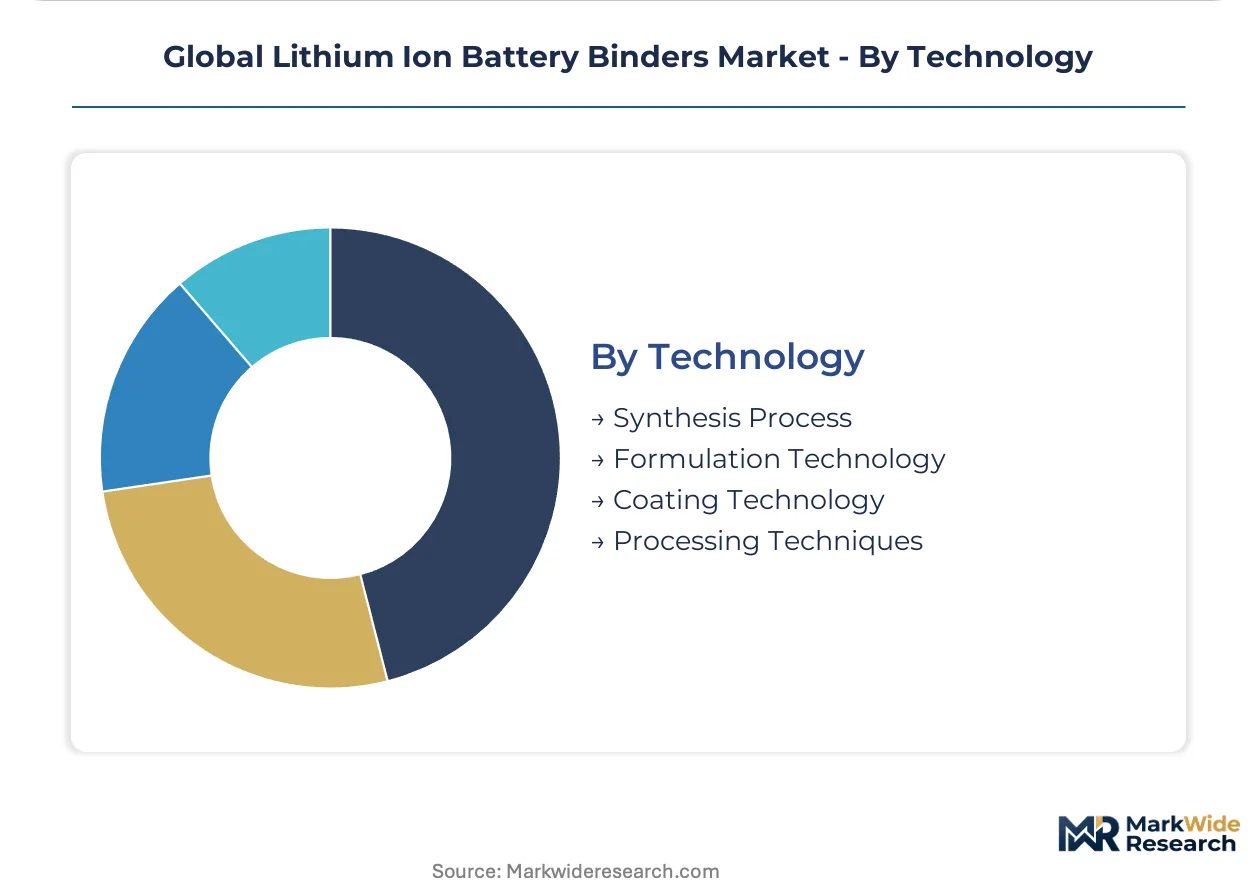
Technology:
Technology categories in lithium ion battery binders reflect varying levels of innovation and market maturity.
- Synthesis Process:Synthesis Process innovations focus on developing novel polymer chemistries to achieve superior adhesion, flexibility, and electrochemical stability for next-generation anodes. Research in South Korea and Germany aims to reduce material costs and improve environmental profiles of binder production.
- Formulation Technology:Formulation Technology involves optimizing binder blends and additive packages to enhance slurry processability, electrode integrity, and long-term cell performance. Academic institutions and specialty chemical firms in Japan and the US are advancing water-based formulations to replace NMP.
- Coating Technology:Coating Technology advancements focus on improving the uniform application of binder slurries onto current collectors, critical for electrode quality and battery performance.
- Processing Techniques:Processing Techniques encompass the methods used to integrate binders into electrode manufacturing, including drying, calendering, and solvent recovery.
Synthesis Process advancements drive fundamental material improvements; Formulation Technology refinements offer immediate performance gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power asymmetry exists between established chemical production centers and nascent battery manufacturing hubs. Supply chain concentration in Asia for key binder components grants producers in those regions considerable leverage, while new gigafactories in Europe and North America seek localized, de-risked sourcing.
China
China's demand for lithium-ion battery binders is primarily driven by its massive electric vehicle production and grid-scale energy storage projects. The nation's GB standards for battery materials influence formulation choices and promote domestic supply. Manufacturing clusters in the Yangtze River Delta and Sichuan-Chongqing regions aggressively scale up binder production to meet internal demand.
United States
The United States experiences significant demand for advanced battery binders due to expanding gigafactory capacity for electric vehicles and energy storage. The US Inflation Reduction Act (IRA) incentivizes domestic material sourcing and manufacturing. New production facilities in states like Georgia and Michigan are attracting substantial investment for localized binder supply chains.
Germany
Germany's automotive industry and strong research ecosystem drive demand for high-performance binders, particularly for silicon anode development. The EU's Battery Regulation imposes strict lifecycle management and carbon footprint requirements on binder materials. Major battery cell production sites in Brandenburg and Lower Saxony are integrating advanced binder solutions for next-generation cells.
South Korea
South Korea remains a critical hub for lithium-ion battery innovation and manufacturing, necessitating specialized binders for high-energy-density cells. The Ministry of Trade, Industry and Energy (MOTIE) supports R&D initiatives for advanced battery materials. Key industrial clusters in Chungcheong and Gyeonggi provinces focus on developing and producing cutting-edge binder technologies.
India
India's growing electric vehicle market and ambitious renewable energy targets create a substantial emerging demand for battery binders. The Production Linked Incentive (PLI) scheme for battery manufacturing is accelerating the establishment of local cell production. States like Gujarat and Maharashtra are becoming focal points for new battery component facilities, including binder plants.
Global Lithium Ion Battery Binders Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials. The market structure for lithium-ion battery binders is tiered, with global chemical giants providing base polymers and specialty firms offering highly customized solutions. Strategic archetypes include diversified chemical conglomerates, niche polymer innovators, and regionally focused suppliers. Capacity expansion and technology licensing are dominant competitive moves among these players.
Specialists in advanced polymer chemistry, such as Arkema, exemplify innovation in specialty PVDF grades for high-voltage stability. Solvay sustains its market position by offering an extensive portfolio of Polyvinylidene Fluoride (PVDF) cathode binders, catering to diverse electrochemical needs. Zeon Corporation occupies a strong position through its leadership in aqueous binders, particularly Styrene-Butadiene Rubber (SBR) for anode applications, serving high-capacity graphite and silicon-based electrodes.
| Leading Market Players |
|---|
| Arkema |
| Solvay |
| LG Chem |
| ENEOS Corporation |
| Zeon Corporation |
| BASF SE |
| DuPont |
| DAIKIN Industries, Ltd. |
| Kureha Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized production capacity in specific polymer lines influences supplier behavior, driving competitive pricing postures for established binder manufacturers. This dynamic is particularly evident as new regional gigafactories seek to de-risk supply chains and secure long-term material contracts.
Pricing Analysis
Configured-to-order pricing for specialty binder grades reflects the performance requirements of advanced cell chemistries, contrasting with more standardized pricing for commodity PVDF. Price differentiation stems from factors like electrochemical stability, specific adhesion properties for silicon anodes, and the level of regulatory compliance certification for new markets. Pricing softness for standard PVDF materials intensifies due to oversupply from Asian producers. Automotive manufacturers, prioritizing long-term cell performance, exhibit lower price sensitivity compared to consumer electronics companies focusing on cost-per-unit.
Supply Chain Analysis
Upstream feedstock availability for butadiene and styrene, critical for SBR production, significantly impacts binder manufacturing costs. The supply chain for lithium-ion battery binders is geographically concentrated, with key production centers for PVDF in China and South Korea. This concentration creates a structural risk of geopolitical vulnerability and potential supply disruptions for battery manufacturers in Europe and North America. Raw material volatility for N-Methyl-2-pyrrolidone (NMP) further influences processing costs. Distribution runs through established chemical distributors and direct supply agreements with large battery cell producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a platform-economics inflection point, driven by the need for integrated material solutions that enhance overall battery ecosystem performance and longevity.
For Market Incumbents:
Insulate core market share by investing heavily in next-generation aqueous binder formulations for both cathodes and anodes. Diversify geographic production footprints, especially into North America and Europe, to mitigate geopolitical risks and qualify for local content incentives like the US Inflation Reduction Act. Focus R&D on multifunctional binder systems that offer integrated thermal management or ionic conductivity to counter emerging polymer innovators.
For New Entrants and Emerging Players:
Pursue niche opportunities in high-growth segments like solid-state battery binders, where legacy materials face significant performance gaps. The most penetrable segment lies within advanced silicon anode applications, requiring superior elasticity and adhesion. A potent go-to-market angle involves strategic partnerships with specialized battery R&D labs and pilot-scale gigafactories to co-develop and rapidly qualify novel binder chemistries.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology-driven growth play because binder innovation directly unlocks higher energy density and cycle life in advanced battery cells. Target acquisition archetypes include specialty chemical firms with proprietary polymer synthesis capabilities or strong intellectual property in aqueous processing. The signal to watch is the commercialization rate of silicon anode-based batteries in mass-market electric vehicles.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Capacity Expansion | Establishes localized supply chains, reducing geopolitical risk for battery manufacturers. |
| Aqueous Binder R&D | Addresses environmental compliance mandates and improves manufacturing cost efficiency for cell producers. |
| Multifunctional Binder Development | Enhances overall battery cell performance by integrating adhesion with thermal or ionic properties. |
| Strategic Partnerships with Gigafactories | Secures long-term supply contracts and accelerates qualification cycles for new materials. |
| Silicon Anode Binder Specialization | Captures premium demand from high-capacity battery cell designs for electric vehicles. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings. This involved discussions with R&D directors at major battery manufacturers, procurement leads at gigafactories, polymer chemists specializing in binder materials, and regulatory affairs specialists. Secondary data sources included company 10-K filings, chemical industry association reports, government energy reports from the EIA and IEA, and battery technology journals. The analysis consistently applied both bottom-up and top-down triangulation methods for data validation.
Calibration of the quantitative model incorporated historical market data across the analysis window, projecting future trends over the forecast period. The segmentation dimensions modeled included product type, application, end-user, technology, and regional production hubs. Compound Annual Growth Rates were derived through a rigorous multi-variable regression analysis, integrating factors such as global EV production volumes and grid-scale ESS deployment targets. Silicon anode adoption rates served as a key industry-specific forecast input.
Sensitivities concentrate around raw material price volatility, geopolitical events impacting trade flows, and faster-than-expected regulatory shifts regarding solvent use. Forecasts reflect assumptions regarding technological advancements in battery chemistry and sustained investment in renewable energy infrastructure. Cross-checking against external benchmarks like national energy agency projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Foam Adhesive Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
North America Electronics Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market