
 Conductive Glue Market | 2026-2036
Conductive Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Glue Market Outlook
Asset-light contract manufacturing and toll-compounding arrangements are reconfiguring competitive entry barriers for conductive glue suppliers. Henkel AG & Co. KGaA leverages its European formulation footprint to anchor automotive qualification pipelines. 3M Company sustains broad patent coverage across silver-flake dispersion chemistries. MG Chemicals Ltd. specializes in small-batch, quick-turn supply for research institutions and prototype shops.
Conductive glue comprises polymeric matrices loaded with electrically functional fillers such as silver flakes, carbon black, or copper particles, formulated to achieve volume resistivity typically below 10⁻³ ohm-cm while maintaining adhesion to substrates including polyimide, FR-4, and aluminum. The material replaces mechanical fasteners and solder joints in heat-sensitive assemblies where thermal excursion would damage components. Silver-based formulations command premium positioning due to unmatched conductivity and oxidation stability, while carbon-based variants occupy cost-driven printed electronics and disposable sensor applications. Biomedical demand is expanding fastest as wearable diagnostic devices require skin-compatible, stretchable conductive traces that survive flex cycling.
EPA guidelines in the United States govern volatile organic compound emissions from adhesive manufacturing and application processes, pushing solvent-based systems toward water-borne or UV-curable alternatives. REACH registration requirements and RoHS substance restrictions in Europe dictate filler purity thresholds and ban specific stabilizer chemistries, directly influencing raw material sourcing decisions. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluorinated surfactants common in conductive paste wetting agents face phased elimination timelines that will force reformulation investments.
Market Dynamics
Automotive electrification is forcing assembly line requalification from solder to adhesive joining, as battery thermal management systems demand flexible conductive interconnects that survive vibration cycling without fatigue failure.
Growth Catalysts
- REACH substance restrictions:RoHS-compliant adhesive alternatives capture share from tin-lead solder in European electronics assembly, redirecting procurement toward silver-filled epoxies.
- Biomedical wearables:Skin-compatible stretchable conductors enable continuous glucose monitors and cardiac patches requiring million-cycle flex durability.
- Copper particle loading:Emerging formulations reduce silver dependency by 40-60% while maintaining target resistivity through flake geometry optimization.
Market Restraints
- Silver price volatility:Precious metal feedstock swings compress formulation margins and destabilize long-term supply agreements.
- Japanese flake supply concentration:Premium silver pigment production clusters with three specialized refiners, creating single-source vulnerability.
- Cure temperature floors:Most conductive epoxies require 150°C minimum, excluding heat-sensitive polyolefin and PET substrates.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile and component assembly create first-mover qualification windows for adhesive suppliers.
- UV-curable paste:Instant polymerization enables in-line processing for roll-to-roll printed antenna production.
- PFAS elimination mandates:Fluorinated wetting agent bans force reformulation, rewarding early movers with validated alternatives.
Industry Challenges
- Automotive qualification timelines:OEM validation cycles span 18-36 months, locking working capital in pre-revenue development.
- Formulation chemist scarcity:Expertise bridging polymer rheology and electrical characterization concentrates with retiring specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Glue Market |
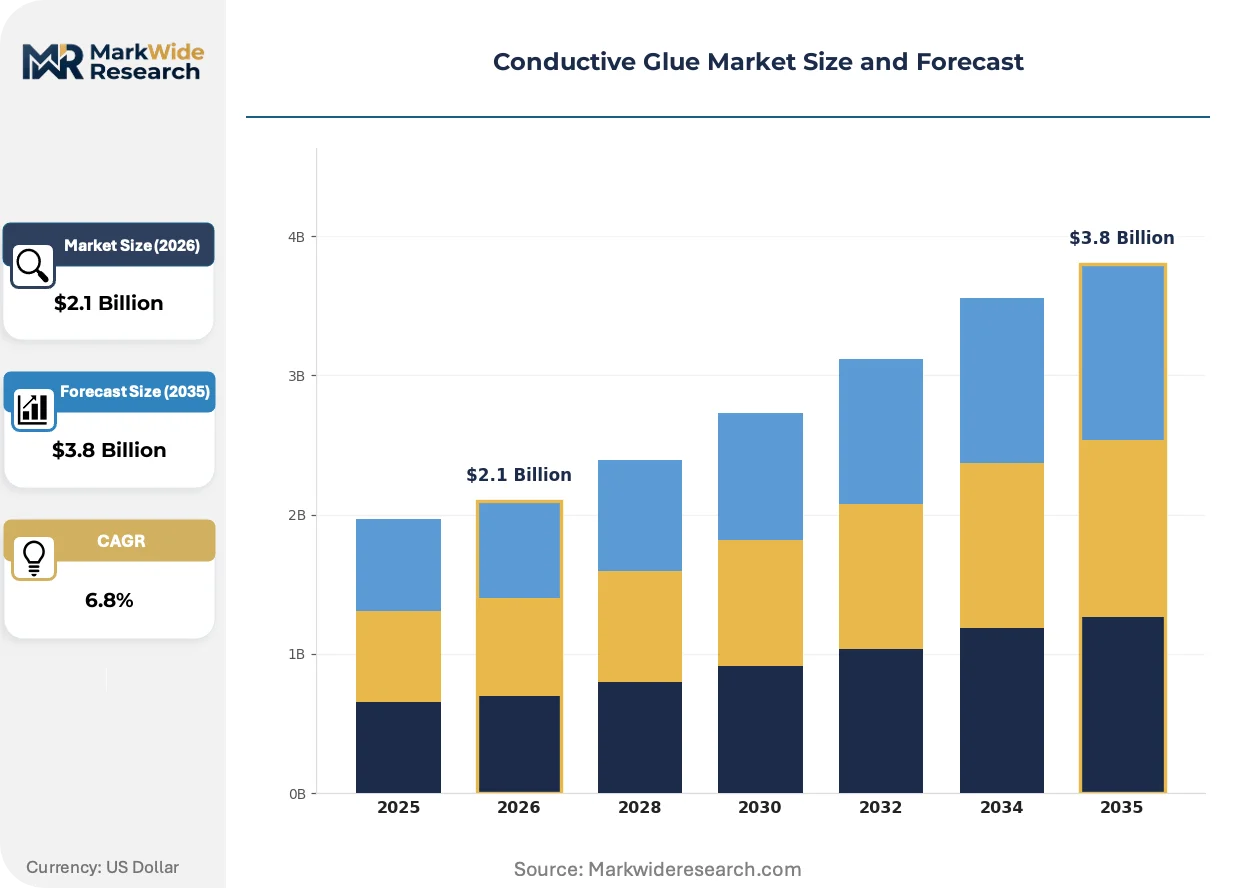
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver-based, Carbon-based, Copper-based, Adhesive Paste Application: Electronics, Automotive, Aerospace, Biomedical Packaging Type: Tubes, Jars, Syringes, Bottles End User: Manufacturers, Research Institutions, DIY Enthusiasts, Contractors |
| Companies Covered | Aremco Products, Inc., Epoxy Technology Inc., 3M Company, Master Bond Inc., Permabond LLC, Henkel AG & Co. KGaA, Dow Corning Corporation, MG Chemicals Ltd., H.B. Fuller Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Glue Market Strategic Shifts
Formulation science is converging with digital manufacturing controls, enabling real-time viscosity adjustment during dispense operations. This integration compresses development cycles and tightens batch consistency.
Nanoparticle silver inks are digitizing printed electronics manufacturing by enabling direct-write circuit formation without subtractive etching. Roll-to-roll converters in Germany and Japan deploy these systems for RFID antenna production. The technology is digitizing supply chains by collapsing tooling lead times from weeks to hours.
EPA volatile organic compound rules are accelerating water-borne conductive adhesive development, pushing solvent-based systems toward phase-out in US assembly operations. Coating applicators face capital decisions on recovery systems versus formulation switches. Medical device manufacturers in Minnesota and California lead adoption due to cleanroom air quality requirements.
Contract manufacturers now specify adhesive performance by joint reliability metrics rather than bulk material properties, shifting supplier relationships toward outcome guarantees. Tier-one automotive electronics assemblers in Bavaria and Michigan drive this transition. The practice concentrates procurement with formulators offering integrated testing and failure analysis capabilities.
Conductive Glue Market Segmentation
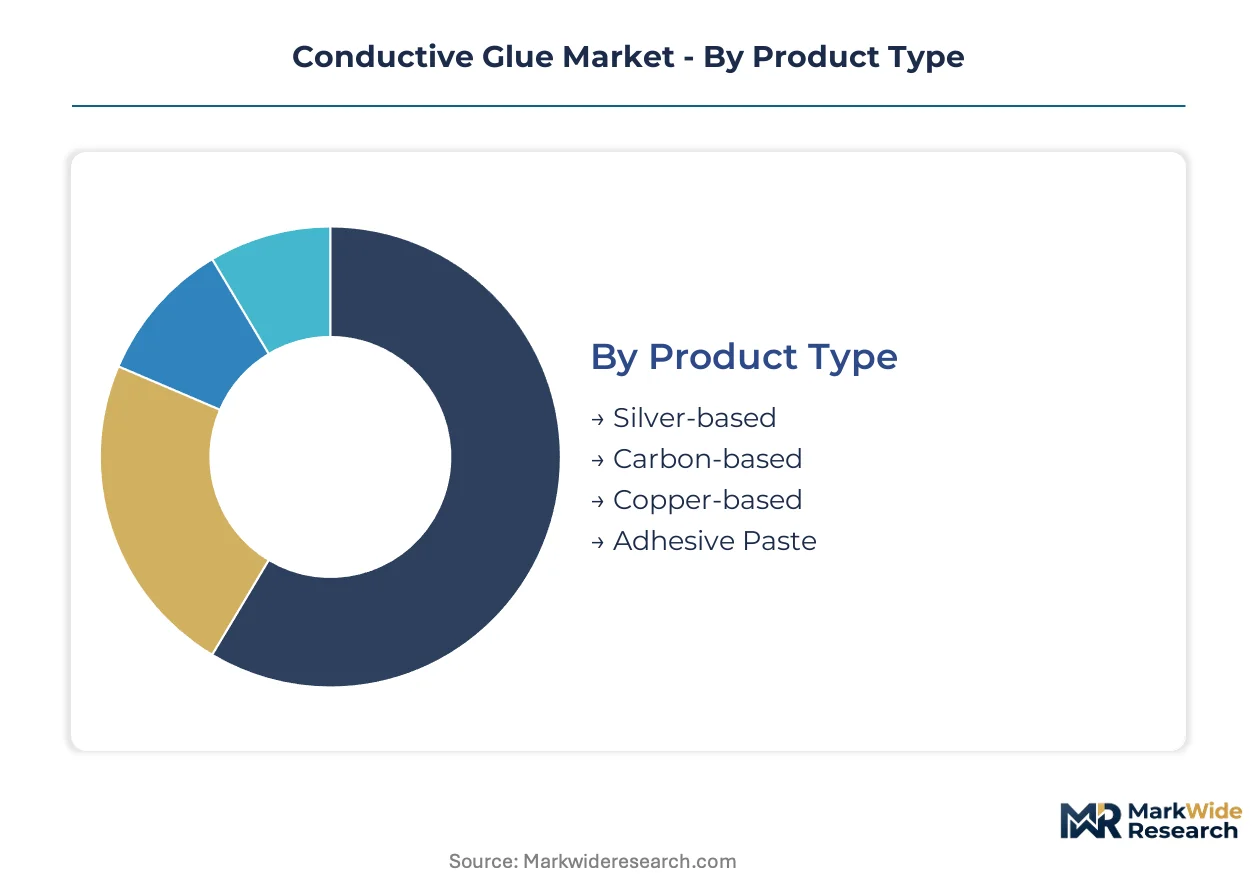
Conductive glue formulations diverge sharply across electrical performance tiers, thermal tolerance thresholds, and substrate compatibility requirements. Procurement patterns track end-use reliability standards, with automotive and biomedical buyers imposing qualification protocols that exclude commodity-grade alternatives.
Product Type:
Cost tier determines filler selection, with precious metal loadings commanding premium positioning against carbon and copper substitutes.
- Silver-based:Silver flake or nanoparticle dispersions in epoxy or silicone matrices deliver volume resistivity below 10⁻⁴ ohm-cm. Battery pack interconnects in Germany's automotive corridor specify these formulations for million-cycle vibration durability.
- Carbon-based:Carbon black or graphite loadings in acrylic binders trade conductivity for cost, achieving 10⁻² to 10⁻¹ ohm-cm. Disposable glucose sensors and printed RFID antennas in Japan and South Korea absorb volume here.
- Copper-based:Oxidation-stabilized copper flakes reduce precious metal dependency by 40-60% while targeting mid-range resistivity. Emerging qualification programs in India's PLI-backed electronics clusters are testing these formulations.
- Adhesive Paste:Pre-mixed, degassed dispersions in dual-barrel packaging eliminate operator mixing variance. Contract manufacturers in Michigan and Bavaria specify paste formats for automated dispense lines.
Silver-based formulations hold installed capacity. Copper-based variants are rotating up the share rankings.
Application:
End-use reliability requirements segment the market across thermal cycling severity, flex fatigue demands, and regulatory exposure.
- Electronics:Surface-mount device attachment and flex circuit splicing dominate consumption. REACH and RoHS restrictions across Europe redirect solder replacement demand toward compliant silver epoxies.
- Automotive:Battery module busbar bonding and sensor integration require conductive joints surviving -40°C to 150°C thermal shock. OEM validation cycles here span 18-36 months, locking suppliers into pre-revenue development.
- Aerospace:Outgassing-compliant silicones with silver filler serve satellite and avionics applications where tin whisker elimination is mandatory. NASA-STD-6016 and ESA ECSS-Q-ST-70-38C govern qualification.
- Biomedical:Skin-compatible, stretchable conductors for cardiac patches and continuous glucose monitors are climbing the fastest. FDA and EMA biocompatibility testing (ISO 10993) filters out non-medical-grade chemistries.
Electronics maintains volume leadership. Biomedical is expanding most quickly on wearable diagnostic adoption.
Packaging Type:
Customer scale and application precision dictate container engineering, from laboratory-scale precision to production-line bulk.
- Tubes:Collapsible aluminum or plastic tubes suit manual application in repair and prototype settings. Research institutions and field service technicians in North America and Europe specify this format.
- Jars:Wide-mouth containers enable spatula dispensing for stencil printing and screen coating. Printed electronics developers in Germany and Japan purchase jar formats for batch processing.
- Syringes:Luer-lock or snap-fit barrels integrate with automated dispense robots and pneumatic applicators. Tier-one automotive electronics assemblers mandate syringe packaging for process control.
- Bottles:Bulk containers with pour spouts or pump dispensers serve high-volume coating operations. Roll-to-roll converters in antenna and membrane switch manufacturing specify bottle formats.
Syringes dominate automotive and medical qualified volumes. Tubes retain share in research and aftermarket channels.
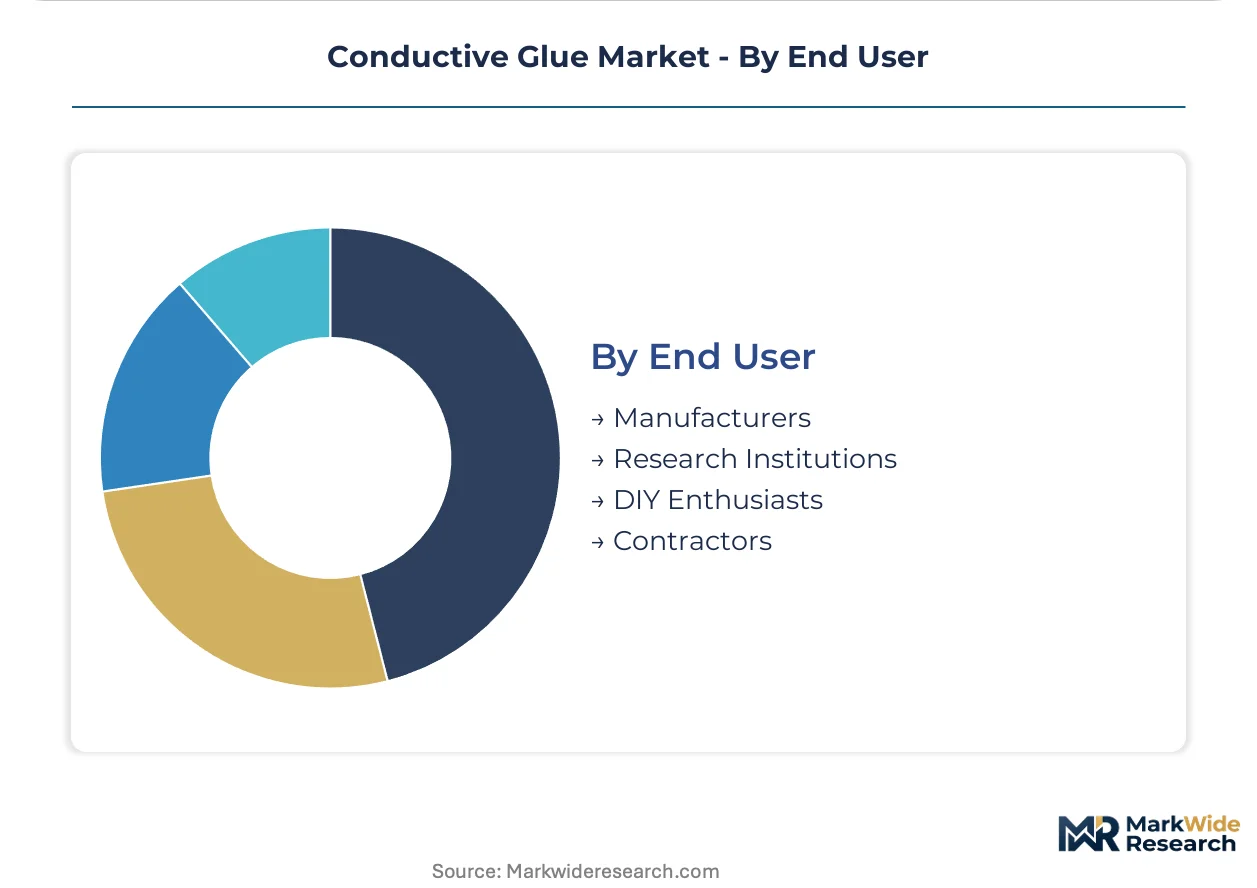
End User:
Customer type separates specification authority from purchasing volume, with contrasting technical support and documentation requirements.
- Manufacturers:OEMs and contract assemblers drive formulation standardization through approved vendor lists and process control mandates. Their procurement concentrates with suppliers offering integrated testing and failure analysis.
- Research Institutions:Universities and national laboratories prioritize small-batch availability, technical data depth, and publication-grade lot traceability. Quick-turn suppliers capture this fragmented demand.
- DIY Enthusiasts:Hobbyist electronics repair and maker community purchases favor retail-accessible formats with application guidance. Online marketplaces and specialty distributors serve this channel.
- Contractors:Field installation technicians for telecommunications, renewable energy, and building systems require portable packaging and ambient cure convenience. Regional electrical distributors stock these SKUs.
Manufacturers command specification authority. Research institutions are rotating up the share rankings on printed electronics and flexible device development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Germany and Japan as net exporters of high-performance conductive formulations, while the United States and China balance substantial internal consumption with selective technology imports. Trade flows concentrate on silver-flake precursors and specialized epoxy resins, with regulatory compliance costs reshaping cross-border procurement patterns.
United States
Automotive electrification in Michigan and California drives adhesive qualification for battery thermal management systems. EPA volatile organic compound rules push solvent-based formulations toward water-borne alternatives in Minnesota and California medical device clusters. Contract manufacturers in the Midwest specify syringe-packaged pastes for automated dispense lines serving tier-one automotive electronics.
Germany
REACH substance restrictions redirect procurement from tin-lead solder toward RoHS-compliant silver epoxies in Bavaria's automotive corridor. The KBA enforces material traceability standards for battery interconnects in electric vehicle platforms. Henkel AG & Co. KGaA anchors formulation supply chains through approved vendor programs with OEMs in Stuttgart and Munich.
Japan
Printed electronics manufacturers in Tokyo and Osaka absorb carbon-based conductive glues for disposable glucose sensors and RFID antennas. METI coordinates domestic flake refining capacity with three specialized suppliers concentrated in the Kanto region. Roll-to-roll converters deploy nanoparticle silver inks for antenna production without subtractive etching.
China
MIIT standards govern conductive adhesive performance in consumer electronics assembly across the Yangtze River Delta. Dual carbon goals accelerate copper-based formulation development to reduce silver dependency in Shenzhen and Dongguan manufacturing parks. Domestic suppliers qualify alternatives for smartphone and wearable device interconnects.
India
PLI scheme incentives for mobile and component assembly create qualification windows for adhesive suppliers in Karnataka and Tamil Nadu. BIS certification requirements filter imported formulations against domestic performance benchmarks. Electronics manufacturing clusters in Noida and Sriperumbudur test copper-based variants for mid-range resistivity applications.
Conductive Glue Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with formulation IP and raw material access. The vendor base organizes across three tiers: multinational chemical conglomerates with automotive qualification pipelines, mid-cap specialists serving research and prototype channels, and regional compounders addressing cost-sensitive electronics assembly. Strategic moves concentrate on toll-manufacturing partnerships to reduce capital intensity and on PFAS-free reformulation to preempt regulatory deadlines.
Within the premium formulation tier, Henkel AG & Co. KGaA and 3M Company exemplify archetypes of integrated chemical platforms with broad patent estates. MG Chemicals Ltd. occupies a distinct position serving small-batch, quick-turn demand from research institutions and prototype shops. These three anchors illustrate how geographic footprint and customer scale segment competitive positioning without overlapping service models.
| Leading Market Players |
|---|
| Aremco Products, Inc. |
| Epoxy Technology Inc. |
| 3M Company |
| Master Bond Inc. |
| Permabond LLC |
| Henkel AG & Co. KGaA |
| Dow Corning Corporation |
| MG Chemicals Ltd. |
| H.B. Fuller Company |
| Others |
Value Chain & Pricing Dynamics
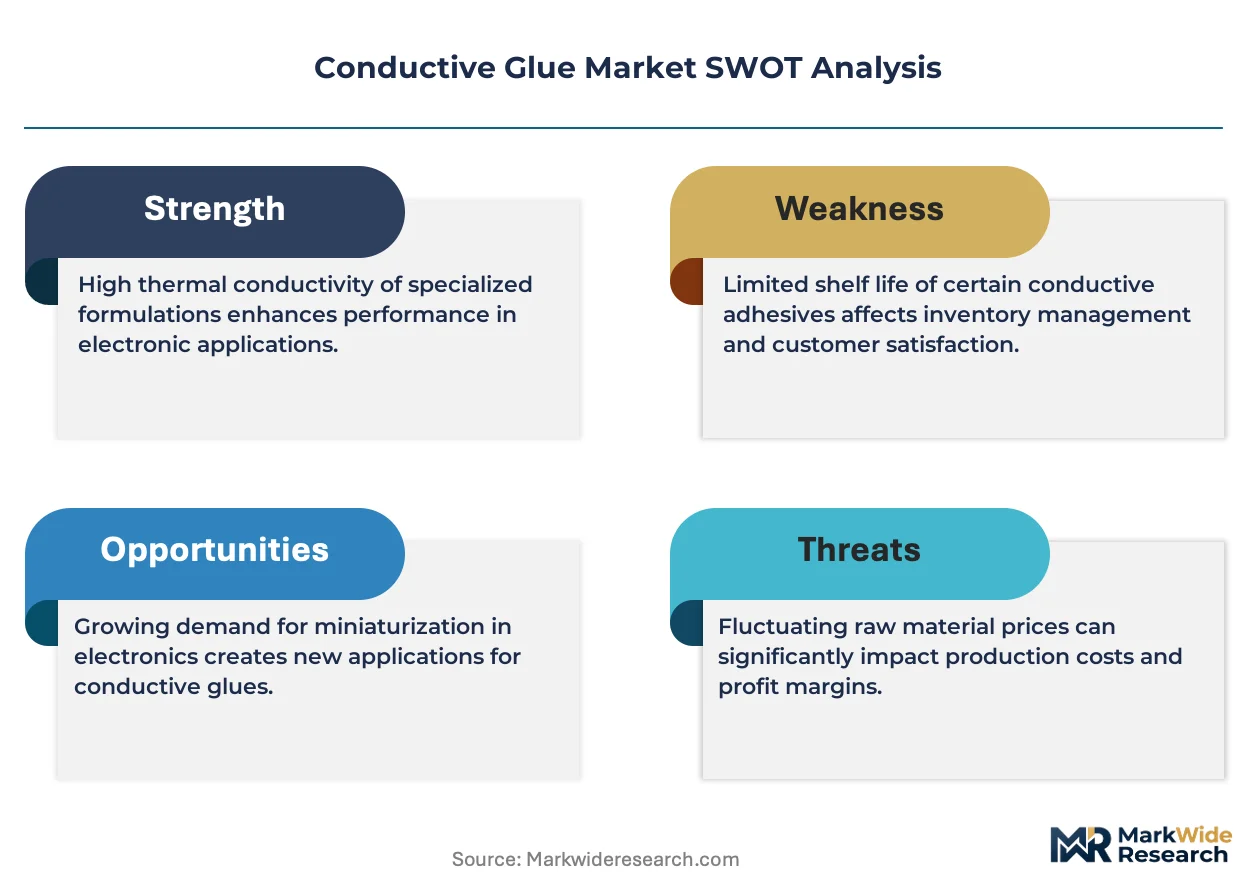
Undercapacity in Japanese silver-flake refining is tightening feedstock availability and amplifying supplier pricing power across conductive adhesive tiers. This utilization squeeze forces formulators into long-term offtake commitments or copper-substitution investments, reshaping procurement economics for automotive and biomedical buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock silver-epoxy pricing across 18-36 month automotive qualification cycles. Price differentiation hinges on REACH/RoHS certification tier and volume scale, with medical-grade biocompatibility testing adding substantial premiums. Cost compression in carbon-based tiers is intensifying because of copper-flake substitution programs in Indian and Chinese electronics clusters. Research institutions and DIY enthusiasts exhibit highest price sensitivity, while automotive OEMs prioritize reliability guarantees over unit cost.
Supply Chain Analysis
Toll-compounding arrangements with specialized EMS providers in Germany, Japan, and Michigan concentrate formulation capacity for qualified automotive volumes. Silver-flake precursors draw from three specialized Japanese refiners, while epoxy resins feed from German and US chemical platforms. Single-source vulnerability in premium flake supply creates structural risk exposure for high-conductivity formulations. Distribution runs through approved vendor programs with tier-one automotive assemblers and direct technical sales to research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against laser-welding and mechanical interconnect technologies that threaten adhesive share in battery assembly. Incumbents must navigate this displacement pressure while locking in automotive qualification pipelines.
For Market Incumbents: Pre-empt copper-formulation commoditization by accelerating PFAS-free qualification ahead of regulatory deadlines. Deepen backward integration into silver-flake toll-refining partnerships to secure feedstock priority during supply crunches. Anchor automotive OEM relationships through integrated failure-analysis capabilities that laser-welding competitors cannot replicate.
For New Entrants and Emerging Players: India's PLI-backed electronics clusters in Karnataka and Tamil Nadu offer the most penetrable geographic underpenetration for copper-based formulation qualification. Target biomedical wearable developers in Minnesota and Bavaria with skin-compatible, stretchable conductor prototypes. Pursue toll-manufacturing partnerships with established German compounders to bypass 18-36 month automotive validation barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across toll-manufacturing-dependent mid-caps, improving returns on specialized formulation IP. The five-to-ten year viability window favors acquisition targets holding automotive-approved vendor status and PFAS-free formulation libraries. Monitor BIS certification progress in Indian electronics clusters as inflection signal for regional supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Reformulation Program | Preempts ECHA restriction timelines and secures REACH-compliant positioning for European automotive procurement. |
| Silver-Flake Toll-Refining Partnership | Locks feedstock priority with Japanese refiners during supply crunches that destabilize competitor margins. |
| Automotive Qualification Pipeline Expansion | Captures 18-36 month OEM validation cycles before laser-welding alternatives achieve reliability parity. |
| Copper-Formulation Scale-Up | Reduces precious metal dependency by 40-60% for cost-sensitive Indian and Chinese electronics assembly. |
| Biomedical Wearable Co-Development | Positions skin-compatible stretchable conductors for FDA and EMA approval in cardiac patch applications. |
Study Parameters
Operator-level perspectives from adhesive formulation chemists, automotive tier-one procurement directors, biomedical device engineers, and toll-compounding facility managers anchored the qualitative base. These primary engagements were cross-validated against customs trade data for silver-flake and epoxy resin flows, SEC filings from chemical conglomerates, and BIS/MIIT certification records. Bottom-up volume modeling triangulated with top-down market sizing across product type, application, and regional production hub dimensions.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity bands reflecting silver price volatility and automotive electrification adoption curves. Segmentation dimensions modeled included filler material tier, end-use reliability standard, packaging format, and customer scale archetype. CAGRs were derived from regression analysis of historical qualification cycle lengths and substitution elasticity parameters, with specific inputs from EPA VOC enforcement intensity and REACH substance restriction timelines.
Practitioners should monitor silver-flake refinery utilization rates, PFAS regulatory advancement, and automotive platform electrification commitments for early signals of forecast revision. Quarterly review of BIS certification progress in Indian electronics clusters and KBA material traceability enforcement in German automotive corridors is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Chemical Anchors Market