
 Structural Adhesives Market | 2026-2036
Structural Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Adhesives Market Intelligence
High-performance epoxy grades rated for elevated-temperature cure cycles is rotating demand toward aerospace-qualified formulations. Henkel AG & Co. KGaA leverages its European automotive certification base to anchor supply contracts with German OEMs. Dow Inc. sustains feedstock integration across its Midland, Michigan operations, controlling raw material cost volatility. Sika AG specializes in construction-grade polyurethane systems, dominating infrastructure repair applications across Western Europe.
Structural adhesives are load-bearing polymer systems formulated from epoxy, polyurethane, acrylic, or silicone resin bases, typically achieving lap-shear strengths above 1,000 psi through controlled crosslinking chemistry; they replace welds, rivets, and bolts in assemblies where stress distribution and weight reduction are critical. Epoxy formulations lead the product type landscape due to their superior strength-to-weight ratio and chemical resistance in aerospace bonding applications. UV-cured technology segments are gaining traction in electronics assembly where rapid processing and minimal thermal exposure protect sensitive components.
EPA emissions standards in the United States restrict solvent-based adhesive formulations, redirecting R&D investment toward water-based and hot-melt platforms. REACH registration requirements in Europe enforce full substance toxicity disclosure, raising compliance costs for imported Asian formulations. ECHA substance evaluations are accelerating substitution of bisphenol-A derived epoxies in consumer-facing applications. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance strategies valid in one geography may disqualify products from adjacent markets.
Market Dynamics
Automotive lightweighting mandates from NHTSA and EU Green Deal targets are compressing bondline specifications, forcing formulators to engineer adhesives that cure faster, carry higher structural loads, and survive electrified powertrain thermal cycling without mechanical fastener backup.
Growth Catalysts
- EU Green Deal decarbonization targets:OEMs in Germany and France must cut fleet emissions, accelerating epoxy and polyurethane substitution for spot welds in battery enclosures and body-in-white assemblies.
- China's NEV manufacturing zones:BYD and CATL supplier parks in Shenzhen and Ningbo concentrate demand for thermally conductive adhesives that manage battery pack heat flux.
- Hot-melt reactive polyurethane technology:Eliminates solvent flash-off time, letting Tier-1 suppliers run continuous bonding lines without VOC abatement capital.
Market Restraints
- Petrochemical feedstock volatility:Propylene oxide and bisphenol-A pricing swings compress epoxy formulator margins, especially for mid-volume producers without backward integration.
- Specialty curing agent concentration:Aliphatic amine supply concentrates among German and Japanese chemical majors, creating single-source risk for aerospace-qualified formulations.
- REACH substance evaluation timelines:ECHA's rolling review of cycloaliphatic amines extends re-registration cycles to 18-24 months, freezing formulation changes for European suppliers.
Strategic Opportunities
- India's PLI scheme for auto component manufacturing:Tier-2 adhesive formulators can anchor supply contracts in Tamil Nadu and Gujarat as Maruti Suzuki and Tata Motors localize EV platforms.
- Wind blade recycling mandates:Thermoplastic-epoxy hybrid chemistries that enable blade de-bonding at end-of-life open retrofit service revenue streams in Denmark and Spain.
- Digital dispensing integration:Robotics OEMs in South Korea and Germany now bundle vision-guided adhesive application systems, creating embedded chemistry subscription models.
Industry Challenges
- Surface preparation technician scarcity:Aerospace bonding shops in Wichita and Toulouse face 18-month backlogs for NDT-certified technicians who can execute phosphoric acid anodizing to BAC5555 specifications.
- Dual-chemistry qualification timelines:Automotive OEMs require 24-36 month validation cycles for new adhesive platforms, locking formulators into existing chemistries even when superior alternatives emerge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Adhesives Market |
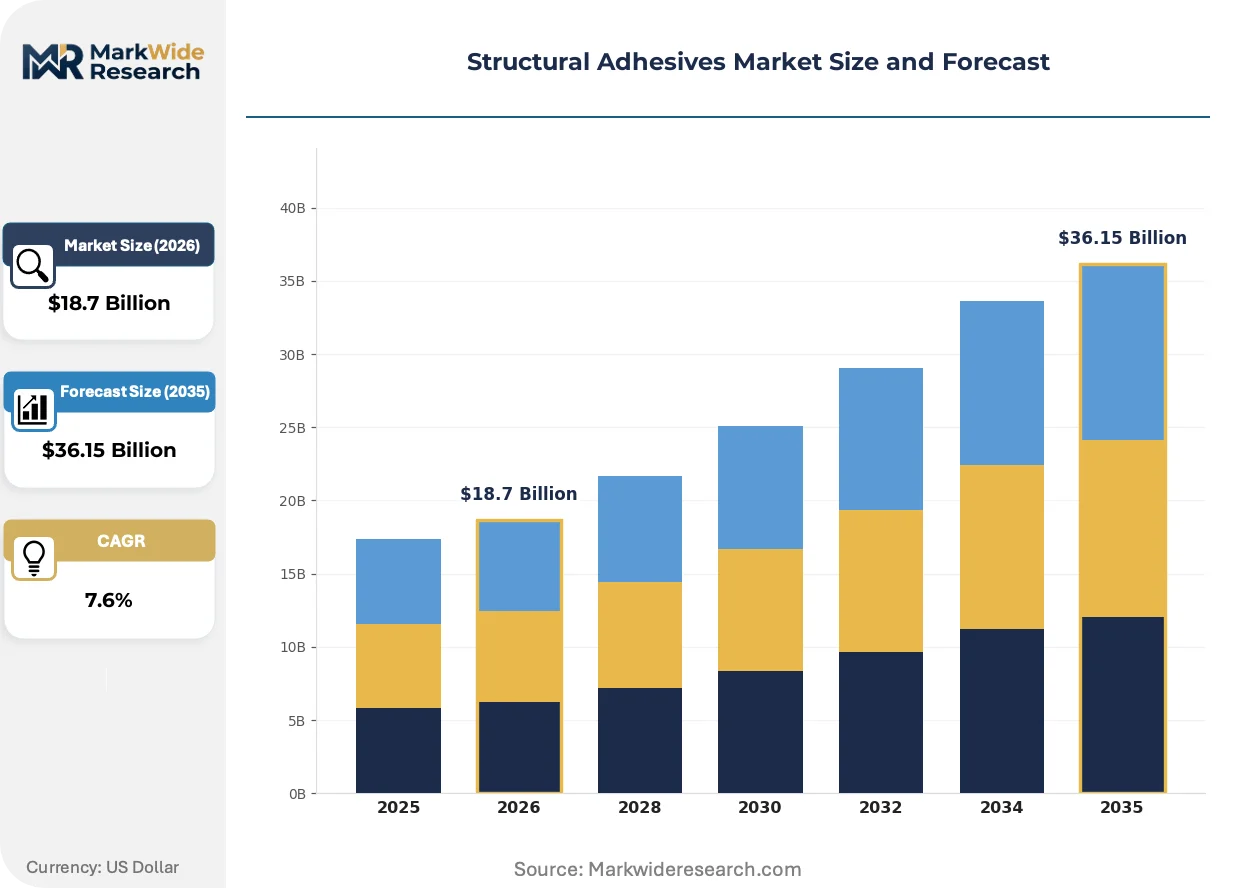
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Technology: Water-Based, Solvent-Based, Hot Melt, UV-Cured End User: Aerospace, Automotive, Construction, Marine Application: Bonding, Coating, Sealing, Assembly |
| Companies Covered | H.B. Fuller Company, Arkema S.A., Henkel AG & Co. KGaA, Illinois Tool Works Inc., Huntsman Corporation, 3M Company, Dow Inc., PPG Industries, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Adhesives Market Strategic Shifts & Innovations
Formulation chemistry is fragmenting into parallel tracks: one optimized for legacy manufacturing infrastructure, another engineered for electrified vehicle thermal management and automated dispensing. This split is compressing R&D cycles and rewiring supplier-OEM technical relationships.
UV-cured acrylic platforms are bifurcating the electronics assembly segment. Smartphone and wearable manufacturers in Taiwan and South Korea now specify cationic epoxy-acrylic hybrids that cure in under 5 seconds under 395nm LED arrays. The technology is displacing thermal-cure silicones in camera module bonding and compressing work-in-process inventory from hours to minutes.
REACH authorization requirements for diisocyanates entered full enforcement in August 2023, mandating industrial user training and respiratory protection upgrades across EU polyurethane adhesive applications. Construction and transportation sectors in Poland and Italy face 15-20% compliance cost inflation, pushing demand toward waterborne polyurethane dispersions and silane-terminated polymer alternatives.
Specification consolidation among battery OEMs is reshaping procurement patterns. CATL, LG Energy Solution, and SK On now publish unified adhesive performance matrices covering thermal conductivity, dielectric strength, and flame retardancy. Tier-2 formulators in Michigan and Bavaria must qualify against these matrices to maintain supplier status, compressing product differentiation to price and logistics responsiveness rather than technical performance claims.
Structural Adhesives Market Segmentation
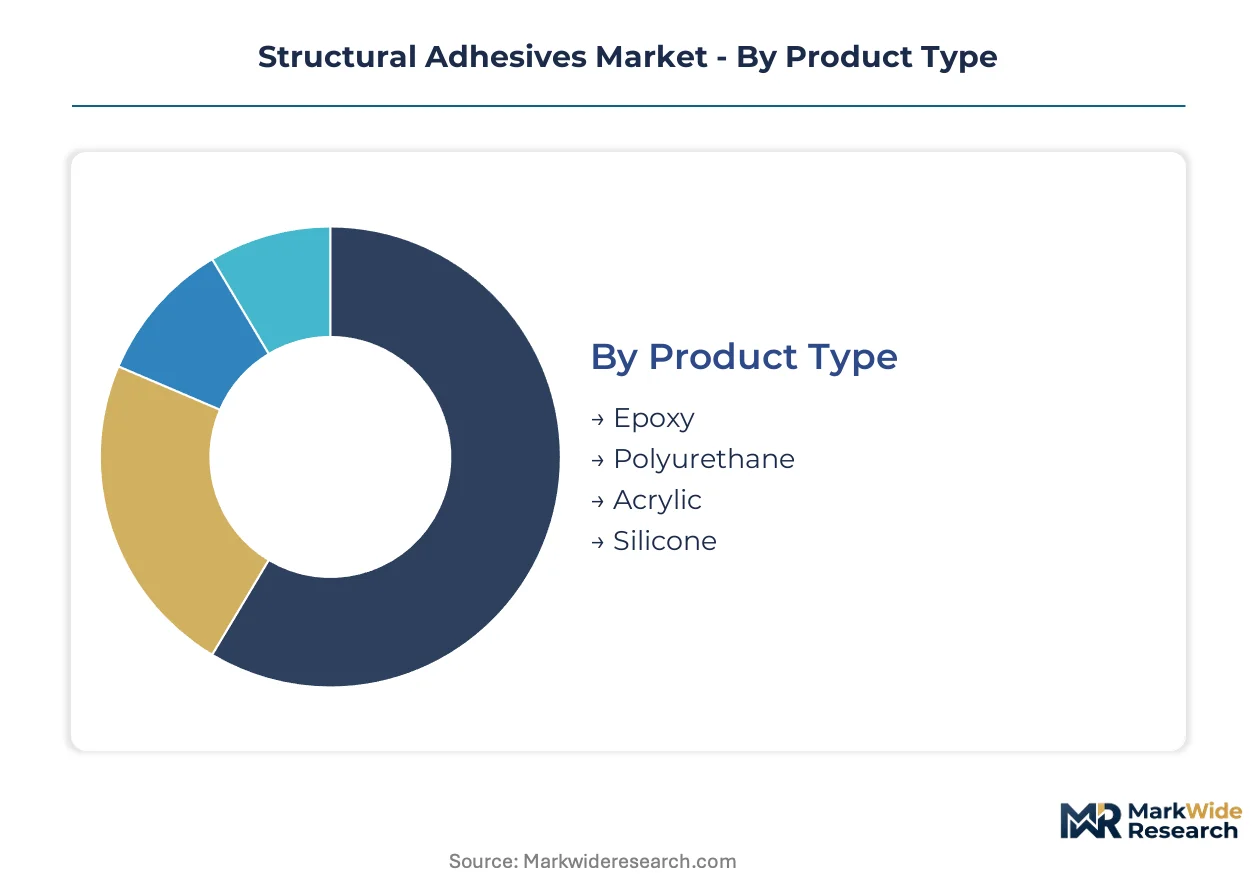
Structural adhesives serve divergent performance regimes across aerospace qualification cycles, automotive line-speed requirements, and construction weathering standards. Segmentation reveals where formulation chemistry, cure kinetics, and regulatory compliance intersect to determine supplier viability.
Product Type:
EPA emissions thresholds and REACH substance evaluations are bifurcating R&D investment toward low-VOC epoxy platforms and bio-based polyurethane alternatives, while acrylic and silicone formulations face divergent regulatory pressure across jurisdictions.
- Epoxy:Two-part thermoset systems built from bisphenol-A or bisphenol-F resins with amine or anhydride hardeners, achieving glass transition temperatures above 150°C. Demand concentrates in Germany's aerospace supplier corridor around Munich and Hamburg, where EASA qualification protocols for primary structural bonding favor epoxy's superior lap-shear performance and chemical resistance.
- Polyurethane:Isocyanate-terminated prepolymers reacting with polyols to form elastomeric bonds with excellent impact absorption and flexibility. China's NEV manufacturing zones in Shenzhen and Ningbo drive volume for battery enclosure bonding, where polyurethane's thermal cycling endurance and faster cure kinetics match CATL and BYD line-speed requirements.
- Acrylic:Reactive monomer systems cured through free-radical polymerization, offering room-temperature cure and tolerance for oily substrates. Construction applications in Poland and Italy favor acrylics for metal-to-plastic bonding where surface preparation is limited.
- Silicone:Crosslinked polydimethylsiloxane networks delivering extreme temperature stability from -55°C to 200°C plus UV resistance. Marine applications in Norway and South Korea specify silicone for deck sealing and glazing systems exposed to salt spray and thermal shock.
Epoxy handles the majority of throughput; polyurethane is expanding most quickly on share as automotive electrification accelerates.
Technology:
Cost tier differentiation separates capital-intensive solvent abatement infrastructure from lean water-based and hot-melt platforms accessible to mid-volume formulators.
- Water-Based:Aqueous dispersions of acrylic or polyurethane polymers with VOC content below 50 g/L, compliant with EPA Method 24 and EU Directive 2004/42/EC. Construction repair contractors in France and Spain specify water-based systems for interior applications where worker exposure limits are stringent.
- Solvent-Based:Solutions of rubber or thermoplastic resins in organic carriers delivering fast tack and high initial strength. Regulatory retreat is concentrating remaining demand in aerospace maintenance facilities where legacy specifications and cold-bonding requirements preserve niche use.
- Hot Melt:Thermoplastic formulations applied molten and solidifying on cooling, eliminating cure time and solvent emissions. Automotive Tier-1 suppliers in Michigan and Bavaria deploy reactive polyurethane hot melts for continuous bonding lines, capturing line-speed advantages without VOC abatement capital.
- UV-Cured:Photoinitiator-loaded acrylates or cationic epoxies polymerizing in seconds under 365-405nm LED arrays. Electronics assemblers in Taiwan and South Korea specify UV-cured platforms for camera module and display bonding, compressing work-in-process inventory from thermal cure cycles.
Hot melt commands the dominant share of new capacity investment; UV-cured systems are climbing the fastest as consumer electronics miniaturization intensifies.
End User:
Application maturity separates established aerospace qualification protocols from emerging automotive electrification requirements and fragmented construction procurement.
- Aerospace:Primary and secondary structural bonding for airframes, interiors, and engine nacelles governed by FAA AC 20-107B and EASA AMC 20-29. Wichita and Toulouse bonding shops face 18-month technician backlogs for phosphoric acid anodizing certification to BAC5555 specifications.
- Automotive:Body-in-white, battery enclosure, and interior trim applications where OEMs specify adhesives for crash-worthiness and NVH performance. NHTSA lightweighting mandates and EU Green Deal fleet emission targets are compressing bondline specifications and accelerating epoxy substitution for spot welds.
- Construction:Infrastructure repair, facade bonding, and flooring systems across Western Europe's aging building stock. Sika AG dominates this segment with polyurethane systems qualified to ETAG 002 for structural glazing.
- Marine:Hull bonding, deck sealing, and composite lamination for commercial vessels and offshore platforms. DNV-ST-C203 certification requirements in Norway and classification society rules in South Korea drive specification toward epoxy and silicone platforms.
Automotive generates the largest revenue pool; aerospace maintains the steepest expansion trajectory as next-generation aircraft programs multiply bonded primary structures.
Application:
Customer type differentiation separates specification-driven OEM engineering teams from price-sensitive maintenance and repair contractors.
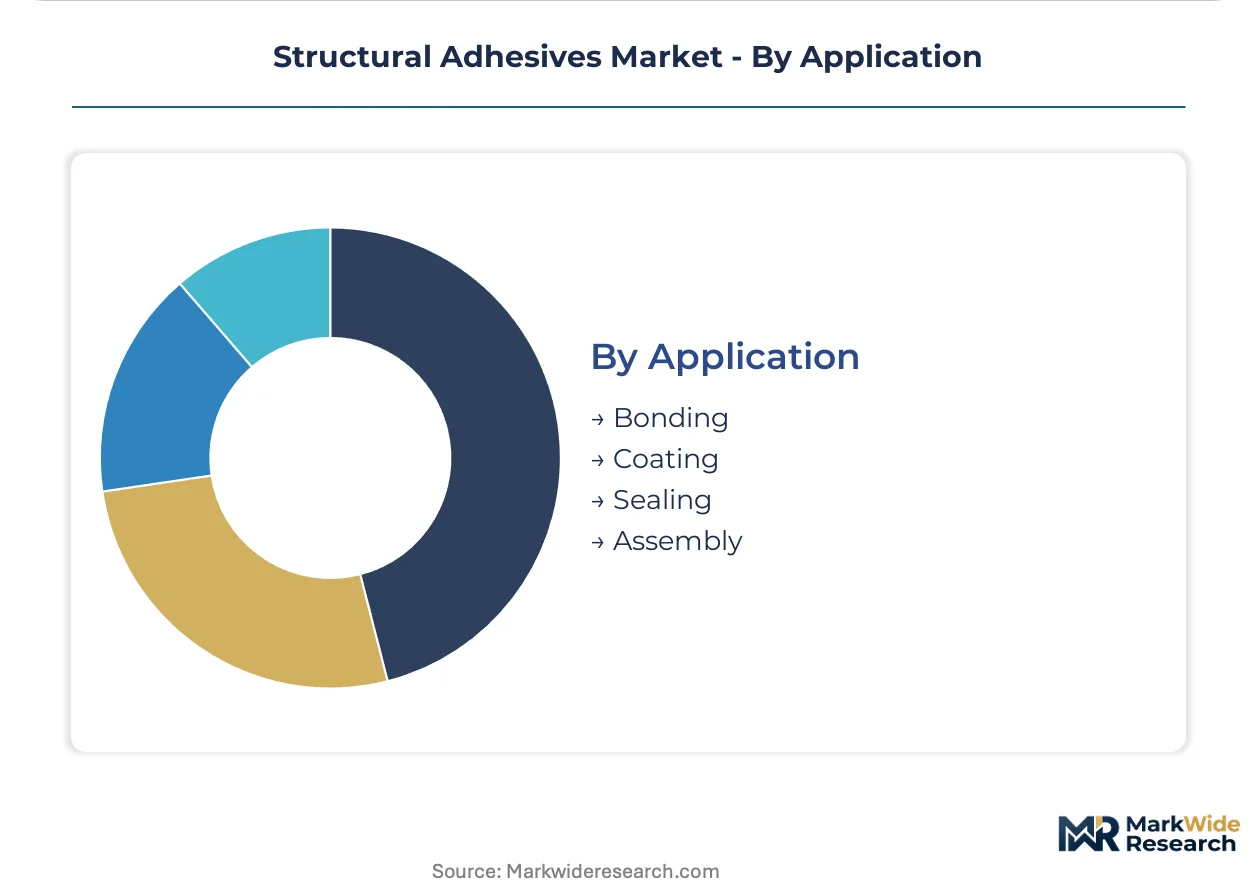
- Bonding:Load-bearing structural attachment replacing welds, rivets, and mechanical fasteners. Battery OEMs including CATL, LG Energy Solution, and SK On publish unified performance matrices covering thermal conductivity and dielectric strength that Tier-2 formulators must meet.
- Coating:Protective layers delivering chemical resistance, abrasion protection, or thermal insulation. Offshore platform operators in the North Sea specify epoxy coating systems for splash zone protection.
- Sealing:Gap-filling and environmental barrier applications requiring elasticity and durability. Automotive weatherstrip and glazing systems in Germany specify polyurethane sealants for 15-year service life.
- Assembly:Multi-component joining operations integrating diverse substrates. Electronics manufacturers in South Korea deploy UV-cured acrylics for rapid component fixation without thermal damage.
Bonding captures the dominant application share; assembly functions are gaining share fastest as automated dispensing systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's NEV manufacturing zones exhibit the lowest price elasticity as battery OEMs prioritize thermal management performance over unit cost, while European construction contractors face acute margin pressure from REACH compliance costs. German automotive suppliers sit at the midpoint, balancing lightweighting mandates against 24-36 month qualification timelines that lock in adhesive specifications.
United States
NHTSA lightweighting mandates and IRA clean vehicle tax credits are accelerating epoxy substitution for spot welds in Michigan's battery enclosure supplier parks. EPA Method 24 emissions thresholds restrict solvent-based formulations, redirecting R&D toward water-based and hot-melt platforms. Wichita's aerospace bonding shops face 18-month technician backlogs for phosphoric acid anodizing certification to BAC5555 specifications.
Germany
EASA qualification protocols for primary structural bonding concentrate epoxy demand around Munich and Hamburg aerospace corridors. EU Green Deal fleet emission targets compress bondline specifications for body-in-white assemblies. ECHA's rolling review of cycloaliphatic amines extends re-registration cycles to 18-24 months, freezing formulation changes for European suppliers.
China
BYD and CATL supplier parks in Shenzhen and Ningbo concentrate demand for thermally conductive adhesives managing battery pack heat flux. MIIT dual carbon goals and GB standards enforcement push toward low-VOC formulations. The Yangtze River Delta petrochemical hub anchors propylene oxide and bisphenol-A feedstock integration for domestic epoxy formulators.
South Korea
Samsung SDI and SK On battery manufacturing drives specification consolidation around unified performance matrices covering thermal conductivity and dielectric strength. MFDS chemical safety assessments and KOSHA workplace exposure limits regulate polyurethane adhesive applications. Seoul Capital Area electronics assemblers deploy UV-cured acrylics for camera module bonding, compressing work-in-process inventory from hours to minutes.
India
PLI scheme incentives for auto component manufacturing are localizing EV platform supply chains in Tamil Nadu and Gujarat. BIS certification requirements and DGFT import restrictions raise barriers for unqualified Asian formulations. Maruti Suzuki and Tata Motors supplier parks in Gurugram and Pune are qualifying new adhesive platforms against 15-year service life specifications for weatherstrip and glazing systems.
Structural Adhesives Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around diversified chemical conglomerates with captive resin production and specialized adhesive formulators with deep OEM qualification relationships. Three archetypes dominate: petrochemical-integrated multinationals controlling feedstock costs, European automotive-certified specialists leveraging EASA and OEM validation assets, and Asian electronics-focused suppliers optimizing UV-cure kinetics for high-speed assembly lines. Competitive dynamics center on backward integration into propylene oxide and bisphenol-A supply, and strategic partnerships with robotics OEMs bundling vision-guided dispensing systems.
Among petrochemical-integrated multinationals, Dow Inc. and Huntsman Corporation exemplify the feedstock-cost-control archetype through their Gulf Coast and Rotterdam manufacturing positions. Henkel AG & Co. KGaA occupies a distinctive position as a European automotive-certified specialist, anchoring supply relationships through its Düsseldorf-based OEM validation infrastructure. Sika AG represents the construction-grade formulation archetype, with its Swiss-registered structure signaling specialization in infrastructure and building envelope applications rather than automotive or electronics segments.
| Leading Market Players |
|---|
| H.B. Fuller Company |
| Arkema S.A. |
| Henkel AG & Co. KGaA |
| Illinois Tool Works Inc. |
| Huntsman Corporation |
| 3M Company |
| Dow Inc. |
| PPG Industries |
| Sika AG |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month REACH re-registration cycles for cycloaliphatic amines compress inventory turns and concentrate pricing power among German and Japanese chemical majors with validated aerospace qualifications. This lead-time band forces mid-volume formulators to absorb feedstock volatility or cede share to backward-integrated multinationals.
Pricing Analysis
After-sales technical service and formulation customization contracts drive lifetime value beyond unit adhesive sales. Three-tier pricing structure across aerospace-qualified, automotive-certified, and construction-grade levels separates EASA-validated epoxies from standard industrial formulations. Cost compression in mid-tier polyurethane segments intensifies as REACH diisocyanate training mandates inflate compliance spend for Polish and Italian contractors. Battery OEMs exhibit the lowest price sensitivity, prioritizing thermal conductivity matrices over unit economics, while construction maintenance contractors face acute margin pressure from VOC abatement capital requirements.
Supply Chain Analysis
Germany and Japan anchor specialty aliphatic amine production for aerospace-qualified curing agents, while China's Yangtze River Delta hub concentrates propylene oxide and bisphenol-A feedstock integration. Domestic epoxy formulators draw from this petrochemical base to serve BYD and CATL supplier parks in Shenzhen and Ningbo. Single-source vulnerability concentrates in German-Japanese amine supply for FAA and EASA-certified formulations. Distribution runs through Tier-1 automotive supplier parks in Michigan and Bavaria, with qualified logistics partners managing temperature-controlled resin transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical fastening resurgence in cost-driven automotive segments threatens adhesive substitution economics, compelling incumbents to defend position through performance validation assets and captive feedstock control.
For Market Incumbents: Fortify aerospace qualification moats by deepening EASA and FAA validation relationships in Toulouse and Wichita corridors. Backward integration into propylene oxide supply through Gulf Coast or Rotterdam positions insulates margin compression from petrochemical volatility. Lock automotive OEMs into 24-36 month qualification cycles before next-generation thermally conductive alternatives reach commercial scale. For New Entrants and Emerging Players: Differentiate on waterborne polyurethane dispersions targeting Poland and Italy construction contractors facing 15-20% REACH compliance cost inflation. India's Tamil Nadu and Gujarat auto component parks under PLI incentives present the most penetrable geography, with Maruti Suzuki and Tata Motors localizing EV platforms. Pursue fast-track BIS certification partnerships to bypass DGFT import barriers for unqualified Asian formulations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core adhesive divisions lacking OEM validation infrastructure. Long-term viability hinges on exposure to aerospace electrification and NEV battery thermal management rather than legacy construction segments. Monitor ECHA substance evaluation timelines for cycloaliphatic amines as inflection signal for formulation substitution cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Dow Inc.'s Midland operations demonstrate captive feedstock control insulating margin volatility for epoxy formulators. |
| EASA Qualification Investment | Henkel's Düsseldorf validation infrastructure anchors German OEM supply contracts against Asian competitors. |
| Waterborne Platform Development | Low-VOC polyurethane dispersions capture Polish and Italian contractors facing REACH diisocyanate enforcement. |
| Digital Dispensing Partnership | Robotics OEMs in South Korea bundle vision-guided systems creating embedded chemistry subscription models. |
| Thermoplastic-Epoxy Hybrid R&D | Denmark and Spain wind blade recycling mandates open retrofit service revenue for de-bondable chemistries. |
Research Approach
Initial hypotheses were tested against primary input from adhesive R&D directors, Tier-1 automotive procurement managers, aerospace bonding shop supervisors, and construction project engineers, and refined through secondary validation against ECHA substance evaluation databases, EPA Method 24 emissions filings, SEC 10-K disclosures from petrochemical majors, and customs trade data for propylene oxide and bisphenol-A flows. Bottom-up volume builds from end-use application modeling triangulated against top-down market sizing from feedstock consumption patterns.
Variance decomposition across product type, cure technology, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization in aerospace versus construction tiers. Forecast inputs incorporated MIIT dual carbon policy enforcement timelines and NHTSA lightweighting mandate compliance deadlines without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable petrochemical feedstock availability, or continued NEV production scaling would require recalibration. Forecasts reflect documented assumptions regarding qualification cycle durations and OEM specification consolidation patterns. Recalibration cycles align with material shifts in ECHA substance evaluation outcomes and battery OEM thermal management standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
American Epoxy Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Central Reinforced Tape Market