
 Global Municipal Water Treatment Chemicals Market | 2026-2036
Global Municipal Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Municipal Water Treatment Chemicals Market Foresight
Aftermarket service revenue is narrowing as a margin pool as chemical suppliers shift toward integrated water management contracts. Solenis leverages its digital monitoring platforms to embed long-term service agreements with municipal clients. Kurita Water Industries Ltd. anchors its position in Asia through localized manufacturing of polymer-based flocculants. Dow competes on scale in the bulk coagulant segment, sustaining cost advantages across North American and European utilities.
Municipal water treatment chemicals encompass formulated substances including aluminum sulfate, polyacrylamide polymers, chlorine derivatives, and phosphonate compounds applied at specified dosages measured in parts per million to remove suspended solids, neutralize pathogens, and stabilize distribution system infrastructure. Coagulants and flocculants dominate volume consumption due to their essential role in primary clarification across both drinking water and wastewater streams, while disinfectants command premium pricing tied to real-time residual monitoring requirements. The drinking water application segment leads value generation as regulatory residual mandates drive precision dosing systems, whereas wastewater applications show faster growth as nutrient removal regulations tighten discharge permits globally.
The EPA Safe Drinking Water Act and EU Drinking Water Directive establish enforceable maximum contaminant levels that directly determine chemical selection, dosing protocols, and supplier qualification criteria for municipal procurement. China's MEE enforces increasingly stringent surface water quality standards that mandate tertiary treatment chemicals in major river basin municipalities. ISO 14001 environmental management certification and NSF/ANSI Standard 60 product safety listings function as de facto market access requirements across multiple jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations, as emerging limits on fluorinated compounds threaten incumbent disinfectant chemistries and create openings for alternative oxidation technologies.
Market Dynamics
Stricter residual contaminant mandates under the EU Drinking Water Directive revision and the EPA's emerging PFAS limits are forcing municipal utilities to abandon legacy chlorine-only disinfection in favor of multi-barrier oxidation trains, compressing procurement cycles and elevating technical qualification barriers for chemical suppliers.
Growth Catalysts
- EU Drinking Water Directive revision:The updated directive mandates tighter control of disinfection byproducts and lead corrosion, compelling utilities across Germany, France, and Italy to upgrade coagulant dosing systems and orthophosphate stabilization programs.
- Southeast Asian megacity expansion:Piped water coverage targets in Jakarta, Manila, and Ho Chi Minh City outpace existing treatment capacity, creating immediate demand for rapid-deployment polymer flocculants and mobile chlorination units.
- Advanced oxidation processes:UV-peroxide and ozone-biofiltration combinations are displacing conventional chlorination in tertiary treatment, opening specification windows for hydrogen peroxide stabilizers and catalytic activators.
Market Restraints
- Alumina trihydrate feedstock volatility:Price swings in bauxite-derived raw materials squeeze margins for aluminum sulfate producers, particularly those serving North American utilities with fixed-price municipal contracts.
- Chinese phosphonate supply concentration:Over 60% of global phosphonate scale inhibitor capacity sits in Shandong and Jiangsu provinces, exposing downstream formulators to export license disruptions and ocean freight bottlenecks.
- Chloramine residual stability limits:Distribution system nitrification and biological regrowth constraints restrict chloramine adoption in warm-climate utilities, preserving chlorine dioxide's niche despite higher unit costs.
Strategic Opportunities
- Sub-Saharan African secondary cities:Utilities in Nigeria, Kenya, and Ghana lack centralized treatment infrastructure, creating openings for containerized coagulation-flocculation-sedimentation systems bundled with chemical supply agreements.
- Peracetic acid disinfection:Food-grade peracetic acid formulations are penetrating wastewater reuse applications in water-stressed Spanish and Australian municipalities seeking chlorine-free alternatives for agricultural irrigation.
- Smart dosing convergence:Integration of real-time turbidity sensors with AI-driven polymer feed controllers enables chemical suppliers to capture recurring software revenue alongside bulk chemical contracts.
Industry Challenges
- NSF/ANSI Standard 60 certification timelines:New chemical additives face 12-18 month evaluation periods for toxicological review and extraction testing, delaying product launches and freezing formulation innovation cycles.
- Legacy SCADA integration friction:Digital chemical feed systems must interface with decades-old programmable logic controllers common in mid-sized US and UK treatment plants, requiring costly custom protocol adapters.
- Specialized polymer chemist scarcity:Formulation expertise in high-molecular-weight polyacrylamide synthesis concentrates among retiring cohorts at German and Japanese suppliers, constraining knowledge transfer to emerging market facilities.
Report Scope
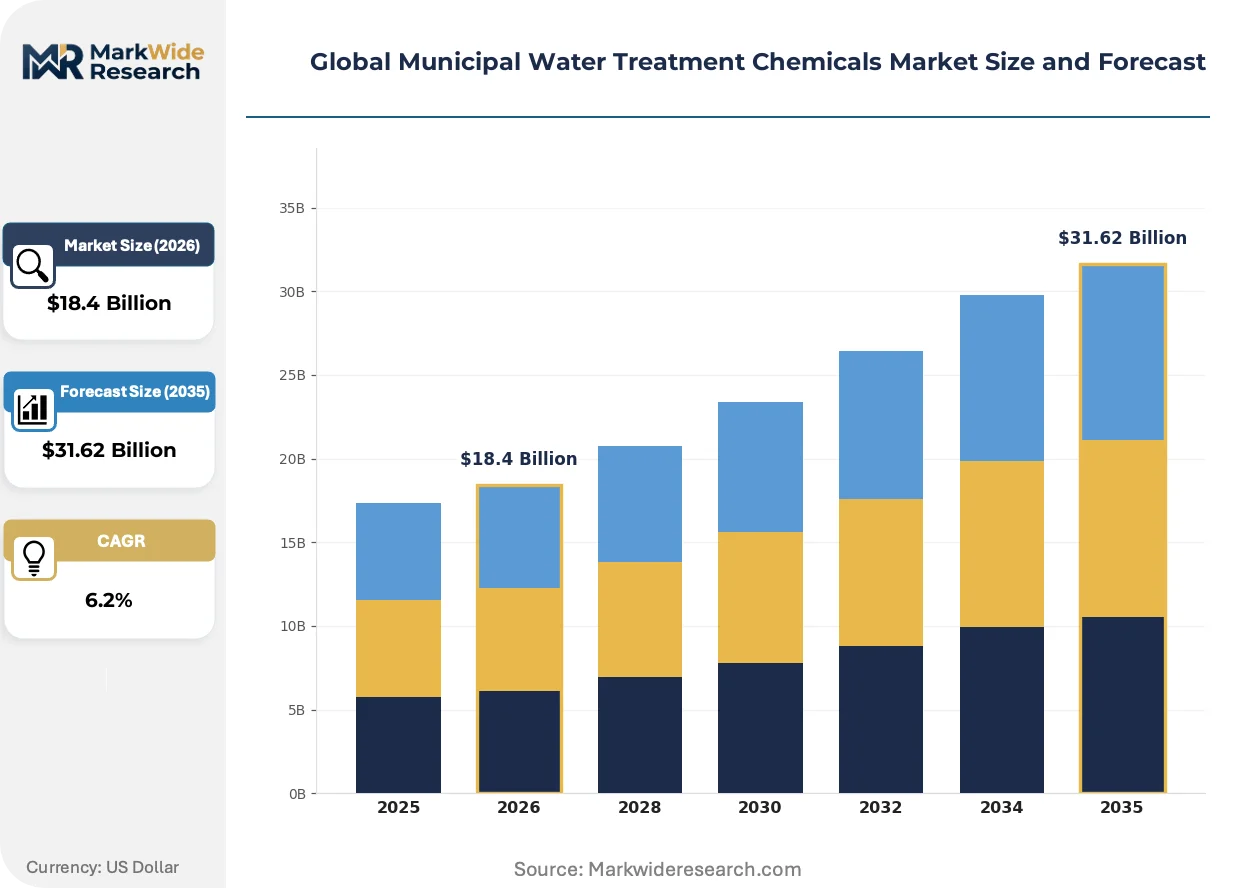
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Municipal Water Treatment Chemicals Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $31.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, Corrosion Inhibitors, pH Adjusters Application: Drinking Water, Wastewater, Industrial Effluent, Stormwater, Reclaimed Water End User: Municipal Corporations, Water Utilities, Environmental Agencies, Public Health Departments Packaging Type: Bulk Bags, Drums, Intermediate Bulk Containers, Cylinders, Sachets |
| Companies Covered | Solenis, Kurita Water Industries Ltd., Ecolab (Nalco Water), SNF, Dow, Kemira, Veolia Water Technologies & Solutions, ChemTreat Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Municipal Water Treatment Chemicals Market Shifts & Advancements
Electrochemical water treatment technologies and bio-based flocculant chemistries are disrupting established procurement patterns, while utility consolidation and performance-based contracting rewrite supplier relationship economics across developed and developing markets alike.
Membrane electrocoagulation systems utilizing sacrificial iron or aluminum anodes are rendering obsolete conventional liquid alum dosing in small-to-medium treatment plants. Danish and Dutch utilities under 50,000 population equivalent are piloting these units for color and natural organic matter removal. The technology eliminates bulk chemical storage hazards and sludge hauling costs, compressing operational expenditure structures by 30-40% in suitable applications.
REACH restrictions on acrylamide monomer residuals in polymer flocculants are tightening purity specifications for polyacrylamide suppliers serving EU municipal markets. The ECHA's 2024 updated guidance demands sub-0.025% monomer content in drinking water grades, forcing reformulation investments and disqualifying several Asian import sources. German and French utilities now require batch-specific chromatography certificates, extending qualification timelines and favoring regional manufacturers with in-house analytical capabilities.
Municipal procurement departments are consolidating chemical purchasing through cooperative purchasing organizations and state-level contracts, displacing individual utility tenders. The US Environmental Protection Agency's Water Infrastructure Finance and Innovation Act is accelerating this concentration by bundling chemical supply into design-build-operate concessions. California, Texas, and Florida water authorities now represent disproportionate decision-making power, compressing supplier margins while extending contract tenures to 7-10 years with renewal options tied to performance metrics.
Global Municipal Water Treatment Chemicals Market Segmentation
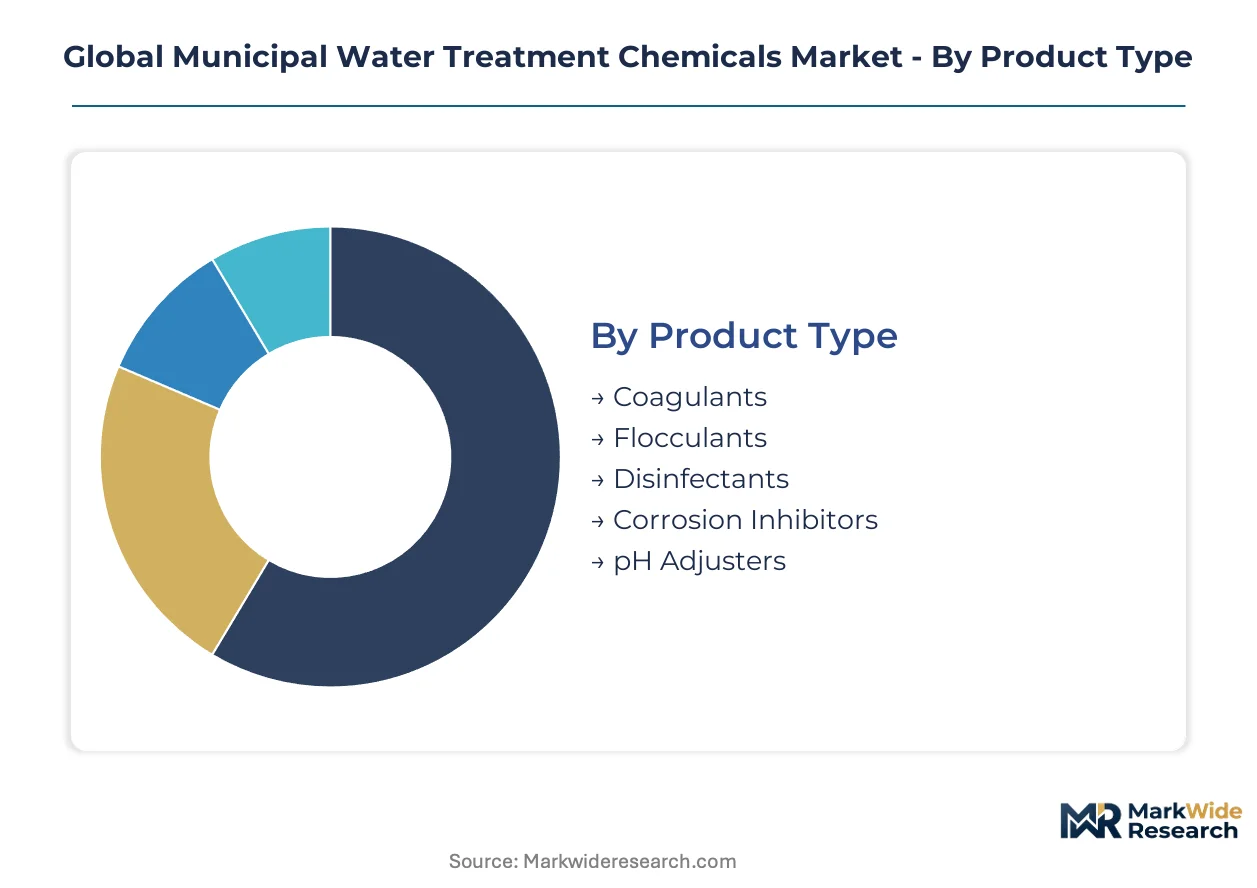
Municipal water treatment chemicals fragment across functional chemistries, application contexts, and delivery formats that each carry distinct margin profiles and qualification barriers. Procurement specifications vary sharply between drinking water and wastewater streams, while packaging economics reshape competitive access for small utilities versus metropolitan authorities.
Product Type:
Mature bulk commodities anchor volume, while advanced polymer formulations and specialty disinfectants capture expanding specification windows.
- Coagulants:Aluminum sulfate and ferric chloride dominate primary clarification, with demand concentrating in Southeast Asian megacities where rapid infrastructure deployment outpaces centralized chemical production. Municipal utilities in Jakarta and Manila favor liquid alum for its handling simplicity in containerized treatment units.
- Flocculants:High-molecular-weight polyacrylamide polymers enable suspended solids capture at lower dosages than metal salts. German and French utilities now mandate sub-0.025% acrylamide monomer content under REACH guidance, disqualifying several Asian import sources and favoring regional manufacturers with chromatography certification capabilities.
- Disinfectants:Chlorine derivatives, chlorine dioxide, and peracetic acid formulations neutralize pathogens across distribution networks.
- Corrosion Inhibitors:Phosphonate compounds and orthophosphate blends stabilize lead and iron infrastructure in aging distribution systems.
- pH Adjusters:Sulfuric acid, caustic soda, and sodium carbonate correct alkalinity in source waters with high natural organic matter.
Coagulants handle the majority of throughput; flocculants are gaining share fastest as precision dosing systems displace conventional metal salt overdosing.
Application:
Regulatory stringency varies across water streams, with potable mandates driving premium chemical grades and wastewater nutrient rules accelerating specialty demand.
- Drinking Water:EPA Safe Drinking Water Act and EU Drinking Water Directive residual mandates enforce real-time monitoring and precision dosing. Utilities in Italy and Spain are upgrading orthophosphate stabilization programs to meet revised lead corrosion controls.
- Wastewater:Tertiary nutrient removal regulations tighten discharge permits globally. Danish utilities under 50,000 population equivalent pilot membrane electrocoagulation for color and natural organic matter removal, eliminating bulk chemical storage hazards.
- Industrial Effluent:Pre-treatment requirements for municipal sewer discharge drive coagulant demand from food processing and textile clusters.
- Stormwater:First-flush capture systems in Australian and US Gulf Coast municipalities deploy rapid-settling polymer flocculants for sediment control.
- Reclaimed Water:Agricultural irrigation reuse in water-stressed Spanish municipalities favors chlorine-free peracetic acid disinfection to avoid crop phytotoxicity.
Drinking water commands the steepest premium tiers; wastewater shows the steepest expansion trajectory as tertiary treatment spreads.
End User:
Consolidation patterns reshape procurement leverage, with cooperative purchasing organizations displacing individual utility tenders in mature markets.
- Municipal Corporations:City governments in Nigeria, Kenya, and Ghana lack centralized treatment infrastructure, creating openings for containerized coagulation-flocculation-sedimentation systems bundled with chemical supply agreements.
- Water Utilities:California, Texas, and Florida authorities now represent disproportionate decision-making power, compressing supplier margins while extending contract tenures to 7-10 years.
- Environmental Agencies:River basin authorities in China enforce surface water quality standards that mandate tertiary treatment chemicals.
- Public Health Departments:Residual monitoring and outbreak response protocols drive emergency disinfectant stockpiling requirements.
Water utilities concentrate the largest contract volumes; environmental agencies are expanding their share fastest through basin-scale quality mandates.
Packaging Type:
Logistics economics and site constraints determine format selection, with bulk favoring large metropolitan plants and smaller units enabling decentralized deployment.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve high-volume coagulant consumers with dedicated unloading equipment.
- Drums:Standard 200-liter steel and polyethylene containers handle corrosive acids and specialized disinfectants.
- Intermediate Bulk Containers:Reusable totes with integrated dispensing systems reduce handling labor at mid-sized treatment plants.
- Cylinders:Pressurized chlorine gas and sulfur dioxide containers require specialized safety protocols and emergency response planning.
- Sachets:Pre-measured polymer packets enable rapid deployment in mobile treatment units and emergency response scenarios.
Bulk bags move the highest tonnage; intermediate bulk containers are climbing fastest as utilities seek to reduce drum waste and handling costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Municipal utilities in Germany and the Netherlands absorb premium chemical grades to meet EU residual mandates, while operators in Indonesia and Nigeria prioritize lowest-unit-cost procurement for rapid coverage expansion.
United States
California and Texas water authorities now bundle chemical supply into decade-long design-build-operate concessions under WIFIA financing. EPA Safe Drinking Water Act revisions on PFAS limits are forcing utilities in Florida and Arizona to abandon legacy chlorination for multi-barrier oxidation trains. The Great Lakes region concentrates demand for orthophosphate corrosion inhibitors as lead service line replacement accelerates.
Germany
REACH restrictions on acrylamide monomer residuals are disqualifying Asian polyacrylamide imports, favoring domestic manufacturers with chromatography certification. The EU Drinking Water Directive revision mandates tighter disinfection byproduct controls, compelling utilities in Bavaria and North Rhine-Westphalia to upgrade coagulant dosing precision. Berlin and Hamburg are piloting membrane electrocoagulation for natural organic matter removal.
China
MEE surface water quality standards mandate tertiary treatment chemicals in Yangtze and Pearl River basin municipalities. Over 60% of global phosphonate scale inhibitor capacity sits in Shandong and Jiangsu provinces, exposing downstream formulators to export license volatility. Shenzhen and Shanghai utilities are expanding advanced oxidation capacity for micropollutant removal.
Indonesia
Jakarta's piped water coverage targets outpace existing treatment infrastructure, creating immediate demand for rapid-deployment polymer flocculants. Municipal corporations lack centralized treatment assets, opening procurement to containerized coagulation-flocculation-sedimentation systems bundled with chemical supply agreements. Surabaya and Bandung are replicating this mobile treatment model.
Nigeria
Utilities in Lagos and Kano lack centralized infrastructure, creating openings for bundled chemical-and-equipment contracts from international suppliers. The national regulator enforces chlorination residual mandates without specifying product grades, preserving lowest-cost procurement preferences. Abuja and Port Harcourt are consolidating water authority purchasing to improve supplier negotiation leverage.
Global Municipal Water Treatment Chemicals Market Competitive Landscape
Capability concentration sits with specialty polymer and digital monitoring providers; scale advantage sits with bulk coagulant and commodity disinfectant producers. The market structures around three tiers: integrated water management contractors capturing long-term service revenue, regional manufacturers with localized formulation expertise, and commodity traders supplying price-sensitive emerging markets. Dominant competitive moves include backward integration into feedstock production and technology licensing for electrochemical treatment systems.
Among integrated service providers, Solenis exemplifies the digital-platform tier through embedded monitoring agreements, while Kurita Water Industries Ltd. anchors regional manufacturing strength in Asia-Pacific polymer supply. Dow occupies the scale-driven commodity position in bulk coagulant supply across North American and European utility networks.
| Leading Market Players |
|---|
| Solenis |
| Kurita Water Industries Ltd. |
| Ecolab (Nalco Water) |
| SNF |
| Dow |
| Kemira |
| Veolia Water Technologies & Solutions |
| ChemTreat Inc. |
| BASF SE |
| Others |
Supply & Pricing Matrix
Shandong and Jiangsu provinces anchor global phosphonate scale inhibitor capacity, concentrating upstream control among Chinese manufacturers and compressing margin flexibility for downstream formulators serving European and North American utilities. This geographic clustering amplifies pricing power during export license disruptions while forcing buyers toward long-term offtake contracts to secure volume certainty.
Pricing Analysis
Aftermarket service revenue from digital monitoring platforms and embedded dosing system maintenance drives lifetime value capture for integrated suppliers. Three-tier pricing structure across premium certified grades, standard NSF/ANSI-listed formulations, and economy bulk commodities separates municipal procurement tiers. Cost compression in standard-grade aluminum sulfate is intensifying because fixed-price municipal contracts in North America cannot pass through bauxite feedstock volatility. Small utilities in Sub-Saharan Africa exhibit highest price sensitivity, while German and Dutch authorities under EU Drinking Water Directive mandates absorb premium grades without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration for high-molecular-weight polyacrylamide rests with German and Japanese specialty polymer houses possessing in-house chromatography certification capabilities. Feedstock supply draws from bauxite refining clusters in Australia, China, and Guinea for aluminum sulfate production, while phosphonate precursor manufacturing anchors in Shandong province. Single-source vulnerability to Chinese export license disruptions represents the dominant structural risk. Distribution runs through cooperative purchasing organizations and state-level contracts in mature markets, with direct supplier-utility relationships dominating emerging economy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
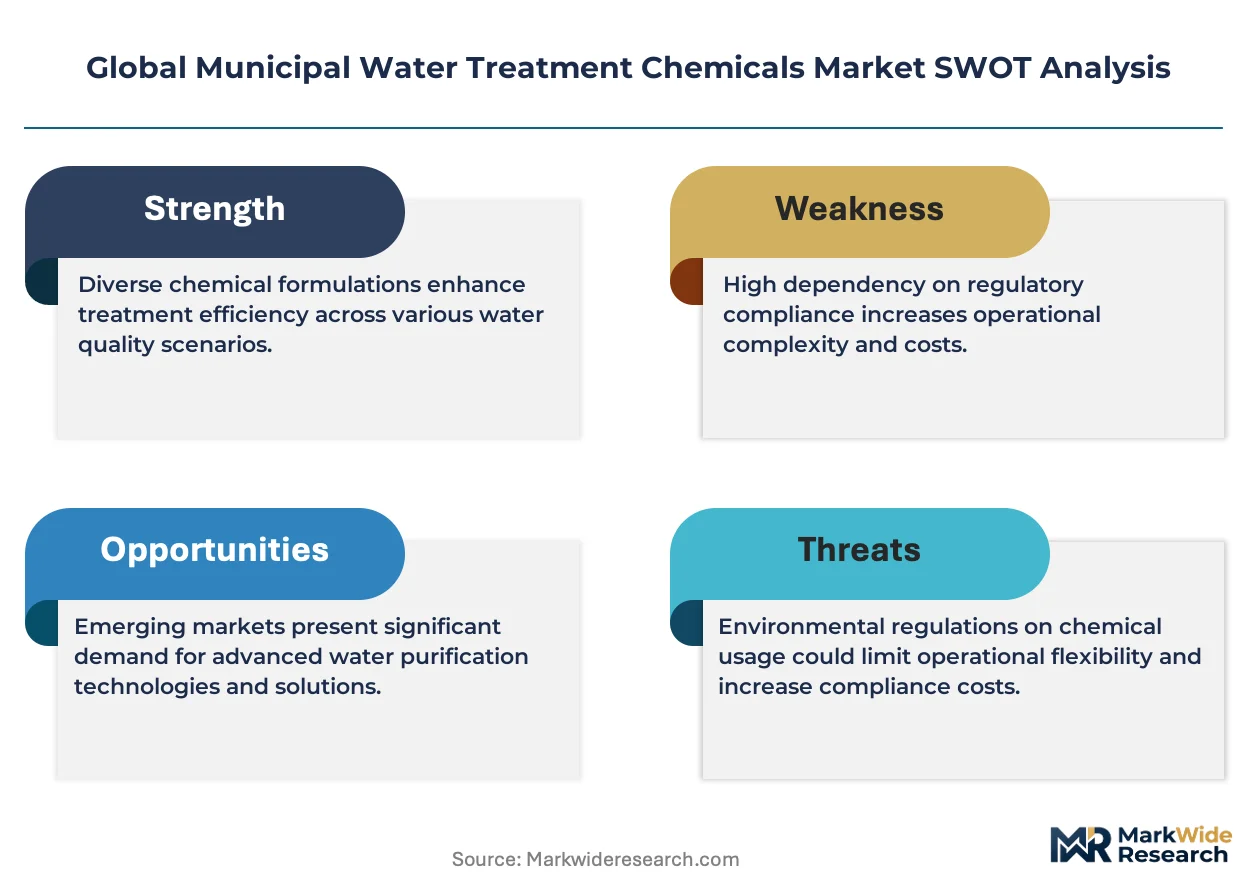
This market functions as a defensive-moat story where regulatory certification entrenchment creates prohibitive switching costs for municipal procurement departments. NSF/ANSI Standard 60 evaluation timelines and REACH acrylamide purity mandates lock qualified suppliers into multi-year relationships.
For Market Incumbents: Entrench position through backward integration into bauxite refining and phosphonate precursor manufacturing to neutralize feedstock volatility exposure. Deepen digital platform penetration by bundling AI-driven polymer feed controllers with chemical supply agreements, creating technical switching costs that resist substitution by electrochemical treatment technologies. For New Entrants and Emerging Players: Pursue containerized treatment system deployments in Nigerian and Kenyan secondary cities where centralized infrastructure gaps eliminate incumbent qualification advantages. Target bundled chemical-and-equipment contracts with municipal corporations lacking technical procurement capacity, leveraging rapid-deployment sachet packaging and mobile chlorination units as entry vectors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty polymer manufacturers with chromatography certification capabilities over commodity coagulant producers facing margin compression. Long-term viability rests on regulatory entrenchment durability rather than volume scale. Monitor ECHA guidance updates on fluorinated compound restrictions as inflection indicators for disinfectant chemistry substitution windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Production | Captive bauxite refining capacity insulates margin stability against alumina trihydrate price swings. |
| Digital Platform Integration | AI-driven dosing controllers from Solenis embed recurring software revenue alongside chemical contracts. |
| Regional Manufacturing Localization | Kurita Water Industries Ltd. anchors Asia-Pacific polymer supply through localized production facilities. |
| Certification Investment | REACH-compliant sub-0.025% acrylamide monomer content disqualifies Asian imports from EU municipal tenders. |
| Long-term Supply Agreement | California and Texas water authorities extend contract tenures to 7-10 years with performance-tied renewal options. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across municipal utility procurement managers, chemical plant technical directors, cooperative purchasing organization contract officers, and regulatory compliance specialists. Secondary validation drew from EPA Safe Drinking Water Act filings, EU Drinking Water Directive implementation reports, ECHA substance guidance updates, customs trade data for bauxite and phosphonate flows, and SEC 10-K disclosures from listed chemical suppliers. Bottom-up volume modeling across coagulant, flocculant, and disinfectant segments triangulated against top-down macroeconomic drivers.
Calibration against historical contract award data and utility capital expenditure announcements anchored projection parameters across the analysis window. Segmentation dimensions modeled include functional chemistry tier, drinking water versus wastewater application context, packaging format economics, and regional regulatory stringency clusters. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure investment pipelines and mandate implementation timelines. Forecast inputs included EU Drinking Water Directive revision compliance deadlines and Southeast Asian megacity piped water coverage targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrochemical technology developers or peracetic acid disinfectant specialists would shift outcomes beyond modeled ranges. Cross-checking against municipal bond issuance data for treatment infrastructure expansion is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Global Water Softeners Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
Fluid Waste Disposal Systems Market
Water & Sludge Treatment
Water Gel Market