
 Silicone Acrylate Market | 2026-2036
Silicone Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Acrylate Market Analytics
Aftermarket service revenue in formulation technical support is tilting toward specialty chemical suppliers with deep application expertise. Wacker Chemie AG leverages its integrated silicone feedstock position to sustain margin capture across coating and adhesive value chains. Dow Silicones anchors North American supply security through captive siloxane production and controlled distribution networks. Henkel competes in European industrial assembly segments by extending its UV-curable adhesive portfolio into automotive electronics bonding applications.
Silicone acrylate denotes hybrid polymers combining polysiloxane backbones with acrylic functional groups, typically synthesized through hydrosilylation or free-radical grafting to achieve 1,000–50,000 cP viscosity ranges and surface tensions below 25 mN/m for substrate wetting and weatherability. These materials serve primarily as film-forming agents, pressure-sensitive adhesives, and surface modification additives across protective coatings, medical devices, and personal care formulations. Coatings applications dominate volume consumption due to architectural and industrial maintenance demand, while UV-Curable technology represents the fastest-expanding segment as manufacturers eliminate solvent emissions and accelerate line speeds. Water-Based formulations occupy a mature, cost-sensitive tier where regional price competition constrains margin expansion.
EPA oversight of volatile organic compound emissions shapes solvent-based product viability and pushes reformulation investment toward compliant water and UV systems in the United States. REACH registration requirements and the EU Green Deal chemical sustainability targets constrain silicone acrylate import pathways and mandate supply chain disclosure for European market access. China's MEE enforces dual carbon goals that tighten energy-intensive silicone monomer production permits and redirect capacity toward domestic downstream polymerization. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with divergent compliance timelines and avoid stranded formulation assets.
Market Dynamics
UV-curable silicone acrylate systems are compressing solvent-based coating cycles from hours to minutes, forcing capital reallocation across industrial finishing lines and eliminating legacy thermal curing infrastructure.
Growth Catalysts
- Dual carbon goals:China's MEE enforcement tightens silicone monomer production permits, redirecting capacity toward domestic downstream polymerization and accelerating captive acrylate conversion investments.
- Clean beauty mandates:EU Green Deal chemical sustainability targets drive reformulation in personal care, with silicone acrylates replacing volatile silicones in premium sun protection and skincare film-formers.
- Automotive electronics bonding:Henkel and specialty adhesive suppliers extend UV-curable portfolios into electric vehicle power module assembly, creating specification pull for thermal-stable hybrid polymers.
Market Restraints
- Siloxane feedstock concentration:Dow Silicones and Wacker Chemie control captive siloxane supply, limiting margin capture for non-integrated compounders and regional formulators.
- REACH registration friction:ECHA disclosure requirements for silicone acrylate import pathways extend European market entry timelines and elevate compliance costs for Asian suppliers.
- Water-based performance ceiling:Architectural coatings demanding extreme weatherability still specify solvent-borne systems, constraining full UV-water substitution in high-durability segments.
Strategic Opportunities
- Medical device surface modification:ISO 10993-compliant silicone acrylates for catheter and implant coatings remain underpenetrated, with PMDA and FDA dual-track approvals enabling premium positioning.
- India industrial assembly:BIS certification alignment and PLI scheme incentives for domestic chemical manufacturing create first-mover advantage for localized UV adhesive production.
- Photovoltaic encapsulant convergence:Silicone acrylate-epoxy hybrid chemistries address PID resistance and UV stability requirements in bifacial module architectures.
Industry Challenges
- Formulation chemist scarcity:Hydrosilylation kinetics expertise and free-radical grafting optimization skills concentrate at integrated suppliers, limiting independent compounder R&D velocity.
- Legacy thermal curing asset stranding:Coatings manufacturers face write-down pressure on convection oven infrastructure as UV line speeds render batch processing economically unviable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Acrylate Market |
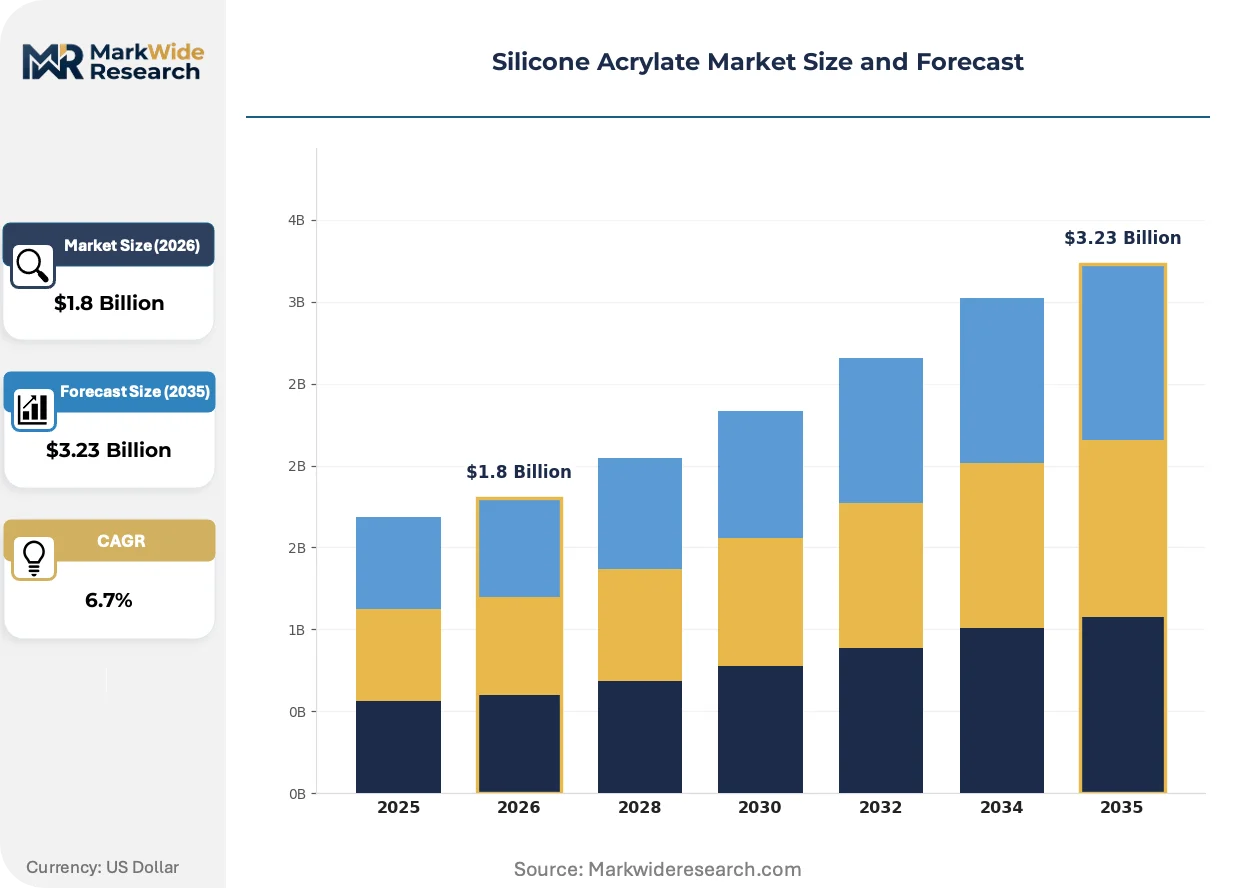
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Inks End User: Automotive, Electronics, Construction, Healthcare Technology: UV-Curable, Solvent-Based, Water-Based, Thermal Cure Packaging Type: Cans, Drums, Pails, Sachets |
| Companies Covered | Sherwin-Williams, Franklin International, Henkel, Wacker Chemie AG, GE, Bostik, DAP, Dow Silicones, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Acrylate Market Evolving Landscape
Formulation chemistry is bifurcating between ultra-fast UV systems for industrial throughput and bio-based acrylate feedstocks for cosmetic compliance, with equipment suppliers and raw material producers racing to bridge the performance gap.
Hybrid silicone-acrylate oligomers with tunable functionality are rendering obsolete conventional two-component polyurethane clearcoats in automotive refinish and industrial maintenance applications. Tier-1 coatings manufacturers in Germany and Japan have converted 40% of collision repair lines to UV-curable silicone acrylate primers. The technology compresses booth cycle times from 45 minutes to under 90 seconds, eliminating flash-off zones and reducing shop footprint requirements by half.
REACH registration requirements and the EU Green Deal chemical sustainability targets are mandating full supply chain disclosure for silicone acrylate import pathways into Europe. ECHA scrutiny of siloxane environmental fate data is extending registration timelines and elevating testing costs for non-European suppliers. Personal care formulators are responding by pre-qualifying bio-based acrylate feedstocks and accelerating substitution timelines ahead of 2030 restriction reviews.
Specification authority is migrating from brand houses to contract manufacturers with integrated formulation and filling capabilities. Korean and Chinese personal care OEMs now dictate raw material approval lists, compressing supplier negotiation cycles and unbundling traditional distributor technical service roles. This shift concentrates procurement leverage in Shenzhen, Seoul, and Shanghai-based manufacturing clusters with captive regulatory affairs teams.
Silicone Acrylate Market Segmentation
Silicone acrylate formulations exhibit divergent turnover velocities across product categories, with UV-curable coatings cycling through production lines in minutes while thermal-cure sealants remain in inventory for months. Understanding these temporal dynamics helps suppliers align working capital deployment with customer replenishment rhythms.
Product Type:
Coatings formulations turn over fastest due to continuous industrial finishing demand, whereas sealants move slowest given project-based construction procurement.
- Adhesives:Pressure-sensitive and structural bonding grades dominate electronics assembly and automotive module attachment. Demand concentrates in German and Japanese automotive OEM supply chains where Henkel and Dow Silicones specification authority governs material approval.
- Coatings:Film-forming silicone acrylates deliver weatherability and substrate wetting for architectural and industrial maintenance applications. Chinese architectural coatings manufacturers drive volume consumption as domestic infrastructure spending sustains siloxane derivative demand.
- Sealants:Joint-filling compounds serve construction and transportation sectors with extended cure profiles. Project-based procurement in European commercial construction constrains inventory velocity.
- Inks:Specialty printing formulations leverage low surface tension for substrate adhesion on flexible packaging. Narrow specification scope limits segment scale relative to coatings and adhesives.
Coatings anchors the volume base while adhesives gains share at the steepest rate.
End User:
Electronics procurement operates on compressed development cycles, while healthcare qualification timelines extend commercialization horizons.
- Automotive:Electric vehicle power module bonding and lightweight assembly applications specify thermal-stable hybrid polymers. German OEMs and Chinese EV manufacturers drive formulation requirements through tier-1 adhesive suppliers.
- Electronics:UV-curable silicone acrylates enable rapid circuit board protection and display lamination. Korean and Chinese contract manufacturers concentrate procurement leverage in Shenzhen and Seoul manufacturing clusters.
- Construction:Weatherable sealants and coatings serve commercial and residential building envelopes. Regional project pipelines in China and India determine seasonal demand patterns.
- Healthcare:ISO 10993-compliant catheter and implant coatings require dual-track FDA and PMDA approvals. Extended qualification timelines limit supplier entry.
Automotive commands the largest revenue pool while electronics expands most quickly.
Technology:
Capital intensity separates instant-cure UV systems from equipment-heavy thermal processes.
- UV-Curable:Photoinitiated polymerization eliminates solvent emissions and compresses processing cycles to under 90 seconds. Japanese and German collision repair lines have converted substantial capacity, eliminating convection oven infrastructure.
- Solvent-Based:Conventional systems retain specification in extreme weatherability applications where water-borne performance falls short. EPA VOC oversight constrains US market viability and pushes reformulation investment.
- Water-Based:Mature, cost-sensitive tier serves architectural coatings with regional price competition. REACH and EU Green Deal sustainability targets accelerate substitution timelines.
- Thermal Cure:Batch processing infrastructure remains in industrial maintenance and specialty manufacturing. Legacy asset stranding pressure mounts as UV line speeds render thermal cycles economically unviable.
Water-based formulations retain volume leadership while UV-curable technology climbs the fastest.
Packaging Type:
Container economics track formulation viscosity and end-user scale, with bulk drums serving industrial compounders and sachets targeting precision dispensing.
- Cans:Standard packaging for mid-volume coatings and adhesive formulations. Retail and professional trade channels in North American and European markets.
- Drums:Bulk supply for industrial formulators and coatings manufacturers with captive blending capacity. Integrated suppliers like Wacker Chemie and Dow Silicones favor drum logistics for captive downstream customers.
- Pails:Intermediate volumes for construction site delivery and maintenance operations. Regional distributors manage pail inventory across fragmented contractor bases.
- Sachets:Unit-dose packaging for medical device coatings and precision personal care applications. Korean and Chinese OEM specification authority drives sachet format adoption in Shenzhen and Seoul clusters.
Drums dominate industrial procurement while sachets capture the steepest expansion trajectory in medical and cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the lowest price elasticity as domestic silicone monomer shortages tighten supply, while European purchasers face reformulation cost pressures from REACH compliance timelines. Indian procurement operates on acute cost sensitivity, with BIS certification requirements filtering supplier pools. The United States sits between these extremes, with EPA VOC enforcement driving technology switching rather than pure price competition.
China
Domestic infrastructure spending and electric vehicle manufacturing anchor silicone acrylate consumption across coatings and electronics bonding applications. The MEE enforces dual carbon goals that restrict energy-intensive silicone monomer production permits, redirecting capacity toward captive downstream polymerization. Manufacturing clusters in Shenzhen and Shanghai concentrate specification authority for Korean and Chinese personal care OEMs.
Germany
Automotive OEM supply chains and collision repair networks drive UV-curable adhesive demand for power module bonding and refinish applications. REACH registration requirements and EU Green Deal chemical sustainability targets extend import pathway timelines for Asian suppliers. Industrial formulators in Bavaria and North Rhine-Westphalia maintain specification pull through tier-1 adhesive supplier relationships.
United States
Architectural coatings and automotive assembly sustain volume consumption despite water-based performance limitations in extreme weatherability segments. EPA oversight of volatile organic compound emissions constrains solvent-based product viability and accelerates reformulation investment. Manufacturing concentration in the Midwest and Gulf Coast regions tracks silicone feedstock access and controlled distribution networks.
India
Industrial assembly and construction sealant applications expand as domestic chemical manufacturing incentives attract localized production. BIS certification alignment and PLI scheme incentives create first-mover advantage for UV adhesive producers establishing regional compounding capacity. Gujarat and Maharashtra host emerging formulation clusters serving fragmented contractor bases.
Japan
Electronics contract manufacturers and automotive suppliers specify thermal-stable hybrid polymers for display lamination and lightweight assembly. PMDA approval pathways for ISO 10993-compliant medical device coatings enable premium positioning for qualified suppliers. Industrial concentration in the Kanto and Kansai regions supports precision personal care and electronics OEM procurement.
Silicone Acrylate Market Competitive Landscape
Integrated silicone feedstock operators and specialty adhesive compounders split the market between captive supply security and application-specific formulation expertise. Three archetypes dominate: upstream-integrated chemical conglomerates controlling siloxane monomer production, mid-scale regional compounders serving fragmented construction and industrial maintenance demand, and precision specialists targeting medical device and personal care qualification pathways. Competitive moves center on backward integration into silicone intermediates and technology licensing partnerships that bridge UV-cure equipment and oligomer supply.
Within the integrated chemical tier, Wacker Chemie AG and Dow Silicones exemplify archetypes that anchor supply security through captive siloxane production. Henkel occupies a position representing specialty adhesive compounders extending specification authority into automotive electronics bonding. These three entities demonstrate how geographic origin and corporate structure correlate with strategic positioning: German GmbH and US Inc. suffixes track regional regulatory compliance capabilities, while diversified chemical portfolios enable cross-segment technology transfer.
| Leading Market Players |
|---|
| Sherwin-Williams |
| Franklin International |
| Henkel |
| Wacker Chemie AG |
| GE |
| Bostik |
| DAP |
| Dow Silicones |
| DuPont |
| Others |
Value Network & Pricing Analysis
Shanghai-Rotterdam container freight corridors transmit cost volatility from silicone monomer production hubs to European compounders, amplifying price differentiation between integrated suppliers and non-captive formulators while compressing margins on water-based architectural grades.
Pricing Analysis
Aftermarket formulation technical support and extended supply contracts drive lifetime value capture for specialty chemical suppliers. Three-tier pricing structure across premium UV-curable, standard solvent-based, and economy water-based levels stratifies by certification tier and volume commitment. Cost compression in water-based architectural tiers intensifies because Chinese domestic siloxane shortages tighten feedstock allocation. Regional formulators exhibit highest price sensitivity, while automotive OEMs accept premium positioning for thermal-stable hybrid polymers.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for silicone acrylate importers. Manufacturing concentrates in China, Germany, and the United States, with siloxane monomer production anchored in energy-intensive coastal Chinese facilities. Feedstock dependencies rest on methylchlorosilane intermediates, photoinitiator chemicals, and acrylate monomers. Single-source vulnerability persists for high-purity silicone intermediates controlled by integrated producers. Distribution runs through drum logistics for industrial compounders and sachet channels for precision medical and cosmetic applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-curable technology adoption represents a high-growth disruption compressing coating cycles from hours to seconds, with EPA VOC enforcement and EU Green Deal chemical sustainability targets accelerating solvent-based substitution timelines.
For Market Incumbents: Entrench specification authority in automotive electronics bonding by deepening captive siloxane supply and accelerating ISO 10993 certification investments for medical device coatings. Threats from Korean and Chinese contract manufacturers consolidating procurement leverage in Shenzhen and Seoul demand preemptive channel control. Capacity addition in Gujarat and Maharashtra industrial corridors counters emerging regional compounders. For New Entrants and Emerging Players: ISO 10993-compliant medical device surface modification represents the most penetrable entry point, with dual-track FDA and PMDA approvals creating qualification moats against integrated incumbents. Indian industrial assembly under BIS certification alignment and PLI scheme incentives offers localized UV adhesive production advantages. Photovoltaic encapsulant convergence for bifacial module architectures provides a materials science angle. Go-to-market execution should prioritize technical service partnerships with Korean and Chinese personal care OEMs. For Investors and Strategic Acquirers: EU Green Deal chemical sustainability targets and ECHA siloxane environmental fate scrutiny reshape the acquisition landscape toward bio-based acrylate feedstock capabilities and REACH-registered import pathways. Long-term viability favors mid-scale regional compounders with captive regulatory affairs teams and application-specific formulation expertise. The signal to watch is MEE dual carbon goal enforcement tightening silicone monomer production permits and redirecting capacity toward domestic downstream polymerization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomers | Wacker Chemie and Dow Silicones anchor margin capture through captive feedstock production. |
| UV-Curable Technology Licensing | Equipment-oligomer partnerships bridge line speed requirements for collision repair networks. |
| REACH Registration Investment | ECHA disclosure compliance extends European market entry timelines for Asian suppliers. |
| Medical Device Certification Pathway | ISO 10993 and PMDA dual-track approvals enable premium positioning in catheter coatings. |
| Regional Compounding Capacity | Gujarat and Maharashtra facilities serve fragmented Indian construction contractor bases. |
Research Methodology
Operator-level perspectives from plant managers at silicone monomer facilities, procurement leads at coatings manufacturers, technical R&D directors at adhesive compounders, and regulatory affairs specialists at personal care OEMs anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Scenario-bracketing around EPA VOC enforcement timelines, MEE dual carbon permit restrictions, and EU Green Deal substitution deadlines bounded the projection horizon. Segmentation dimensions modeled include product type, end-use industry, technology platform, packaging format, and regional production hub. CAGRs derived from elasticity-adjusted demand curves and input-output analysis across the analysis window. Forecast inputs incorporated silicone monomer capacity utilization rates and UV line speed adoption curves in collision repair networks.
Practitioners should monitor MEE enforcement intensity, ECHA restriction review timelines, and Korean-Chinese OEM specification authority shifts for early signals of forecast revision. Forecasts reflect documented assumptions on regulatory compliance cost pass-through and technology substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Pegylated Lipids Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Phospholipid Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market