
 Australia Sealants Market | 2026-2036
Australia Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Sealants Market Outlook
Low-VOC and silyl-modified polymer chemistries are rewriting specification standards across Australian commercial construction. H.B. Fuller Australia leverages its local compounding footprint to serve project-scale glazing contracts with faster cure profiles. Sika AG anchors the infrastructure segment with bituminous and elastic jointing systems engineered for bridge and tunnel movement. Dow Inc. competes on silicone technology leadership, supplying structural glazing silicones certified to ASTM C1184 for high-rise facade applications.
Sealants are elastomeric materials formulated from polymers including polyurethane, silicone, acrylic, and butyl, designed to fill gaps while accommodating substrate movement through elastic recovery of 25% to 50% or greater. These compounds cure via moisture, heat, or UV activation to form impermeable barriers against air, water, dust, and acoustic transmission in building envelopes, vehicles, and industrial assemblies. Polyurethane dominates volume in construction bonding and sealing where high elongation and paint compatibility command specification preference. Silicone captures premium margin pools in structural glazing and weatherproofing applications demanding UV stability across decades of exposure. Acrylic serves cost-sensitive interior sealing and gap-filling segments where movement accommodation requirements remain modest.
TGA regulates chemical substance safety under the Industrial Chemicals Act while the National Construction Code mandates fire resistance and accessibility standards that directly influence sealant selection in commercial builds. Australian Building Codes Board updates to energy efficiency provisions are expanding demand for air-tight sealing systems in new residential and commercial construction. Stakeholders must monitor BIS-equivalent standard harmonization pressures and state-level environmental licensing shifts that could reshape local formulation requirements and import compliance pathways.
Market Dynamics
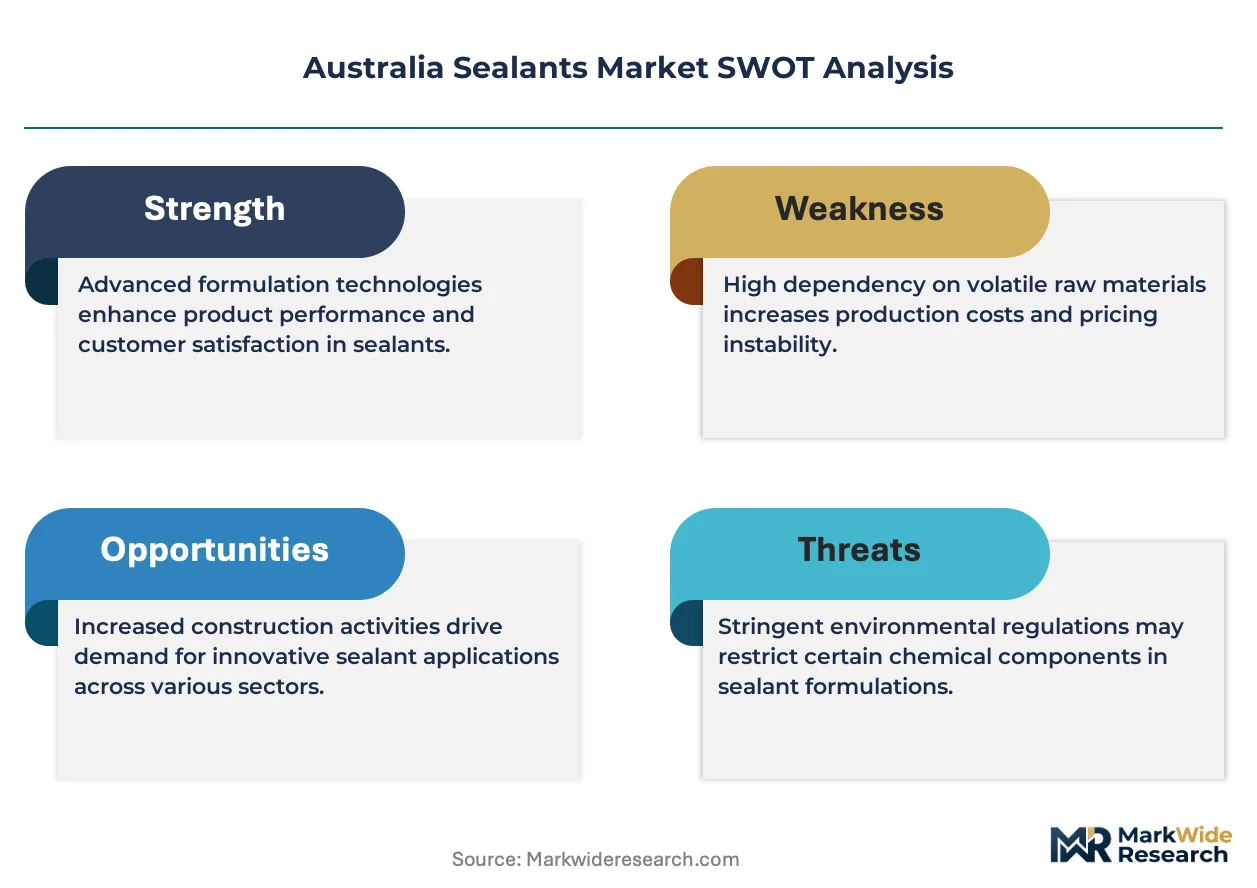
TGA's tightening VOC limits under the Industrial Chemicals Act are forcing wholesale chemistry transitions across Australian commercial construction, compressing specification windows and elevating compliance costs for non-silicone formulations.
Growth Catalysts
- National Construction Code energy efficiency provisions:Mandates for air-tight building envelopes are expanding specification of high-performance sealing systems across new residential and commercial developments in New South Wales and Victoria.
- Infrastructure sealing demand:Bridge and tunnel movement jointing requirements along Australia's eastern seaboard are accelerating procurement of bituminous and elastic jointing systems engineered for dynamic load accommodation.
- Structural glazing certification:ASTM C1184-compliant silicones are capturing premium specification pools in high-rise facade applications across Sydney and Melbourne CBD developments.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane precursor costs fluctuate with crude oil derivatives, compressing margin stability for construction-grade formulations.
- Import dependency concentration:Specialty silicone intermediates concentrate supply from Northeast Asian chemical complexes, exposing Australian compounders to freight and currency risk.
- Acrylic substitution ceiling:Interior gap-filling applications face displacement pressure from lower-cost hybrid sealants with comparable movement accommodation.
Strategic Opportunities
- Queensland infrastructure pipeline:Cross River Rail and Olympic venue construction are creating concentrated demand for certified fire-resistant jointing systems in Brisbane and Gold Coast corridors.
- Silyl-modified polymer convergence:Hybrid chemistries combining silicone weatherability with polyurethane paint compatibility are opening specification pathways in commercial refurbishment segments.
- Digital specification platforms:Building information modeling integration is enabling direct-to-contractor technical sales channels that bypass traditional distributor markups.
Industry Challenges
- Formulation chemist scarcity:Industrial chemical expertise concentration in Melbourne and Sydney limits regional compounding facility expansion.
- BIS-equivalent harmonization delays:Pending alignment between Australian Standards and ISO test methods is extending product certification timelines for import-dependent distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Sealants Market |
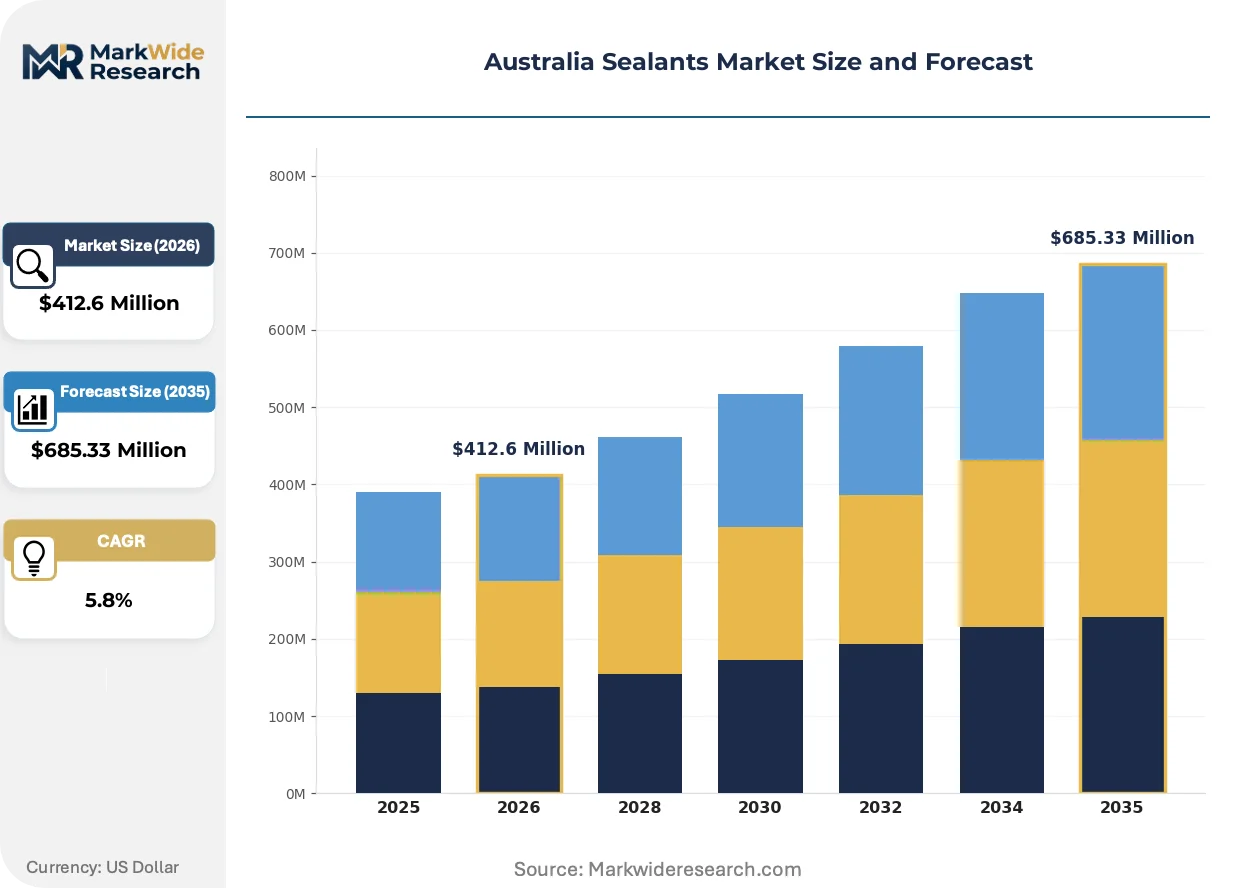
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: polyurethane, silicone, acrylic, butyl End User: construction, automotive, aerospace, marine Application: glazing, bonding, sealing, soundproofing Distribution Channel: online, wholesalers, retailers, direct sales |
| Companies Covered | Arkema Group, H.B. Fuller Australia, 3M, Weicon Australia, Bostik Australia Pty. Ltd., Sika AG, DuluxGroup Ltd., Dow Inc., Henkel AG & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Sealants Market Strategic Shifts
Moisture-cure chemistry advances and digital specification workflows are compressing traditional technical sales cycles across Australian commercial construction, with compliance automation emerging as the decisive competitive differentiator.
Silyl-modified polymer formulations are collapsing the historical trade-off between paint compatibility and UV stability that segmented polyurethane and silicone procurement. Specifiers in Victorian commercial glazing are adopting these hybrids at accelerating rates for refurbishment contracts requiring both aesthetic finish and long-term weatherproofing performance. The technology is collapsing premium-mid-tier price stratification as single products satisfy previously distinct specification tiers.
TGA's Industrial Chemicals Act enforcement is tightening substance safety documentation requirements for all imported sealant formulations. Commercial builders now face extended compliance verification timelines that compress project procurement windows and elevate preference for domestically compounded products with pre-cleared regulatory pathways. Multi-residential developments in New South Wales are responding by embedding TGA-compliant chemistry specifications into design-stage documentation.
Building information modeling platforms are enabling specification-integrated procurement where architects embed certified product libraries directly into construction documentation. Traditional distributor technical sales functions face compression as contractors source validated products through digital channels linked to compliance databases. This channel shift concentrates most visibly in Sydney and Melbourne commercial tower developments where design-build contracts compress traditional supply chain tiers.
Australia Sealants Market Segmentation
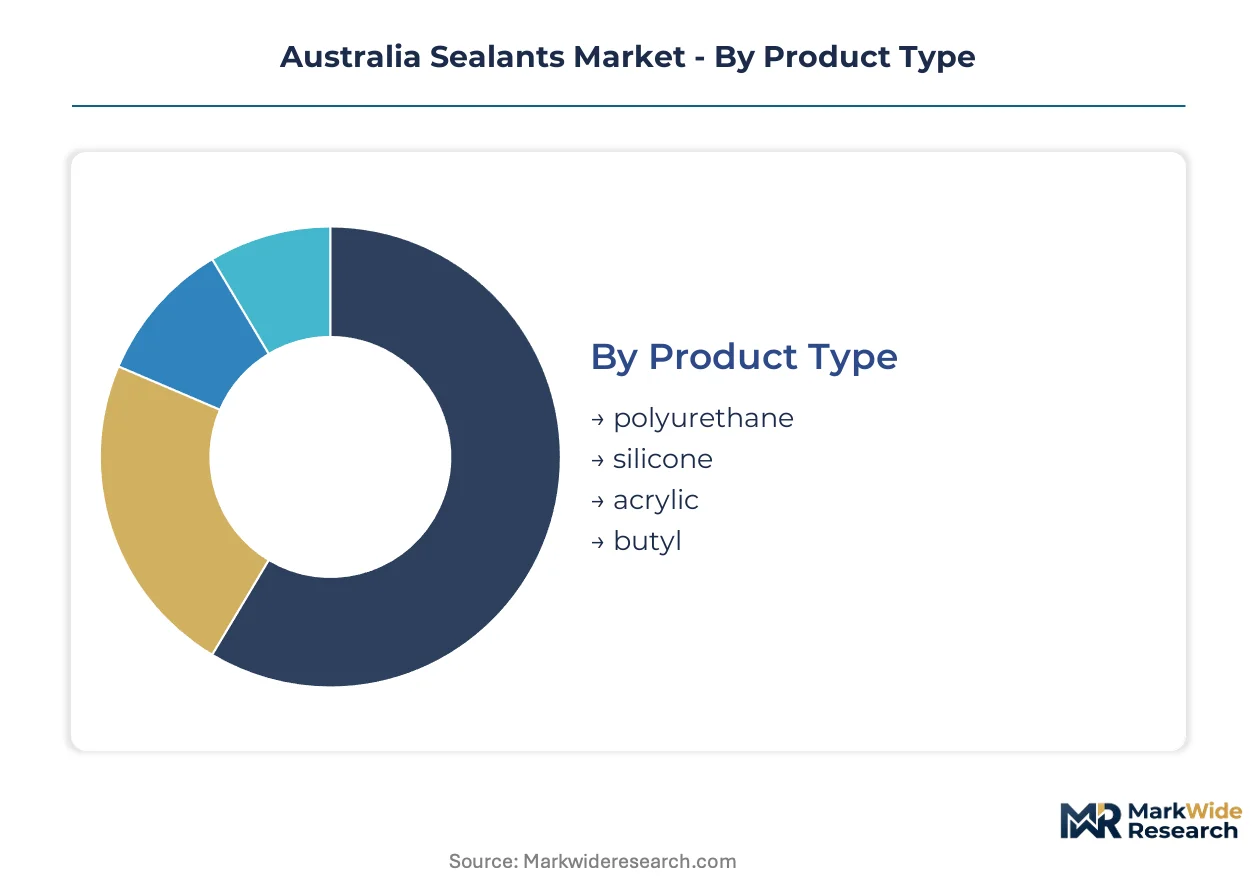
Australian sealant procurement divides sharply between mature construction chemistries and emerging hybrid formulations. Specification decisions track regulatory pressure from TGA and the National Construction Code, concentrating demand in compliant product tiers and certified application channels.
Product Type:
Mature polyurethane and silicone formulations dominate specification volumes, while silyl-modified polymers emerge as the convergent technology bridging paint compatibility with weatherability.
- Polyurethane:High-elongation elastomers formulated from isocyanate-terminated prepolymers cure through atmospheric moisture to form flexible seals accommodating 25% to 50% joint movement. Construction bonding across New South Wales commercial developments favors these formulations for paint compatibility and structural adhesion. Feedstock volatility from crude oil derivatives compresses margin stability for local compounders.
- Silicone:Cross-linked polydimethylsiloxane systems deliver UV stability across multi-decade exposure cycles, commanding premium specification in structural glazing applications. Sydney and Melbourne CBD high-rise facades specify ASTM C1184-certified silicones for structural glazing. Import dependency on Northeast Asian intermediates exposes compounders to freight and currency risk.
- Acrylic:Water-based emulsion sealants serve cost-sensitive interior gap-filling where movement accommodation requirements remain modest.
- Butyl:Preformed tapes and solvent-based compounds deliver impermeable vapor barriers in roofing and membrane applications.
Polyurethane retains volume leadership; silyl-modified polymer hybrids hold the steepest expansion curve as specifiers collapse the traditional silicone-polyurethane trade-off.
End User:
Application intensity varies by sector, with construction procurement anchoring volume and aerospace demanding certified performance tiers.
- Construction:Commercial glazing and infrastructure jointing across eastern seaboard developments concentrate demand for fire-resistant and air-tight sealing systems. National Construction Code energy efficiency provisions mandate air-tight envelopes, expanding specification of high-performance products in Victorian and Queensland residential towers. TGA VOC compliance requirements compress procurement windows toward pre-cleared domestic formulations.
- Automotive:OEM assembly and aftermarket repair applications specify noise-dampening and weatherstrip bonding systems. Paint-shop compatibility requirements favor polyurethane and hybrid chemistries over silicone for body-sealing applications.
- Aerospace:Fuel-resistant and high-temperature formulations serve MRO activities in Queensland and Victoria maintenance facilities.
- Marine:Submersible and deck-sealing applications along Australian coastal manufacturing corridors specify salt-resistant elastomeric systems.
Construction commands absolute volume; aerospace maintains the most stringent certification barriers to entry.
Application:
Functional requirements segment procurement between structural performance and secondary barrier applications.
- Glazing:Structural and weatherproofing seals for curtain wall and window systems demand ASTM-certified silicones with validated adhesion to anodized aluminum and coated glass. Sydney commercial tower developments embed certified product libraries directly into building information modeling documentation.
- Bonding:Structural adhesion in panelized construction and facade assembly favors high-strength polyurethane formulations with validated substrate compatibility.
- Sealing:General-purpose joint filling across building envelopes accommodates movement through elastic recovery.
- Soundproofing:Acoustic barrier applications in multi-residential construction specify mass-loaded and viscoelastic compounds.
Glazing captures premium margin pools; soundproofing gains share fastest as multi-residential density increases in Melbourne and Brisbane corridors.
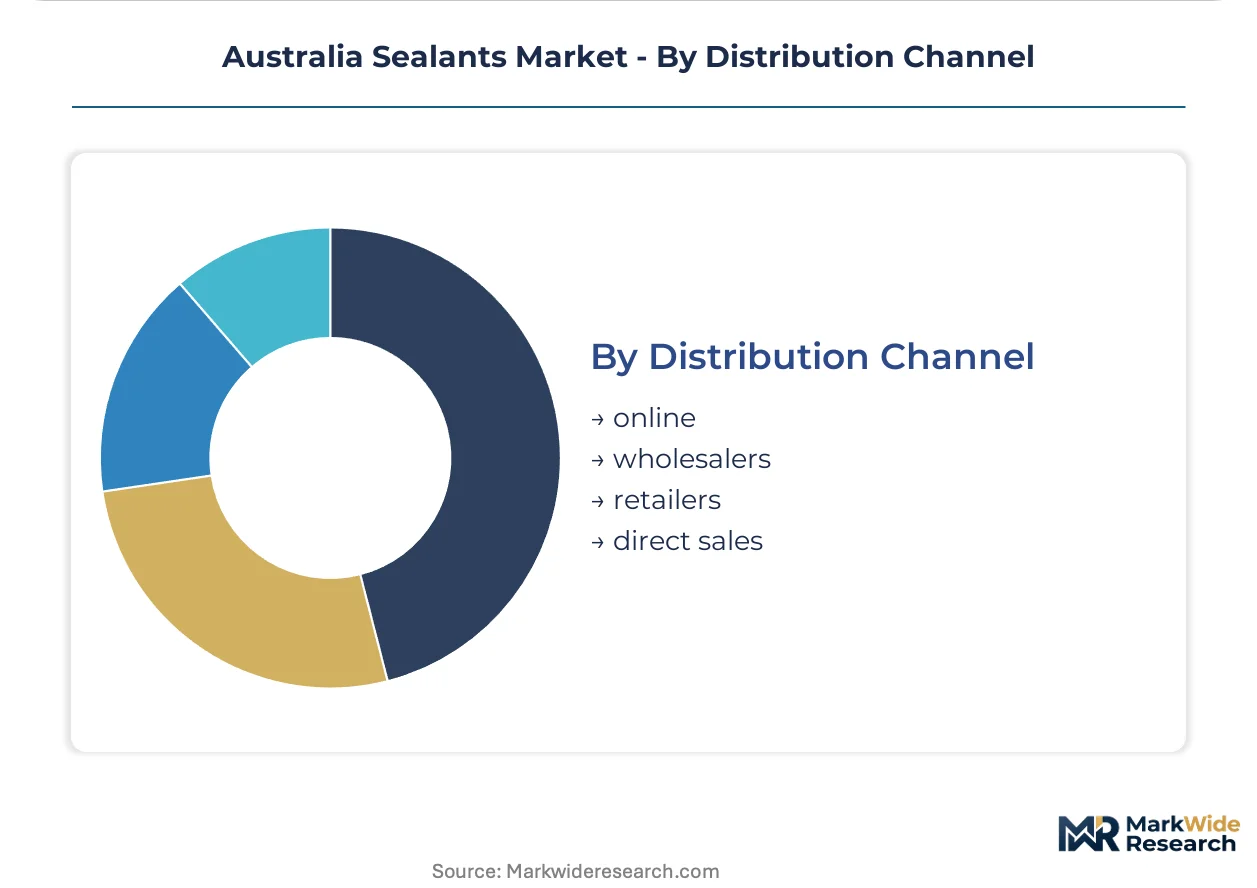
Distribution Channel:
Channel structure reflects project scale and specification integration, with digital platforms compressing traditional distributor tiers.
- Online:Digital specification platforms linked to TGA compliance databases enable direct-to-contractor procurement, bypassing traditional technical sales functions. Building information modeling integration concentrates this channel shift in Sydney and Melbourne design-build contracts.
- Wholesalers:Regional distributors maintain inventory positions for construction-grade formulations across state-level markets.
- Retailers:Hardware and trade outlets serve renovation and residential repair segments with consumer-packaged formulations.
- Direct Sales:Manufacturer technical representatives engage project-scale glazing contracts and infrastructure jointing specifications.
Wholesalers retain volume leadership; online channels climb the fastest as compliance automation reshapes procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean chemical intermediates flow into Australian compounding facilities serving construction projects across the eastern seaboard. This trade corridor concentrates supply risk in Northeast Asian manufacturing clusters while demand localizes in state-level building booms.
New South Wales
Commercial tower developments in Sydney CBD and Parramatta drive specification of ASTM C1184-certified structural glazing silicones. TGA's Industrial Chemicals Act enforcement compresses procurement windows toward pre-cleared domestic formulations. The Sydney-Melbourne corridor anchors high-rise facade demand with design-build contracts embedding certified product libraries into building information modeling documentation.
Victoria
Multi-residential density expansion in Melbourne's inner suburbs accelerates soundproofing sealant procurement for acoustic barrier applications. National Construction Code energy efficiency provisions mandate air-tight envelopes across Victorian residential towers. The Melbourne metropolitan construction cluster concentrates demand for silyl-modified polymer hybrids bridging paint compatibility with weatherability.
Queensland
Cross River Rail and 2032 Olympic venue construction create concentrated demand for fire-resistant jointing systems in Brisbane and Gold Coast corridors. State-level environmental licensing shifts redirect specification toward low-VOC chemistries compliant with tightening emission standards. The Brisbane infrastructure pipeline anchors bituminous and elastic jointing procurement for bridge and tunnel movement accommodation.
Western Australia
Mining sector maintenance activities in the Pilbara and Goldfields regions sustain industrial-grade sealing demand for equipment and processing infrastructure. Remote logistics costs elevate preference for bulk-formulation procurement with extended shelf stability. The Perth industrial corridor serves as distribution hub for resource sector sealant supply chains extending into northwestern extraction zones.
South Australia
Defence shipbuilding expansion at Osborne sustains marine-grade elastomeric procurement for submersible and deck-sealing applications. TGA compliance requirements extend verification timelines for import-dependent distributors serving the Adelaide manufacturing corridor. The state's coastal manufacturing base specifies salt-resistant formulations for naval and commercial vessel construction.
Australia Sealants Market Competitive Environment
On the supply side, the industry is moderately consolidated around multinational chemical compounders with Australian manufacturing or blending footprints. Three strategic archetypes dominate competitive positioning: global specialty chemical majors with localized compounding capacity, regional distributors with technical sales integration, and hybrid-technology specialists capturing refurbishment specification shifts. Dominant competitive moves include portfolio diversification into silyl-modified polymer formulations and strategic partnerships with building information modeling platform providers to compress distributor tiers.
Among multinational compounders with Australian presence, H.B. Fuller Australia, Sika AG, and Dow Inc. exemplify the tier of players leveraging global technology platforms against localized regulatory compliance capabilities. H.B. Fuller Australia represents the archetype of regional compounding operations serving project-scale contracts with faster cure profiles. Sika AG anchors infrastructure-focused positioning through bituminous and elastic jointing system expertise. Dow Inc. occupies a position emphasizing silicone technology leadership for structural glazing certification requirements. These three companies sit within the premium specification tier where ASTM certification and TGA pre-clearance create competitive moats against import-dependent distributors.
| Leading Market Players |
|---|
| Arkema Group |
| H.B. Fuller Australia |
| 3M |
| Weicon Australia |
| Bostik Australia Pty. Ltd. |
| Sika AG |
| DuluxGroup Ltd. |
| Dow Inc. |
| Henkel AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Northeast Asian silicone intermediate production is compressing feedstock margins and transferring pricing power downstream to Australian compounders with TGA pre-clearance pathways. This utilization dynamic elevates domestic formulation premiums while penalizing import-dependent distributors facing extended compliance verification timelines.
Pricing Analysis
Current-generation silyl-modified polymer formulations command 15-25% premiums over prior-generation polyurethane and silicone standalone products, reflecting collapsed trade-offs between paint compatibility and UV stability. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with ASTM C1184-certified structural glazing silicones anchoring the premium tier. Cost compression in mid-tier polyurethane formulations is intensifying because of crude oil derivative volatility, while acrylic economy tiers face displacement pressure from hybrid alternatives. Residential repair segments exhibit highest price sensitivity; infrastructure jointing specifications demonstrate lowest sensitivity due to performance guarantees and warranty bundling.
Supply Chain Analysis
Contract manufacturing concentration rests with Japanese and South Korean chemical complexes supplying specialty silicone intermediates and isocyanate-terminated prepolymers to Australian blending facilities. Geographic supply concentration centers on Japan, South Korea, and China for critical inputs including polydimethylsiloxane, MDI, and specialty catalyst packages. Single-source vulnerability from Northeast Asian intermediate concentration exposes compounders to freight cost spikes and currency fluctuation. Distribution runs through project-integrated digital channels in Sydney and Melbourne design-build contracts, with regional wholesalers maintaining inventory positions for state-level construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silyl-modified polymer substitution is accelerating specification shifts that threaten standalone polyurethane and silicone incumbents. Incumbents must defend position through chemistry convergence and compliance automation.
For Market Incumbents: Entrench TGA pre-clearance advantages by embedding certified product libraries into building information modeling platforms, compressing procurement windows for import-dependent competitors. Backward integration into specialty intermediate sourcing from Japanese suppliers reduces currency exposure and secures formulation consistency. Prioritize silyl-modified polymer R&D to collapse remaining performance gaps with standalone chemistries. For New Entrants and Emerging Players: Build out Queensland infrastructure corridor presence by targeting Cross River Rail and Olympic venue fire-resistant jointing specifications where incumbent technical sales coverage remains thin. Queensland state-level environmental licensing shifts create specification windows for low-VOC domestic compounders. Digital specification platform partnerships enable direct-to-contractor channels that bypass established distributor markups in Brisbane and Gold Coast markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with TGA pre-cleared formulation portfolios and building information modeling platform integration. Long-term viability favors Australian manufacturing footprint holders over import-dependent distributors facing compliance timeline extension. Acquisition target archetype: mid-cap compounders with silyl-modified polymer capabilities and Queensland infrastructure project exposure. Signal to watch: state-level environmental licensing acceleration in Victoria and New South Wales as inflection indicator for low-VOC chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | Captive supply from Japanese chemical complexes reduces currency exposure and secures TGA compliance pathways. |
| Building Information Modeling Platform Partnership | Direct specification integration in Sydney design-build contracts compresses traditional distributor technical sales tiers. |
| Silyl-Modified Polymer Capacity Expansion | Hybrid chemistry convergence captures refurbishment specification shifts across Victorian commercial glazing segments. |
| Queensland Infrastructure Corridor Positioning | Cross River Rail and Olympic venue procurement concentrates fire-resistant jointing demand in Brisbane corridors. |
| TGA Pre-Clearance Acceleration Program | Domestic formulation verification shortens procurement windows against import-dependent competitors. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with plant managers at Australian compounding facilities, procurement leads at New South Wales commercial developers, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, Australian Bureau of Statistics construction activity reports, TGA Industrial Chemicals Act filings, and SEC 10-K disclosures from multinational parent companies. Bottom-up and top-down triangulation cross-validated volume estimates against state-level building permit data and infrastructure project pipelines.
Forecast inputs considered chemistry-grade tier, end-use construction segment, packaging format, and regional production hub across the analysis window. Segmentation dimensions modeled include product type, application function, end-user industry, and distribution channel. CAGRs were derived from regression analysis against construction output indices and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated National Construction Code energy efficiency provision adoption curves and TGA enforcement intensity projections.
Sensitivities concentrate around crude oil derivative volatility, Northeast Asian supply disruption, and BIS-equivalent harmonization delays extending certification timelines. Forecasts reflect assumptions regarding state-level environmental licensing acceleration and building information modeling adoption rates in commercial construction. Quarterly review of TGA enforcement actions, Queensland infrastructure project award announcements, and silicone intermediate freight rate indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Epoxy Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Anaerobic Adhesives Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Saudi Arabia Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market