
 Fabric Adhesive Market | 2026-2036
Fabric Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Adhesive Market Analytics
The EU Green Deal is shifting procurement criteria across European textile supply chains, forcing adhesive suppliers to reformulate away from solvent-based systems. Henkel AG & Co. KGaA leverages its European manufacturing footprint to supply certified low-VOC bonding solutions to automotive tier-1 suppliers. H.B. Fuller Company anchors its position through captive resin synthesis capabilities that reduce raw material exposure. Arkema SA competes on specialty acrylic chemistry designed for heat-activated industrial lamination.
Fabric adhesives are polymeric bonding agents formulated from acrylics, polyurethanes, or synthetic rubbers that create flexible, durable joints between textile substrates at temperatures ranging from ambient to 150°C depending on activation method. Water-based acrylic emulsions dominate volume in clothing and home decor applications where regulatory limits on volatile organic compounds constrain solvent alternatives. Pressure-sensitive adhesives lead value generation in automotive interior assembly where film lamination technology enables precise, repeatable bonding of headliner and seat fabrics. Hot melt systems sustain above-average growth in industrial bonding as manufacturers seek elimination of drying stages and reduced energy intensity.
REACH in Europe, EPA VOC regulations in the United States, and China's GB standards on hazardous substance limits collectively constrain formulation freedom while creating competitive advantage for compliant suppliers. ECHA substance-of-very-high-concern listings directly eliminate certain phthalate plasticizers from flexible adhesive grades, redirecting R&D toward bio-based polyol alternatives. Stakeholders must monitor evolving chemical restriction schedules across multiple jurisdictions to anticipate raw material obsolescence and secure first-mover position in next-generation compliant chemistries.
Market Dynamics
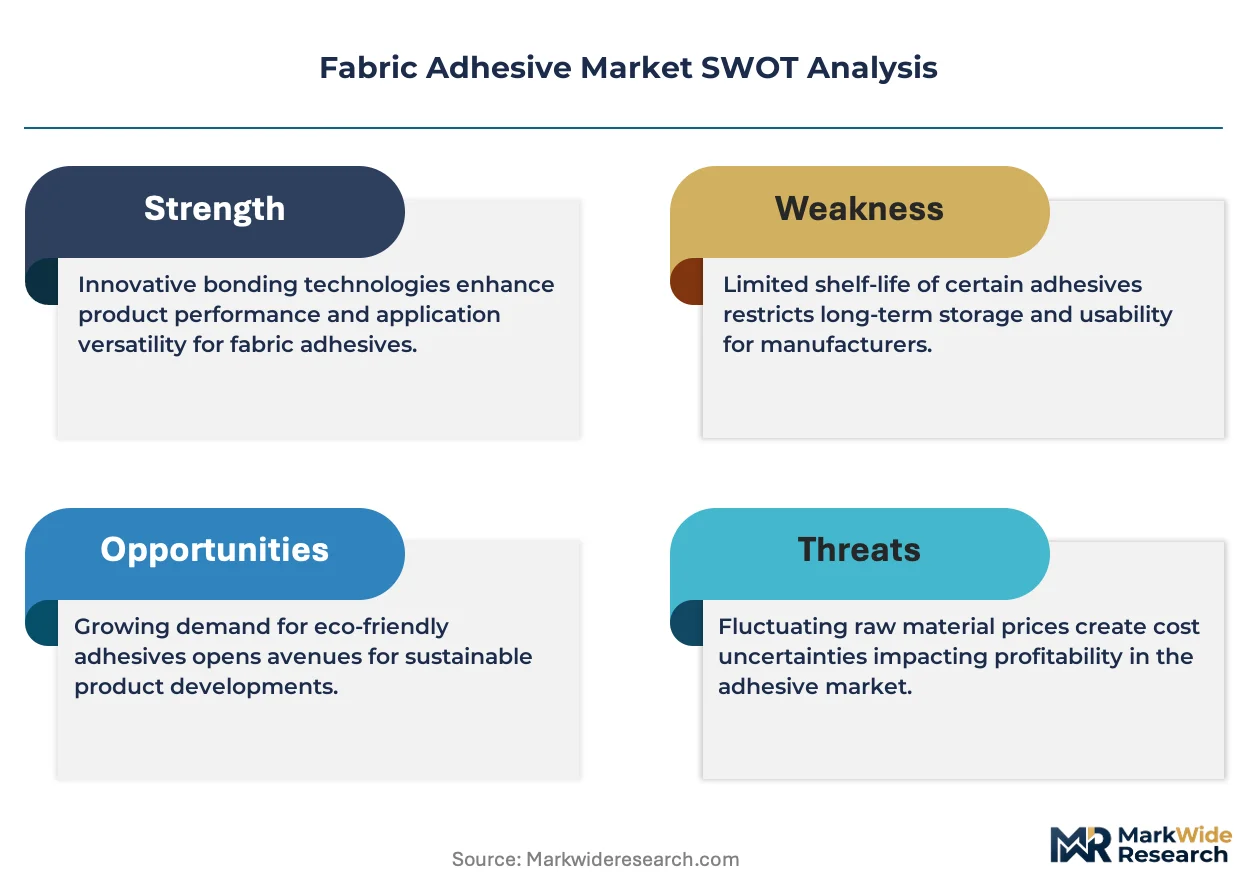
REACH substance-of-very-high-concern listings are systematically eliminating phthalate plasticizers from flexible adhesive grades, forcing formulators toward bio-based polyol alternatives across European textile supply chains. This regulatory compression is reshaping raw material sourcing strategies and R&D allocation priorities industry-wide.
Growth Catalysts
- EU Green Deal procurement criteria:European automotive tier-1 suppliers now mandate certified low-VOC bonding solutions for vehicle interior applications, redirecting specification authority toward compliant adhesive vendors.
- Film lamination technology:Pressure-sensitive adhesive systems enable precise, repeatable bonding of headliner and seat fabrics in automotive assembly, sustaining value generation in interior component manufacturing.
- Zhejiang and Guangdong textile clusters:China's concentrated manufacturing infrastructure generates sustained volume demand for water-based acrylic emulsions in apparel and home décor bonding applications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and polyurethane precursor prices fluctuate with crude oil indices, compressing formulation margins for non-integrated adhesive producers.
- Specialty resin supply concentration:Captive synthesis capabilities at major chemical conglomerates limit third-party access to performance-critical raw materials, constraining mid-tier formulator competitiveness.
- Heat activation temperature floors:Industrial lamination processes requiring sustained temperatures above 120°C restrict substrate compatibility and energy efficiency gains.
Strategic Opportunities
- India technical textile expansion:BIS certification requirements for automotive and medical textile bonding create entry points for compliant adhesive suppliers in underpenetrated subcontinent manufacturing.
- Hot melt system adoption:Elimination of drying stages and reduced energy intensity in industrial bonding applications positions reactive polyurethane hot melts for above-average growth in sustainable manufacturing environments.
- MEE hazardous substance enforcement:China's tightening GB standards on industrial chemical emissions create competitive advantage for water-based formulation specialists with established compliance documentation.
Industry Challenges
- Polymer chemistry specialization:Shortage of formulators trained in rheology control and substrate-specific adhesion science lengthens product development cycles for customized textile bonding solutions.
- Multi-jurisdiction certification timelines:Parallel registration requirements under REACH, EPA VOC regulations, and China's GB standards extend time-to-market for new adhesive grades by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Adhesive Market |
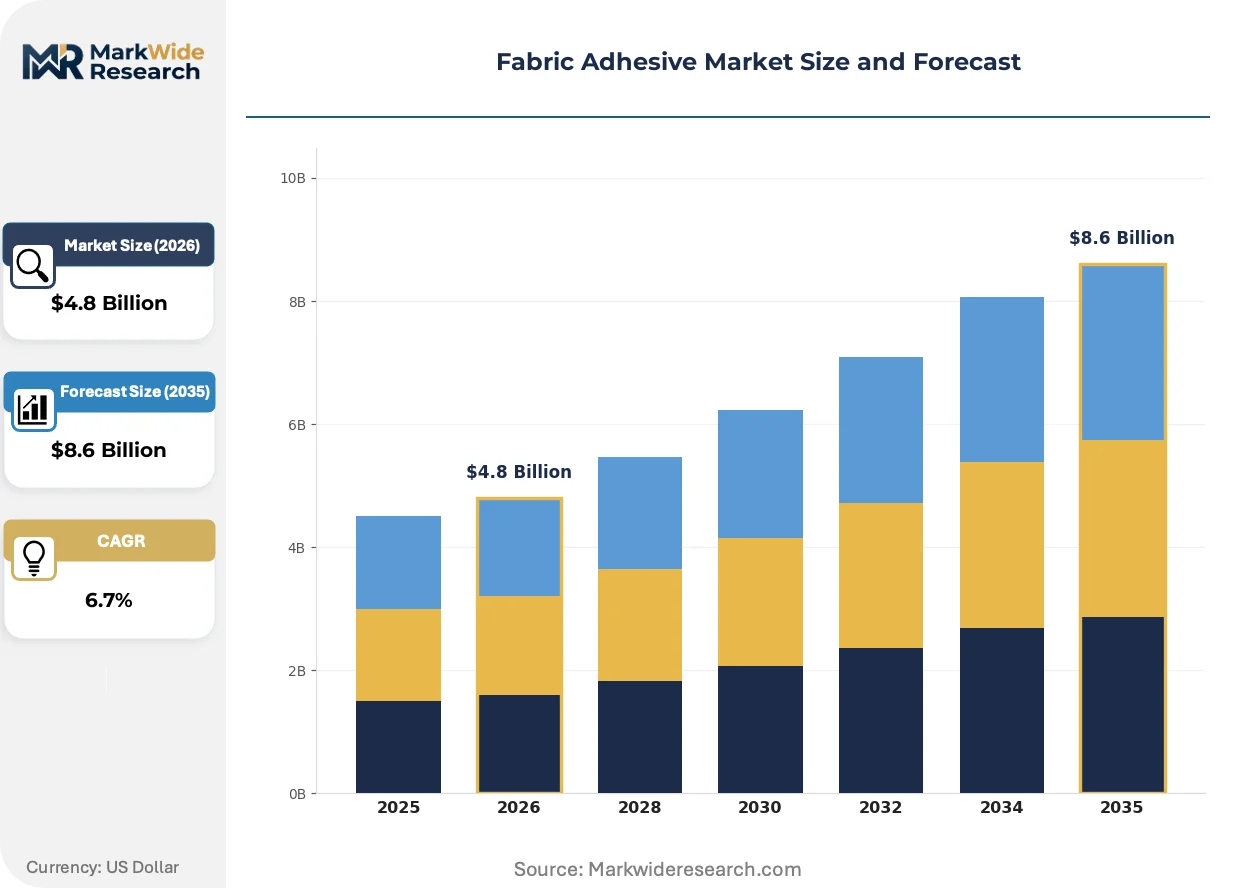
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Water-Based, Solvent-Based, Pressure-Sensitive Application: Clothing, Upholstery, Crafts, Industrial Bonding End User: Fashion Industry, Automotive Sector, Home Decor, Manufacturing Technology: Heat Activation, Cold Bonding, Adhesive Transfer, Film Lamination |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema SA, 3M Company, Sika AG, Pidilite Industries Ltd, Avery Dennison Corporation, Beacon Adhesives, Inc, Aleene’s Premium Glue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Adhesive Market Evolving Landscape
Electrification of industrial heating systems and concurrent tightening of emissions standards are converging to accelerate adoption of low-temperature activation chemistries across textile lamination processes. These pressures are compressing the viable temperature window for adhesive performance while demanding equivalent bond durability.
Reactive polyurethane hot melt technology is electrifying industrial bonding equipment requirements as manufacturers retrofit lamination lines for precise temperature control and rapid thermal cycling. Automotive interior suppliers in Germany and China are adopting these systems at accelerated pace to eliminate solvent drying stages. This technology is compressing energy intensity benchmarks in textile lamination while maintaining structural bond performance under vehicle cabin thermal stress.
REACH Annex XIV authorization requirements are systematically restricting diisocyanate use in polyurethane adhesive formulations, forcing suppliers toward aliphatic alternatives and blocked prepolymer architectures. Industrial consequences include reformulation costs and extended safety data sheet documentation obligations. European automotive and furniture textile laminators are responding by consolidating supplier relationships with REACH-authorized chemical distributors capable of compliant raw material assurance.
Specification authority is migrating from procurement departments to sustainability compliance officers as major apparel brands implement chemical management protocols aligned with ZDHC Manufacturing Restricted Substances List standards. Direct supplier auditing is displacing traditional distributor relationships in premium textile bonding segments. This behavioral shift is most visible in Northern European fashion manufacturing clusters where brand reputation risk drives adhesive selection criteria ahead of unit cost optimization.
Fabric Adhesive Market Segmentation
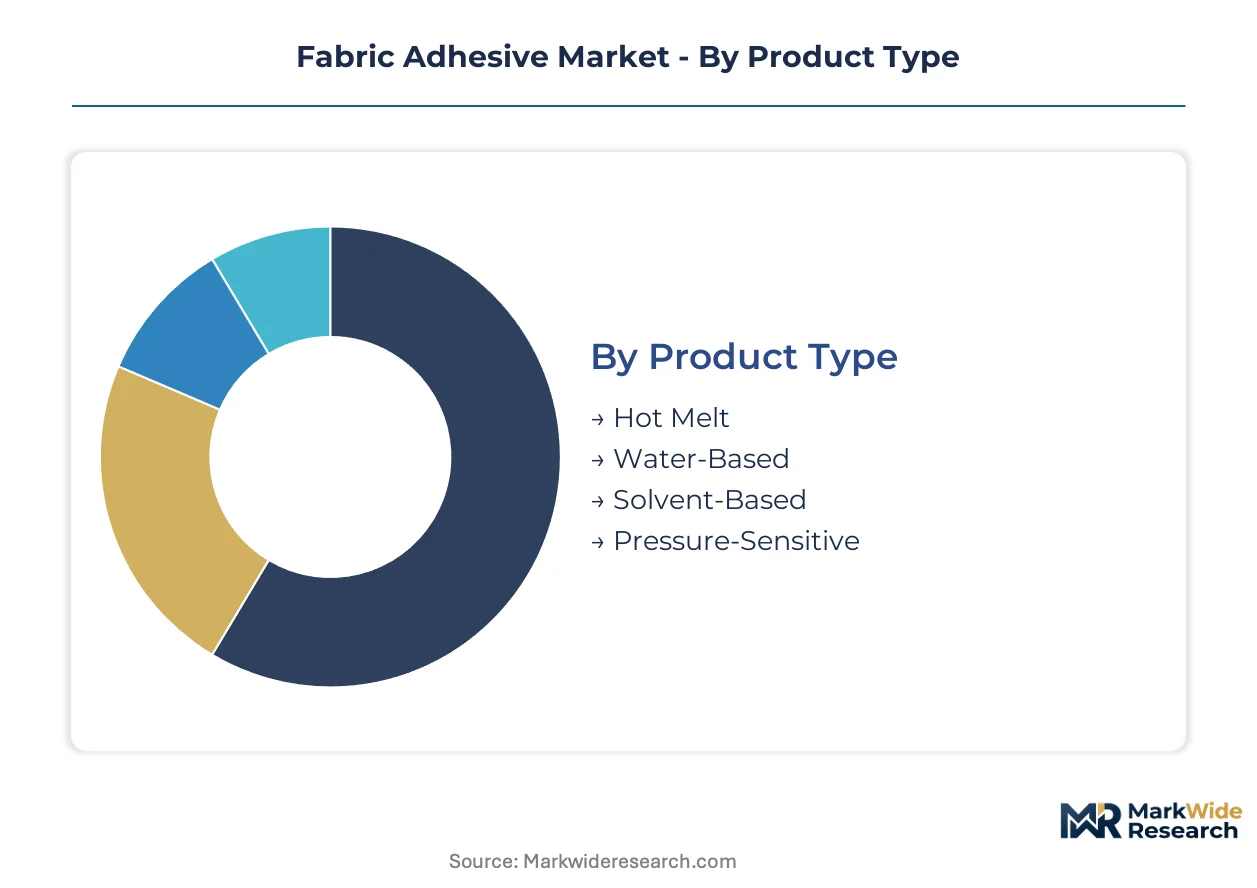
Fabric adhesive segmentation reveals how formulation chemistry and application method determine regulatory exposure, energy intensity, and margin structure across textile bonding value chains. Distinct technical requirements in automotive lamination versus apparel assembly create divergent specification pathways that reshape supplier competitiveness.
Product Type:
Upgrade cycles in textile lamination equipment are accelerating displacement of solvent-dependent systems by water-based and hot melt alternatives that align with electrified heating infrastructure and emissions controls.
- Hot Melt:Reactive polyurethane formulations cure through moisture crosslinking to deliver structural bonds without drying stages. German automotive interior manufacturers are retrofitting lamination lines for these systems to eliminate solvent recovery equipment and compress energy intensity benchmarks under EU Green Deal procurement criteria.
- Water-Based:Acrylic emulsion polymers suspended in aqueous carriers activate at ambient temperatures with volatile organic compound profiles that satisfy EPA VOC regulations and REACH substance restrictions. Zhejiang province textile clusters generate sustained volume demand for these formulations in apparel and home décor applications where regulatory limits constrain solvent alternatives.
- Solvent-Based:Solutions of synthetic rubbers or polyurethanes in organic carriers deliver aggressive tack and rapid bond formation for specialty industrial substrates.
- Pressure-Sensitive:Permanently tacky polymers enable repositionable bonding and film lamination precision in automated assembly environments.
Water-Based sits at the top of the volume ranking, with Hot Melt climbing the fastest.
Application:
Cost tier differentiation separates commodity apparel bonding from specification-driven automotive and industrial segments where certification documentation commands premium positioning.
- Clothing:Water-based acrylics dominate garment construction and embellishment bonding where fast fashion cycle compression demands rapid curing and low-temperature activation to protect delicate synthetic fabrics.
- Industrial Bonding:Technical textile lamination for filtration, medical, and protective equipment requires adhesive systems validated under ISO 10993 biocompatibility and EN 469 thermal protection standards. China's GB standards on hazardous substance limits are tightening qualification requirements for suppliers serving export-oriented manufacturing clusters in Guangdong province.
- Upholstery:Furniture and seating applications balance aesthetic seam concealment with durability under cyclic loading and environmental aging.
- Crafts:Consumer hobby segments prioritize convenience and safety labeling over performance specifications in retail distribution channels.
Industrial Bonding captures the steepest margin expansion trajectory, while Clothing maintains absolute volume leadership across the analysis window.
End User:
Customer type concentration in automotive tier-1 supply chains concentrates specification authority among a limited cohort of compliance-certified adhesive vendors.
- Automotive Sector:Headliner, seat fabric, and interior trim lamination demands pressure-sensitive and hot melt systems capable of withstanding thermal cycling between -40°C and 80°C cabin environments. ECHA diisocyanate restrictions under REACH Annex XIV are forcing reformulation toward aliphatic polyurethane architectures and extended safety data sheet documentation.
- Fashion Industry:Northern European apparel brands are implementing ZDHC Manufacturing Restricted Substances List protocols that displace traditional distributor relationships with direct supplier auditing and chemical management certification requirements.
- Home Decor:Curtain, drapery, and soft furnishing manufacturers prioritize color stability and UV resistance in adhesive selection criteria.
- Manufacturing:Broad industrial textile bonding spans filtration media, geotextiles, and composite reinforcement applications with substrate-specific adhesion science requirements.
Automotive Sector leads value generation per kilogram, with Fashion Industry expanding most quickly as sustainability compliance protocols proliferate across brand supply chains.
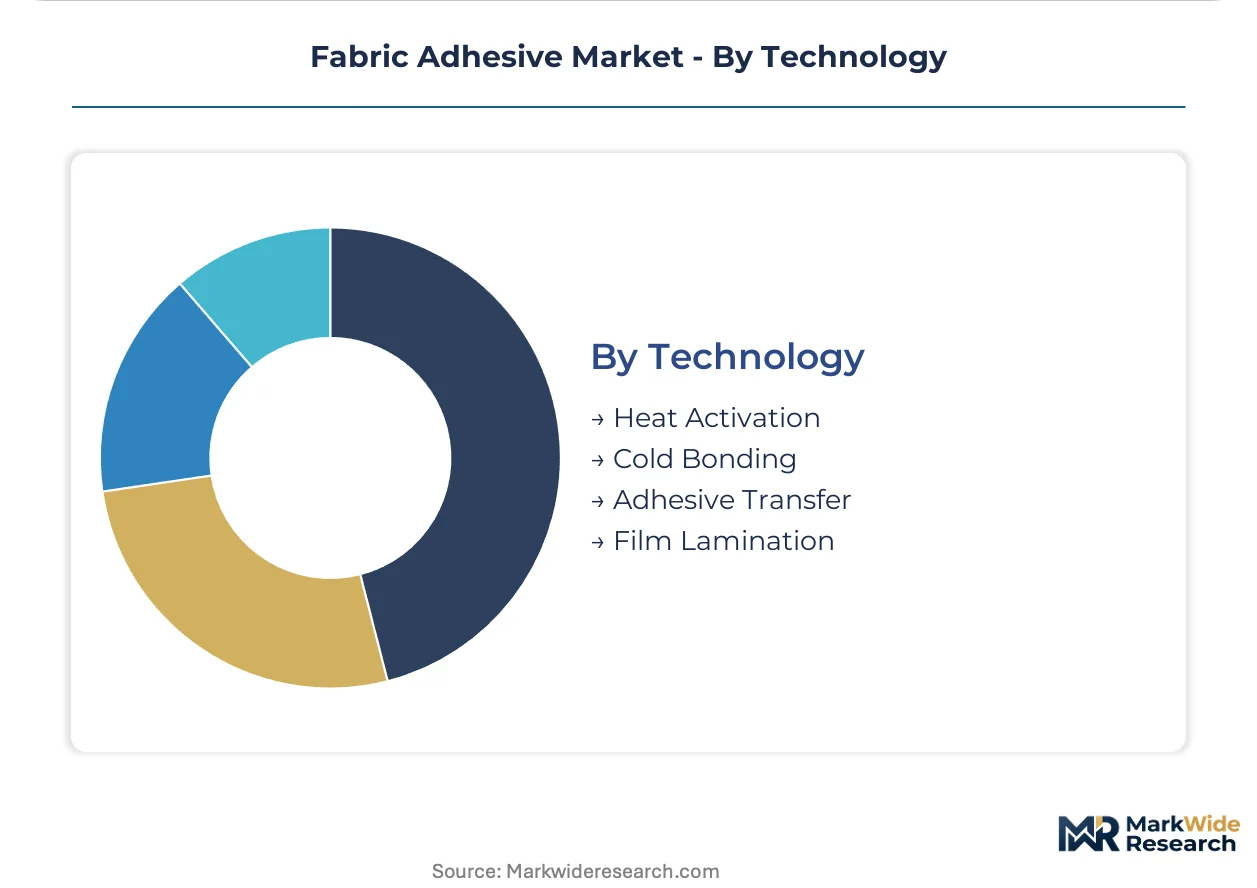
Technology:
Supply concentration in film lamination equipment manufacturing shapes technology adoption patterns among textile converters seeking precision and repeatability.
- Film Lamination:Continuous roll-to-roll adhesive transfer enables micron-level thickness control and automated assembly integration for automotive interior components. German equipment manufacturers dominate precision lamination line supply, creating technology lock-in for adhesive formulations optimized to their thermal profile specifications.
- Heat Activation:Hot melt and reactive systems require sustained temperature exposure between 120°C and 150°C, restricting substrate compatibility to thermally stable materials while delivering immediate handling strength.
- Cold Bonding:Ambient-cure water-based and pressure-sensitive systems expand substrate compatibility to heat-sensitive synthetics and coated fabrics.
- Adhesive Transfer:Double-sided tape and transfer film formats enable clean, metered application in assembly environments where liquid dispensing creates quality variability.
Film Lamination dominates specification authority in premium segments, with Heat Activation gaining share fastest as electrified industrial heating retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive formulators cluster in Germany's industrial corridor, China's coastal manufacturing belts, and the US Great Lakes chemical processing region, anchoring regional supply capabilities to end-use demand density.
United States
Automotive interior assembly in Michigan and Ohio sustains demand for pressure-sensitive film lamination systems. EPA VOC regulations under the Clean Air Act constrain solvent-based formulation deployment across Great Lakes manufacturing. Detroit-area tier-1 suppliers are retrofitting lamination lines for hot melt compatibility to meet OEM sustainability scorecards.
Germany
Technical textile laminators in Bavaria and Baden-Württemberg drive specification authority for low-VOC bonding solutions. ECHA REACH Annex XIV diisocyanate restrictions are forcing aliphatic polyurethane adoption across automotive supply chains. Stuttgart-headquartered OEMs are consolidating supplier relationships with REACH-authorized chemical distributors.
China
Zhejiang and Guangdong province textile clusters generate sustained volume demand for water-based acrylic emulsions in apparel and home décor applications. MEE enforcement of GB standards on hazardous substance limits is tightening qualification requirements for export-oriented manufacturers. Shenzhen-based converters are migrating from solvent systems to comply with brand chemical management protocols.
India
Technical textile expansion in Maharashtra and Gujarat creates entry points for compliant adhesive suppliers in automotive and medical bonding segments. BIS certification requirements for industrial chemical formulations are elevating documentation burdens for imported raw materials. Surat's synthetic fabric processing hub is attracting water-based formulation specialists with established compliance portfolios.
Japan
Precision lamination equipment manufacturers in Nagoya and Osaka shape technology adoption patterns among regional textile converters. METI energy efficiency standards are accelerating electrification of industrial heating systems for adhesive activation. Aichi Prefecture automotive suppliers are specifying reactive hot melt systems to eliminate solvent recovery infrastructure.
Fabric Adhesive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and application equipment domains. The vendor base separates into integrated chemical conglomerates with captive resin synthesis, mid-tier formulators dependent on third-party raw material supply, and specialized equipment-technology bundlers. Three archetypes dominate: REACH-authorized European suppliers, Asia-Pacific volume producers, and North American automotive specification holders. Competitive dynamics center on M&A for geographic coverage and strategic partnerships for film lamination technology access.
Within the European REACH-compliant tier, Henkel AG & Co. KGaA and Arkema SA exemplify formulation specialists with established authorization documentation. H.B. Fuller Company occupies a position among North American players with automotive interior specification authority. These three represent divergent strategic postures: European regulatory compliance anchoring, captive resin synthesis capabilities, and automotive tier-1 relationship depth respectively.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema SA |
| 3M Company |
| Sika AG |
| Pidilite Industries Ltd |
| Avery Dennison Corporation |
| Beacon Adhesives, Inc |
| Aleene's Premium Glue |
| Others |
Value Network & Pricing Analysis
Automotive tier-1 suppliers in Germany and China concentrate specification authority for fabric adhesives, anchoring a contract-based pricing structure where multi-year offtake agreements lock in volume commitments and certification premiums. This buyer concentration compresses margin negotiation leverage for non-integrated formulators while rewarding REACH-authorized vendors with pricing stability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and captive resin synthesis capabilities. Premium tiers command valuation premiums for ECHA-authorized aliphatic polyurethane formulations and documented compliance with ZDHC Manufacturing Restricted Substances List protocols. Cost compression in standard-grade water-based acrylics is intensifying because Zhejiang province textile clusters consolidate procurement volumes among fewer qualified suppliers. Price sensitivity peaks among apparel converters in Guangdong province, while automotive interior laminators in Stuttgart and Detroit exhibit lowest sensitivity due to specification lock-in and thermal performance requirements.
Supply Chain Analysis
Reverse logistics flows for solvent recovery equipment and spent adhesive containers create secondary material loops that German automotive suppliers monetize through certified waste-to-energy pathways. Raw material sourcing draws from petrochemical feedstocks concentrated in Germany's industrial corridor, China's coastal chemical processing zones, and US Gulf Coast monomer production. Acrylic monomer and polyurethane precursor supply rests on crude oil index volatility, exposing non-integrated formulators to margin compression. Single-source vulnerability concentrates in specialty aliphatic diisocyanate production authorized under REACH Annex XIV. Distribution runs through authorized chemical distributors with REACH documentation capabilities, particularly for European automotive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fabric adhesive market compounds steadily as regulatory compliance protocols proliferate across automotive and apparel supply chains, embedding recurring specification authority into vendor relationships.
For Market Incumbents: Anchor market position through backward integration into captive resin synthesis and consolidation of REACH-authorized raw material supply relationships. Defend against emerging water-based formulation specialists by accelerating hot melt technology bundling with German precision lamination equipment manufacturers. Prioritize certification investment in ZDHC-compliant chemical management systems for Northern European fashion brand supply chains. For New Entrants and Emerging Players: Begin with technical textile bonding applications in India's Maharashtra and Gujarat industrial corridors, where BIS certification requirements create documentation barriers that favor compliant specialists over commodity importers. Target automotive medical textile laminators seeking ISO 10993 biocompatibility validation as the most penetrable segment. Pursue direct supplier auditing relationships with sustainability compliance officers at premium apparel brands as the primary go-to-market angle. For Investors and Strategic Acquirers: Chemical conglomerates with captive resin synthesis capabilities are the most active acquirer in this space, seeking geographic coverage in Asia-Pacific textile manufacturing clusters. The market exhibits long-term viability as a 5-10 year compounder driven by electrification of industrial heating infrastructure and regulatory compression on solvent-based alternatives. Monitor ECHA substance-of-very-high-concern listing announcements as the critical inflection signal for raw material obsolescence and reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of acrylic monomers insulates H.B. Fuller from petrochemical volatility. |
| REACH Annex XIV Authorization Investment | Aliphatic polyurethane certification locks Henkel into German automotive supply chains. |
| Hot Melt Equipment Bundling Partnership | Technology integration with Bavarian lamination line manufacturers accelerates specification authority. |
| ZDHC Compliance Certification Program | Chemical management protocols open direct supplier relationships with Northern European fashion brands. |
| India Technical Textile Market Entry | BIS certification capabilities position compliant suppliers for Maharashtra automotive bonding demand. |
Research Methodology
Bottom-up textile end-use modeling reconciled against top-down adhesive formulation tracking forms the analytical core of this study. Primary interviews with technical textile plant managers, automotive tier-1 procurement leads, chemical distribution channel partners, and ECHA regulatory affairs specialists were combined with secondary validation from REACH substance restriction databases, EPA VOC regulatory filings, China MEE GB standard publications, and customs trade data on acrylic emulsion imports. Triangulation between demand-side consumption patterns and supply-side production capacity ensures cross-verified market sizing.
Input-output matrices map formulation chemistry segments against application methods and regional regulatory clusters across the projection horizon. Segmentation dimensions modeled include product type, activation technology, end-use industry, and regional compliance framework. CAGRs were derived from elasticity-adjusted demand projections incorporating electrification retrofit cycles in industrial lamination equipment and evolving chemical restriction schedules. Industry-specific forecast inputs encompass automotive interior content per vehicle trends and ZDHC protocol adoption rates among apparel brand supply chains.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock price shocks, unilateral regulatory acceleration beyond published ECHA restriction timelines, and substitution by mechanical fastening technologies in select automotive applications. Forecasts reflect documented assumptions about compliance transition speeds and equipment replacement cycles. Practitioners should monitor ECHA SVHC listing announcements, MEE enforcement intensity in Guangdong province, and German automotive OEM sustainability scorecard revisions for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Brazil Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Waterproofing Admixture Market