
 High Temperature Adhesives and Sealants Market | 2026-2036
High Temperature Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Adhesives and Sealants Market Foresight
Aerospace assembly is expanding its share of high-temperature adhesive consumption as next-generation engine programs and thermal protection systems raise performance specifications. Henkel leverages its European formulation heritage to supply qualified materials for turbine manufacturing. Dow sustains technology leadership in silicone chemistry for extreme-heat environments. Momentive Performance Materials specializes in custom thermal management solutions for propulsion OEMs.
High temperature adhesives and sealants are formulated to maintain structural integrity and bonding performance above 150 degrees Celsius, typically incorporating epoxy, silicone, or hybrid resin systems with ceramic fillers and thermal stabilizers. Their primary purpose is to join, seal, or protect components in environments where conventional organic adhesives degrade through thermal oxidation or creep. Epoxy formulations dominate current volume due to established qualification protocols in automotive and industrial equipment. Silicone segments capture premium margin pools in aerospace and electronics where flexibility across thermal cycling is mandatory. Polyurethane and acrylic categories occupy narrower niches in lower-temperature industrial sealing and rapid-assembly electronics applications.
The EPA in the United States enforces volatile organic compound emission limits that constrain solvent-based adhesive formulations, while REACH in Europe mandates disclosure and restriction of hazardous substances in chemical products. These frameworks compel manufacturers to reformulate toward waterborne, hot-melt, and 100-percent-solid systems that meet both performance and compliance thresholds. Stakeholders must monitor evolving substance restrictions and thermal qualification standards to preserve market access and avoid portfolio obsolescence.
Market Dynamics
Electric powertrain thermal management requirements are forcing automotive OEMs to replace mechanical fasteners with bonded assemblies rated above 180°C, redirecting specification authority from chassis engineers to materials scientists.
Growth Catalysts
- REACH substance restrictions:European chemical disclosure mandates are accelerating reformulation investments toward ceramic-filled silicones that eliminate hazardous stabilizers while maintaining thermal ratings.
- Aerospace propulsion OEMs:Next-generation turbine programs specify flexible thermal barrier coatings that bond directly to superalloy substrates, expanding addressable application scope beyond traditional gasket replacement.
- German automotive cluster:Battery pack assembly lines in Stuttgart and Munich are standardizing two-part epoxy systems for module-to-housing attachment, creating qualified supplier preference effects.
Market Restraints
- Specialty ceramic filler supply:Boron nitride and alumina precursor availability concentrates among Chinese raw material processors, exposing formulators to export quota volatility.
- EPA VOC enforcement:Solvent-based silicone dispersions face compliance cost escalation in US manufacturing facilities, compressing margin pools for mid-volume producers.
- Curing equipment capital intensity:Industrial ovens and UV-LED arrays required for high-temperature adhesive activation demand seven-figure facility investments that deter market entry.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for domestic electronics manufacturing are attracting adhesive formulators to establish localized compounding for smartphone and server thermal interface materials.
- Solid-state battery assembly:Dry electrode stacking processes eliminate wet slurry coating, creating demand for precision-applied thermal interface pads that bond under compression rather than cure.
- EU Green Deal procurement:Public infrastructure projects now embed embodied carbon scoring, favoring bio-based epoxy hardeners and recycled ceramic fillers in civil engineering specifications.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise combining silicone rheology with ceramic surface chemistry concentrates among retiring specialists at German and Japanese heritage firms.
- Dual qualification timelines:Aerospace OEMs require 18-24 month thermal aging validation protocols that lock working capital in inventory before revenue recognition.
- Legacy ERP integration:Batch traceability requirements for REACH compliance conflict with existing manufacturing execution systems at mid-tier compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Adhesives and Sealants Market |
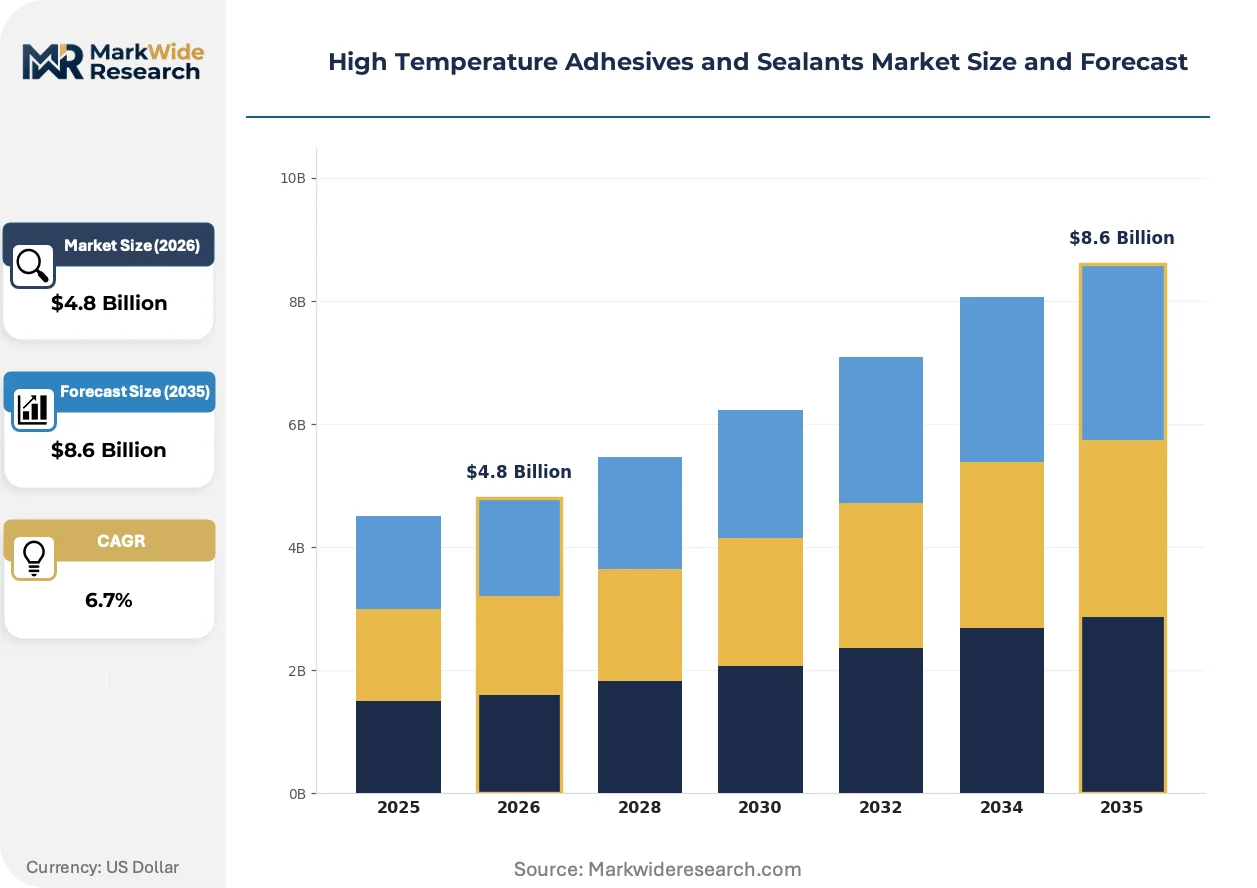
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Acrylic Application: Aerospace, Automotive, Electronics, Industrial End User: Manufacturers, Contractors, Distributors, OEMs Form: Liquid, Paste, Film, Tape |
| Companies Covered | 3M, Bostik, Avery Dennison Corporation, PPG Industries, Henkel, H.B. Fuller Company, Sika, Momentive Performance Materials, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Adhesives and Sealants Market Shifts & Advancements
Bio-ceramic hybrid formulations and in-situ curing monitoring are compressing development cycles while regulatory carbon accounting is rewiring procurement evaluation criteria across industrial buyer segments.
Additive manufacturing of ceramic-filled thermoset pastes is absorbing tooling costs from low-volume aerospace component bonding. Propulsion OEMs at Rolls-Royce and GE Aviation are qualifying direct-write deposition for turbine vane repair applications. This capability is absorbing traditional subtractive machining steps in remanufacturing workflows, shortening turnaround times for engine overhaul facilities.
REACH Annex XIV authorization requirements are restricting bisphenol-A derivatives in epoxy hardener systems used above 150°C. Formulators at Henkel and Dow are accelerating aliphatic amine and anhydride substitutions through requalification pipelines. European automotive electronics suppliers face the most compressed compliance timelines, with some Tier-1s advancing PFAS-free specifications ahead of regulatory mandates.
Specification authority is migrating from purchasing departments to thermal management engineering teams within OEM organizations. Battery pack designers at Volkswagen and BMW now issue bonded joint performance requirements directly to adhesive suppliers, bypassing traditional fastener category managers. This pattern concentrates most visibly in German and South Korean electric vehicle manufacturing clusters, where thermal runaway containment standards exceed baseline regulatory thresholds.
High Temperature Adhesives and Sealants Market Segmentation
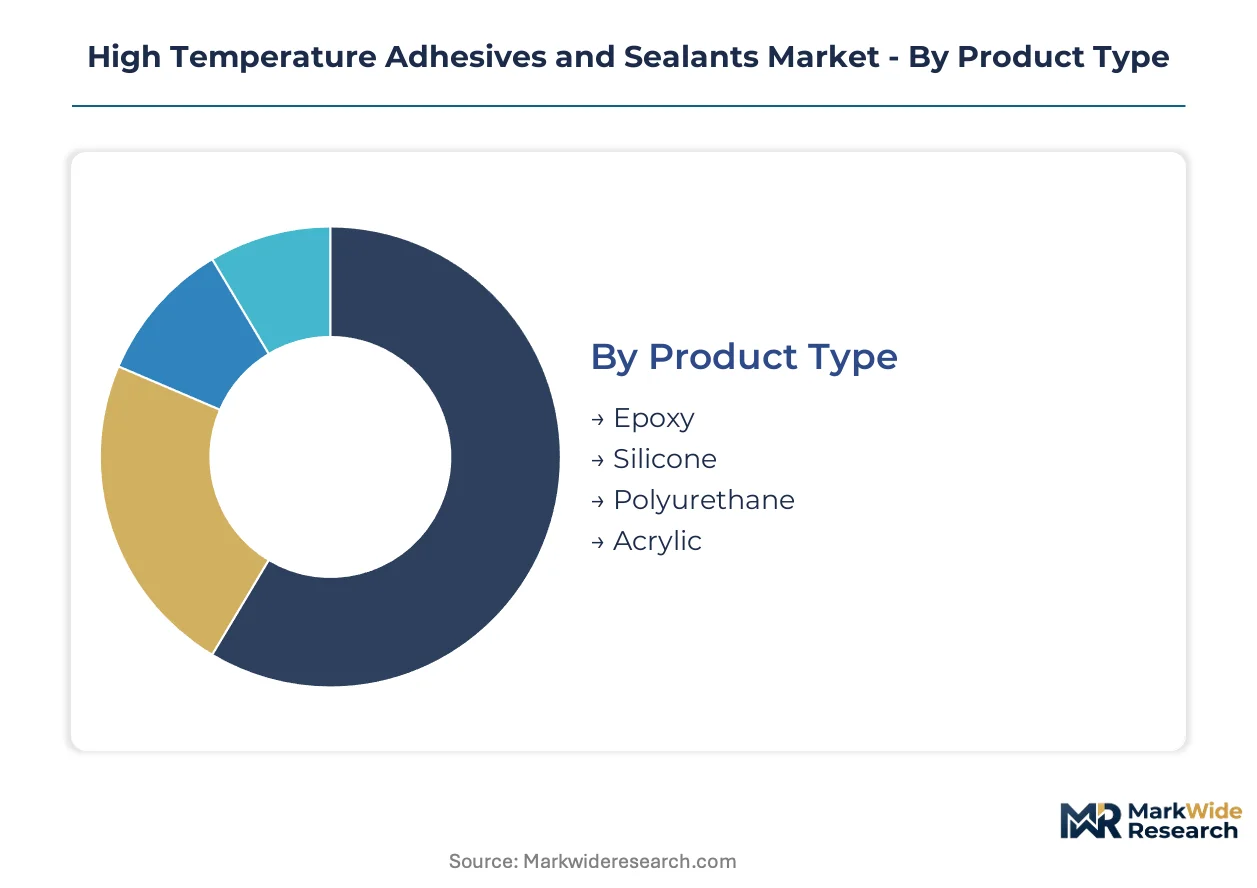
High temperature adhesives and sealants serve divergent thermal, mechanical, and regulatory requirements across end-use industries. Segmentation reveals how formulation chemistry, application method, and supply chain position determine margin capture and specification authority.
Product Type:
Specification authority flows from thermal performance thresholds and qualification heritage.
- Epoxy:Two-part thermoset systems dominate automotive module bonding and industrial equipment assembly through established OEM qualification protocols. Volume concentrates in German and South Korean battery pack manufacturing where thermal runaway containment standards exceed baseline regulatory thresholds.
- Silicone:Flexible polysiloxane networks maintain elastomeric properties across thermal cycling from -50°C to 300°C. Aerospace propulsion OEMs at Rolls-Royce and GE Aviation specify addition-cure silicones for turbine vane thermal barrier coatings.
- Polyurethane:Isocyanate-cured systems occupy lower-temperature industrial sealing below 150°C where cost sensitivity outweighs thermal ceiling requirements.
- Acrylic:Rapid UV-cure formulations serve electronics assembly lines demanding tack-free handling within seconds of exposure.
Volume sits with epoxy systems; growth tilts toward silicone segments as aerospace thermal management specifications expand.
Application:
End-use thermal environments dictate formulation investment and regulatory exposure.
- Aerospace:Engine nacelle and thermal protection system bonding requires ceramic-filled silicones qualified to FAA airworthiness standards. Next-generation turbine programs at Safran and Pratt & Whitney specify flexible thermal barrier coatings that bond directly to superalloy substrates.
- Automotive:Electric powertrain thermal management requirements are displacing mechanical fasteners with bonded assemblies rated above 180°C. Battery pack designers at Volkswagen and BMW now issue bonded joint performance requirements directly to adhesive suppliers.
- Electronics:Server and smartphone thermal interface materials demand thin-film consistency and dielectric stability. India's PLI scheme for domestic electronics manufacturing is attracting localized compounding capacity.
- Industrial:Furnace linings, exhaust systems, and process equipment maintenance consume high-volume epoxy and silicone formulations where EPA VOC enforcement constrains solvent-based options.
Revenue concentrates in automotive applications; expansion accelerates most quickly in aerospace as propulsion OEMs absorb bonding steps into remanufacturing workflows.
End User:
Procurement authority varies with technical specification depth and inventory risk tolerance.
- Manufacturers:Tier-1 component producers maintain qualified supplier lists with 18-24 month thermal aging validation protocols that lock working capital before revenue recognition.
- Contractors:Installation and maintenance service providers purchase through distribution with shorter lead times and lower volume commitments.
- Distributors:Regional chemical distributors aggregate demand from mid-volume industrial accounts, facing margin compression from REACH batch traceability compliance costs.
- OEMs:Original equipment manufacturers concentrate specification authority as thermal management engineering teams bypass traditional fastener category managers.
Specification control rests with OEMs; transaction volume flows through distributors serving fragmented industrial maintenance demand.
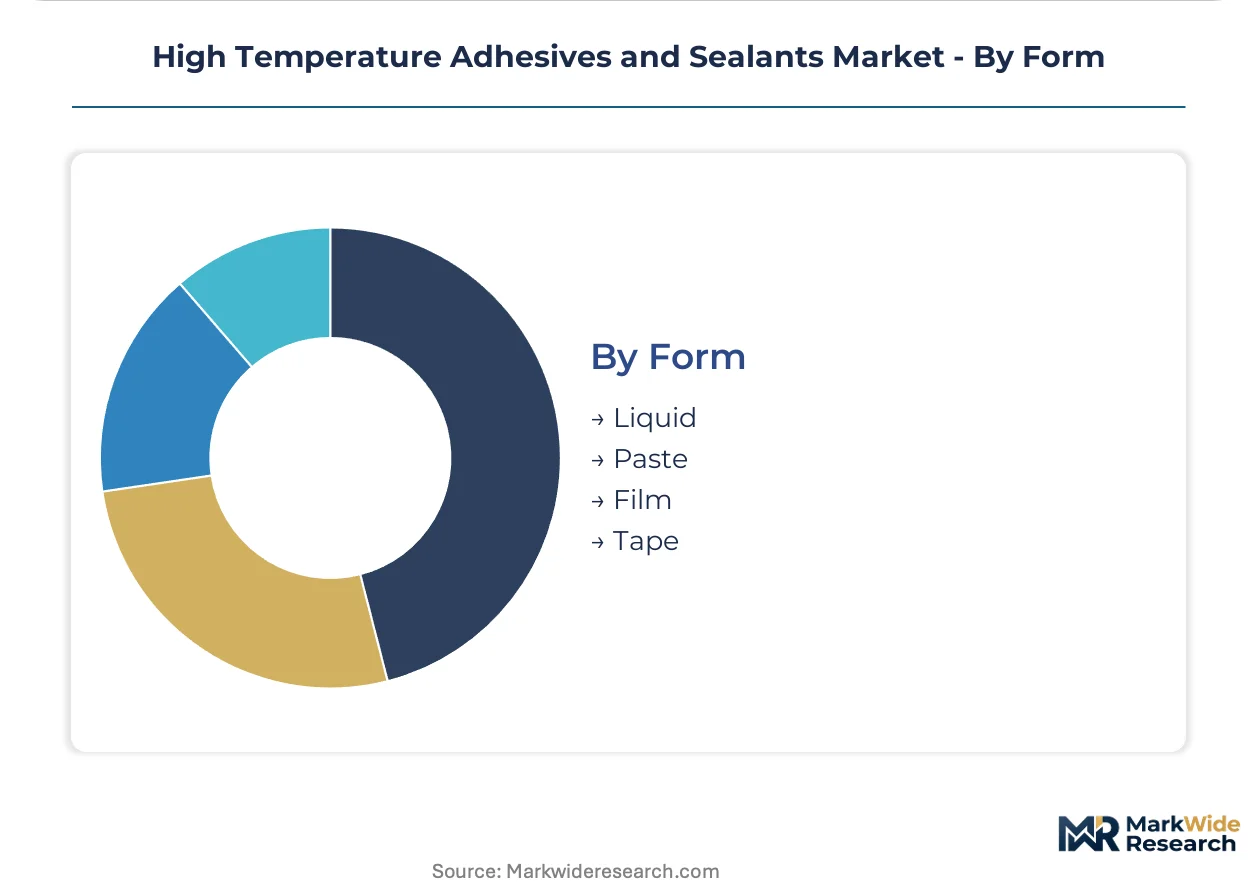
Form:
Application equipment and joint geometry determine format selection and margin structure.
- Liquid:Low-viscosity dispersions enable automated meter-mix equipment in high-volume automotive assembly. REACH substance restrictions on bisphenol-A derivatives are accelerating aliphatic amine hardener substitutions.
- Paste:Thixotropic formulations maintain position on vertical surfaces during cure, serving aerospace manual repair applications and industrial equipment field service.
- Film:Pre-cast supported and unsupported films deliver consistent bondline thickness for electronics thermal interface pads. Solid-state battery dry electrode stacking processes are creating demand for precision-applied thermal interface pads that bond under compression.
- Tape:Pressure-sensitive and heat-activated tape formats serve rapid-assembly electronics and temporary fixturing in composite manufacturing.
Shipments skew toward liquid formats; film segments gain share fastest as electronics miniaturization demands precise bondline control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Asia-Pacific and Europe are concentrating high-temperature adhesive manufacturing through tax abatements and streamlined customs procedures. These zones attract formulators seeking proximity to automotive and electronics OEMs while reducing regulatory compliance overhead. The geographic footprint spans mature industrial clusters and emerging production hubs.
United States
EPA VOC enforcement is accelerating reformulation investments toward waterborne and hot-melt systems. The FAA maintains stringent airworthiness qualification protocols for aerospace bonding materials. Manufacturing concentrates in the Ohio-Indiana automotive corridor and the Pacific Northwest electronics cluster near Seattle.
Germany
REACH Annex XIV restrictions on bisphenol-A derivatives are forcing epoxy hardener substitutions in automotive electronics. The KBA enforces thermal management standards for electric powertrain assemblies. Stuttgart and Munich battery pack facilities are standardizing two-part epoxy systems for module-to-housing attachment.
China
MIIT dual carbon goals are pressuring industrial adhesive producers to eliminate solvent-based formulations. GB standards govern ceramic filler content in high-temperature sealants. Yangtze River Delta chemical parks host concentrated silicone compounding capacity serving domestic aerospace and EV manufacturers.
India
PLI scheme incentives for domestic electronics manufacturing are attracting adhesive formulators to establish localized compounding operations. BIS certification requirements govern thermal interface material imports. Karnataka and Tamil Nadu smartphone assembly lines are absorbing precision-applied thermal pads for server and mobile device production.
Japan
METI industrial decarbonization targets are reshaping procurement criteria for high-temperature bonding systems. JIS standards maintain qualification barriers for automotive and electronics applications. Nagoya-area propulsion OEMs specify ceramic-filled silicones for next-generation turbine thermal barrier coatings.
High Temperature Adhesives and Sealants Market Competitive Landscape
Top-tier vendors anchor specification authority through OEM qualification heritage, while mid-tier compounders compete on reformulation speed and regional compliance expertise. The market structure tilts toward consolidation in aerospace segments and fragmentation in industrial maintenance applications. Three archetypes dominate: diversified chemical conglomerates with silicone chemistry depth, specialty adhesive pure-plays with automotive qualification pipelines, and regional compounders serving cost-sensitive industrial accounts. Competitive moves center on strategic partnerships with battery OEMs and capacity expansion into Indian and Southeast Asian manufacturing zones.
Among diversified chemical conglomerates, 3M, Henkel, and Dow occupy positions defined by formulation breadth and thermal qualification heritage. These entities exemplify the integrated archetype spanning epoxy, silicone, and hybrid resin platforms. Their market presence reflects decades of OEM specification accumulation rather than discrete competitive actions. Regional pure-plays and specialized compounders sit within narrower application niches, competing through compliance agility and customized technical service.
| Leading Market Players |
|---|
| 3M |
| Bostik |
| Avery Dennison Corporation |
| PPG Industries |
| Henkel |
| H.B. Fuller Company |
| Sika |
| Momentive Performance Materials |
| Dow |
| Others |
Supply & Pricing Matrix
Boron nitride spot indices cascade through three pricing tiers as formulators pass ceramic filler volatility down to automotive OEMs, aerospace propulsion manufacturers, and industrial maintenance buyers with divergent volume commitments and qualification timelines.
Pricing Analysis
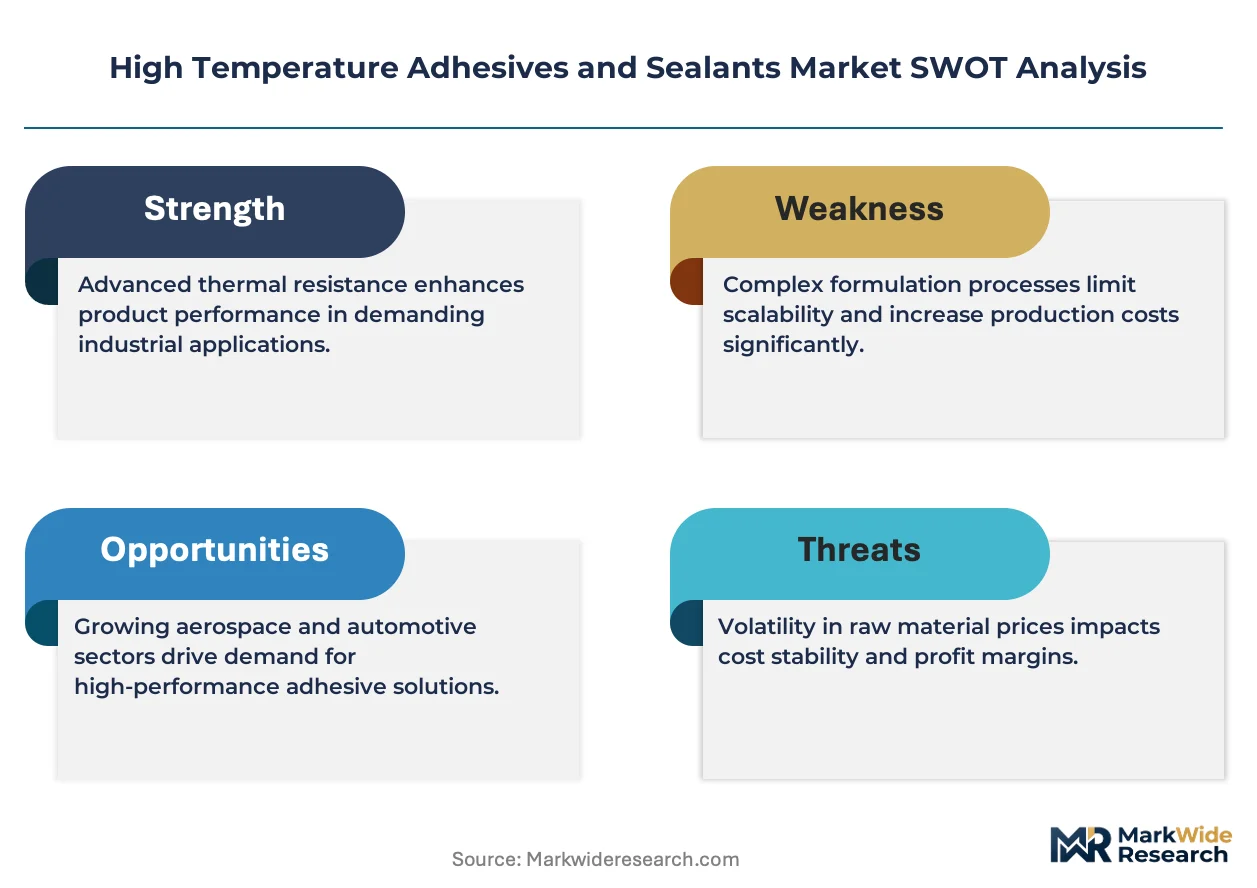
Lead-time compression commands premium positioning as battery pack designers at Volkswagen and BMW accept elevated pricing for qualified two-part epoxy systems deliverable within eight weeks versus standard twenty-four-week thermal aging protocols. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified silicones from automotive module epoxies and unqualified industrial maintenance formulations. Cost compression in mid-volume solvent-based silicone segments is intensifying because EPA VOC enforcement escalates compliance expenditure at US manufacturing facilities. Tier-1 automotive suppliers exhibit lowest price sensitivity due to thermal runaway containment liability exposure, while industrial maintenance contractors purchasing through distribution channels drive hardest bargain terms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart and Munich battery pack facilities, while regional chemical distributors aggregate fragmented industrial maintenance procurement across smaller volume accounts. Raw material supply concentrates among Chinese boron nitride processors, German specialty chemical manufacturers, and Japanese silicone monomer producers. Formulation draws from alumina precursors, ceramic fillers, and thermal stabilizers with concentrated upstream exposure to export quota volatility. Single-source vulnerability in boron nitride precursor supply creates structural risk for European formulators dependent on Yangtze River Delta chemical park output. Distribution runs through qualified supplier lists at Tier-1 component producers and spot purchasing through regional distributors serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV substance restrictions erect a cost-of-compliance moat that rewards incumbents with requalification infrastructure while screening out undercapitalized entrants lacking eighteen-month thermal aging validation capabilities.
For Market Incumbents: Lock in specification authority at German and South Korean battery OEMs through accelerated aliphatic amine hardener substitutions ahead of bisphenol-A derivative restrictions. Deepen backward integration into ceramic filler supply through offtake agreements with Yangtze River Delta processors to neutralize export quota volatility threatening margin stability at mid-volume competitors. For New Entrants and Emerging Players: India's PLI scheme for domestic electronics manufacturing opens a window for localized thermal interface material compounding serving Karnataka and Tamil Nadu smartphone assembly lines. Target precision-applied film formats for solid-state battery dry electrode stacking processes where compression-bonding thermal pads bypass incumbent curing equipment advantages. Lead with REACH batch traceability compliance as differentiated service capability against legacy ERP-constrained mid-tier compounders. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty adhesive pure-plays with automotive qualification pipelines in Germany and South Korea where thermal management engineering teams now bypass traditional fastener category managers. Long-term viability centers on formulation expertise combining silicone rheology with ceramic surface chemistry concentrated among retiring specialists at heritage firms. Watch for dual qualification timeline compression at aerospace OEMs as signal of working capital efficiency inflection enabling faster revenue recognition cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Fillers | Captive boron nitride supply from Chinese processors neutralizes export quota exposure for European formulators. |
| Localized Compounding in India | PLI scheme incentives attract adhesive capacity to Karnataka and Tamil Nadu electronics manufacturing zones. |
| Aliphatic Amine Hardener Substitution | REACH Annex XIV compliance ahead of bisphenol-A restrictions preserves market access for German automotive suppliers. |
| Direct-Write Deposition Qualification | Rolls-Royce and GE Aviation turbine vane repair applications absorb traditional subtractive machining steps. |
| PFAS-Free Specification Advancement | Tier-1 automotive electronics suppliers accelerate compliance timelines ahead of regulatory mandates. |
Research Methodology
Multi-period observation of ceramic filler price indices, REACH substance restriction timelines, and aerospace OEM thermal aging protocols anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, Tier-1 automotive procurement leads, battery pack thermal management engineers, and regional chemical distribution channel partners. Secondary validation drew from ECHA restriction proposals, EPA VOC enforcement disclosures, SEC filings of diversified chemical conglomerates, and customs trade data on boron nitride and alumina precursor flows. Bottom-up segment sizing triangulated against top-down chemical industry production estimates across the analysis window.
Input-output matrices modeled volume and value trajectories across product type, application, end user, and form dimensions, with additional layering by regional production cluster and thermal performance tier. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion patterns throughout the forecast period. Industry-specific forecast inputs included electric vehicle battery pack production schedules at German OEMs and next-generation turbine program timelines at aerospace propulsion manufacturers.
The model assumes a particular technology adoption path for solid-state battery assembly; alternative pathways for dry electrode stacking would alter the outlook for precision-applied thermal interface pad demand. Forecasts reflect base-case assumptions regarding REACH enforcement intensity and ceramic filler supply continuity that alternative scenarios could revise substantially. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Fabric Adhesive Market