
 Die Cut Adhesive Market | 2026-2036
Die Cut Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cut Adhesive Market Analytics
Automotive OEMs is reorganizing procurement priorities around lightweight bonding solutions that replace mechanical fasteners. Henkel leverages its European formulation centers to supply die-cut acrylic tapes with thermal management properties. 3M sustains technology leadership through proprietary adhesive polymer architectures optimized for electronics miniaturization. Sika anchors construction-adjacent demand with waterproofing-grade die-cut gaskets that compete on durability metrics.
Die cut adhesives are pressure-sensitive materials engineered to precise geometries via rotary or flat-bed die cutting, typically manufactured from foam, film, or foil carriers coated with acrylic, rubber, or silicone adhesives and specified by peel adhesion, shear strength, and temperature resistance for bonding, sealing, gasketing, or shielding applications. Double-sided tape dominates value capture in electronics assembly where space constraints demand zero-profile bonding, while silicone-based formulations represent the fastest-expanding material category due to thermal stability requirements in electric powertrains. Medical-grade die-cut labels remain a mature margin pool constrained by FDA validation timelines and biocompatibility certification costs.
EPA regulates volatile organic compound emissions from adhesive manufacturing facilities, while REACH restricts hazardous substance content in European supply chains, and China's GB standards mandate flame-retardant performance in automotive interior applications. Regulatory divergence across these jurisdictions forces manufacturers to maintain multiple formulation portfolios rather than unified global products. Stakeholders must monitor evolving battery-pack bonding standards as electric vehicle platforms redefine thermal and structural adhesive specifications.
Market Dynamics
Electric vehicle thermal management requirements are forcing adhesive formulators to engineer silicone-based die-cut solutions capable of withstanding sustained temperatures above 150°C while maintaining structural integrity across battery pack architectures.
Growth Catalysts
- GB 8410 automotive flame-retardant standards:Chinese domestic production mandates are pulling die-cut adhesive consumption into EV battery enclosures and interior assemblies at accelerating rates.
- Consumer electronics miniaturization:Smartphone and wearable manufacturers specify ultra-thin double-sided tapes below 50 micrometers for component stacking in space-constrained devices.
- Acrylic thermal interface materials:Power semiconductor packaging is adopting die-cut pads with directional thermal conductivity to replace greases in electric drivetrain inverters.
Market Restraints
- Silicone raw material concentration:Precursor supply chains cluster in East Asian chemical processing hubs, exposing converters to feedstock volatility and logistics disruptions.
- REACH SVHC authorization timelines:European substance restriction procedures extend 18-24 months, freezing formulation changes and delaying product launches for cross-border suppliers.
- Mechanical fastener residual preference:Automotive assembly lines in cost-sensitive segments continue specifying screws and clips for structural joints where adhesive bonding would reduce weight.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for mobile device assembly are constructing new demand nodes for precision die-cut bonding components.
- Solid-state battery platform transitions:Next-generation cell architectures with ceramic electrolytes require redesigned thermal interface and compression pad specifications.
- CE marking for medical devices:EU MDR implementation is expanding the addressable market for biocompatible die-cut adhesive components in diagnostic equipment and wearable monitors.
Industry Challenges
- Adhesive polymer chemist scarcity:Formulation expertise combining pressure-sensitive rheology with thermal stability specifications remains concentrated among experienced practitioners approaching retirement.
- ISO 10993 biocompatibility certification costs:Medical-grade validation requires cytotoxicity and sensitization testing budgets exceeding mid-tier converter capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cut Adhesive Market |
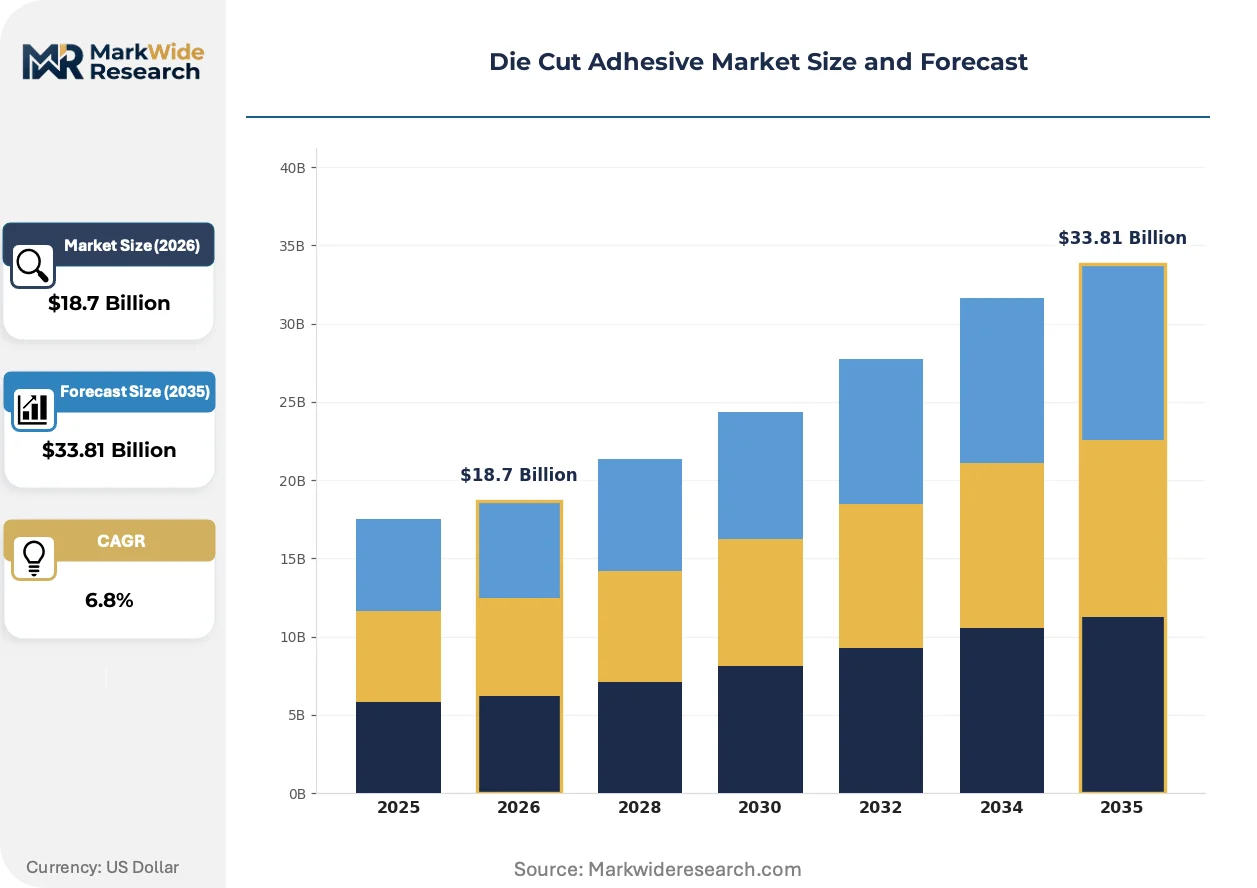
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tape, Double-Sided Tape, Transfer Tape, Label Application: Automotive, Electronics, Packaging, Medical Material: Acrylic, Rubber, Silicone, Vinyl End User: Manufacturers, Retailers, Contractors, Consumers |
| Companies Covered | Sika, RPM International, Henkel, Wacker Chemie, Huntsman, 3M, Arkema, Illinois Tool Works, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cut Adhesive Market Evolving Landscape
Material science advances and regulatory stringency are splitting die-cut adhesive development along performance-optimized versus cost-optimized trajectories, with formulators forced to choose specialization rather than serving unified product portfolios.
Acrylic foam tapes with embedded phase-change materials are bifurcating thermal management applications from conventional silicone gasket solutions. Automotive battery pack engineers specify these hybrid constructions for cell-to-cell bonding where passive thermal buffering complements active cooling systems. The technology is compressing the addressable market for standalone thermal interface pads by integrating structural adhesion with heat-spreading functionality.
EPA volatile organic compound emission thresholds for adhesive manufacturing facilities are tightening coating operation permit requirements. US-based converters face capital expenditure decisions for solvent recovery systems or waterborne adhesive transitions. Southern California air quality districts impose the most restrictive mass emission limits, pushing regional suppliers toward electron-beam curing technologies that eliminate solvent handling entirely.
Automotive OEM engineering teams now specify bonded joint performance warranties rather than material specifications, transferring validation burden downstream to tier-one adhesive converters. This contractual inversion rewards suppliers with in-house finite element modeling and accelerated aging test capabilities. German and Japanese vehicle manufacturers lead this specification evolution, with North American OEMs adopting similar outcome-based procurement frameworks within 18-24 month lag patterns.
Die Cut Adhesive Market Segmentation
Die cut adhesive specifications diverge sharply across end-use contexts, with automotive and electronics procurement teams demanding thermal-rated formulations while packaging converters prioritize cost-optimized acrylic constructions. Segmentation clarity enables suppliers to align formulation investments with margin concentration rather than spreading capabilities thin across incompatible performance tiers.
Product Type:
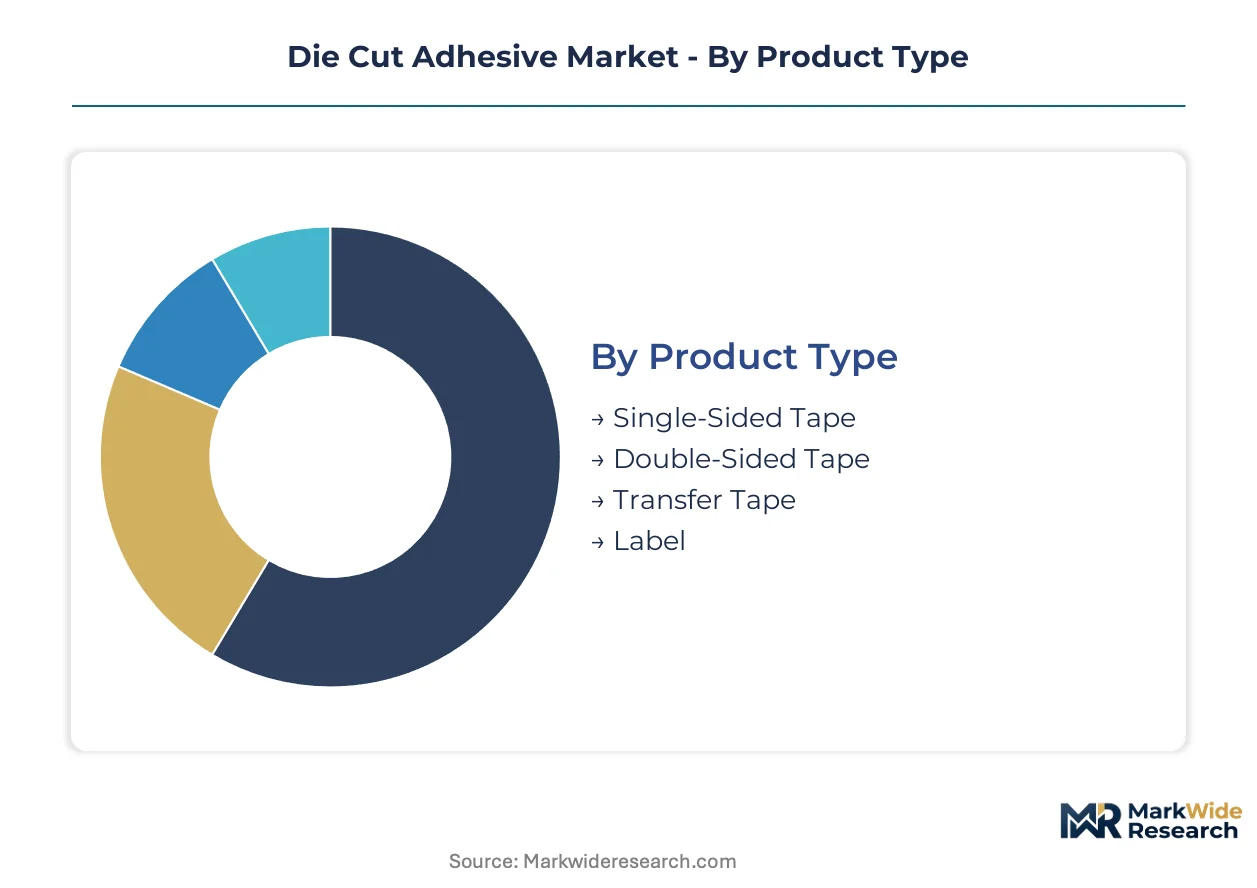
Double-sided tape dominates export flows to Chinese EV battery pack assembly plants, while single-sided constructions serve predominantly domestic construction and general industrial maintenance channels.
- Double-Sided Tape:Zero-profile bonding constructions with carrier substrates ranging from 25 to 250 micrometers enable component stacking in space-constrained smartphones and wearable devices. Chinese smartphone OEMs specify ultra-thin variants below 50 micrometers for display lamination, driving precision die-cutting equipment investments among Guangdong province converters.
- Single-Sided Tape:Pressure-sensitive constructions with exposed adhesive on one face and printable or protective backing on the reverse serve gasketing and surface protection applications. US automotive interior trim suppliers source flame-retardant grades certified to FMVSS 302 for seat assembly and dashboard bonding.
- Transfer Tape:Adhesive-only constructions without carrier substrates enable invisible bonding in electronics bezel attachment and medical device assembly where substrate flexibility matters.
- Label:Printable facestock constructions with permanent or removable adhesives serve asset tracking, safety compliance marking, and consumer product branding across retail and industrial channels.
Double-sided tape holds the largest share; momentum sits with transfer tape as electronics miniaturization eliminates carrier thickness tolerance.
Application:
Cost tiers separate automotive specification-grade formulations from packaging commodity constructions, with medical applications commanding 3-5x price multiples due to biocompatibility validation burdens.
- Automotive:Structural bonding and NVH damping applications specify acrylic foam tapes with dynamic shear resistance above 50 N/cm² for body-in-white assembly. German OEMs now require 10-year corrosion warranty coverage on bonded joints, forcing tier-one suppliers to maintain accelerated aging test facilities.
- Electronics:Thermal interface and electromagnetic shielding applications demand silicone-based die-cut pads with thermal conductivity above 2 W/mK for power semiconductor packaging. South Korean memory chip fabricators specify these constructions for HBM stack bonding where heat dissipation constrains device density.
- Packaging:Carton sealing and label applications utilize cost-optimized rubber-resin adhesives with quick tack development for high-speed filling line compatibility.
- Medical:Wearable device attachment and diagnostic component bonding require ISO 10993-5 cytotoxicity certification and sterilization stability validation that extends procurement cycles 18-24 months.
Automotive commands the steepest pricing; medical is climbing the fastest as EU MDR implementation expands diagnostic equipment adhesive specifications.
Material:
Volume concentration favors acrylic chemistry for its balance of clarity, UV resistance, and moderate temperature tolerance across consumer and industrial applications.
- Silicone:Polysiloxane-based adhesives with service temperatures from -40°C to 200°C dominate EV battery pack thermal interface and compression pad specifications. Chinese GB 38031 battery safety standards mandate flame-retardant silicone constructions for cell-to-cell bonding in passenger electric vehicles.
- Acrylic:Photocrosslinked polymer networks deliver optical clarity and weathering resistance for electronics display bonding and outdoor signage applications. Japanese display panel manufacturers specify these formulations for OLED encapsulation where yellowing resistance determines product lifetime.
- Rubber:Natural and synthetic elastomer-based adhesives with aggressive tack and lower cost serve packaging, masking, and temporary holding applications where temperature extremes are absent.
- Vinyl:Plasticized PVC carrier films with conformable adhesive coatings enable irregular surface bonding in automotive interior trim and recreational vehicle assembly.
Acrylic holds the largest share; silicone is gaining share fastest as electric vehicle thermal management specifications proliferate.
End User:
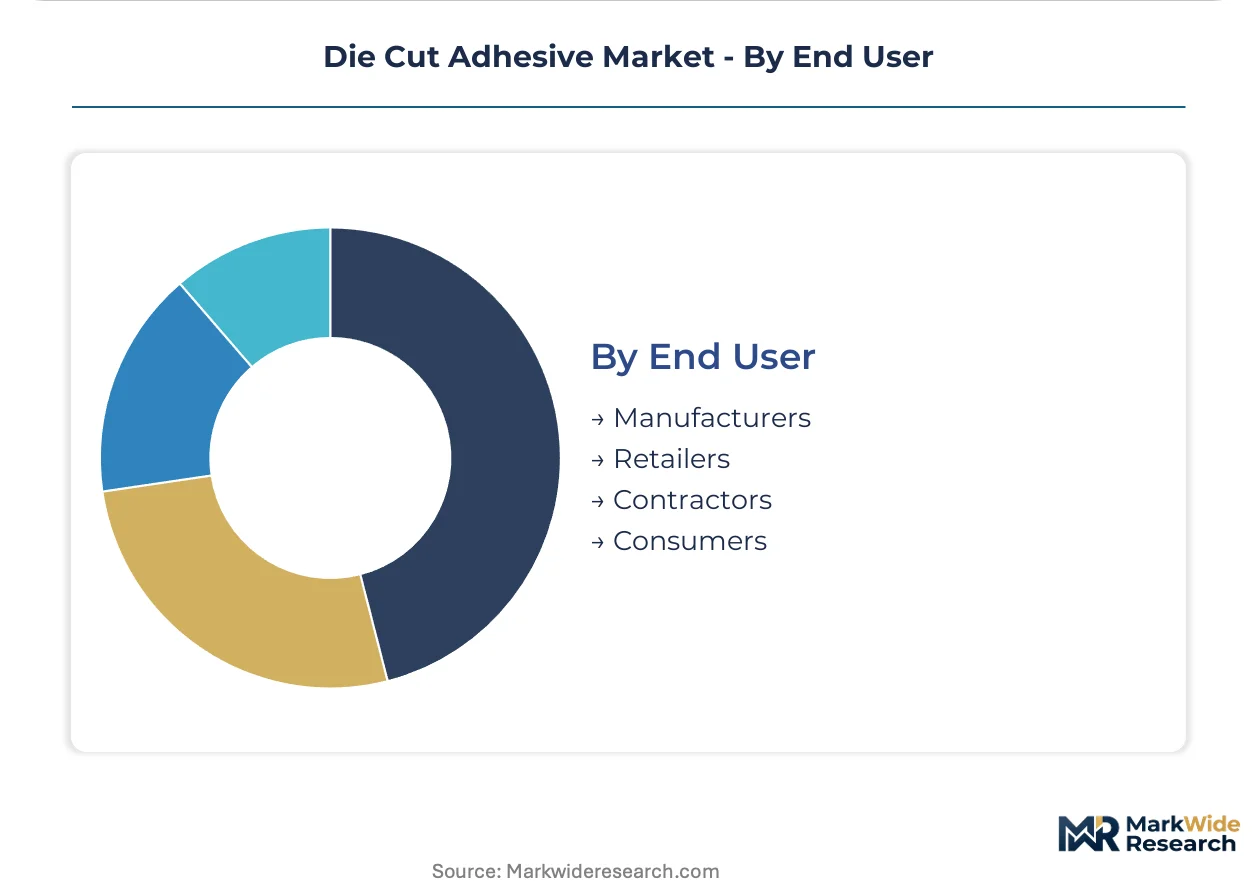
Customer type determines technical support intensity, with manufacturers demanding application engineering partnership while retailers and consumers transact through distribution stock-keeping units.
- Manufacturers:OEM and tier-one assembly operations specify custom die-cut geometries with statistical process control documentation and lot traceability for automotive and electronics qualification. German automotive suppliers require PPAP Level 3 submission for adhesive component approval.
- Contractors:Construction and installation trades purchase standard dimensional products through industrial distribution for HVAC sealing, flooring installation, and waterproofing membrane application.
- Retailers:Big-box and specialty retailers stock consumer-format rolls and sheets for DIY repair, craft, and home organization applications with minimal technical specification.
- Consumers:Direct e-commerce purchases of pre-cut shapes and craft assortments represent the lowest value-per-transaction segment with highest return rates due to misapplication.
Manufacturers hold the largest share; contractors are expanding most quickly as construction adhesive substitution for mechanical fastening accelerates in residential and commercial building codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific supply chain throughput for pressure-sensitive adhesive raw materials, while the Rhine-Alpine freight corridor sustains European just-in-time delivery networks for automotive bonding components.
China
Domestic EV battery production and consumer electronics assembly dominate die-cut adhesive consumption. GB 38031 battery safety standards mandate flame-retardant silicone constructions for cell-to-cell bonding. Guangdong province converters invest in precision die-cutting equipment to supply smartphone OEMs with ultra-thin tape variants below 50 micrometers.
Germany
Automotive OEM engineering teams specify bonded joint performance warranties rather than material specifications. REACH SVHC authorization procedures extend formulation approval timelines. Bavarian adhesive formulators maintain accelerated aging test facilities to satisfy 10-year corrosion warranty requirements from domestic vehicle manufacturers.
United States
EPA volatile organic compound emission thresholds tighten coating operation permit requirements for adhesive manufacturing. Southern California air quality districts impose the most restrictive mass emission limits. Midwest-based converters face capital expenditure decisions for solvent recovery systems or waterborne adhesive transitions.
South Korea
Memory chip fabricators specify silicone-based die-cut pads with thermal conductivity above 2 W/mK for HBM stack bonding. MFDS regulates medical-grade adhesive components for wearable device attachment. Seoul-Incheon industrial corridor hosts precision converter operations serving display panel manufacturers.
India
PLI scheme production-linked incentives for mobile device assembly construct new demand nodes for precision die-cut bonding components. BIS standards govern adhesive specifications for automotive interior applications. Tamil Nadu and Karnataka electronics manufacturing clusters attract converter investments to localize supply chains.
Die Cut Adhesive Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized adhesive formulators competing across incompatible performance tiers. The vendor base separates into three strategic archetypes: integrated material science multinationals with polymer synthesis capabilities, regional converters with die-cutting equipment and application engineering expertise, and niche specialists serving medical-grade validation requirements. M&A activity targets thermal interface material portfolios, while capacity expansion concentrates in proximity to Chinese EV battery assembly hubs.
Among European-based chemical conglomerates, Henkel and Sika occupy positions anchoring formulation leadership across automotive and construction-adjacent specifications. 3M represents the integrated material science archetype with proprietary adhesive polymer architectures. These three companies exemplify the competitive structure where technology ownership and geographic proximity to OEM engineering centers determine tier-one supplier status.
| Leading Market Players |
|---|
| Sika |
| RPM International |
| Henkel |
| Wacker Chemie |
| Huntsman |
| 3M |
| Arkema |
| Illinois Tool Works |
| H.B. Fuller |
| Others |
Value Network & Pricing Analysis
Silicone precursor substitution for petroleum-based acrylic feedstocks is simultaneously relocating supply geography toward East Asian chemical processing corridors and compressing margin structures for European formulators facing REACH compliance cost layering. This input shift concentrates pricing power among integrated polysiloxane producers while fragmenting converter margins across incompatible regulatory jurisdictions.
Pricing Analysis
Three-tier pricing structure across automotive specification-grade, electronics precision-grade, and packaging commodity-grade levels dominates contract negotiations. Price differentiation hinges on thermal performance certification and volume commitment scale, with automotive OEMs locking annual offtake agreements while spot purchasing governs construction-grade acrylic tapes. Cost compression in packaging-grade rubber-resin constructions is intensifying because Chinese converters are flooding export channels with undifferentiated capacity. Electronics assemblers exhibit lowest price sensitivity due to performance warranty requirements, whereas general industrial distributors face margin erosion from interchangeable commodity supply.
Supply Chain Analysis
China, South Korea, and Japan anchor silicone adhesive polymer production for thermal-rated die-cut applications serving electric vehicle battery pack assembly. Raw material sourcing draws from East Asian organosilicon precursor facilities, German specialty chemical additive suppliers, and US acrylic monomer production corridors. Single-source vulnerability concentrates in polydimethylsiloxane feedstock channels where three chemical conglomerates control global precursor output. Distribution runs through Shanghai Yangshan port consolidation for Asia-Pacific battery assembly hubs, with Rhine-Alpine rail corridors sustaining European automotive just-in-time networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die cut adhesive market fragmentation creates multiple specialization niches as electric vehicle thermal specifications diverge from consumer electronics miniaturization requirements. Procurement teams now demand application-engineered solutions rather than catalog standard products.
For Market Incumbents: Secure formulation patent positions in silicone thermal interface architectures before solid-state battery platform transitions obsolete current compression pad specifications. Backward integration into organosilicon precursor production hedges feedstock volatility exposure from East Asian chemical processing concentration. Accelerated aging test facility investments satisfy German OEM outcome-based procurement frameworks that transfer validation liability downstream.
For New Entrants and Emerging Players: Differentiate on medical-grade biocompatibility certification capabilities where ISO 10993 validation timelines create incumbent switching costs. Target Indian electronics manufacturing clusters where PLI scheme incentives are constructing new demand nodes without established supplier relationships. Pursue partnership-based go-to-market models with precision die-cutting equipment houses to bypass capital-intensive coating line investments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional converters holding automotive qualification certificates but lacking thermal interface material R&D depth. Five-to-ten year viability hinges on portfolio repositioning toward EV battery specifications rather than legacy internal combustion engine NVH applications. Monitor GB 38031 flame-retardant standard enforcement intensity as inflection indicator for Chinese domestic demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Supply | Henkel and Wacker Chemie captive production secures margin control against East Asian feedstock volatility. |
| Medical-Grade Biocompatibility Certification Investment | ISO 10993-5 cytotoxicity validation opens diagnostic equipment procurement cycles with 18-24 month switching barriers. |
| Precision Die-Cutting Equipment Expansion | Guangdong province converter investments capture smartphone OEM ultra-thin tape specifications below 50 micrometers. |
| Accelerated Aging Test Facility Construction | Bavarian formulator capabilities satisfy German OEM 10-year corrosion warranty requirements on bonded joints. |
| Waterborne Adhesive Coating Transition | Southern California converters achieve EPA VOC compliance without electron-beam curing capital expenditure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with adhesive formulators, automotive tier-one procurement directors, electronics assembly engineers, and precision die-cutting equipment operators; and secondary validation through customs trade databases, SEC chemical sector filings, REACH SVHC registration repositories, and GB standards documentation. Bottom-up volume modeling from converter capacity utilization rates triangulated against top-down OEM adhesive content-per-vehicle and content-per-device estimates.
Across the analysis window, projections incorporate segmentation dimensions spanning material chemistry, product construction type, end-use application intensity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves calibrated to electric vehicle production ramp schedules and smartphone form factor evolution trajectories. Thermal conductivity specification trajectories and flame-retardant certification adoption curves constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle platform standardization or accelerated solid-state battery commercialization would require recalibration. Forecasts reflect documented assumptions regarding REACH authorization timeline stability and Chinese GB standard enforcement consistency. Recalibration cycles align with material shifts in battery pack thermal management specifications and medical device regulatory pathway revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
Polysulfide Sealants Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market