
 Global Slack Wax Market | 2026-2036
Global Slack Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Slack Wax Market Foresight
Market Context with Strategic Players
Refinery-direct supply contracts is rewriting how slack wax reaches tire and rubber compounders across Asia. ExxonMobil Corporation leverages its integrated refinery network to sustain captive feedstock access for fully refined grades. Sasol Limited anchors southern African supply into European candle and polish markets through specialized distribution partnerships. China National Petroleum Corporation dominates domestic volume flows, extending its position via pipeline-linked storage terminals.
Technical Definition and Structural Segments
Slack wax is a soft, unrefined petroleum wax separated from lubricating oil fractions through solvent dewaxing, typically containing 5-30% oil content and serving as the primary feedstock for refined paraffin and microcrystalline wax production. Its industrial purpose centers on providing cost-effective moisture barriers, release agents, and blend stocks across rubber processing, candle manufacturing, and coating formulations. Semi-refined slack wax occupies the largest margin pool due to its versatility across tire production and adhesives, while microcrystalline wax segments are gaining traction in electrical insulation applications where higher melt points and flexibility are required. Candle manufacturing remains structurally mature with thin margins, whereas polishes and coatings command premium positioning through formulation complexity and brand-specified certifications.
Regulatory Frame and Forward-Looking Close
REACH in Europe, GB standards under SAMR in China, and FDA oversight for pharmaceutical-grade wax contact applications collectively tighten purity thresholds and documentation burdens for cross-border slack wax trade. These frameworks are forcing exporters to invest in laboratory certification and batch traceability systems to maintain market access. Stakeholders must monitor how evolving EU Green Deal carbon accounting rules and China's dual carbon goals reshape refinery operating costs and regional supply competitiveness.
Market Dynamics
Refinery consolidation and feedstock volatility are compressing supply chain flexibility for rubber compounders and candle manufacturers, forcing buyers to lock in multi-year offtake agreements or accept widening price spreads between spot and contract volumes.
Growth Catalysts
- EU Green Deal carbon accounting:European refiners are investing in hydrocracker upgrades to produce lower-carbon slack wax grades, creating certified supply lines for tire makers with Scope 3 reduction mandates.
- Rubber processing expansion:Indian tire manufacturers are scaling slack wax consumption for anti-ozonant formulations as domestic vehicle production accelerates and export quotas tighten.
- Microcrystalline wax adoption:Electrical insulation applications are absorbing higher-melt-point slack wax derivatives as power grid investments in Southeast Asia demand materials with superior thermal stability.
Market Restraints
- Crude oil price volatility:Lubricating oil feedstock costs swing unpredictably, squeezing margin visibility for semi-refined grade producers who cannot pass through increases to fixed-price contract customers.
- Supply concentration risk:Pipeline-linked storage terminals in eastern China dominate regional volume flows, creating single-point vulnerability for Southeast Asian buyers dependent on transshipment through Ningbo-Zhoushan.
- Paraffin substitution threat:Bio-based wax alternatives from palm oil and soy feedstocks are capturing premium candle segments in Germany and France where sustainability certifications command shelf space.
Strategic Opportunities
- Brazilian rubber sector underpenetration:Domestic tire production in São Paulo state lacks established slack wax supply relationships, offering first-mover positioning for exporters with REACH-compliant documentation.
- India PLI scheme tailwind:Production-linked incentives for automotive component manufacturing are accelerating domestic rubber compounding capacity, pulling in imported slack wax for anti-ozonant masterbatch production.
- Direct refinery procurement platforms:Digital tendering systems are disintermediating traditional distributors, allowing tire makers in Thailand and Indonesia to negotiate volume discounts previously reserved for national oil company affiliates.
Industry Challenges
- REACH registration complexity:Small and mid-size exporters face prohibitive costs for full substance dossier preparation, blocking market access despite product quality equivalence.
- Batch traceability system integration:Legacy ERP platforms at Southeast Asian rubber compounders cannot ingest refinery-level certificate of analysis data, forcing manual reconciliation and compliance documentation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Slack Wax Market |
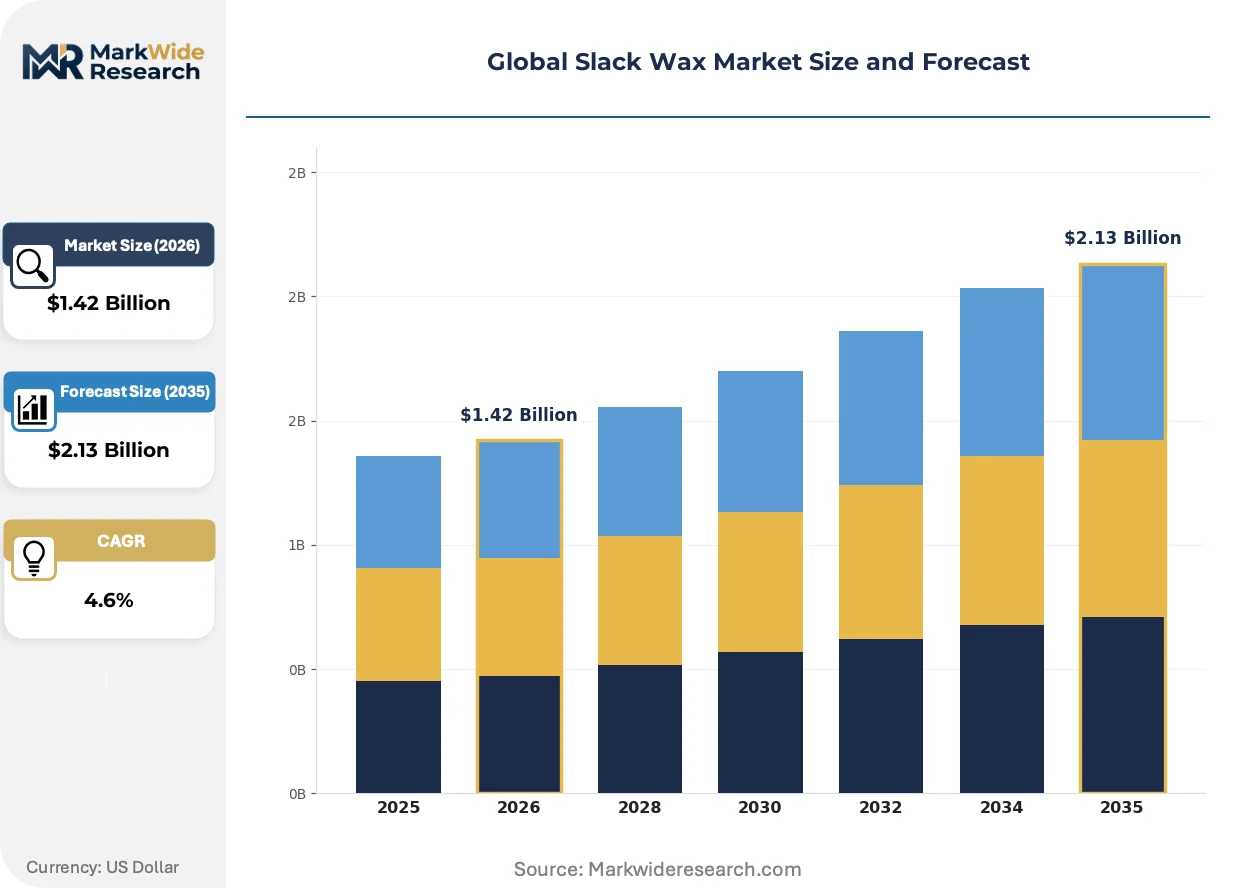
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Refined, Semi-Refined, Scale Wax, Microcrystalline Wax, Paraffin Wax Application: Candle Manufacturing, Rubber Processing, Polishes & Coatings, Tire Production, Adhesives, Electrical Insulation End User Industry: Printing & Packaging, Textile Fabricators, Construction Material Producers, Pharmaceutical Manufacturers, Cosmetics Producers, Chemical Suppliers Packaging Type: Drums, Bags, Bulk Containers, Boxes, Intermediate Bulk Containers, Totes |
| Companies Covered | China National Petroleum Corporation, IRPC Public Company Limited, ExxonMobil Corporation, American Refining Group Inc, Thai Oil Public Company Limited, Royal Dutch Shell plc, Sasol Limited, BP plc, China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Slack Wax Market Shifts & Advancements
Digital infrastructure and regulatory transparency requirements are rewriting how slack wax specifications are verified, traded, and integrated into downstream formulations across rubber, candle, and coating applications.
Blockchain-enabled certificate of origin systems are digitizing custody documentation from refinery dewaxing units through to tire mold release applications. Indian and Thai rubber compounders are piloting these platforms to satisfy EU importer due diligence requirements. This technology is digitizing what was previously paper-based batch reconciliation, compressing customs clearance timelines and reducing documentary dispute arbitrations.
REACH authorization list expansion is tightening purity thresholds for polycyclic aromatic hydrocarbon content in slack wax destined for consumer candle applications. German and French regulators are enforcing stricter testing protocols at import checkpoints. Candle manufacturers in Poland and Romania are responding by sourcing only from refineries with accredited laboratory partnerships, displacing lower-cost uncertified alternatives from non-EU origins.
Specification-driven procurement is consolidating buyer decision criteria around melt point range and oil content precision rather than brand loyalty or historical supplier relationships. Korean tire makers are deploying technical audit teams to evaluate refinery solvent dewaxing capabilities directly. This behavioral shift concentrates volume with integrated producers capable of certificate-matched consistency, marginalizing traders without laboratory verification capacity.
Global Slack Wax Market Segmentation
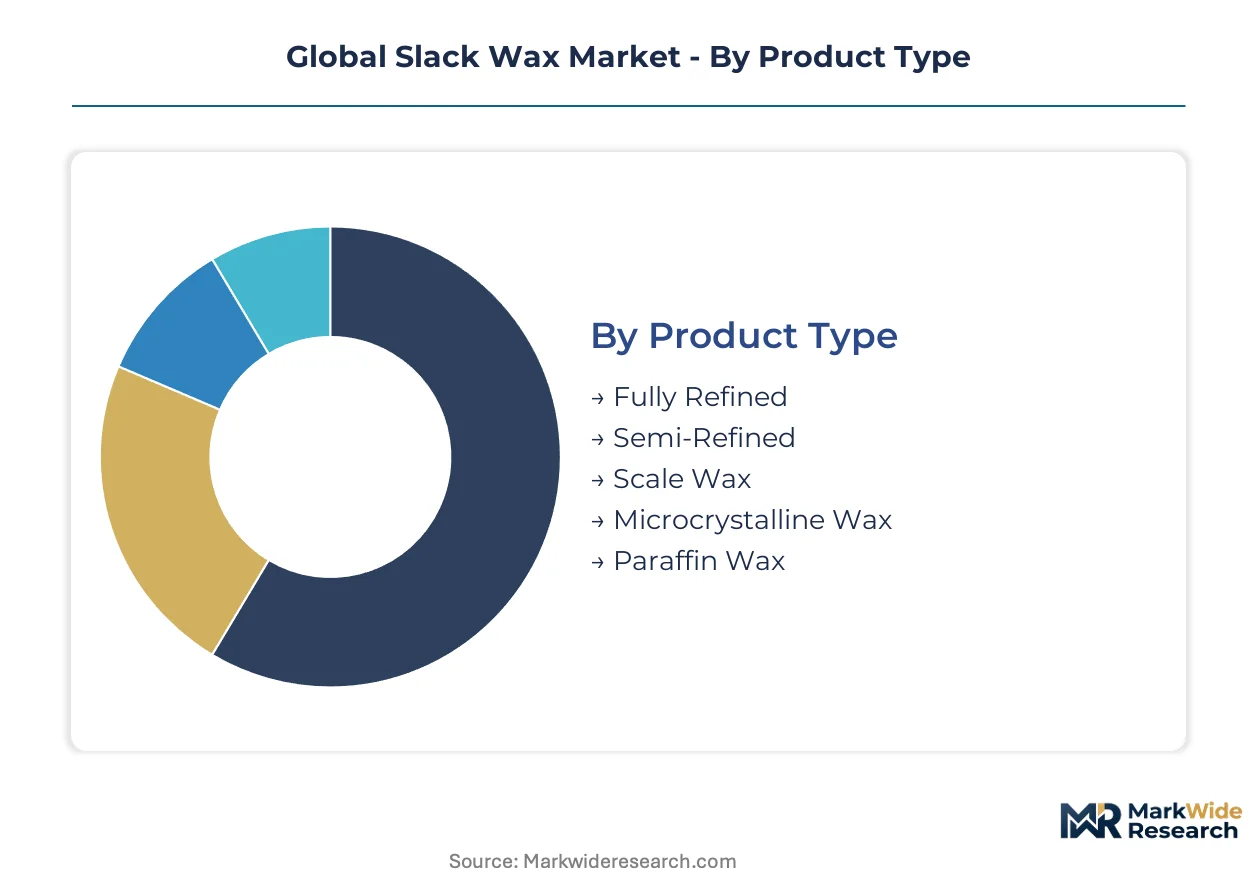
Slack wax segmentation reflects divergent technical requirements across rubber compounding, candle manufacturing, and electrical insulation end-uses. Buyers prioritize oil content precision and melt point consistency over brand affiliation, forcing suppliers to align product grades with application-specific certification demands.
Product Type:
After-sales service intensity varies sharply across refined grades, with fully refined segments demanding laboratory verification support and batch traceability systems that semi-refined buyers rarely require.
- Fully Refined:Contains less than 0.5% oil content after hydrofinishing and clay treatment, delivering pharmaceutical-grade purity for cosmetic and food-contact applications. Demand concentrates in German candle manufacturing where REACH PAH thresholds are tightening. This grade commands premium positioning through accredited laboratory partnerships.
- Semi-Refined:Retains 1-3% oil content after partial solvent dewaxing, balancing cost efficiency with functional performance across tire anti-ozonant formulations. Indian rubber compounders in Chennai and Pune are scaling procurement as domestic vehicle production accelerates. This segment absorbs volume through multi-year offtake agreements with refinery-direct suppliers.
- Scale Wax:Intermediate refining product with 3-8% oil content serving polish and coating blend stocks.
- Microcrystalline Wax:Higher-melt-point derivative with branched hydrocarbon structure for electrical insulation and adhesive applications.
- Paraffin Wax:Fully dewaxed and refined straight-chain hydrocarbon competing with slack wax feedstocks in candle segments.
By volume, semi-refined leads. By growth pace, microcrystalline wax derivatives for electrical insulation are climbing the fastest.
Application:
Margin structures diverge across applications, with tire production and electrical insulation commanding technical premiums while candle manufacturing operates on thin, volume-driven economics.
- Tire Production:Anti-ozonant and softening agent in rubber compounding, requiring precise oil content control to prevent bloom and surface defects. Thai and Indonesian tire makers are deploying technical audit teams to evaluate refinery solvent dewaxing capabilities directly. This application concentrates procurement with integrated producers capable of certificate-matched consistency.
- Electrical Insulation:Higher-melt-point slack wax derivatives for cable filling and transformer insulation, demanding superior thermal stability under load cycling. Power grid investments across Vietnam and the Philippines are absorbing specialized microcrystalline grades. This segment expands most quickly as Southeast Asian infrastructure buildouts accelerate.
- Candle Manufacturing:Traditional end-use facing bio-based substitution pressure in German and French premium segments.
- Rubber Processing:General compounding applications beyond tire-specific formulations.
- Polishes & Coatings:Surface protection and gloss formulations with brand-specified certification requirements.
- Adhesives:Hot-melt and pressure-sensitive adhesive blend stocks.
Tire production captures the largest revenue pool. Electrical insulation exhibits the steepest expansion trajectory as grid modernization drives specification upgrades.
End User Industry:
Customer procurement sophistication varies by industry, with pharmaceutical and cosmetic buyers imposing documentation burdens that construction material producers rarely match.
- Pharmaceutical Manufacturers:FDA and EMA compliance requirements for excipient-grade wax used in tablet coatings and sustained-release matrices. Batch traceability from refinery dewaxing unit through final formulation is mandatory. This industry pays premiums for verified certificate of analysis documentation.
- Cosmetics Producers:REACH and GB standard compliance for skin-contact applications, with French and Chinese regulators enforcing stricter testing protocols at import checkpoints. Polish and Romanian formulators are sourcing only from accredited laboratory partnerships. This segment is displacing uncertified alternatives through specification-driven procurement.
- Printing & Packaging:Moisture barrier coatings and release agent applications.
- Textile Fabricators:Sizing and finishing agent for yarn lubrication.
- Construction Material Producers:Waterproofing additive for concrete and bitumen modification.
- Chemical Suppliers:Intermediate feedstock for further derivative production.
Pharmaceutical manufacturers lead by margin contribution. Cosmetics producers are gaining share fastest as clean beauty certifications proliferate.
Packaging Type:
Logistics cost structures and handling requirements fragment procurement preferences across drum, bulk, and intermediate container formats.
- Bulk Containers:Marine and rail shipment of unrefined grades to tire compounders with dedicated unloading infrastructure. Ningbo-Zhoushan pipeline-linked terminals dominate regional volume flows for Southeast Asian buyers. This format minimizes per-unit logistics cost for high-volume contract customers.
- Intermediate Bulk Containers:Flexible handling for mid-scale rubber processors and candle manufacturers without dedicated bulk receiving capabilities. Indonesian and Vietnamese compounders are adopting IBC formats to reduce inventory holding costs. This packaging type bridges bulk efficiency and drum flexibility.
- Drums:Standard 200-liter steel containers for refined grades requiring contamination protection.
- Bags:Powdered or flaked wax formats for specific compounding applications.
- Boxes:Smaller quantity shipments for specialty and sample requirements.
- Totes:Flexible intermediate capacity for variable demand patterns.
Bulk containers dominate by tonnage shipped. Intermediate bulk containers are expanding most quickly as mid-tier processors upgrade handling infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan port complex underwrites China's dominance in regional slack wax flows, with pipeline-linked storage terminals feeding Southeast Asian tire compounders through dedicated marine corridors.
China
Domestic rubber processing and tire production absorb semi-refined slack wax volumes from Sinopec and CNPC refineries. GB standards under SAMR tighten oil content specifications for export-grade material. The Yangtze River Delta cluster around Shanghai and Ningbo concentrates dewaxing capacity and transshipment logistics.
India
Production-linked incentives for automotive components accelerate rubber compounding demand in Chennai and Pune. BIS certification requirements for industrial wax imports force laboratory partnerships on foreign suppliers. The Gujarat refinery corridor supplies domestic semi-refined grades while coastal processors rely on Middle Eastern imports.
Germany
REACH PAH thresholds and EU Green Deal carbon accounting reshape procurement for candle manufacturers in Hamburg and Cologne. ECHA enforcement at Rotterdam and Hamburg checkpoints blocks uncertified shipments. The Rhine-Ruhr industrial belt maintains specialized blending capacity for pharmaceutical-grade fully refined wax.
Thailand
Thai Oil's refinery-direct supply relationships anchor regional tire production for Bridgestone and Michelin affiliates. Digital tendering platforms disintermediate traditional distributors for Indonesian and Vietnamese buyers. The Map Ta Phut petrochemical zone integrates slack wax output with downstream rubber processing.
United States
Gulf Coast refineries supply domestic tire makers and export semi-refined grades to Latin American rubber compounders. FDA oversight for pharmaceutical-grade applications limits eligible import sources. The Houston Ship Channel concentrates storage and blending infrastructure for North American distribution.
Global Slack Wax Market Competitive Landscape
On the supply side, the industry is consolidating around integrated refinery operators with captive dewaxing capacity and laboratory certification infrastructure. National oil companies and multinational energy majors occupy distinct tiers, with mid-scale regional refiners filling specialty grade niches. Strategic moves center on multi-year offtake agreements with tire makers and blockchain-enabled batch traceability investments for EU compliance.
Among Asia-Pacific-based suppliers, China National Petroleum Corporation and Thai Oil Public Company Limited exemplify the integrated refinery archetype with pipeline-linked terminal advantages. ExxonMobil Corporation anchors the multinational major tier through Gulf Coast and Singapore refining positions. These three entities represent divergent geographic footprints while converging on direct procurement platform development.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| IRPC Public Company Limited |
| ExxonMobil Corporation |
| American Refining Group Inc |
| Thai Oil Public Company Limited |
| Royal Dutch Shell plc |
| Sasol Limited |
| BP plc |
| China Petroleum & Chemical Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in European hydrocracker units is tightening fully refined grade availability and pushing tire compounders toward multi-year contract structures that lock in volume before spot premiums escalate further.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified fully refined grades from semi-refined tire feedstocks and unrefined scale wax for coatings. Price differentiation centers on laboratory certification tier and volume scale, with pharmaceutical-grade buyers absorbing premiums for batch traceability while Indian rubber compounders negotiate on oil content precision. Cost compression in semi-refined segments is intensifying because crude-linked feedstock volatility outpaces contract pass-through mechanisms. Candle manufacturers exhibit highest price sensitivity due to bio-based substitution threats, whereas tire makers prioritize specification consistency over unit economics.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian rubber processors dominates supply chain risk calculations as GB standard compliance costs accumulate at Ningbo-Zhoushan transshipment points. Geographic supply concentrates in China, Thailand, and South Africa, with dewaxing capacity clustering around refinery-integrated petrochemical zones. Raw material dependencies rest on lubricating oil fractions from Group I/II base stock production, solvent dewaxing chemicals, and hydrofinishing catalysts. Single-source vulnerability runs through pipeline-linked terminals in eastern China that feed Southeast Asian tire production. Distribution runs through marine bulk corridors to dedicated unloading infrastructure at Thai and Indonesian compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around Indian tire manufacturers and European candle makers with REACH compliance mandates, fragmenting supplier leverage across fragmented refinery-direct negotiations.
For Market Incumbents: Build certification moats through accredited laboratory partnerships that block mid-tier exporters from EU and Indian pharmaceutical-grade segments. Anchor defensive positioning by locking multi-year offtake agreements with Thai and Indonesian tire makers before digital tendering platforms erode contract premiums. Prioritize hydrocracker upgrades for lower-carbon grade production to capture EU Green Deal procurement preferences from Scope 3-conscious automotive OEMs. For New Entrants and Emerging Players: Build out white-space positioning in Brazilian rubber compounding around São Paulo tire production clusters where established supply relationships remain underdeveloped. Target India PLI scheme beneficiaries in Chennai and Pune with semi-refined grades certified for anti-ozonant masterbatch applications. Lead go-to-market through direct refinery procurement platforms that disintermediate legacy distributor networks and capture volume discounts previously reserved for national oil company affiliates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refinery operators with captive dewaxing capacity and long-term tire maker contracts. Long-term viability across the analysis window favors upstream assets with pipeline-linked terminal access over trading-dependent intermediaries. Acquisition focus should center on Southeast Asian refiners with laboratory certification infrastructure and uncontracted capacity expansion potential. Monitor blockchain-enabled batch traceability adoption rates as inflection signal for EU market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dewaxing Capacity | Captive feedstock access insulates ExxonMobil and CNPC from lubricating oil price volatility. |
| Blockchain-Enabled Batch Traceability | Indian rubber compounders pilot these platforms to compress EU customs clearance timelines. |
| Long-Term Supply Agreement with Tire Makers | Thai Oil anchors regional procurement for Bridgestone and Michelin affiliate production. |
| Green Manufacturing Transition | European hydrocracker upgrades produce lower-carbon grades for Scope 3 reduction mandates. |
| Joint Venture for Laboratory Certification | Polish candle manufacturers source only from accredited partnerships to satisfy ECHA enforcement. |
Research Methodology
The analysis maps fully refined, semi-refined, and microcrystalline wax segments, each validated through refinery operations managers, tire compounder procurement leads, candle manufacturer technical directors, and coatings formulator R&D heads. Primary interview data triangulates against customs and trade flow databases, SEC 10-K petroleum product disclosures, ACC and Cefic wax market reports, and ECHA REACH registration filings. Bottom-up volume builds from grade-specific application demand and top-down cross-checks against refinery capacity utilization estimates ensure methodological rigor.
Assumptions held fixed include GB standard enforcement timelines, EU Green Deal carbon accounting implementation, and Indian PLI scheme beneficiary qualification criteria. Segmentation dimensions modeled span oil content grade, end-use application, packaging format, and regional production hub classification. CAGRs derive from segment-level demand elasticity analysis applied to refinery output projections. Industry-specific forecast inputs incorporate lubricating oil feedstock availability from Group I/II base stock transitions and rubber compounding capacity expansion in automotive manufacturing clusters.
Stress conditions across crude oil price bands, REACH authorization list expansions, and bio-based wax substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions while acknowledging that regulatory enforcement intensity, refinery consolidation patterns, or alternative material breakthroughs could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Glue Pen Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Europe Bone Glue Market
Adhesives & Sealants
Automotive Adhesives and Sealants Market