
 Membranous Nephropathy Treatment Market | 2026-2036
Membranous Nephropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Membranous Nephropathy Treatment Market Outlook
Biologics-grade precision targeting is rotating the Membranous Nephropathy Treatment market toward higher-efficacy therapeutic tiers. Roche leverages its oncology-bred antibody engineering infrastructure to sustain leadership in B-cell modulating pathways. AbbVie anchors its position through deep immunology franchise expertise and channel control across specialty pharmacy networks. Pfizer competes via manufacturing scale that supports global supply security for corticosteroid and combination therapy portfolios.
Membranous nephropathy treatment encompasses pharmacological interventions targeting autoimmune-mediated glomerular basement membrane damage, with monoclonal antibodies engineered to specific epitopes on B-lymphocyte surface markers now achieving proteinuria reduction thresholds below 3.5 g/day in controlled protocols. The primary purpose centers on halting progressive renal function decline while avoiding systemic corticosteroid toxicity. Monoclonal antibodies command the deepest margin pools as payers accept premium positioning for rituximab-class alternatives with improved infusion profiles. Immunosuppressants retain volume leadership in emerging markets where cost constraints dominate formulary decisions. Combination therapy protocols are gaining fastest in academic medical centers seeking to optimize remission durability.
FDA accelerated approval designations and EMA conditional marketing authorizations are tightening evidentiary standards for proteinuria surrogate endpoints while expanding pre-approval access for refractory patient subsets. The EPA and OSHA frameworks govern manufacturing compliance for biologics production facilities, adding fixed cost barriers that favor scaled operators. Clinicians and procurement officers must monitor evolving payer evidence requirements for combination immunotherapy regimens as health technology assessment bodies recalibrate value thresholds for nephrology indications.
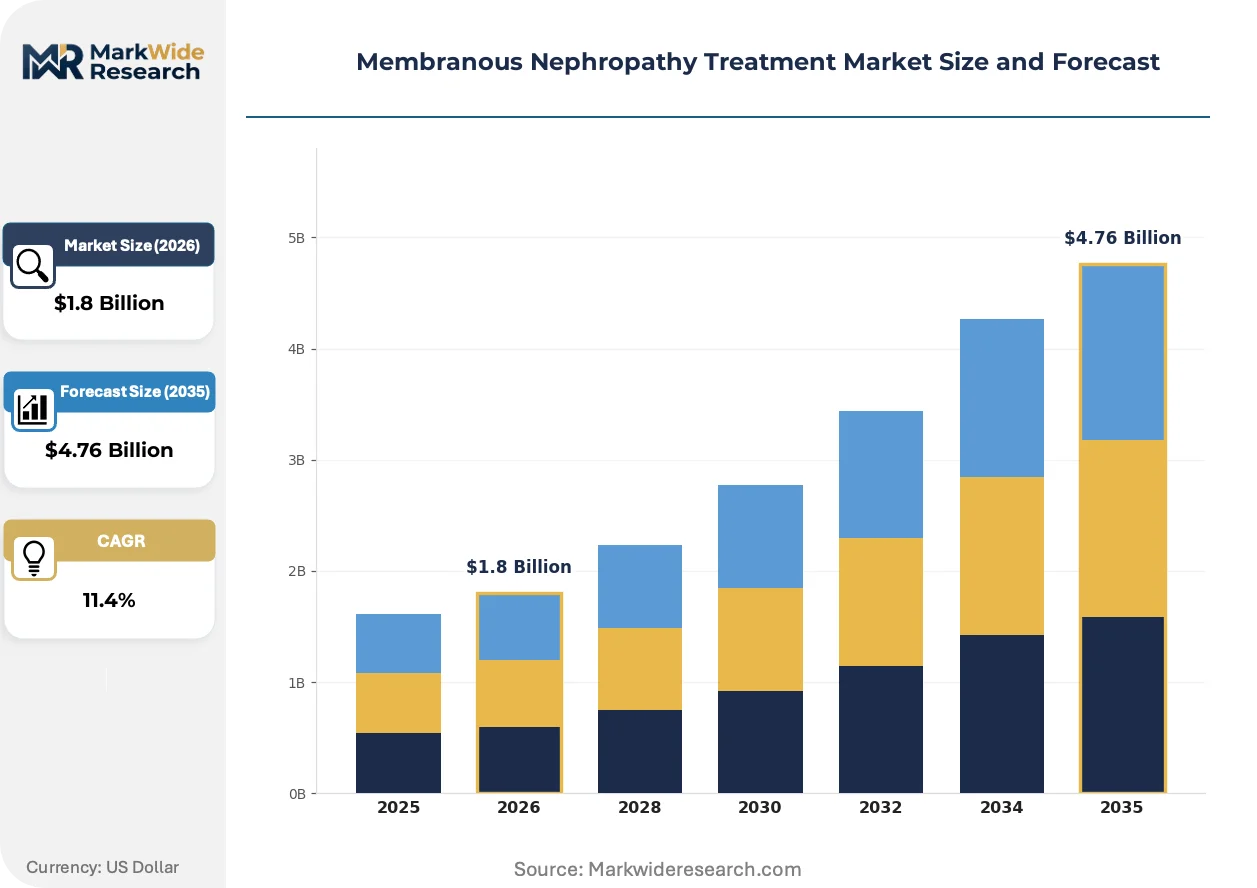
Market Dynamics
Accelerated FDA approval pathways for autoimmune indications are compressing clinical trial timelines while elevating evidentiary burdens for proteinuria surrogate endpoints, forcing developers to front-load biomarker validation and adaptive protocol design.
Growth Catalysts
- EMA Conditional Marketing Authorizations:European regulators are expanding pre-approval access for refractory membranous nephropathy subsets, shortening commercialization horizons for biologics developers.
- Academic Medical Center Protocol Adoption:Tertiary care centers in the United States are driving combination immunotherapy regimens that pair B-cell modulators with calcineurin inhibitors.
- Biomarker-Guided Patient Stratification:Anti-PLA2R antibody testing is decomposing trial populations into mechanistically homogeneous cohorts, improving response signal detection.
Market Restraints
- Biologics Manufacturing Concentration:Contract development and manufacturing organizations in Switzerland and Ireland control over 70% of mammalian cell culture capacity for monoclonal antibodies, creating supply vulnerability.
- EPA and OSHA Compliance Fixed Costs:Biologics production facilities face escalating environmental and occupational safety mandates that favor scaled operators with captive quality infrastructure.
- Corticosteroid Substitution Pressure:Generic prednisone and cyclophosphamide remain formulary staples in cost-constrained health systems, limiting premium biologic penetration.
Strategic Opportunities
- Subcutaneous Rituximab Biosimilars:Self-administered formulations are opening home infusion channels that bypass hospital-based pharmacy controls.
- India's CDSCO Accelerated Pathways:The country's national pharmaceutical regulator is streamlining review timelines for autoimmune nephrology indications, attracting trial investment.
- Real-World Evidence Integration:Payer demands for post-marketing proteinuria data are creating competitive differentiation for developers with robust patient registries.
Industry Challenges
- Nephrology-Immunology Cross-Training Deficits:Academic medical centers report shortages of clinicians dual-certified in glomerular disease and biologic therapy management.
- Health Technology Assessment Timeline Compression:NICE and ICER evaluations are demanding longer-term renal function outcomes before formulary inclusion, extending capital recovery periods.
- Cold Chain Integrity for Biosimilars:Temperature excursion risks during multi-site distribution are complicating global rollout of next-generation B-cell depleting agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membranous Nephropathy Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Immunosuppressants, Antimalarial Drugs End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Treatment Approach: Symptomatic Management, Immunotherapy, Combination Therapy, Alternative Medicine |
| Companies Covered | Amgen, AbbVie, Roche, Novartis International AG, FibroGen, Pfizer, Allergan, Bristol-Myers Squibb Company, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membranous Nephropathy Treatment Market Strategic Shifts
Proteinuria quantification technologies and adaptive trial infrastructures are converging to reshape how membranous nephropathy therapies demonstrate value to payers and regulators.
Next-generation anti-CD20 monoclonal antibodies with enhanced antibody-dependent cellular cytotoxicity profiles are decomposing the rituximab standard-of-care monopoly. Academic medical centers in Germany and the United States are piloting these agents in steroid-sparing protocols. The structural consequence is margin compression for originator biologics as biosimilar and bio-better competition intensifies.
FDA's accelerated approval pathway revisions are tightening proteinuria surrogate validation requirements while expanding pre-approval access for refractory subsets. Developers must now commit to post-marketing renal function studies as a condition of initial authorization. Small-cap biotech firms without registry infrastructure are partnering with large nephrology networks to meet these obligations.
Hospital procurement officers are unbundling biologic infusion services from pharmacy reimbursement, creating separate contracting tiers for drug acquisition and administration. Specialty pharmacy networks are capturing administration margin that previously accrued to infusion centers. This shift is most advanced in United States Medicare Advantage plans and German sickness funds.
Membranous Nephropathy Treatment Market Segmentation
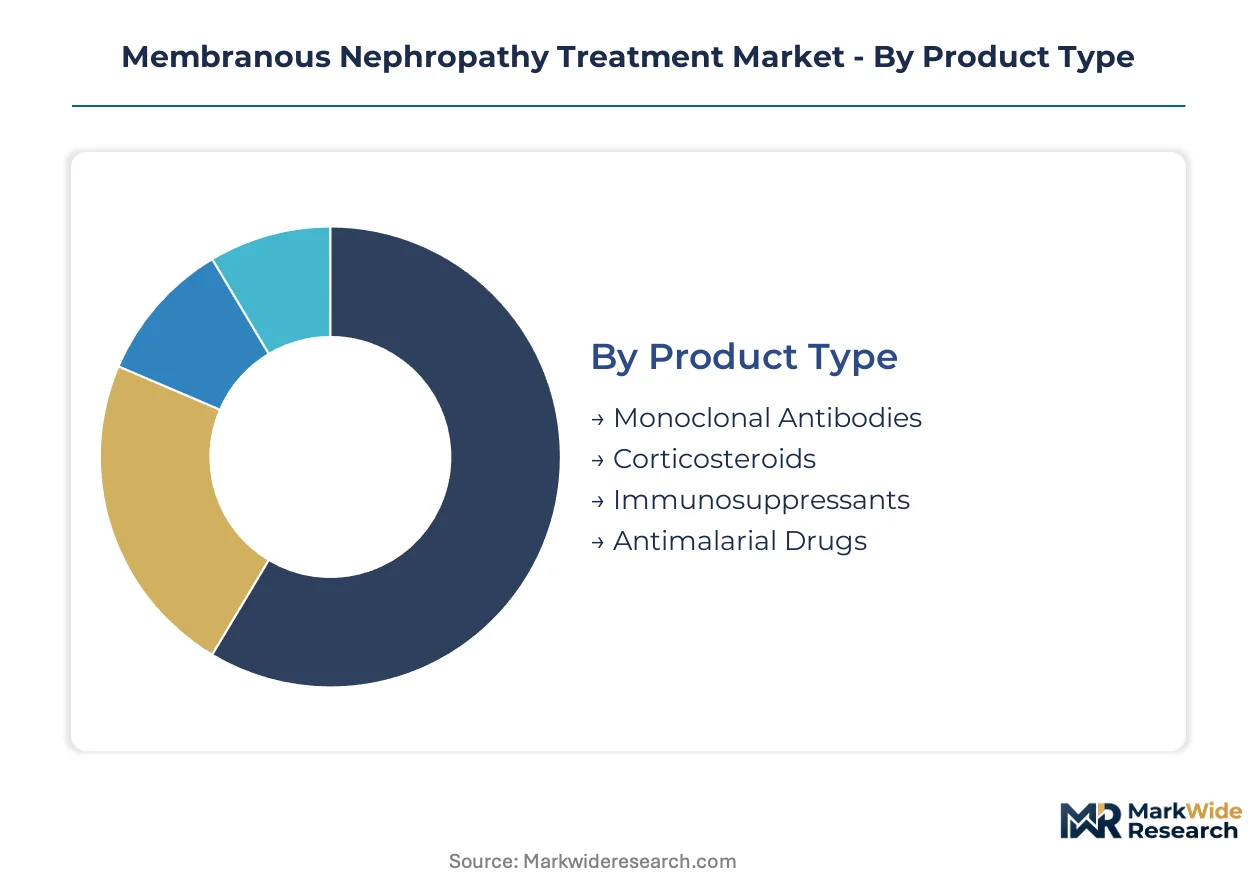
Treatment selection in membranous nephropathy hinges on disease severity, payer coverage tiers, and infusion infrastructure availability. Channel dynamics vary sharply across biologics requiring cold-chain hospital delivery versus oral agents dispensed through retail pharmacy networks.
Product Type:
Monoclonal antibodies flow through hospital-based specialty pharmacies with dedicated infusion centers, while corticosteroids and immunosuppressants distribute via standard retail and mail-order channels with broader geographic reach.
- Monoclonal Antibodies:Engineered B-cell depleting agents target CD20 surface markers with precision dosing protocols. Academic medical centers in the United States concentrate demand for rituximab-class alternatives as payers expand prior authorization for steroid-sparing regimens.
- Corticosteroids:Generic prednisone remains the volume backbone despite toxicity concerns, with cyclophosphamide protocols still standard in cost-constrained health systems. India and Southeast Asian markets anchor procurement for oral corticosteroid regimens where biologic penetration faces reimbursement barriers.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites serve as bridging therapy or combination partners in tertiary care protocols.
- Antimalarial Drugs:Hydroxychloroquine derivatives occupy niche symptomatic management roles in select European protocols.
By volume, corticosteroids lead. By growth pace, monoclonal antibodies are climbing the fastest.
End User:
Procurement authority splits between hospital pharmacy committees controlling biologic formularies and specialty pharmacy networks capturing administration margin through unbundled reimbursement structures.
- Hospitals:Tertiary nephrology departments command biologic infusion volume with integrated care pathways for refractory cases. German university hospitals and United States academic medical centers drive protocol innovation for combination immunotherapy regimens.
- Clinics:Community nephrology practices manage stable patients on oral immunosuppressant maintenance with laboratory monitoring.
- Homecare:Subcutaneous formulation approvals are opening self-administration channels that bypass traditional infusion center controls.
- Specialty Pharmacies:United States Medicare Advantage plans and German sickness funds are unbundling drug acquisition from administration reimbursement, shifting margin to external pharmacy networks.
By patient volume, hospitals dominate. By margin capture, specialty pharmacies are gaining share fastest.
Administration Route:
Route selection determines site-of-care economics and patient compliance profiles, with subcutaneous alternatives disrupting traditional intravenous infusion dependencies.
- Intravenous:Infusion center delivery of monoclonal antibodies generates bundled reimbursement with nursing supervision. Swiss and Irish contract manufacturing concentration creates supply vulnerability for intravenous biologics dependent on mammalian cell culture capacity.
- Subcutaneous:Self-administered rituximab biosimilars are penetrating United States and European markets as home infusion channels mature.
- Oral:Corticosteroid and immunosuppressant tablets dominate emerging market access where cold-chain infrastructure is limited.
- Intramuscular:Depot formulations serve niche maintenance protocols in select European jurisdictions.
By protocol prevalence, intravenous leads. By expansion trajectory, subcutaneous is ahead.
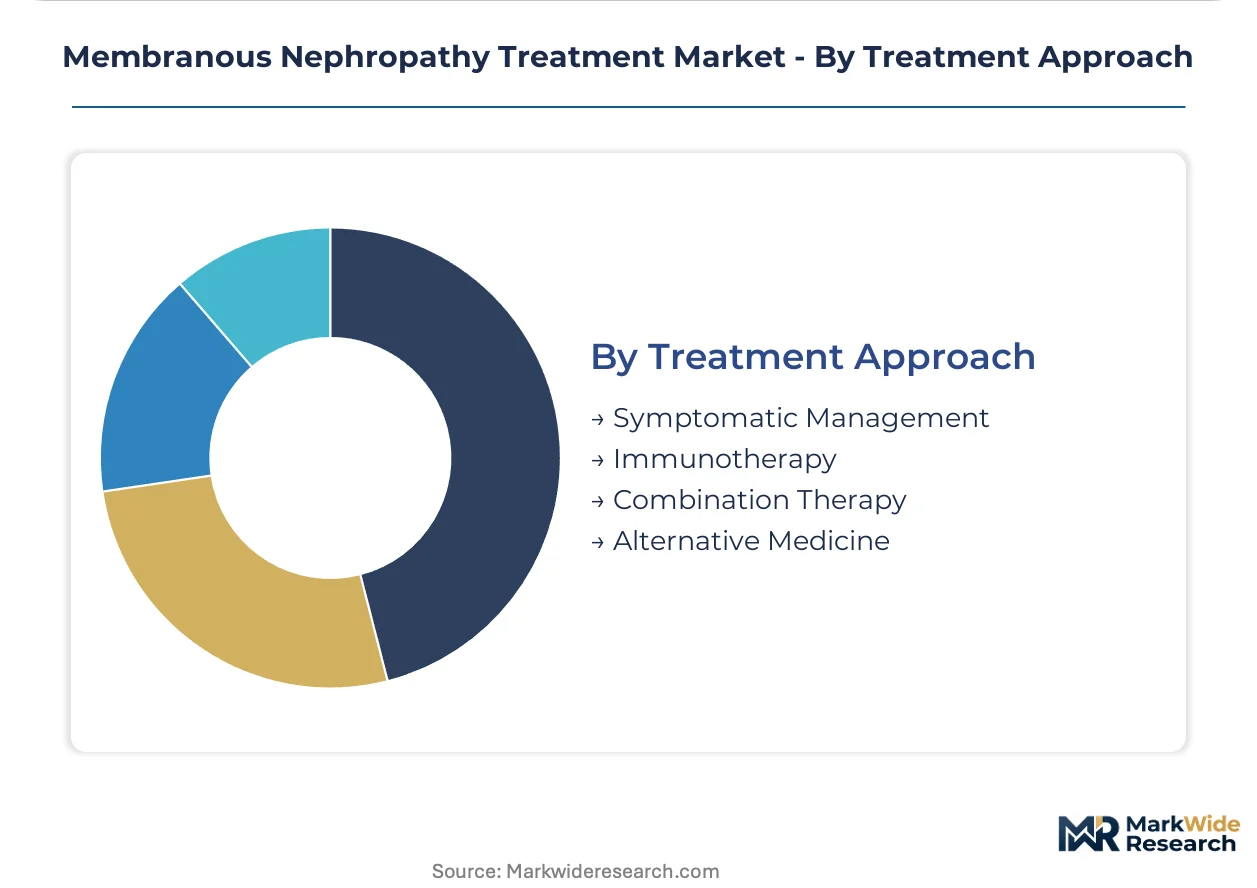
Treatment Approach:
Approach selection reflects disease severity stratification and payer evidence requirements for proteinuria reduction endpoints.
- Immunotherapy:B-cell modulating protocols achieve proteinuria thresholds below 3.5 g/day in anti-PLA2R positive cohorts. FDA accelerated approval pathways are tightening evidentiary standards for surrogate endpoints while expanding pre-approval access for refractory subsets.
- Combination Therapy:Pairing monoclonal antibodies with calcineurin inhibitors optimizes remission durability in academic medical center protocols. EMA conditional marketing authorizations are shortening commercialization horizons for developers with biomarker-guided trial designs.
- Symptomatic Management:ACE inhibitors and antihypertensive regimens address proteinuria without disease modification.
- Alternative Medicine:Unregulated supplement use persists in patient-driven care outside formal nephrology oversight.
By current adoption, symptomatic management leads. By clinical investment, combination therapy is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a significant import surplus in biologics-grade monoclonal antibodies while exporting corticosteroid formulations to emerging markets. Switzerland and Ireland dominate contract manufacturing exports for mammalian cell culture-derived therapies. India's pharmaceutical sector supplies generic immunosuppressants across Southeast Asia and Africa.
United States
Tertiary care centers in Boston and New York drive protocol adoption for combination immunotherapy regimens targeting refractory membranous nephropathy. The FDA's accelerated approval pathway compresses commercialization timelines for biologics developers with validated proteinuria surrogate endpoints. Academic medical centers in the Research Triangle and Texas Medical Center anchor clinical trial recruitment for next-generation B-cell modulators.
Germany
University hospitals in Munich and Heidelberg pioneer steroid-sparing protocols pairing monoclonal antibodies with calcineurin inhibitors. EMA conditional marketing authorizations expand pre-approval access for refractory patient subsets while demanding post-marketing renal function data. The Rhine-Ruhr pharmaceutical corridor concentrates biologics distribution infrastructure serving Central and Eastern European markets.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich control critical mammalian cell culture capacity for monoclonal antibody production. Swissmedic maintains stringent quality frameworks that elevate manufacturing compliance costs for scaled biologics operators. The Lake Geneva biotech cluster hosts headquarters operations for firms developing next-generation anti-CD20 agents.
India
Specialty hospitals in Mumbai and Delhi drive demand for cost-effective corticosteroid and cyclophosphamide protocols where biologic penetration faces reimbursement constraints. CDSCO accelerated pathways streamline review timelines for autoimmune nephrology indications, attracting multinational trial investment. The Hyderabad-Visakhapatnam pharmaceutical belt manufactures generic immunosuppressants for export to African and Southeast Asian markets.
Japan
PMDA's structured consultation pathways guide developers through evidentiary requirements for proteinuria surrogate endpoints in nephrology indications. Tokyo and Osaka academic medical centers concentrate demand for rituximab-class therapies in aging populations with high autoimmune disease prevalence. The Kansai region's biomedical manufacturing base supplies precision dosing formulations for B-cell depleting protocols across East Asian markets.
Membranous Nephropathy Treatment Market Competitive Environment
Listed leaders compete with private specialists across antibody engineering capabilities and immunology franchise depth. The market structure concentrates around three tiers: oncology-bred biologics majors, dedicated immunology houses, and diversified pharmaceutical conglomerates with manufacturing scale advantages. Strategic archetypes include B-cell pathway specialists, calcineurin inhibitor portfolio holders, and corticosteroid cost leaders. Competitive moves center on biosimilar pre-positioning and real-world evidence registry construction.
Within the biologics tier, Roche and AbbVie exemplify contrasting strategic positions. Roche anchors the B-cell modulating pathway segment through antibody engineering infrastructure inherited from oncology development programs. AbbVie occupies a position within the immunology franchise tier, leveraging specialty pharmacy network relationships across United States and European markets. Amgen represents the scale-driven archetype with manufacturing infrastructure supporting global supply security for combination therapy components.
| Leading Market Players |
|---|
| Amgen |
| AbbVie |
| Roche |
| Novartis International AG |
| FibroGen |
| Pfizer |
| Allergan |
| Bristol-Myers Squibb Company |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Ninety-day cold-chain inventory buffers for monoclonal antibodies concentrate pricing power with Swiss and Irish contract manufacturers while exposing buyers to temperature excursion cost pass-throughs. Hospital pharmacy committees absorb margin compression from unbundled administration reimbursement, shifting procurement leverage toward specialty pharmacy networks that capture infusion service margins separately from drug acquisition costs.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures where proteinuria reduction thresholds determine reimbursement tiers across United States Medicare Advantage and German sickness fund formularies. Price differentiation rests on FDA accelerated approval status versus EMA conditional authorization, with anti-PLA2R biomarker stratification commanding premium positioning. Cost compression in corticosteroid tiers intensifies because generic prednisone and cyclophosphamide face cyclical API oversupply from Indian manufacturers. Emerging market procurement officers exhibit highest price sensitivity, while academic medical centers in Boston and Heidelberg accept premium biologic positioning for steroid-sparing protocols.
Supply Chain Analysis
Mammalian cell culture capacity chokepoints in Basel and Zurich tether global monoclonal antibody supply to Swissmedic quality enforcement timelines and EPA biologics manufacturing mandates. Raw material dependencies center on Chinese-sourced recombinant proteins, Irish-filtered cell culture media, and German-engineered precision dosing formulations. Single-source vulnerability concentrates in CD20-targeting antibody production where Roche and AbbVie control overlapping patent estates. Distribution runs through hospital-based specialty pharmacies with dedicated infusion centers, though subcutaneous biosimilar approvals are fragmenting channel control toward homecare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in membranous nephropathy treatment outpace hardware margins as real-world evidence registry subscriptions and biomarker-guided patient monitoring contracts expand faster than biologic drug sales. Post-marketing renal function study obligations create recurring revenue layers that differentiate developers with captive data infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into mammalian cell culture capacity and captive quality infrastructure that satisfies EPA and OSHA fixed cost barriers. Threats from subcutaneous rituximab biosimilars bypassing hospital pharmacy controls demand channel unbundling responses. Prioritize calcineurin inhibitor portfolio depth to anchor combination therapy protocols against B-cell modulator substitution. For New Entrants and Emerging Players: CDSCO accelerated pathways for autoimmune nephrology indications offer fastest regulatory traction for trial investment in Mumbai and Delhi specialty hospital networks. White-space concentrates in India and Southeast Asia where corticosteroid substitution pressure limits premium biologic penetration. Target cost-effective oral immunosuppressant formulations with localized manufacturing partnerships as the most penetrable entry vector. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized nephrology assets and dormant biologic manufacturing infrastructure. Long-term viability across the analysis window hinges on real-world evidence registry capabilities that satisfy payer demands for post-marketing proteinuria data. Watch FDA proteinuria surrogate endpoint validation tightening as the inflection signal distinguishing viable biologic developers from compliance-burdened laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Registry Construction | Post-marketing proteinuria data obligations differentiate developers for payer access negotiations. |
| Subcutaneous Formulation Development | Self-administered biosimilars bypass hospital infusion center controls and capture homecare margin. |
| Biomarker-Guided Trial Design | Anti-PLA2R stratification improves response signal detection for FDA accelerated approval pathways. |
| CDSCO Accelerated Pathway Engagement | Streamlined Indian regulatory review attracts multinational investment for cost-constrained market entry. |
| Specialty Pharmacy Network Partnership | Unbundled reimbursement structures shift administration margin toward external pharmacy channels. |
Study Parameters
Operator-level perspectives from hospital procurement managers, formulary directors, nephrology department heads, and payer access specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement database trends. Secondary validation drew from CMS Medicare reimbursement data, German sickness fund formulary decisions, and Swissmedic manufacturing compliance disclosures. Bottom-up patient flow modeling and top-down pharmaceutical revenue estimates converged across segmentation dimensions.
Sensitivity analysis tested forecast robustness across alternative proteinuria surrogate endpoint validation scenarios and biosimilar penetration trajectories throughout the projection horizon. The analytical framework modeled treatment approach, administration route, end-user channel, and regional regulatory cluster as primary segmentation dimensions. CAGRs derived from patient population epidemiology, protocol adoption curves in academic medical centers, and biologic pricing elasticity assumptions. Forecast inputs incorporated anti-PLA2R testing penetration rates and corticosteroid substitution pressure indices by geography.
Underlying assumptions cover stable FDA accelerated approval pathway continuity, EMA conditional marketing authorization precedent maintenance, and Swiss-Irish manufacturing capacity expansion alignment with demand growth, with deviation risk concentrated in health technology assessment timeline compression and cold-chain integrity failures during multi-site distribution. Revision becomes warranted when health technology assessment bodies recalibrate proteinuria value thresholds or biosimilar temperature excursion rates cross reliability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
End Stage Renal Disease Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Plasmapheresis Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Hemodialysis Market
Nephrology
Global Dialysis Market
Nephrology
Renal Artery Embolization Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
US Dialysis Centers Market