
 Global Artificial Kidney Market | 2026-2036
Global Artificial Kidney Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Kidney Market Foresight
Aftermarket service revenue is reshaping profit pools across the artificial kidney landscape. Fresenius Medical Care AG leverages its vertically integrated dialysis clinic network to capture recurring consumables income. Baxter International Inc. sustains competitive advantage through peritoneal dialysis fluid logistics and remote patient monitoring infrastructure.
An artificial kidney is a bioengineered or electromechanical device designed to replicate renal filtration, typically employing semipermeable membranes with pore sizes of 0.1–10 nanometers to clear urea, creatinine, and excess electrolytes from blood or peritoneal fluid without transplantation. Its primary purpose is sustaining metabolic homeostasis in patients with end-stage renal disease when donor organs remain scarce. Wearable devices command premium pricing due to patient mobility gains, while implantable devices represent the fastest-growing segment as regenerative medicine advances reduce immunosuppression burdens. Hemodialysis systems retain the largest installed base but face margin compression from commoditized dialyzer manufacturing.
The FDA's Breakthrough Device Designation and the EU Medical Device Regulation (MDR) impose divergent evidence standards that fragment commercialization timelines for bioartificial platforms. Japan's PMDA accelerates conditional approval for renal assist devices through its Sakigake fast-track pathway, creating a regulatory arbitrage opportunity for developers with robust Japanese clinical data. Stakeholders must monitor reimbursement parity between home-based and in-center modalities as portable technologies mature.
Market Dynamics
Portable renal replacement technologies are compressing treatment delivery from clinical settings into domestic environments, forcing incumbents to reconfigure service revenue models around remote monitoring and consumables logistics rather than facility-based care.
Growth Catalysts
- Medicare reimbursement reforms:The United States' expanded coverage for home-based dialysis modalities reduces patient out-of-pocket burdens and accelerates portable device uptake among Medicare beneficiaries.
- Sakigake fast-track pathway:Japan's PMDA conditional approval mechanism shortens time-to-market for renal assist devices, attracting developers with robust Japanese clinical trial portfolios.
- Silicon nanopore membranes:Advances in nanofabrication enable smaller, more efficient filtration surfaces that reduce device footprint while maintaining urea clearance rates comparable to conventional dialyzers.
Market Restraints
- Polymer supply concentration:High-grade polysulfone and polyethersulfone membrane materials depend on a limited supplier base concentrated in Germany and Japan, exposing manufacturers to input cost volatility.
- EU MDR evidence requirements:The European Union's Medical Device Regulation imposes extended clinical evaluation timelines for bioartificial platforms, fragmenting commercialization schedules relative to FDA pathways.
- Transplantation substitution:Living donor programs and paired exchange networks in high-income countries retain preference for biological kidney replacement where donor availability permits.
Strategic Opportunities
- India's tier-2 cities:Dialysis penetration remains below 15% in secondary urban centers outside Delhi and Mumbai, creating whitespace for portable device deployment through hub-and-spoke distribution models.
- Peritoneal dialysis convergence:Integration of wearable artificial kidneys with existing peritoneal catheter infrastructure offers hybrid therapy pathways for patients with residual renal function.
- Breakthrough Device Designation:The FDA's accelerated review pathway for bioartificial prototypes enables priority regulatory engagement and earlier reimbursement discussions for qualifying developers.
Industry Challenges
- Bioengineer talent scarcity:Cross-disciplinary expertise combining nephrology, membrane science, and implantable device engineering remains concentrated in a handful of academic medical centers in the United States and Switzerland.
- Biocompatibility certification timelines:ISO 10993-compliant cytotoxicity and sensitization testing for novel membrane materials extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Kidney Market |
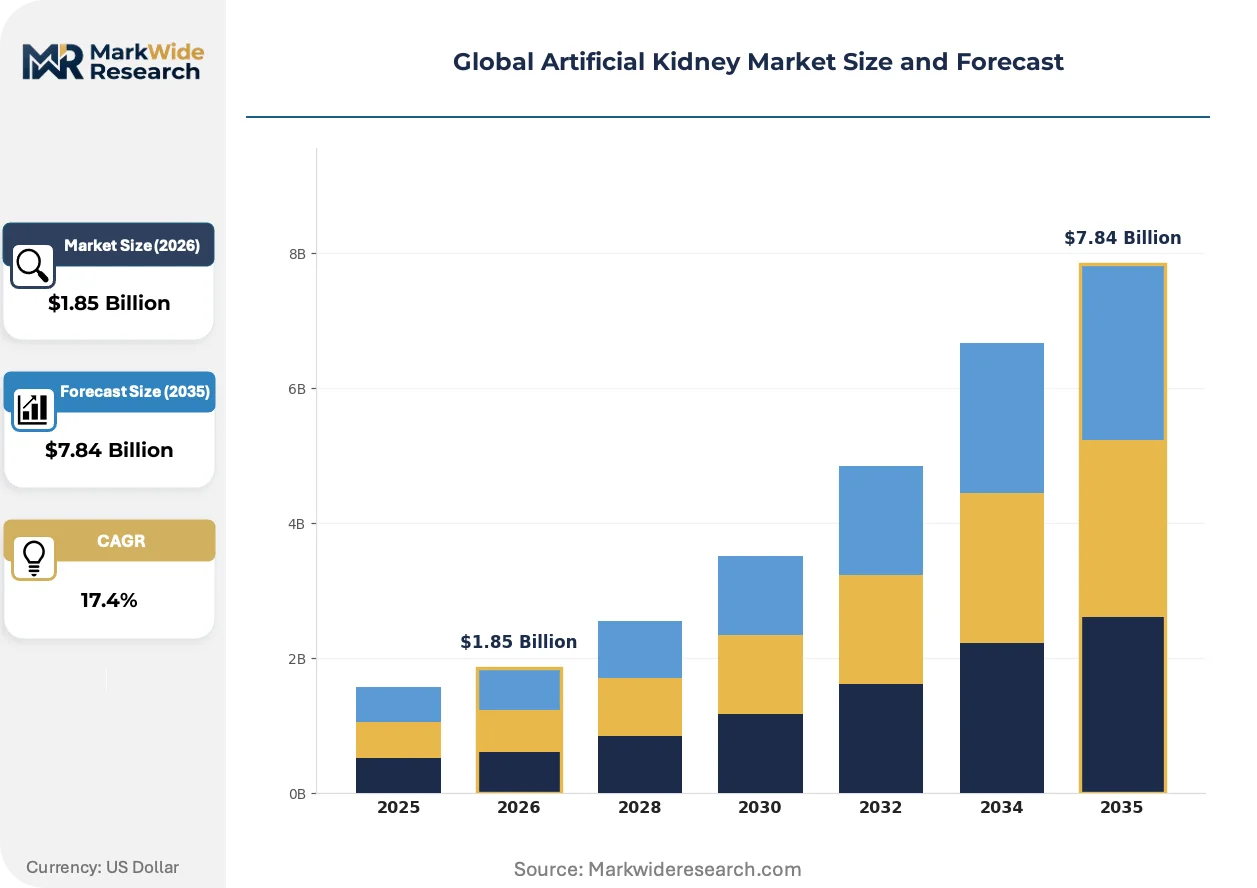
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Portable Machines, Hemodialysis Systems End User: Home Care, Hospitals, Dialysis Centers, Specialty Clinics Technology: Nanotechnology, Biocompatible Materials, Microfiltration, Regenerative Medicine Application: Chronic Kidney Disease, Acute Renal Failure, Transplantation Support, Emerging Therapies |
| Companies Covered | Fresenius Medical Care AG, Baxter International Inc., Medtronic, B. Braun Melsungen AG, Nipro Corporation, DaVita Inc., Asahi Kasei Medical Co. Ltd., Nikkiso Co. Ltd., Outset Medical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Kidney Market Shifts & Advancements
Regenerative medicine capabilities are merging with electromechanical filtration systems, producing hybrid platforms that reduce immunosuppression requirements while maintaining metabolic homeostasis. This convergence is redrawing competitive boundaries between dialysis incumbents and cell therapy specialists.
Silicon nanopore membrane technology is digitizing renal filtration by enabling real-time clearance monitoring through integrated biosensors. Wearable device manufacturers in the United States and Japan are embedding these membranes into compact cartridges that transmit solute clearance data to cloud-based clinical dashboards. The technology is digitizing patient management workflows, compressing the interval between treatment anomalies and clinical intervention from days to hours.
The EU Medical Device Regulation's heightened clinical evidence requirements are extending market access timelines for bioartificial kidney developers seeking CE marking. Manufacturers must now submit prospective safety data from European patient cohorts rather than relying on FDA 510(k) equivalency determinations. Implantable device segments face the steepest compliance burdens, prompting some developers to sequence EU launches behind US commercialization.
Home-based therapy procurement is consolidating purchasing decisions from individual nephrologists to integrated dialysis provider networks with centralized technology assessment committees. These committees evaluate total cost-of-ownership metrics including training, remote monitoring infrastructure, and consumables logistics. The United States exhibits the most pronounced consolidation, where large dialysis organizations now control device selection for over 70% of home dialysis initiations.
Global Artificial Kidney Market Segmentation
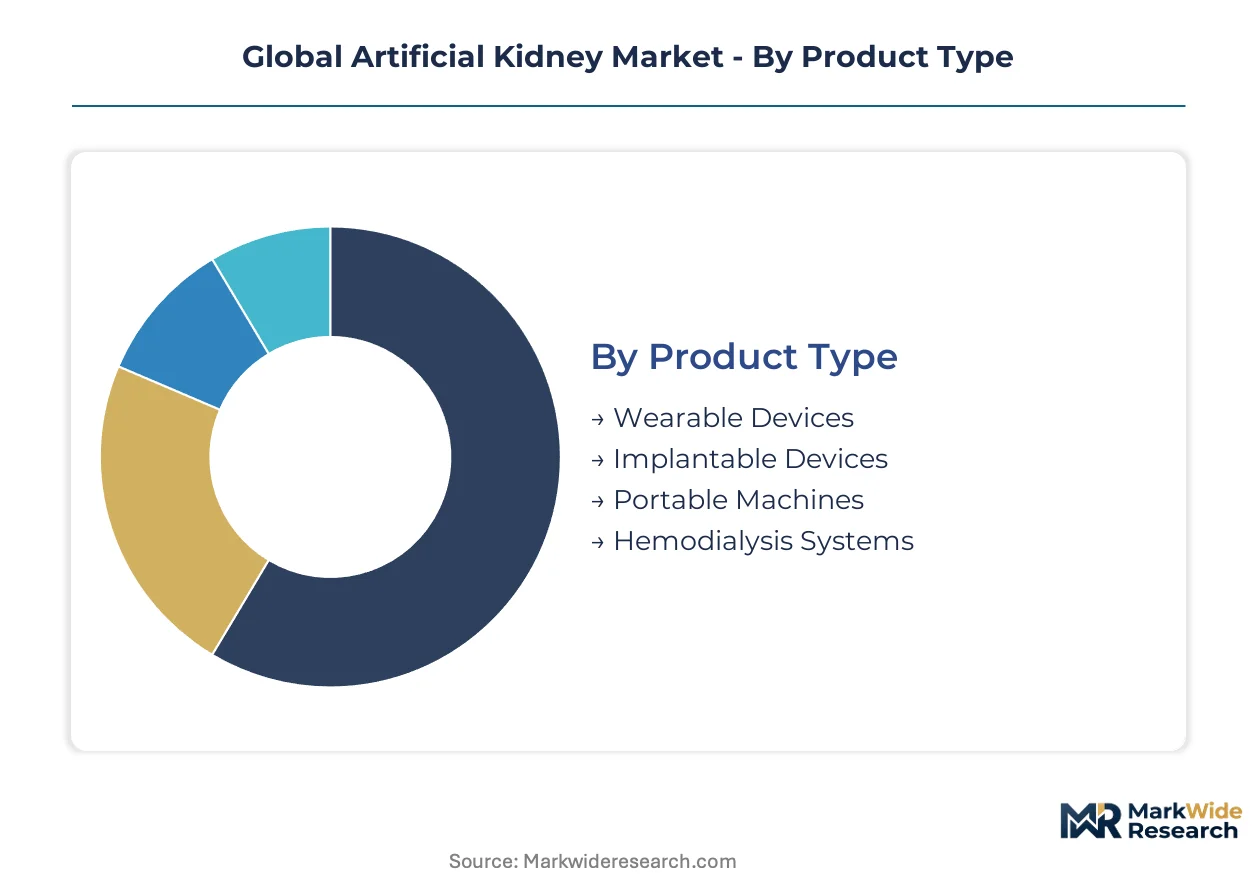
Segmentation in the artificial kidney market reflects divergent patient mobility requirements, clinical infrastructure availability, and reimbursement pathways across care settings. Understanding these divides enables manufacturers to align device specifications with specific regulatory and procurement environments rather than pursuing undifferentiated commercialization strategies.
Product Type:
Use-case spectrum spans from mobility-restoring wearables for employed patients to permanent implantables eliminating clinic dependency entirely.
- Wearable Devices:Belt-mounted or vest-integrated systems employ silicon nanopore membranes with integrated biosensors for real-time clearance monitoring. Demand concentrates among employed Medicare beneficiaries in the United States seeking to maintain occupational activity during treatment, driven by CMS reimbursement parity reforms for home-based modalities.
- Implantable Devices:Bioartificial constructs combining electromechanical filtration with living renal cells require immunosuppression protocols but eliminate external hardware. Japanese developers leveraging the PMDA Sakigake pathway are advancing conditional approvals fastest, attracted by compressed regulatory timelines relative to FDA PMA processes.
- Portable Machines:Compact hemodialysis units designed for domestic environments with reduced water and power requirements compared to clinical systems.
- Hemodialysis Systems:Conventional clinic-based machines with established reimbursement codes but facing margin pressure from commoditized dialyzer manufacturing.
The dominant share belongs to Hemodialysis Systems, while Implantable Devices is closing the gap fastest.
End User:
Cost tier differentiation separates capital-intensive hospital deployments from distributed home care models with recurring consumables revenue.
- Home Care:Patient-managed therapy environments requiring remote monitoring infrastructure and consumables logistics networks. United States large dialysis organizations now control device selection for over 70% of home initiations, consolidating procurement decisions away from individual nephrologists.
- Hospitals:Acute care settings managing acute renal failure and transplantation support with intensive monitoring capabilities and immediate surgical backup.
- Dialysis Centers:Dedicated outpatient facilities capturing economies of scale through high patient throughput and standardized treatment protocols.
- Specialty Clinics:Nephrology-focused practices offering personalized care coordination and early technology access for eligible patients.
Home Care commands expanding reimbursement bandwidth, while Specialty Clinics are gaining share fastest among early-adopter populations.
Technology:
Volume concentration tracks manufacturing maturity, with nanofabrication approaches scaling more slowly than established membrane chemistries.
- Nanotechnology:Silicon nanopore membranes enabling 0.1–10 nanometer precision filtration with embedded biosensor integration. United States and Japanese manufacturers are embedding these into compact cartridges transmitting clearance data to cloud-based clinical dashboards, compressing anomaly response intervals from days to hours.
- Biocompatible Materials:Polysulfone and polyethersulfone membranes with ISO 10993-compliant certification, constrained by supplier concentration in Germany and Japan exposing manufacturers to input cost volatility.
- Microfiltration:Conventional pore-based separation technologies with established manufacturing infrastructure and lower unit economics.
- Regenerative Medicine:Cell-based approaches combining tissue engineering with mechanical filtration, extending development cycles by 18–24 months for cytotoxicity and sensitization testing.
Biocompatible Materials retains installed base dominance, though Nanotechnology is expanding most quickly through wearable device integration.
Application:
Customer type stratification separates chronic maintenance populations from acute intervention episodes with divergent device performance requirements.
- Chronic Kidney Disease:Long-term management of end-stage renal disease representing the addressable base for home-based and wearable technologies. India's tier-2 cities outside Delhi and Mumbai present whitespace opportunity with dialysis penetration below 15% and hub-and-spoke distribution potential.
- Acute Renal Failure:Critical care settings requiring rapid intervention with continuous renal replacement therapy capabilities and intensive monitoring.
- Transplantation Support:Bridge-to-transplant or organ preservation applications competing with living donor programs where donor availability permits.
- Emerging Therapies:Investigational indications including sepsis-associated acute kidney injury and pediatric applications with evolving evidence bases.
Chronic Kidney Disease anchors revenue concentration, while Emerging Therapies shows steepest expansion trajectory through expanded indication development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade polysulfone and polyethersulfone membrane materials concentrate in Germany and Japan, exposing artificial kidney manufacturers to input cost volatility while creating regional supply dependencies that shape commercialization strategies.
United States
Medicare reimbursement reforms for home-based dialysis modalities reduce patient out-of-pocket burdens and accelerate portable device uptake among beneficiaries. The FDA's Breakthrough Device Designation pathway accelerates regulatory timelines for bioartificial kidney prototypes. Large dialysis organizations in the United States now control device selection for over 70% of home dialysis initiations, consolidating procurement decisions away from individual nephrologists.
Germany
Polysulfone membrane manufacturing clusters in Germany supply high-grade filtration materials to global dialyzer producers, creating captive supply relationships with downstream device manufacturers. The EU Medical Device Regulation imposes extended clinical evaluation timelines for bioartificial platforms, fragmenting commercialization schedules relative to FDA pathways. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia hosts membrane chemistry specialists and precision engineering firms serving renal replacement technology developers.
Japan
The PMDA's Sakigake fast-track pathway shortens time-to-market for renal assist devices, attracting developers with robust Japanese clinical trial portfolios. Conditional approval mechanisms enable earlier patient access while post-market surveillance requirements ensure safety monitoring. Tokyo and Osaka metropolitan areas concentrate bioengineer expertise combining nephrology, membrane science, and implantable device engineering.
India
Dialysis penetration remains below 15% in tier-2 cities outside Delhi and Mumbai, creating whitespace for portable device deployment through hub-and-spoke distribution models. CDSCO regulatory pathways for medical devices are streamlining import and local manufacturing approvals for renal replacement technologies. Maharashtra and Karnataka host emerging medical device manufacturing corridors targeting domestic production of dialysis consumables and portable systems.
Switzerland
Cross-disciplinary bioengineer expertise combining nephrology, membrane science, and implantable device engineering concentrates in Swiss academic medical centers and research institutes. Swissmedic maintains rigorous pre-market approval standards for implantable renal devices while offering scientific advice pathways for novel technology developers. The Basel and Zurich regions anchor precision manufacturing capabilities for miniaturized filtration components and biosensor integration.
Global Artificial Kidney Market Competitive Landscape
Vertically integrated dialysis service providers and standalone device manufacturers split the market along recurring revenue versus capital equipment lines. Consolidation among large dialysis organizations in the United States compresses vendor selection to centralized technology assessment committees evaluating total cost-of-ownership metrics. Three strategic archetypes dominate: clinic network operators capturing consumables income, precision membrane specialists supplying filtration components, and wearable technology developers pursuing regulatory fast-tracks. Competitive moves center on backward integration into membrane manufacturing and geographic sequencing of regulatory submissions to exploit pathway timing differentials.
Among Germany-based diversified healthcare conglomerates, Fresenius Medical Care AG and B. Braun Melsungen AG exemplify vertically integrated archetypes combining device manufacturing with service delivery infrastructure. Baxter International Inc., an Illinois-based corporation, occupies a position within the peritoneal dialysis and fluid logistics segment. Japanese specialists Asahi Kasei Medical Co. Ltd. and Nikkiso Co. Ltd. represent precision membrane and equipment manufacturing archetypes with concentrated expertise in filtration component engineering.
| Leading Market Players |
|---|
| Fresenius Medical Care AG |
| Baxter International Inc. |
| Medtronic |
| B. Braun Melsungen AG |
| Nipro Corporation |
| DaVita Inc. |
| Asahi Kasei Medical Co. Ltd. |
| Nikkiso Co. Ltd. |
| Outset Medical Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on high-grade polysulfone membrane production in Germany and Japan determines both pricing tier spreads and supply chain shape, forcing manufacturers to absorb input volatility or pass through cost escalations to buyers locked into long-term service contracts.
Pricing Analysis
The FDA's Breakthrough Device Designation dictates the pricing tier structure for bioartificial kidney developers, creating premium positioning for qualifying devices against standard hemodialysis systems. Pricing stratifies across premium wearable tiers with embedded biosensors, standard portable machines for home deployment, and economy clinic-based systems facing commoditization. Cost compression in the hemodialysis segment is intensifying because dialyzer manufacturing has standardized around polysulfone membranes with limited differentiation. Large dialysis organizations exhibit lowest price sensitivity due to total cost-of-ownership evaluation frameworks, while independent specialty clinics remain most responsive to upfront capital expenditure differentials.
Supply Chain Analysis
Extended payment terms from German and Japanese membrane suppliers strain working capital for device assemblers, compressing cash conversion cycles and favoring vertically integrated manufacturers with captive polymer production. Manufacturing concentrates in Germany for polysulfone chemistry, Japan for precision membrane engineering, and the United States for wearable device integration. Raw material inputs draw from medical-grade polymer resins, silicon wafer substrates for nanopore fabrication, and biocompatible coatings requiring ISO 10993 certification. Single-source vulnerability in polyethersulfone supply exposes assemblers to disruption from regulatory inspections or force majeure events. Distribution runs through large dialysis organization procurement committees in the United States, hospital purchasing consortia in Western Europe, and hub-and-spoke logistics networks targeting India's tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA and PMDA fast-track pathways create multi-year head starts that compound through clinical data generation and reimbursement code capture.
For Market Incumbents: Harden market position by backward integration into membrane manufacturing to neutralize German and Japanese supplier leverage, while securing exclusive service contracts with large dialysis organizations that lock out emerging wearable competitors. Threats from silicon nanopore startups and Japanese bioartificial developers demand preemptive patent portfolio expansion around biosensor-integrated filtration cartridges. Priority investment in PMDA Sakigake pathway positioning secures conditional approval timing advantages against FDA PMA-track rivals. For New Entrants and Emerging Players: India's tier-2 cities outside Delhi and Mumbai present the most penetrable whitespace, with dialysis penetration below 15 percent and limited incumbent service infrastructure. Hub-and-spoke distribution partnerships with regional hospital networks offer lower customer acquisition costs than direct competition in saturated United States and Western European markets. Go-to-market execution should emphasize portable device deployment through consumables-subscription models that align with emerging CDSCO regulatory frameworks for medical device imports. For Investors and Strategic Acquirers: The market sits at a technology-convergence phase that favors precision membrane specialists with regulatory fast-track experience over pure-play service operators. Long-term viability across the analysis window hinges on successful navigation of EU MDR clinical evidence requirements and Medicare reimbursement parity maintenance for home-based modalities. Acquisition target archetypes include silicon nanopore membrane developers with embedded biosensor platforms and Japanese clinical trial portfolios. The signal to watch is PMDA conditional approval announcements for implantable bioartificial constructs, which would validate regenerative medicine integration timelines and trigger competitive response acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerates regulatory timelines and enables earlier Medicare reimbursement discussions for qualifying developers. |
| Silicon Nanopore Membrane Integration | Enables real-time clearance monitoring through embedded biosensors, differentiating wearable platforms from conventional dialyzers. |
| PMDA Sakigake Pathway Engagement | Compresses time-to-market for renal assist devices through Japanese conditional approval mechanisms. |
| Backward Integration into Membrane Manufacturing | Neutralizes supply concentration risk from German and Japanese polysulfone suppliers while capturing margin pool expansion. |
| Hub-and-Spoke Distribution in India | Addresses underpenetrated tier-2 cities through localized service infrastructure and CDSCO-compliant logistics networks. |
Research Methodology
Desk research of FDA 510(k) and PMA filings, PMDA approval databases, CMS Medicare reimbursement bulletins, and EU MDR technical documentation preceded structured interviews with dialysis clinic operations directors, biomedical engineering leads at academic medical centers, GPO contracts managers, and nephrology practice administrators. Primary fieldwork combined with secondary validation against hospital procurement databases, large dialysis organization financial disclosures, and membrane manufacturer trade flow records. Bottom-up device shipment modeling and top-down service revenue estimation were triangulated to produce segment-level outputs.
Analytical assumptions held reimbursement parity between home-based and in-center modalities stable across the projection horizon while varying regulatory pathway timing differentials between FDA, PMDA, and EU MDR frameworks. Segmentation modeling incorporated product type mobility tier, end-user procurement consolidation level, technology manufacturing maturity, and application chronicity. CAGRs were derived from installed base growth rates and consumables attach rate assumptions specific to wearable device adoption curves and implantable bioartificial development timelines.
Practitioners should monitor PMDA conditional approval decisions, CMS home dialysis reimbursement rate adjustments, and polysulfone supply contract renegotiations for early signals of trajectory revision. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and membrane material cost stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Video Dermatoscope Market
Medical Devices
France Drug Delivery Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Facial Implant Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Global on-Body Injectors Market