
 Saudi Arabia Aesthetic Devices Market | 2026-2036
Saudi Arabia Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Aesthetic Devices Market Analytics
The capability gap between capital-heavy laser platform manufacturers and lighter distributors is reorganizing competitive tiers across the Kingdom. Alma Lasers leverages its direct service infrastructure to anchor premium placements in Jeddah's dermatology corridor. Galderma S.A. sustains its position through injectable-focused channel control rather than device ownership. Candela Medical competes on specialized hair removal and vascular platforms that occupy distinct clinical niches.
Saudi Arabia aesthetic devices comprise electromechanical systems engineered to deliver controlled thermal, acoustic, or cryogenic energy to cutaneous or subcutaneous tissue, typically operating at wavelengths between 532 nm and 10,600 nm for laser modalities. These systems serve commercial purposes by enabling clinics to perform revenue-generating procedures with minimal downtime and repeatable outcomes. Laser devices dominate current procurement volumes due to their versatility across skin rejuvenation and hair removal applications, while radiofrequency platforms represent the fastest-growing category as practitioners seek alternatives for darker skin phototypes common in the Gulf population. Body contouring applications command premium pricing within the application area dimension, though skin rejuvenation generates higher absolute patient throughput across the Kingdom's expanding clinic base.
SFDA medical device registration requirements mandate clinical evidence and local authorized representation for all imported aesthetic systems, creating compliance barriers that favor established multinational suppliers with regulatory affairs capacity. The Saudi Food and Drug Authority also enforces post-market surveillance protocols that shape product liability exposure and service contract structures for distributors. MOHAP coordination with private healthcare licensing frameworks influences where clinics may deploy Class II and Class III energy-based devices. Stakeholders must monitor how Vision 2030 localization incentives alter distributor economics and whether domestic assembly partnerships emerge as a prerequisite for public hospital tenders.
Market Dynamics
SFDA medical device registration requirements are reorganizing competitive tiers across Saudi Arabia aesthetic devices, favoring multinational suppliers with established regulatory affairs infrastructure over smaller distributors lacking clinical evidence capabilities and local authorized representation.
Growth Catalysts
- Vision 2030 Healthcare Privatization:The Saudi government's push to privatize healthcare facilities is expanding the addressable clinic base for energy-based aesthetic systems, particularly in Riyadh and Jeddah where dermatology center construction accelerates.
- Radiofrequency Platform Versatility:Radiofrequency devices address the Gulf population's darker skin phototypes with reduced post-inflammatory hyperpigmentation risk compared to laser alternatives, expanding treatable patient populations.
- Jeddah Dermatology Corridor Expansion:Premium clinic clusters along Jeddah's western coastal zone are procuring multi-modality platforms to capture medical tourism flows from neighboring GCC states.
Market Restraints
- SFDA Registration Capital Requirements:Clinical evidence generation and local authorized representation mandates impose six-figure compliance costs that exclude smaller distributors from Class III energy-based device markets.
- Service Infrastructure Concentration:Technical service capabilities for laser and radiofrequency platforms concentrate with multinational direct operations, creating single-source dependencies for maintenance and calibration.
- Substitution by Injectable Protocols:Neurotoxin and hyaluronic acid filler regimens compete for facial rejuvenation spending with lower capital requirements and faster provider training curves.
Strategic Opportunities
- Eastern Province Clinic Penetration:Dammam and Khobar maintain lower aesthetic device density than Riyadh and Jeddah, presenting first-mover positioning for platform suppliers establishing service hubs.
- Combination Therapy Protocol Development:Sequential radiofrequency and laser treatments for body contouring command premium pricing through outcome differentiation and extended patient engagement.
- Domestic Assembly Partnerships:Vision 2030 localization incentives may reward manufacturers establishing Saudi-based device assembly or refurbishment operations with preferential public hospital tender access.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Laser and radiofrequency platform maintenance requires specialized photonics and electromechanical expertise that Saudi technical training programs have not scaled to match clinic expansion rates.
- SFDA Post-Market Surveillance Burden:Adverse event reporting and periodic safety update submission obligations consume distributor operational bandwidth and reshape service contract economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Aesthetic Devices Market |
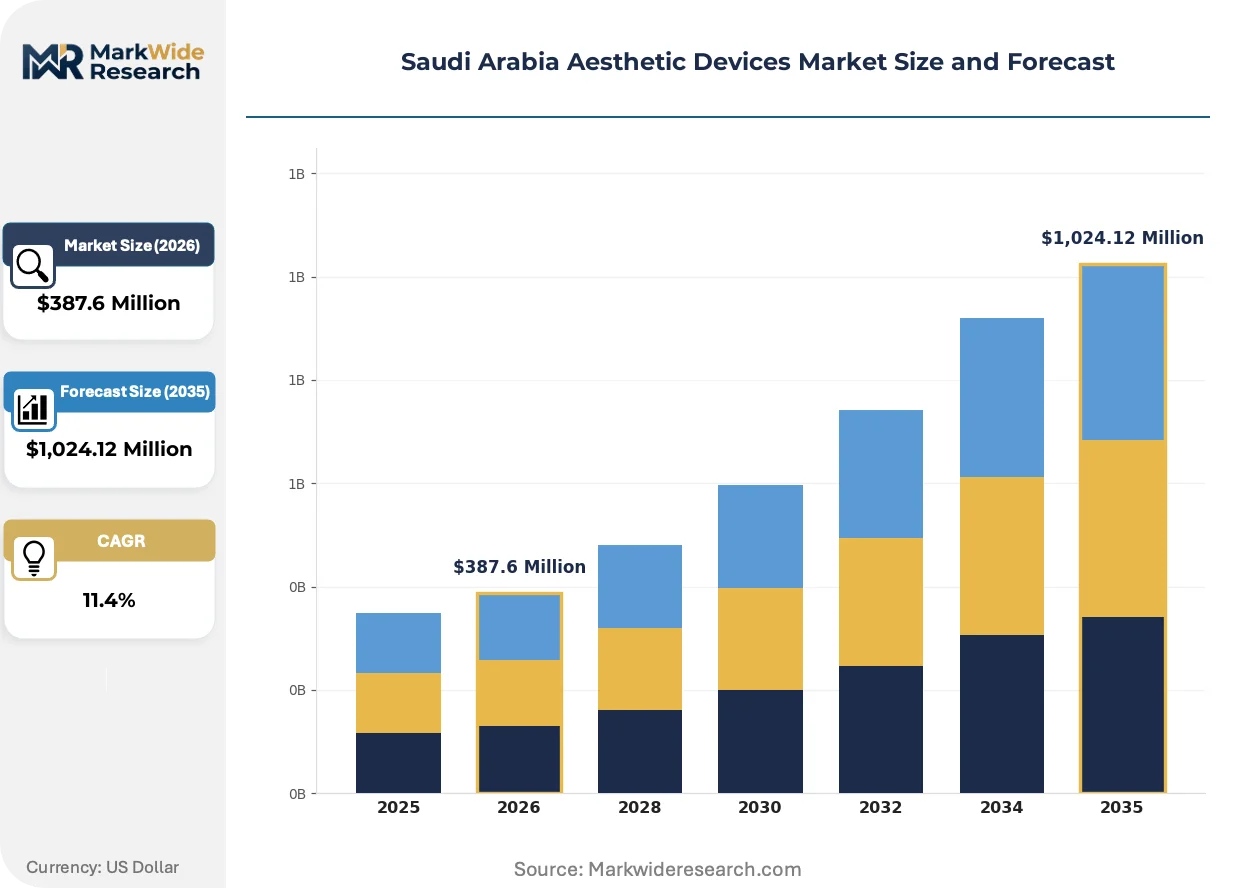
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Devices, Ultrasound Devices, Radiofrequency Devices, Cryotherapy Devices Application Area: Skin Rejuvenation, Body Contouring, Hair Removal, Tattoo Removal End User: Clinics, Dermatology Centers, Beauty Salons, Hospitals Service Type: Non-Invasive, Minimally Invasive, Surgical, Aesthetic |
| Companies Covered | Galderma S.A., Sinclair Pharma PLC, Lumenis Inc., Cynosure, Kalium Group, Candela Medical, Alma Lasers (Sisram Medical), Merz Pharma, AbbVie Inc (Allergan Aesthetics), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Aesthetic Devices Market Evolving Landscape
Energy delivery modalities and procurement structures are converging to reshape how Saudi clinics acquire and deploy aesthetic systems, with technology choices increasingly tied to service model preferences rather than standalone device specifications.
Fractional radiofrequency microneedling platforms are displacing traditional ablative laser systems in Saudi dermatology centers serving darker skin phototypes. Riyadh's premium clinic clusters adopted these devices at accelerated rates during 2023-2024 procurement cycles. The shift is compressing demand for CO2 laser resurfacing platforms while expanding treatable patient populations previously excluded due to melanin-related complication risks.
SFDA post-market surveillance protocols now mandate systematic adverse event reporting and periodic safety updates for all registered aesthetic energy devices. This regulatory tightening elevates compliance costs for distributors and favors suppliers with dedicated Saudi regulatory affairs staff. Class III laser platform providers have responded by restructuring service contracts to bundle compliance support with maintenance agreements.
Clinic procurement committees now prioritize total cost-of-ownership calculations over upfront device pricing when evaluating aesthetic platform acquisitions. Saudi dermatology groups with multiple locations are consolidating vendor relationships to secure volume-based service rate reductions and standardized training protocols. This behavioral shift concentrates procurement influence with Jeddah and Riyadh-based clinic networks that can aggregate demand across branch locations.
Saudi Arabia Aesthetic Devices Market Segmentation
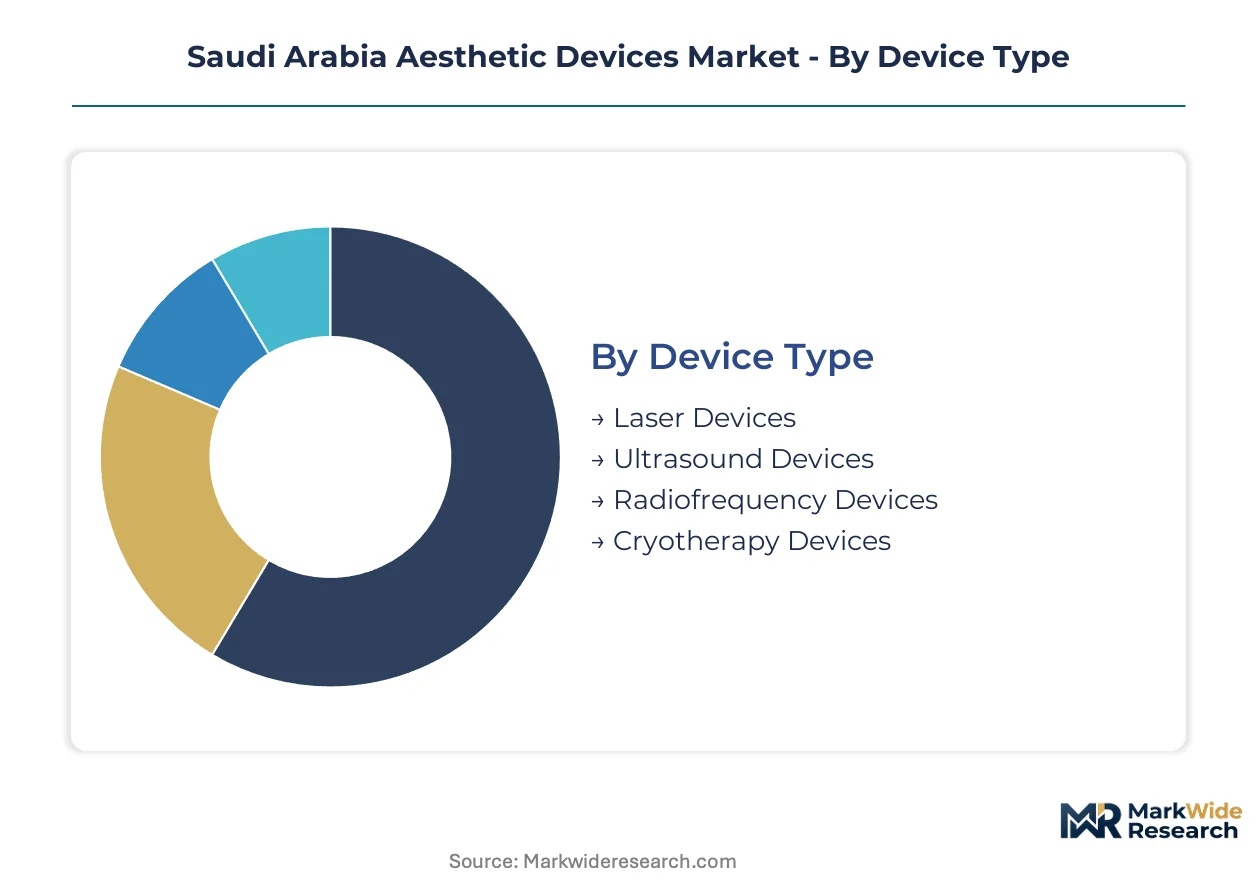
Saudi Arabia aesthetic devices fragment across four dimensions that determine procurement pathways and regulatory obligations. Device type and application area govern SFDA classification tiers, while end user and service type shape distribution economics and training requirements.
Device Type:
Laser and radiofrequency platforms anchor domestic demand through Riyadh and Jeddah clinic networks, while ultrasound and cryotherapy systems draw heavier import dependency from European and North American suppliers.
- Laser Devices:Electromechanical systems operating across 532 nm to 10,600 nm wavelengths deliver controlled thermal energy for tissue interaction. Dermatology centers in Riyadh's premium clusters procure these platforms most intensively, though darker skin phototype prevalence constrains wavelength selection and limits treatable patient populations for certain modalities.
- Radiofrequency Devices:Alternating current systems generate dermal heating through tissue resistance rather than chromophore targeting. Jeddah's coastal corridor clinics favor these devices for reduced post-inflammatory hyperpigmentation risk, expanding addressable patient bases among Gulf population skin types.
- Ultrasound Devices:High-intensity focused acoustic energy platforms for non-invasive fat reduction and skin tightening applications.
- Cryotherapy Devices:Controlled cooling systems targeting adipocyte apoptosis and localized fat deposit reduction.
Laser devices hold the largest share; momentum sits with radiofrequency platforms.
Application Area:
Revenue concentration varies sharply by procedure pricing and patient throughput, with body contouring commanding premium per-session rates while skin rejuvenation generates volume through repeat visits.
- Skin Rejuvenation:Fractional resurfacing, intense pulsed light, and non-ablative laser protocols address photodamage and texture irregularities. Beauty salons in Khobar and Dammam are expanding into these lower-complexity procedures, though SFDA restrictions on energy-based device operation by non-medical personnel constrain this channel.
- Body Contouring:Cryolipolysis, radiofrequency lipolysis, and high-intensity focused ultrasound target adipose tissue reduction. Riyadh's premium dermatology groups bundle these procedures into membership programs, capturing sustained patient engagement through multi-session protocols.
- Hair Removal:Laser and intense pulsed light platforms for permanent hair reduction across multiple skin types.
- Tattoo Removal:Q-switched and picosecond laser systems for pigment fragmentation and clearance.
Skin rejuvenation dominates patient volume; body contouring claims the steepest expansion trajectory.
End User:
Procurement authority and device complexity requirements stratify sharply across institutional types, with hospitals and dermatology centers holding exclusive access to Class III energy-based systems under SFDA licensing frameworks.
- Dermatology Centers:Multi-specialty facilities with board-certified practitioners operating the full spectrum of laser, radiofrequency, and ultrasound platforms. These centers concentrate in Jeddah's western corridor and Riyadh's northern districts, where disposable income densities support capital-intensive device acquisition.
- Clinics:Single or limited-specialty outpatient facilities focusing on high-frequency, lower-complexity procedures. Clinic networks in the Eastern Province are consolidating vendor relationships to secure volume-based service pricing and standardized training protocols across branch locations.
- Beauty Salons:Non-medical aesthetic service providers limited to superficial treatments and skincare protocols.
- Hospitals:Acute care institutions with aesthetic departments, primarily in the public sector under Ministry of Health oversight.
Dermatology centers capture the premium device installed base; clinics are gaining share fastest through network expansion.
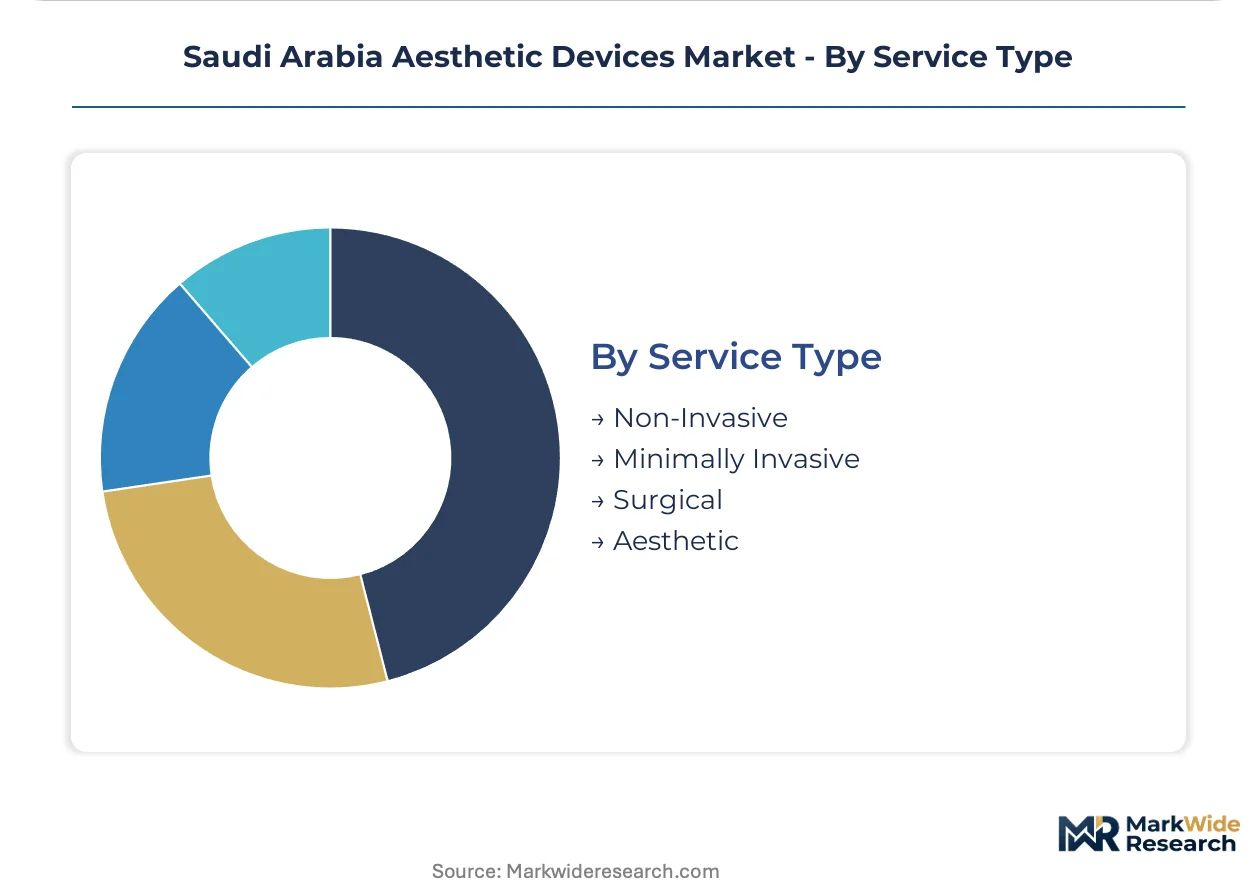
Service Type:
Capital requirements and provider training intensity separate non-invasive and minimally invasive modalities from surgical alternatives, with reimbursement absence across all categories forcing pure out-of-pocket economics.
- Non-Invasive:Energy-based procedures requiring no skin breach, including laser hair removal, radiofrequency skin tightening, and cryolipolysis. These services dominate Saudi consumer spending due to zero downtime and immediate return to daily activities, particularly among professional women in Riyadh and Jeddah.
- Minimally Invasive:Procedures involving microneedle, cannula, or small-caliber instrument entry, including fractional radiofrequency microneedling and micro-focused ultrasound. Dermatology centers are displacing traditional ablative lasers with these platforms to serve darker skin phototypes safely.
- Surgical:Invasive aesthetic procedures requiring operative facilities and anesthesia support.
- Aesthetic:Broad category encompassing cosmetic enhancement services without medical necessity designation.
Non-invasive services hold the largest share; minimally invasive protocols are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Riyadh and Jeddah clinic clusters, while Eastern Province markets operate at lower device density and compressed service margins. This asymmetry shapes where multinational suppliers deploy direct service infrastructure versus distributor-dependent models.
Riyadh
Capital expenditure on multi-modality platforms accelerates through northern district dermatology groups consolidating vendor relationships. SFDA Class III device licensing requirements concentrate procurement authority with board-certified practitioners operating in MOHAP-coordinated private healthcare zones. Premium clinic clusters along King Fahd Road anchor demand for advanced laser and radiofrequency systems.
Jeddah
Western coastal corridor clinics capture medical tourism flows from neighboring GCC states with bundled aesthetic protocols. Vision 2030 healthcare privatization incentives accelerate dermatology center construction along the Red Sea commercial zone. Alma Lasers maintains direct service infrastructure here to support premium platform placements.
Eastern Province
Dammam and Khobar maintain lower aesthetic device density than central and western regions, presenting first-mover positioning for suppliers establishing service hubs. SFDA registration requirements impose identical compliance costs regardless of market size, delaying distributor entry. Khobar clinic networks are consolidating to aggregate procurement volume and secure standardized training protocols.
Western Region
Makkah and Madinah aesthetic service demand concentrates around religious tourism visitor flows rather than resident disposable income. Device procurement prioritizes compact, multi-application platforms suitable for smaller clinic footprints. SFDA restrictions on energy-based device operation by non-medical personnel limit beauty salon channel expansion in these markets.
Saudi Arabia Aesthetic Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with laser platform specialists competing against injectable-focused pharmaceutical houses for facial rejuvenation spending. The market structure organizes around three tiers: multinational device manufacturers with direct Saudi operations, pharmaceutical companies controlling injectable distribution channels, and regional distributors dependent on manufacturer service support. Dominant competitive moves include consolidation of clinic network vendor relationships and restructuring of service contracts to bundle SFDA compliance support with maintenance agreements.
Within the multinational device manufacturer tier, Alma Lasers and Candela Medical exemplify direct-service infrastructure strategies, while Galderma S.A. occupies a position exemplifying pharmaceutical-channel control over aesthetic medicine flows. These three anchors represent divergent competitive approaches: capital-intensive platform ownership versus injectable-focused distribution economics versus specialized clinical niche targeting.
| Leading Market Players |
|---|
| Galderma S.A. |
| Sinclair Pharma PLC |
| Lumenis Inc. |
| Cynosure |
| Kalium Group |
| Candela Medical |
| Alma Lasers (Sisram Medical) |
| Merz Pharma |
| AbbVie Inc (Allergan Aesthetics) |
| Others |
Value Network & Pricing Analysis
Ninety-to-one-hundred-twenty-day lead times for Class III laser platform imports from Israel and the United States concentrate procurement authority with Riyadh-based dermatology groups capable of absorbing working capital strain. This inventory intensity reinforces pricing power for multinational manufacturers with direct Saudi service infrastructure while compressing margins for distributor-dependent competitors lacking balance sheet depth.
Pricing Analysis
The customization-premium spread between standard-configured radiofrequency platforms and wavelength-optimized laser systems runs three-to-one across Jeddah and Riyadh clinic networks. Three-tier pricing structure across premium, standard, and economy levels tracks SFDA registration tier and bundled compliance support rather than hardware specifications alone. Cost compression in the economy tier intensifies because Eastern Province clinic networks aggregate procurement volume to extract standardized service rates. Dermatology centers with multi-branch footprints exhibit lowest price sensitivity due to outcome-based patient retention economics, while independent single-location clinics in Khobar and Dammam face acute capital constraints.
Supply Chain Analysis
Inbound logistics costs through Jeddah Islamic Port congestion and Red Sea container availability constraints elevate landed costs for cryolipolysis and ultrasound platforms originating from Switzerland and Germany. Manufacturing concentration in Israel, the United States, and Italy anchors supply for laser and radiofrequency modalities, while cryotherapy device production centers on German and Swiss precision engineering capabilities. Supply chain risk rests on single-source vulnerability for YAG laser crystal substrates and RF generator components sourced from Japanese and German specialty suppliers. Distribution runs through manufacturer-direct service hubs in Riyadh and Jeddah for premium platforms, with regional distributors handling mid-tier device logistics to Eastern Province and Western Region clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia aesthetic devices sit in a cyclical recovery phase driven by Vision 2030 healthcare privatization accelerating clinic construction and capital expenditure release. This infrastructure build-out creates differentiated opportunity windows across competitive tiers.
For Market Incumbents: Fortify service contract bundling to capture SFDA compliance support as a recurring revenue anchor against injectable-focused competitors like Galderma S.A. Deepen backward integration into Saudi-based technical training academies to address biomedical engineer scarcity and lock in clinic network loyalty through workforce pipeline control.
For New Entrants and Emerging Players: Differentiate on Eastern Province first-mover positioning where Dammam and Khobar device density lags Riyadh and Jeddah by substantial margins. Target minimally invasive radiofrequency microneedling platforms as the most penetrable application segment given darker skin phototype safety advantages and displacement of ablative laser protocols.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capability compounder play because SFDA registration barriers favor scaled multinational suppliers with dedicated Saudi regulatory affairs staff. Acquisition targets should display established authorized representation infrastructure and hospital system procurement relationships. The signal to watch is domestic assembly partnership announcements triggering preferential public hospital tender access under localization incentives.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Clinical evidence packages and authorized representation secure Class III device market access before competitors complete compliance cycles. |
| Domestic Assembly Partnership | Vision 2030 localization incentives reward Saudi-based refurbishment operations with preferential Ministry of Health tender positioning. |
| Clinic Network Consolidation | Volume-based service rate reductions and standardized training protocols aggregate procurement influence across branch locations. |
| Combination Therapy Protocol Development | Sequential radiofrequency and laser treatments command premium pricing through outcome differentiation and extended patient engagement. |
| Biomedical Engineer Training Academy | Specialized photonics and electromechanical expertise pipelines address talent scarcity constraining clinic expansion rates. |
Research Methodology
A spread of perspectives from dermatology center procurement directors, biomedical engineering managers, SFDA regulatory consultants, and multinational device manufacturer country managers converged on the working assumptions shaping this analysis. Primary field engagement with clinic network executives and hospital purchasing committees combined with secondary validation through SFDA medical device registration databases, MOHAP healthcare licensing records, and customs import documentation for energy-based aesthetic systems. Bottom-up installed base enumeration across Riyadh, Jeddah, and Eastern Province clinic networks triangulated against top-down healthcare privatization expenditure forecasts.
Segmentation dimensions modeled span device type, application area, end user institution class, and service modality across the projection horizon. Analytical framework deployment tracked laser, radiofrequency, ultrasound, and cryotherapy platform adoption curves through dermatology center, clinic, hospital, and beauty salon channels. CAGRs derived from procedure volume elasticity to disposable income growth and capital expenditure release timing under Vision 2030 healthcare transformation programs. Industry-specific forecast inputs incorporated SFDA registration pipeline velocity and biomedical engineer graduation rates from Saudi technical training institutions.
The analysis sits within stated boundaries; outcomes outside sustained Vision 2030 privatization momentum and stable SFDA regulatory frameworks would require recalibration. Forecasts reflect assumptions regarding clinic construction completion rates and import logistics normalization through Red Sea shipping lanes. Practitioners should keep alternative scenarios live as geopolitical conditions affecting Israeli and European supply routes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Dermal Allograft Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Intradermal Injections Market
Medical Devices
Telehealth Device Market
Medical Devices
Self-Injections Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Dysphagia Management Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Tattoo Removal Devices Market