
 Endoscope Procedure Kits Market | 2026-2036
Endoscope Procedure Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Procedure Kits Market Foresight
Subscription-based reprocessing and maintenance programs for flexible endoscope systems is hardening into a core revenue layer for manufacturers. Olympus Corporation leverages its captive service network across Japan and North America to lock in hospital procurement cycles. Stryker Corporation anchors its kit offerings through backward integration into sterilization validation services. KARL STORZ specializes in rigid endoscope bundles for orthopedic and ENT applications, competing on optical precision rather than volume scale.
Endoscope procedure kits are pre-sterilized, single-use or limited-use assemblies containing an endoscope, biopsy valves, irrigation tubing, and suction channels, designed to eliminate reprocessing variability in minimally invasive diagnostic and therapeutic procedures. Flexible endoscopes dominate procedure volume in gastroenterology and pulmonology, while video endoscopes command premium positioning due to CMOS sensor resolution thresholds and integrated light-emitting diode illumination. Gastroenterology applications generate the deepest kit consumption cycles, whereas robotic systems integration represents the fastest-growing technology segment as da Vinci-compatible platforms expand into transoral procedures.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape sterile barrier validation and biocompatibility testing burdens for kit assemblers. The EPA regulates ethylene oxide sterilization emissions from kit manufacturing facilities, pushing producers toward gamma irradiation and vaporized hydrogen peroxide alternatives. ISO 13485 quality management systems and IEC 60601 electrical safety standards govern design controls across all target markets. Stakeholders must monitor how FDA guidance on disposable endoscope components evolves relative to reusable system reprocessing claims.
Market Dynamics
Single-use endoscope kits are compressing hospital sterilization infrastructure requirements while FDA 510(k) pathways tighten biocompatibility documentation burdens for assemblers.
Growth Catalysts
- DRG Reimbursement Reforms:Germany's diagnosis-related group restructuring accelerates outpatient endoscopy volumes, expanding kit pull-through in ambulatory settings.
- Ethylene Oxide Emission Controls:EPA enforcement actions against sterilization facilities push manufacturers toward gamma irradiation and vaporized hydrogen peroxide alternatives, validating kit-based sterile barrier systems.
- CMOS Sensor Thresholds:Video endoscope resolution requirements above 1080p drive integrated LED illumination bundles, consolidating disposable kit value propositions against reusable reprocessing.
Market Restraints
- Polymer Feedstock Volatility:Medical-grade polycarbonate and thermoplastic elastomer price swings compress kit assembler margins without pass-through mechanisms in hospital contracts.
- Gamma Irradiation Capacity Concentration:Sterilization service providers cluster in the United States Midwest and Belgium, creating geographic single points of failure for just-in-time kit delivery.
- Reusable System Reprocessing Claims:Olympus and Pentax automated endoscope reprocessors retain institutional installed bases, delaying full kit conversion in budget-constrained health systems.
Strategic Opportunities
- Transoral Robotic Surgery:da Vinci-compatible single-use platforms for oropharyngeal procedures open ENT and head-and-neck surgical suites previously served by rigid endoscope systems.
- EU MDR Class IIa Certification:Stricter sterile barrier validation requirements under the Medical Device Regulation create compliance moats for early-adopting kit assemblers against late entrants.
- Subscription Reprocessing Programs:Ambulatory surgical centers in Texas and Florida are piloting bundled per-procedure pricing that wraps kit supply, maintenance, and disposable replacement into fixed contracts.
Industry Challenges
- Sterile Barrier Validation Timelines:ISO 11607 compliance testing for new kit configurations extends product development cycles by 8-14 months, delaying revenue recognition.
- Biomedical Engineering Talent Scarcity:Cross-functional expertise combining endoscope optical design with single-use polymer processing remains concentrated among a narrow cohort of specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Procedure Kits Market |
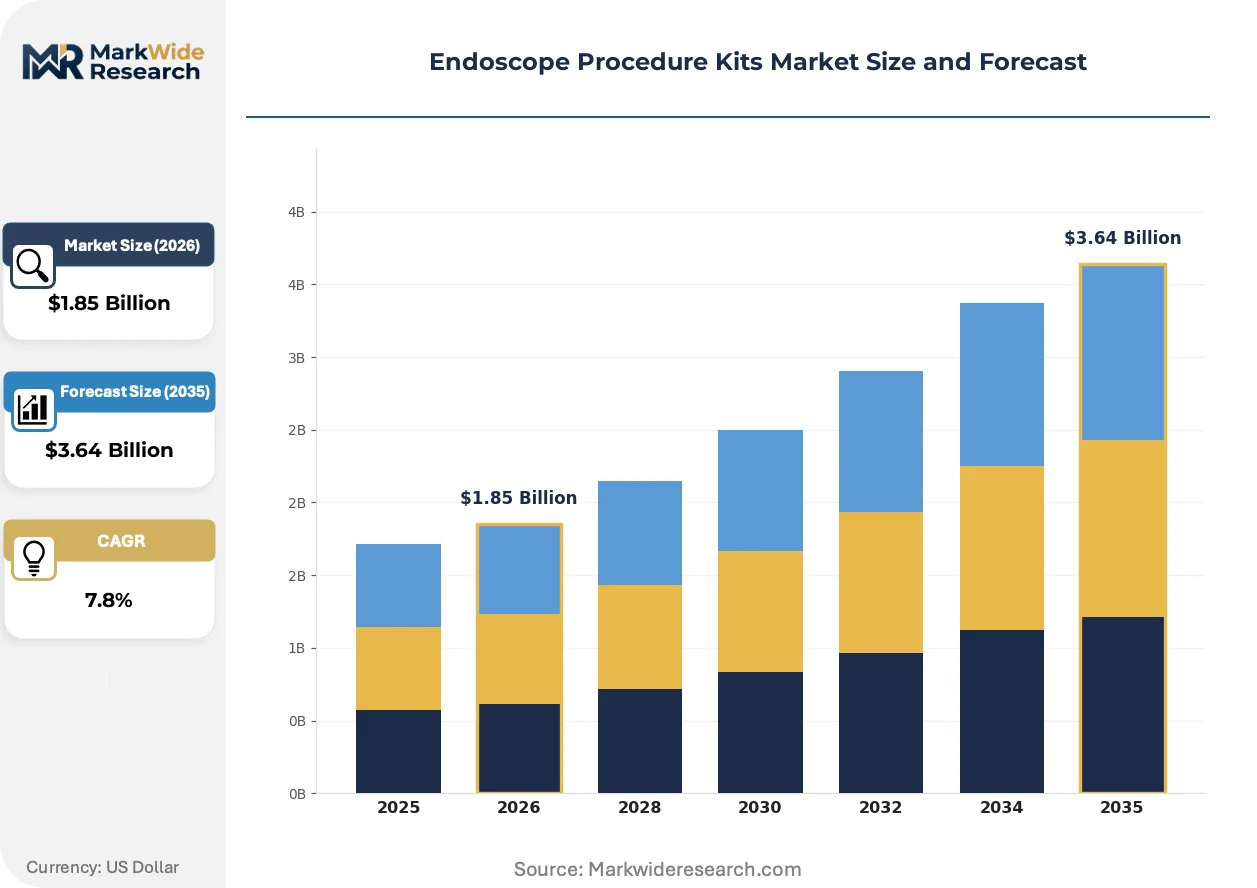
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Video Endoscopes, Accessories Application: Gastroenterology, Urology, Pulmonology, Gynecology End User: Hospitals, Clinics, Surgical Centers, Research Institutions Technology: Optical Imaging, Digital Imaging, Laser Systems, Robotic Systems |
| Companies Covered | Olympus Corporation, Stryker Corporation, KARL STORZ, Ethicon, Inc., Boston Scientific Corporation, Fujifilm Holdings Corporation, Medtronic plc, Hoya Corporation, Steris Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Procedure Kits Market Shifts & Advancements
Disposable sensor integration and regulatory pressure on sterilization emissions are compressing the viable design space for reusable endoscope systems.
CMOS-based single-use duodenoscopes is rewriting infection control economics in ERCP procedures. Gastroenterology departments at academic medical centers in Massachusetts and North Carolina are adopting these platforms within 18-month capital cycles. The technology is compressing liability exposure from carbapenem-resistant organism transmission while eliminating high-temperature reprocessing bottlenecks.
EU MDR Annex IX technical documentation requirements are extending sterile barrier validation obligations to kit subassemblies previously exempt under the Medical Devices Directive. German and Dutch notified bodies are demanding real-time ethylene oxide residual testing protocols for imported kits. Flexible endoscope assemblers serving European markets are reconfiguring supply chains toward gamma-sterilized production lines in Ireland and the Netherlands.
Per-procedure procurement contracts are displacing capital equipment purchasing in United States ambulatory surgical centers. Texas-based multispecialty chains now specify all-inclusive kit pricing that bundles endoscope, valve, and irrigation components with procedural waste disposal. This model concentrates purchasing authority at corporate procurement offices rather than individual physician preference, flattening brand loyalty premiums.
Endoscope Procedure Kits Market Segmentation
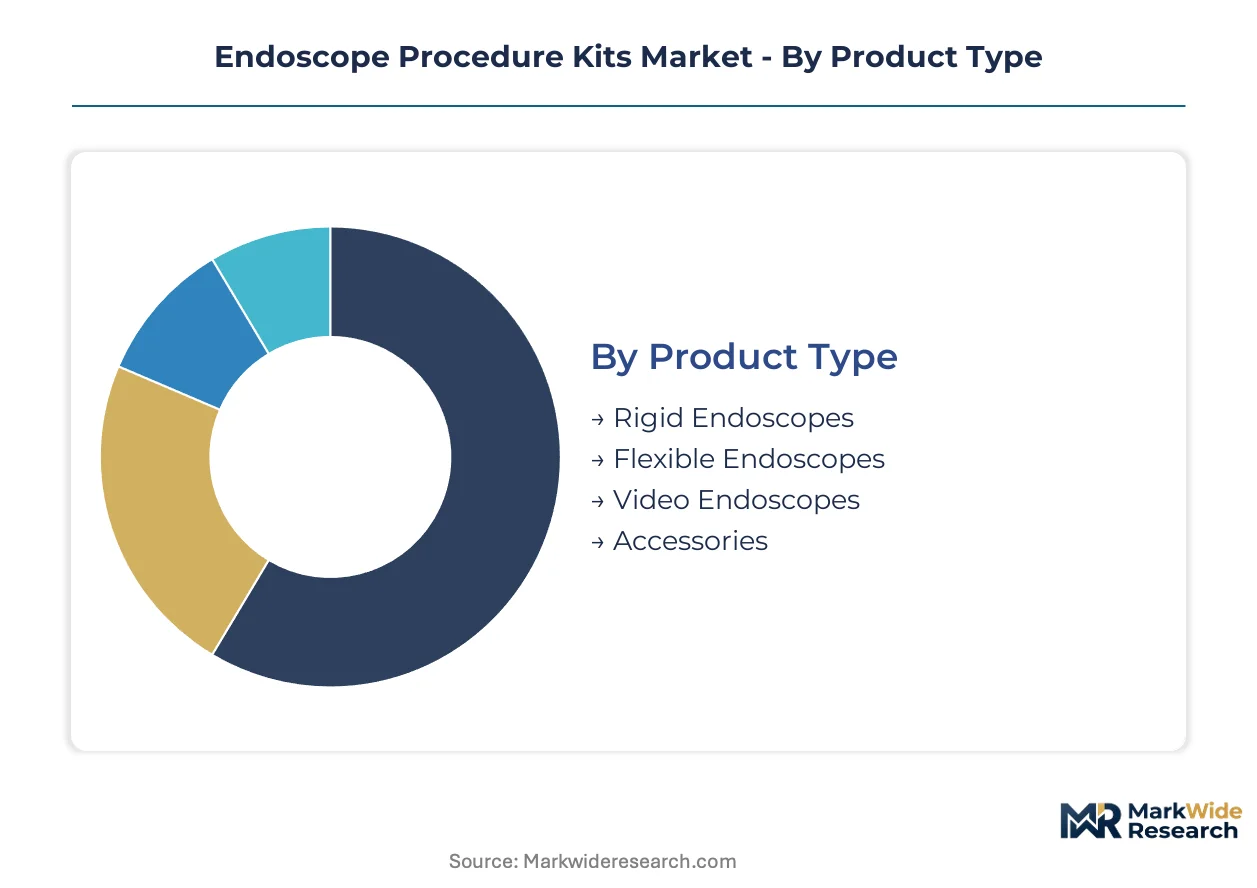
Endoscope procedure kits segment across multiple technical and commercial dimensions, each carrying distinct regulatory validation burdens and procurement economics. Understanding these divides clarifies where sterile barrier investments concentrate and which customer types drive volume conversion from reusable systems.
Product Type:
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements vary sharply across product types, with video endoscopes demanding the most extensive biocompatibility documentation and rigid systems facing lighter sterile barrier validation timelines.
- Flexible Endoscopes:Fiber-optic or video-equipped scopes with steerable distal tips, containing biopsy channels and irrigation ports. Demand concentrates in gastroenterology suites across Germany and the United States, where outpatient procedure volumes are rising under DRG reimbursement reforms and cross-contamination liability pressures.
- Video Endoscopes:CMOS sensor-based systems with integrated LED illumination and digital image processing capabilities. Academic medical centers in Massachusetts and North Carolina are adopting these within 18-month capital cycles, driven by resolution thresholds above 1080p and infection control economics.
- Rigid Endoscopes:Rod-lens optical systems for orthopedic and ENT applications.
- Accessories:Biopsy valves, irrigation tubing, and suction channels bundled in sterile barrier packaging.
Leading the category by volume: Flexible Endoscopes. Growing fastest: Video Endoscopes.
Application:
Procedure reimbursement rates and infection risk profiles determine kit penetration depth across clinical specialties, with high-volume outpatient settings converting faster than inpatient surgical departments.
- Gastroenterology:Colonoscopy, upper endoscopy, and ERCP procedures generate the deepest kit consumption cycles. Outpatient endoscopy volumes in Germany are expanding under DRG restructuring, while academic centers in the United States adopt CMOS-based single-use duodenoscopes to eliminate carbapenem-resistant organism transmission risks.
- Pulmonology:Bronchoscopy and thoracoscopy applications. Demand clusters in ambulatory surgical centers across Texas and Florida, where per-procedure procurement contracts bundle kit supply with procedural waste disposal.
- Urology:Cystoscopy and ureteroscopy procedures.
- Gynecology:Hysteroscopy and laparoscopy applications.
Volume leadership: Gastroenterology. Steepest expansion trajectory: Pulmonology.
End User:
Capital equipment ownership models and sterilization infrastructure availability shape kit adoption patterns, with asset-light operators converting more aggressively than established hospital systems.
- Surgical Centers:Ambulatory facilities in the United States are expanding adoption of single-use kits to compress sterilization infrastructure requirements. Texas-based multispecialty chains now specify all-inclusive kit pricing that bundles endoscope, valve, and irrigation components with maintenance and disposable replacement.
- Hospitals:Large health systems with captive automated endoscope reprocessor installed bases. Olympus and Pentax reprocessing claims retain institutional loyalty in budget-constrained systems, delaying full kit conversion.
- Clinics:Office-based diagnostic and minor therapeutic procedures.
- Research Institutions:Academic medical centers piloting next-generation imaging platforms.
Fastest-growing customer type: Surgical Centers. Largest absolute volume: Hospitals.
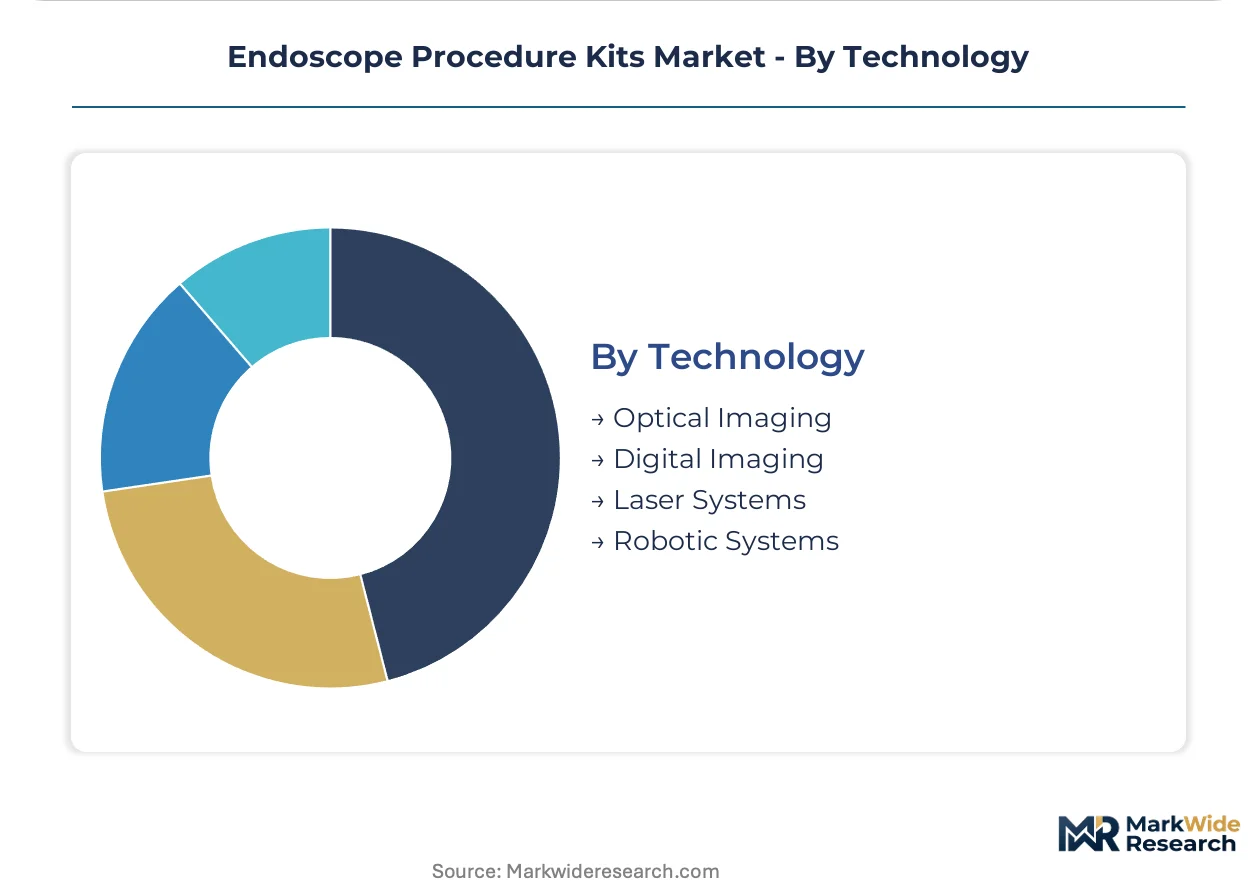
Technology:
Resolution specifications and systems integration requirements stratify R&D investment and regulatory submission complexity across imaging modalities.
- Robotic Systems:da Vinci-compatible single-use platforms for transoral procedures. ENT and head-and-neck surgical suites previously served by rigid endoscope systems are converting as these platforms expand into oropharyngeal applications.
- Digital Imaging:CMOS sensor-based capture with integrated processing. EPA enforcement actions against ethylene oxide sterilization facilities are pushing manufacturers toward gamma irradiation and vaporized hydrogen peroxide alternatives for these electronics-heavy kits.
- Optical Imaging:Traditional fiber-optic and rod-lens systems.
- Laser Systems:Therapeutic endoscopy with integrated energy delivery.
Technology category with steepest growth: Robotic Systems. Current volume base: Digital Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of sterilized endoscope kits clusters in the United States Midwest and Belgium, while consumption concentrates in Germany, Japan, and the United States where outpatient procedure volumes are expanding fastest.
United States
Ambulatory surgical centers in Texas and Florida are driving single-use kit adoption through per-procedure procurement contracts. FDA 510(k) clearance pathways are tightening biocompatibility documentation burdens for kit assemblers. The Midwest sterilization corridor, spanning Illinois and Ohio, houses concentrated gamma irradiation capacity serving just-in-time delivery networks.
Germany
Outpatient endoscopy volumes are accelerating under DRG reimbursement restructuring, expanding kit pull-through in ambulatory settings. EU MDR Class IIa certification requirements are extending sterile barrier validation obligations to kit subassemblies. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host notified body activity and gamma-sterilized production lines.
Japan
Flexible endoscope demand concentrates in aging-population gastroenterology suites across Kanto and Kansai regions. PMDA regulatory frameworks govern sterile barrier validation for imported kits. Tokyo-based manufacturers leverage captive service networks to lock in hospital procurement cycles through subscription-based reprocessing programs.
Belgium
Gamma irradiation capacity concentration creates a geographic chokepoint for European kit sterilization. ECHA oversight of ethylene oxide emissions is pushing manufacturers toward vaporized hydrogen peroxide alternatives. Antwerp and Liège industrial zones host contract sterilization facilities serving German and Dutch markets.
China
Domestic CMOS sensor manufacturing is reducing import dependency for video endoscope components. NMPA medical device registration requirements are lengthening approval timelines for foreign kit assemblers. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang are developing localized sterile barrier packaging capabilities.
Endoscope Procedure Kits Market Competitive Landscape
Top-tier vendors anchor the premium video endoscope segment, while mid-scale assemblers compete on sterilization service bundling and regional logistics. The market structure stratifies across three tiers: integrated device-service conglomerates, specialized optical manufacturers, and contract sterilization-dependent assemblers. Two strategic archetypes dominate: backward integration into sterilization validation services, and captive maintenance network deployment. M&A activity concentrates on gamma irradiation facility acquisition, while capacity expansion focuses on EU MDR-compliant sterile barrier lines in Ireland and the Netherlands.
Among Japanese and German optical specialists, Olympus Corporation, KARL STORZ, and Fujifilm Holdings Corporation exemplify divergent competitive positions. Olympus occupies a position representing the integrated service-network archetype, leveraging geographic density in domestic markets. KARL STORZ exemplifies specialization in rigid endoscope bundles for surgical subspecialties. Fujifilm Holdings Corporation anchors the digital imaging transition, representing CMOS sensor integration strategies. These three sit within distinct tier positions rather than direct segment overlap.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| KARL STORZ |
| Ethicon, Inc. |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Medtronic plc |
| Hoya Corporation |
| Steris Corporation |
| Others |
Supply & Pricing Matrix
Academic medical centers and ambulatory surgical centers in the United States are concentrating purchasing authority through per-procedure procurement contracts, flattening brand loyalty premiums and compressing kit assemblers toward subscription-based pricing models that bundle sterile barrier systems with maintenance and replacement cycles.
Pricing Analysis
Margin tightening in the video endoscope tier reflects medical-grade polycarbonate and thermoplastic elastomer feedstock volatility without pass-through mechanisms in hospital contracts. Three-tier pricing structure across premium, standard, and economy levels separates CMOS sensor-integrated systems with FDA 510(k) clearance from basic fiber-optic bundles and unvalidated accessories. Ambulatory surgical centers in Texas and Florida exhibit acute price sensitivity, while academic medical centers in Massachusetts prioritize infection control economics over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German and United States notified bodies mandate multi-supplier qualification for gamma-sterilized components, forcing assemblers to qualify redundant irradiation capacity across Belgium and the Midwest United States. Medical-grade polycarbonate, CMOS sensors, and thermoplastic elastomer tubing draw from concentrated polymer processing hubs in Germany, Japan, and the United States. Single-source vulnerability in gamma irradiation capacity creates geographic chokepoints for just-in-time kit delivery. Distribution runs through hospital procurement offices and GPO contracts rather than physician-directed purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS-based single-use duodenoscopes are displacing fiber-optic reusable systems in gastroenterology suites, compressing the viable design space for legacy reprocessing-dependent platforms and rewriting infection control economics across ambulatory settings.
For Market Incumbents: Deepen backward integration into sterilization validation services to defend against gamma irradiation capacity concentration in Belgium and the Midwest United States. Lock in hospital procurement cycles through subscription-based reprocessing programs that wrap kit supply, maintenance, and disposable replacement into fixed contracts, neutralizing emerging entrants competing on per-unit transactional pricing. For New Entrants and Emerging Players: The price-point gap between premium video endoscope systems and economy fiber-optic bundles opens white-space targeting for mid-tier CMOS sensor platforms with EU MDR Class IIa certification. Pulmonology applications in Texas and Florida ambulatory surgical centers present the most penetrable segment, where per-procedure procurement contracts concentrate purchasing authority and flatten incumbent brand loyalty. Lead with gamma-sterilized production partnerships in Ireland and the Netherlands to bypass Belgian capacity chokepoints. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract sterilization-dependent assemblers with EU MDR-compliant sterile barrier lines in Ireland and the Netherlands, where regulatory compliance moats are hardening against late entrants. Long-term viability hinges on acquisition targets with validated gamma irradiation relationships and digital imaging transition capabilities. Watch FDA guidance evolution on disposable endoscope components relative to reusable system reprocessing claims as the inflection indicator for kit conversion acceleration versus delay.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Stricter sterile barrier validation requirements under EU MDR create compliance moats for early-adopting kit assemblers against late entrants. |
| Gamma-Sterilized Production Line Expansion | EPA enforcement actions against ethylene oxide facilities push manufacturers toward gamma irradiation and vaporized hydrogen peroxide alternatives. |
| Hospital System Partnership | Texas-based multispecialty chains specify all-inclusive kit pricing that bundles endoscope, valve, and irrigation components with procedural waste disposal. |
| Software Companion Development | Integrated LED illumination bundles with digital image processing capabilities consolidate disposable kit value propositions against reusable reprocessing. |
| Reimbursement Strategy | Germany's DRG restructuring accelerates outpatient endoscopy volumes, expanding kit pull-through in ambulatory settings under reformed payment models. |
Research Methodology
Multi-period observation of outpatient endoscopy volumes, DRG reimbursement reforms, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and sterilization validation specialists. Secondary validation drew from FDA premarket notification databases, EU MDR technical documentation requirements, EPA ethylene oxide emission enforcement records, and hospital procurement databases. Bottom-up kit volume modeling triangulated against top-down market sizing from sterile barrier packaging demand and gamma irradiation capacity utilization.
Input-output matrices mapped CMOS sensor resolution thresholds, LED illumination integration rates, and robotic systems adoption across gastroenterology, pulmonology, and ENT applications. Segmentation dimensions spanned product type, clinical application, end-user facility category, and technology modality. CAGRs were derived from procedure volume trajectories under reimbursement reform scenarios and cross-contamination liability exposure trends. Sterilization emission regulatory pressure and polymer feedstock volatility served as industry-specific forecast sensitivity inputs.
Inputs from hospital procurement databases and notified body certification records were available through the study window; gaps in real-time ethylene oxide residual testing protocols for imported kits introduce uncertainty bands around European market penetration assumptions. Deviation in FDA guidance on disposable endoscope components relative to reusable system reprocessing claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Global Medical Implants Market
Medical Devices
Bariatric Beds Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Subdural Electrodes Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Ingestible Smart Pills Market